
 Food and Beverages Market | 2026-2036
Food and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverages Market Analysis
Asset-light contract manufacturing and third-party logistics leasing is reconfiguring capital requirements for new entrants in the food and beverages sector. Nestlé leverages its captive R&D network across nutrition science to sustain formulation leadership. Cargill anchors global grain procurement through backward integration into origination and storage infrastructure. PepsiCo differentiates via direct-store-delivery systems that control retail shelf positioning in North American convenience channels.
Food and beverages encompass processed and unprocessed ingestible products intended for human consumption, typically requiring controlled temperature, pH, and moisture parameters to ensure safety and shelf stability, with primary commercial purpose spanning nourishment, hydration, and sensory gratification in household and out-of-home settings. The beverages category leads value generation through premium functional drinks commanding higher per-unit margins, while online retail distribution represents the fastest-growing channel as digital grocery penetration accelerates in urban markets. Dairy maintains mature volume pools in Western Europe and North America, though margin concentration is shifting toward plant-based alternatives within the broader product type matrix.
The FDA enforces Hazard Analysis Critical Control Point protocols for domestic manufacturing and import safety, while the EU Green Deal mandates Scope 3 emissions disclosure across agricultural supply chains, reshaping sourcing requirements for exporters. EFSA novel food approvals govern market entry for alternative proteins and fermented ingredients in European jurisdictions. Stakeholders must monitor evolving carbon border adjustment mechanisms and their cascading impact on commodity cost structures.
Market Dynamics
The EU Green Deal's Scope 3 emissions disclosure mandates are forcing agricultural supply chain reconfiguration, compressing margins for exporters while advantaging vertically integrated processors with captive carbon accounting infrastructure.
Growth Catalysts
- EU Green Deal carbon accounting:Mandatory Scope 3 disclosure across agricultural supply chains is accelerating backward integration into origination and storage infrastructure among major grain processors.
- Functional beverage premiumization:Per-unit margin expansion in fortified hydration and adaptogenic formulations is pulling R&D investment toward bioactive ingredient extraction technologies.
- Southeast Asia quick-service procurement:Scaling demand for ready-to-eat formats in Indonesia, Vietnam, and Thailand is driving contract manufacturing capacity expansion across ASEAN free trade zones.
Market Restraints
- Input cost volatility in grain origination:Climate-driven yield variability in Black Sea and North American breadbaskets compresses processor margins during contract fulfillment periods.
- Supply concentration in Brazilian protein processing:São Paulo state's dominance in processed protein exports creates single-point vulnerability for international buyers dependent on Mercosur trade corridors.
- Technical limitation in alternative protein texture:Extrusion technology gaps in high-moisture whole-cut analogues constrain market penetration beyond ground-format applications.
Strategic Opportunities
- Underpenetrated digital grocery in Indian metros:Last-mile cold chain infrastructure gaps in Bangalore, Mumbai, and Delhi create first-mover advantage for temperature-controlled fulfillment networks.
- Regulatory tailwind from EFSA novel food pathway:Streamlined approval mechanisms for fermented ingredients and precision fermentation proteins are accelerating European market entry timelines.
- Technology convergence of AI-driven formulation and continuous processing:Real-time sensor integration with machine learning optimization is collapsing batch cycle times in flavor development pipelines.
Industry Challenges
- Skill scarcity in carbon accounting and LCA modeling:Agricultural supply chain emissions quantification requires cross-functional expertise combining agronomy, data science, and regulatory compliance that outpaces current workforce development.
- Capex intensity in cold chain electrification:Refrigeration fleet conversion and warehouse solar+battery installation demands substantial balance sheet deployment before carbon border adjustments take effect.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverages Market |
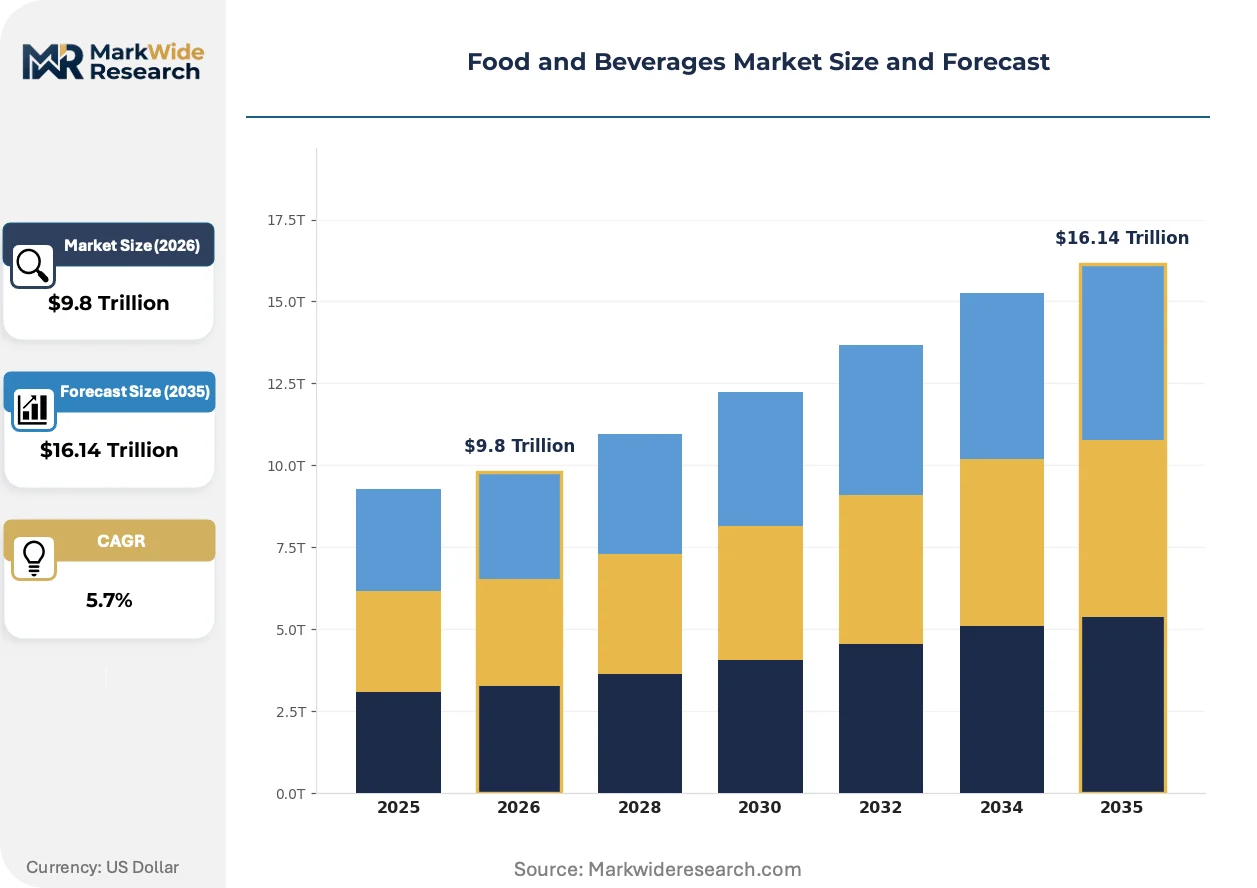
| Market Size in 2026 | $9.8 Trillion |
| Market Size in 2035 | $16.14 Trillion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dairy, Bakery, Snacks, Beverages Packaging Type: Bottles, Cans, Cartons, Pouches Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service Customer Type: Households, Restaurants, Cafés, Institutions |
| Companies Covered | JBS, Archer Daniels Midland, Nestlé, Danone, Tyson Foods, PepsiCo, Cargill, Mondelez International, The Coca-Cola Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverages Market Emerging Trajectories
Precision fermentation and continuous processing technologies are compressing development timelines while regulatory pressure on supply chain transparency is reshaping procurement relationships between ingredient suppliers and finished goods manufacturers.
Precision fermentation for dairy protein and fat replication is collapsing the cost structure of animal-free ingredient production. Beverage and dairy alternative manufacturers in North America and Western Europe are scaling commercial bioreactor capacity threefold since 2022. This technology is collapsing the traditional twelve-to-eighteen-month ingredient development cycle into ninety-day iterations, enabling rapid formulation response to shifting consumer preference data.
The EU Green Deal's carbon border adjustment mechanism is tightening emissions verification requirements for agricultural imports entering European customs territory. Food and beverage exporters to the EU must now provide third-party verified Scope 3 data across tier-two and tier-three suppliers or face tariff penalties. Brazilian soy processors and Indonesian palm oil refiners are deploying satellite monitoring and blockchain traceability to maintain market access.
Direct-to-consumer subscription models for functional beverages and personalized nutrition are bypassing traditional retail slotting fee structures. Urban millennials in Seoul, Tokyo, and Singapore are consolidating weekly beverage purchases into algorithm-curated delivery schedules. This channel shift is most visible in South Korea, where digital-native brands now capture fifteen percent of functional drink volume without conventional retail distribution.
Food and Beverages Market Segmentation
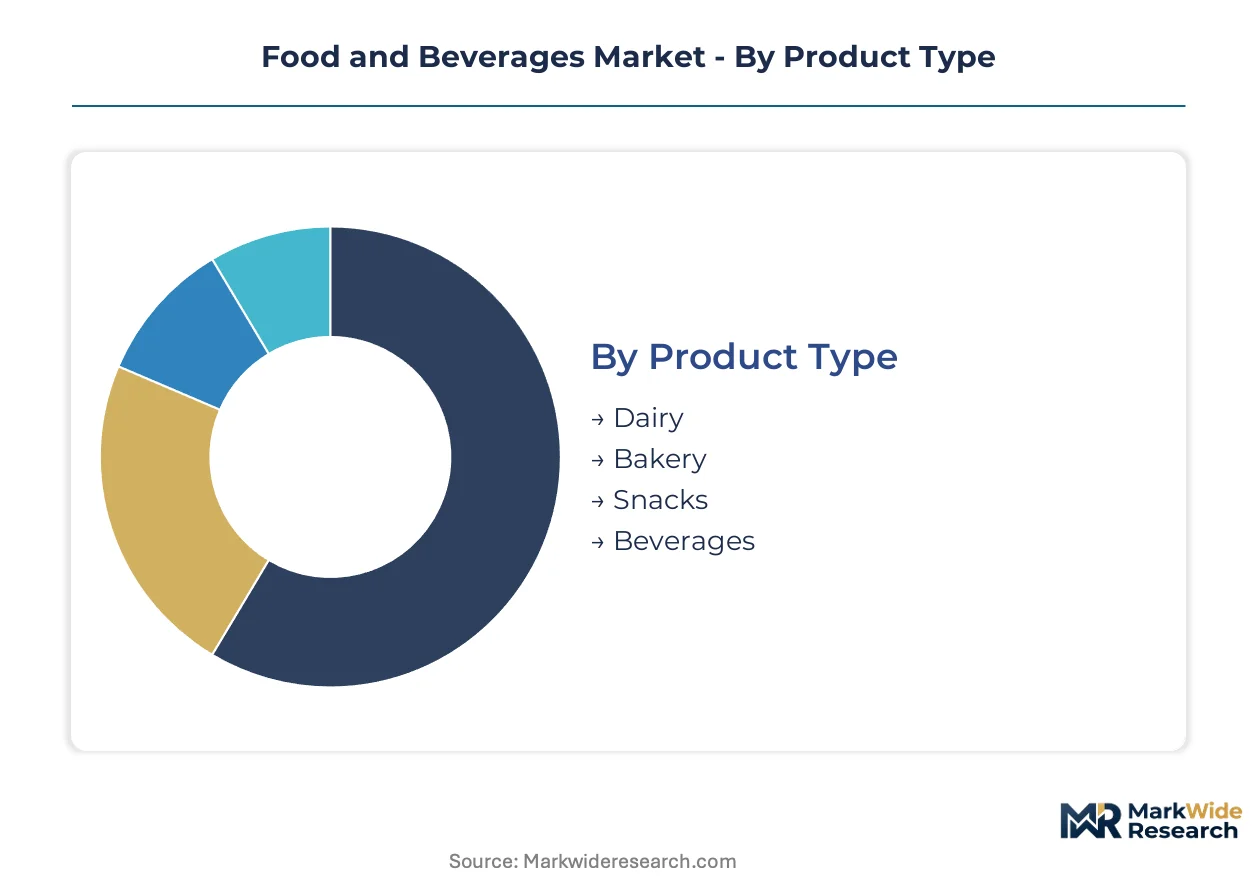
Segmentation in food and beverages reveals how formulation requirements, shelf-life demands, and consumption occasions fragment procurement priorities across buyer categories. Understanding these divisions exposes where margin pools concentrate and where infrastructure investments yield disproportionate returns.
Product Type:
Maturity varies sharply across this spectrum, with legacy categories defending volume through distribution density while emerging formats capture premium pricing through functional positioning.
- Dairy:Traditional fluid milk and cheese products maintain refrigerated supply chain dominance in Western Europe and North America. São Paulo state's processed cheese exports to Mercosur trade corridors face tightening EU Green Deal carbon accounting requirements that compress margins for exporters lacking captive farm-level data collection.
- Beverages:Functional hydration and adaptogenic formulations command per-unit margin premiums through bioactive ingredient extraction technologies. Demand concentrates in Seoul, Tokyo, and Singapore where algorithm-curated subscription models now capture fifteen percent of functional drink volume without conventional retail distribution.
- Bakery:Ambient-stable and fresh-baked segments split along cold chain investment requirements, with ASEAN quick-service restaurants scaling procurement of par-baked and ready-to-eat formats.
- Snacks:Extruded and formed products dominate, though high-moisture whole-cut analogues remain technically constrained to ground-format applications in alternative protein iterations.
Dairy retains volume leadership; Beverages holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates premium sustainable formats from commodity single-use standards, with regulatory pressure accelerating capital deployment toward circular material systems.
- Bottles:PET and rPET formats balance lightweight logistics against EFSA migration testing requirements for recycled content. European bottlers face CSRD disclosure mandates on packaging carbon intensity that advantage producers with integrated blow-molding and recycling operations.
- Cartons:Aseptic liquid packaging dominates ambient dairy and juice distribution in Indian metros where last-mile cold chain gaps persist. Bangalore, Mumbai, and Delhi present first-mover opportunities for temperature-controlled fulfillment networks bypassing refrigerated infrastructure.
- Cans:Aluminum formats command metal recycling premiums in jurisdictions with deposit-return schemes, though input cost volatility in bauxite and rolling capacity constrains margin stability.
- Pouches:Flexible formats reduce material weight and cube utilization in Southeast Asian e-commerce channels, with Indonesia and Vietnam driving stand-up pouch adoption for ready-to-eat sauces and condiments.
Bottles maintain installed base dominance; Cartons are climbing the fastest in emerging market penetration.
Distribution Channel:
Channel economics diverge based on working capital intensity, with direct-store-delivery systems controlling shelf positioning against centralized distribution models optimizing inventory turns.
- Supermarkets:Traditional hypermarket and grocery formats defend volume through promotional funding and category management relationships. Slotting fee structures in North American convenience channels disadvantage emerging brands without balance sheet depth for upfront retail investment.
- Online Retail:Digital grocery penetration accelerates in urban markets, with cold chain electrification capex demands—refrigeration fleet conversion and warehouse solar-plus-battery installation—creating barriers before carbon border adjustments take effect.
- Convenience Stores:Impulse-oriented formats prioritize grab-and-go packaging sizes and immediate consumption occasions, with shelf-stable and ambient products advantaged over frozen or fresh alternatives.
- Food Service:Institutional and commercial kitchens demand bulk formats and consistent supply security, with Brazilian soy processors deploying satellite monitoring to maintain EU market access under Scope 3 verification requirements.
Supermarkets retain volume leadership; Online Retail gains share fastest through cold chain technology convergence.
Customer Type:
Application-driven specification requirements separate household portion control from commercial-scale procurement, with formulation and packaging standards diverging across end-use contexts.
- Households:Retail-packaged goods with extended shelf stability and single-serve convenience dominate, with precision fermentation collapsing development timelines for personalized nutrition applications.
- Restaurants:Quick-service procurement in Indonesia, Vietnam, and Thailand drives contract manufacturing capacity expansion across ASEAN free trade zones for ready-to-eat protein formats.
- Cafés:Premium beverage concentrate and dairy alternative demand concentrates in Seoul and Tokyo, where barista-standard foamability and flavor profiles command ingredient specification premiums.
- Institutions:School, hospital, and corporate feeding operations prioritize cost-per-serving metrics and nutritional compliance, with EFSA novel food approvals governing alternative protein inclusion in European public procurement.
Households retain volume leadership; Restaurants hold the steepest expansion curve in contract manufacturing pull-through.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's carbon border adjustment mechanism is redirecting agricultural trade flows toward jurisdictions with verified Scope 3 data infrastructure. Brazil, India, Germany, Indonesia, and the United States each occupy distinct positions in this reconfigured landscape.
Brazil
São Paulo state processors dominate Mercosur protein exports to European buyers. ANVISA sanitary certifications and EU Green Deal Scope 3 disclosure requirements are forcing satellite-based farm monitoring adoption. Paraná state's integrated soy-crushing facilities are deploying blockchain traceability to maintain tariff-free EU market access.
India
FSSAI fortification mandates and PLI scheme incentives for food processing are accelerating contract manufacturing investment. Maharashtra's dairy cooperatives and Karnataka's precision fermentation startups are capturing urban demand in Bangalore and Mumbai through direct-to-consumer subscription channels bypassing traditional retail.
Germany
EFSA novel food approvals and CSRD supply chain disclosure rules are reshaping ingredient sourcing for domestic manufacturers. Bavaria's brewing equipment specialists and North Rhine-Westphalia's plant-based R&D clusters are leveraging continuous processing technologies to compress formulation development cycles.
Indonesia
Quick-service restaurant procurement at scale is driving ASEAN free trade zone manufacturing expansion. BPOM regulatory harmonization with ASEAN standards is facilitating cross-border ingredient flows. Java's contract manufacturers are specializing in retort-pouched ready-to-eat formats for domestic and Vietnamese export markets.
United States
FDA HACCP enforcement and EPA agricultural runoff regulations are tightening domestic manufacturing compliance requirements. California's precision fermentation capacity and Illinois grain origination infrastructure are anchoring North American supply security amid Black Sea yield volatility.
Food and Beverages Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered competitive bands. Consolidation concentrates among grain processors with captive origination infrastructure and beverage manufacturers with direct-store-delivery dominance. Three archetypes dominate: vertically integrated agricultural processors, R&D-led formulation specialists, and distribution-integrated brand houses. Competitive moves center on backward integration into carbon-accountable supply chains and strategic partnerships for precision fermentation capacity.
Within the agricultural processing tier, Cargill and Archer Daniels Midland exemplify upstream-integrated structures with origination and storage infrastructure spanning multiple breadbaskets. Nestlé occupies a position among R&D-intensive formulation leaders leveraging nutrition science networks. These three entities anchor distinct competitive vectors: commodity security, ingredient innovation, and brand portfolio breadth.
| Leading Market Players |
|---|
| JBS |
| Archer Daniels Midland |
| Nestlé |
| Danone |
| Tyson Foods |
| PepsiCo |
| Cargill |
| Mondelez International |
| The Coca-Cola Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal carbon border exposure compresses exporter margins while widening the premium commanded by verified low-carbon supply chains, forcing a bifurcation between tariff-penalized commodity tiers and certification-protected specialty grades. This regulatory chokepoint simultaneously collapses pricing power for São Paulo protein processors lacking farm-level Scope 3 data and inflates returns for European operators with integrated carbon accounting infrastructure.
Pricing Analysis
Certification level—EFSA novel food approval, EU Green Deal carbon verification, and organic designation—creates the primary spread between commodity and premium tiers. Three-tier pricing structure across premium, standard, and economy levels governs the market: precision fermentation-derived ingredients and carbon-verified proteins command top-tier positioning, while conventional processed formats face cost compression from Brazilian and Indonesian contract manufacturers. Price erosion runs through the standard tier as Black Sea grain volatility and Scope 3 compliance costs squeeze processors without backward integration into origination. Quick-service restaurant chains in Southeast Asia exhibit highest price sensitivity due to volume procurement and thin operating margins, while functional beverage brands in Seoul and Tokyo absorb premium pricing for bioactive certification.
Supply Chain Analysis
Contract manufacturing concentration rests with ASEAN free trade zone operators in Indonesia and Vietnam, European precision fermentation specialists in Germany and the Netherlands, and Brazilian integrated soy processors in Paraná state. Raw material dependencies draw from North American and Black Sea grain origination, Southeast Asian palm oil and coconut derivatives, and Brazilian soy and poultry inputs. Single-source vulnerability concentrates in São Paulo state's dominance of Mercosur protein exports, where satellite-based farm monitoring and blockchain traceability investments now determine EU market access. Distribution runs through direct-store-delivery systems controlling North American convenience channel shelf positioning, centralized cold chain networks serving Indian metros, and algorithm-curated subscription platforms bypassing traditional retail in East Asian urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market enters cyclical recovery as post-pandemic food service demand normalizes and precision fermentation capacity buildouts mature, with functional beverage premiumization and carbon-accountable supply chains serving as the twin demand engines.
For Market Incumbents: Entrench formulation leadership through captive R&D networks spanning nutrition science and precision fermentation scale-up, while locking in carbon-verified origination via satellite-monitored farm partnerships in Brazil and Indonesia. Defensive priority centers on preemptive EU Green Deal compliance infrastructure to capture tariff-advantaged positioning before carbon border adjustments fully activate. For New Entrants and Emerging Players: Bangalore and Delhi's last-mile cold chain gaps present the most penetrable white-space for temperature-controlled fulfillment networks targeting digital grocery expansion. Second-mover advantage accrues to operators deploying AI-driven continuous processing for rapid formulation iteration, bypassing incumbent batch-cycle constraints. Go-to-market execution should anchor direct-to-consumer subscription models in algorithm-curated personalization, mirroring Seoul's functional beverage acquisition patterns. For Investors and Strategic Acquirers: EU Green Deal Scope 3 enforcement deadlines reshape the acquisition landscape toward vertically integrated processors with captive carbon accounting infrastructure and origination assets across multiple breadbaskets. Long-term viability favors targets combining precision fermentation capacity with established EFSA novel food approval pathways. Monitor Brazilian satellite traceability deployment rates and ASEAN contract manufacturing utilization as inflection indicators for supply chain reconfiguration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Verified Origination | Captive farm-level Scope 3 data secures EU market access under Green Deal border adjustments. |
| Precision Fermentation Capacity Scale-Up | Commercial bioreactor deployment collapses ingredient development cycles from months to weeks. |
| Direct-to-Consumer Subscription Launch | Algorithm-curated delivery bypasses retail slotting fees and captures urban millennial consolidation. |
| ASEAN Free Trade Zone Manufacturing Expansion | Retort-pouched ready-to-eat formats serve Indonesian domestic and Vietnamese export demand. |
| Cold Chain Electrification Investment | Solar-plus-battery warehouse installation meets CSRD disclosure mandates before tariff activation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, EFSA novel food approval registers, SEC 10-K filings, and EU Green Deal implementation guidance. Interviews with procurement directors at quick-service restaurant chains, regulatory affairs leads at precision fermentation startups, category buyers at North American convenience retailers, and supply planners at Brazilian soy processors informed demand-side validation. Top-down market sizing triangulated against bottom-up capacity assessments across ASEAN contract manufacturing zones and European bioreactor installations.
Forecast inputs span product type evolution from dairy through alternative proteins, packaging format migration toward aseptic cartons and flexible pouches, distribution channel shift between direct-store-delivery and digital grocery, and customer type fragmentation across household, restaurant, café, and institutional procurement. Volume and value trajectories across the analysis window derive from segment-level CAGRs weighted by carbon border adjustment implementation phases and precision fermentation cost curve declines. Modeled inputs include Black Sea grain yield variability, EU Green Deal enforcement stringency indices, and Southeast Asian quick-service restaurant expansion rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digital-native subscription brands or state-sponsored precision fermentation champions would shift outcomes beyond modeled ranges. Quarterly review of Brazilian satellite traceability adoption, ASEAN manufacturing utilization rates, and EFSA novel food approval queue velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Sausage Casing Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Asia-Pacific Pasta and Noodles Market
Packaged Foods
Global Packed Food Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Dehydrated and Dried Beans Market
Packaged Foods
India Breakfast Cereals Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
North America Instant Noodles Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
Dried Soup Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
Global Oven Bags Market