
 Packaged Zhug Market | 2026-2036
Packaged Zhug Market Size, Share, and Industry Trends Forecast 2026-2036
Packaged Zhug Market Analytics
EU Green Deal sustainability targets for food packaging is decoupling conventional plastic formats from premium zhug positioning across European retail channels. Sabra Dipping Company leverages its established hummus distribution network to secure refrigerated placement for zhug variants in mainstream supermarkets. Grecian Delight Foods anchors its portfolio in authentic Mediterranean condiment credentials, competing on heritage positioning rather than price. Steenbergs specializes in organic spice sourcing, extending its ethical supply chain reputation into the zhug category through transparent procurement narratives.
Packaged zhug is a Yemeni-origin hot sauce comprising fresh chili peppers, cilantro, garlic, cardamom, and cumin emulsified with olive oil, typically exhibiting a pH below 4.6 for ambient stability and a Scoville range of 3,000–15,000 SHU depending on chili variety. The condiment functions primarily as a table sauce and marinade base in Middle Eastern, Mediterranean, and fusion cuisine applications. Green Zhug dominates product type volume due to its broader palatability and visual differentiation on retail shelves, while Spicy Zhug captures disproportionate margin contribution from specialty store and foodservice channels. Squeeze bottle packaging leads unit sales in household segments for convenience-driven application, though glass jars sustain premium positioning in specialty retail where artisanal provenance commands price premiums.
FDA compliance with acidified food regulations under 21 CFR 114 governs thermal processing requirements for shelf-stable zhug distributed in the United States, while EFSA additive authorization frameworks shape clean-label formulation decisions for European export products. BIS certification requirements affect market access for Indian-manufactured zhug variants seeking formal retail distribution. Stakeholders must monitor evolving packaging waste directives in target jurisdictions, as extended producer responsibility schemes will soon force material format decisions that directly impact cost structures and brand positioning.
Market Dynamics
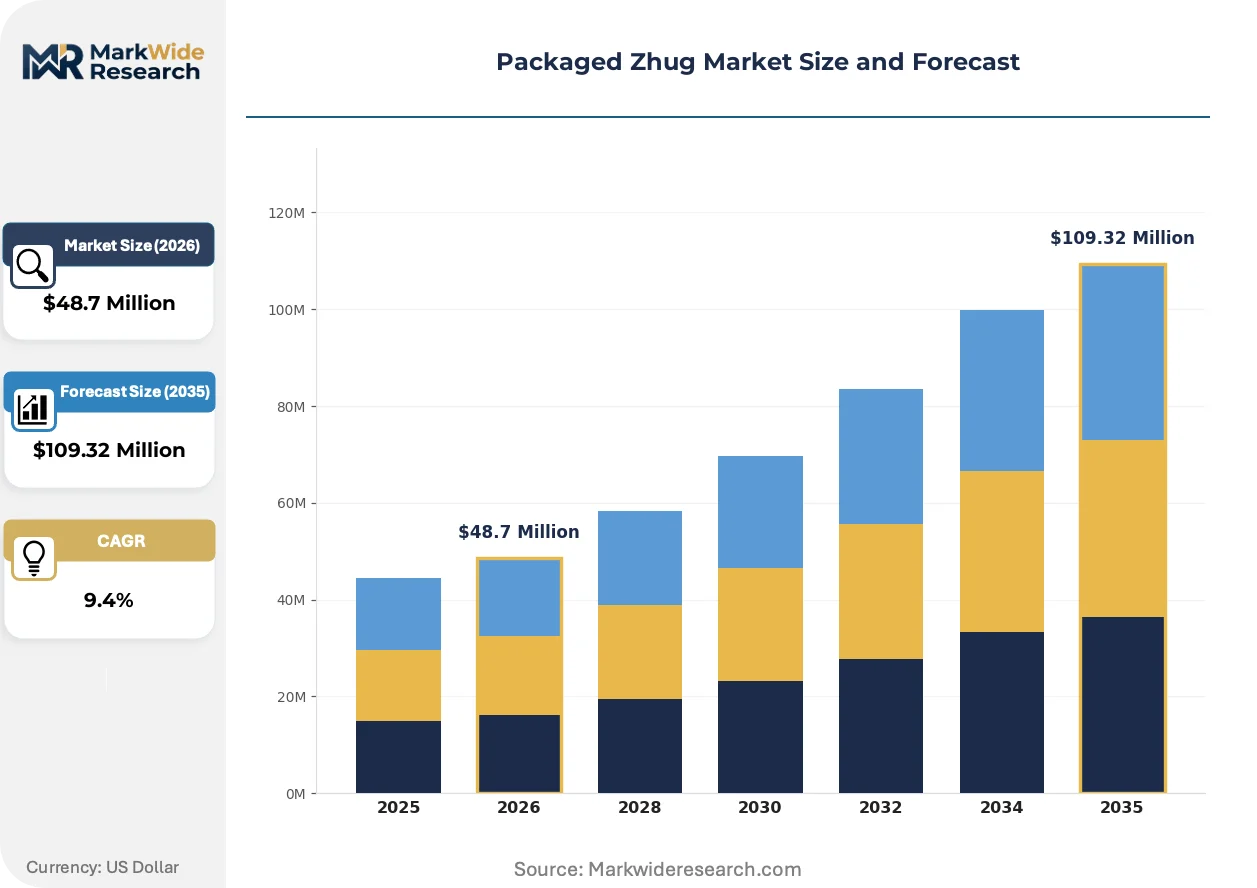
Clean-label formulation mandates from FDA and EFSA are compressing ingredient lists and forcing thermal process redesigns across shelf-stable zhug manufacturing, while EU Green Deal packaging directives accelerate material transitions that fragment cost structures between premium and mass-market tiers.
Growth Catalysts
- EFSA Clean-Label Frameworks:Additive authorization restrictions in Europe reward preservative-free recipes with expanded retail authorization and shelf placement priority.
- Foodservice Marinade Adoption:Middle Eastern and Mediterranean restaurant chains in the United States incorporate zhug as standard marinade base, creating institutional volume anchors.
- Diaspora Community Concentration:Metropolitan clusters in Michigan, California, and New York sustain baseline demand that reduces new market entry risk for specialty condiment entrants.
Market Restraints
- Fresh Chili Input Volatility:Jalapeño and serrano pepper spot markets exhibit seasonal price swings that compress margin predictability for small-batch producers.
- Glass Jar Supply Concentration:Premium packaging substrate sourcing clusters in Italy and Spain, exposing brands to single-region disruption risk.
- pH Stability Technical Ceiling:Ambient shelf life extension beyond 18 months requires formulation compromises that conflict with clean-label positioning.
Strategic Opportunities
- United Kingdom Retail Underpenetration:Specialty condiment shelf space in British supermarkets remains underdeveloped relative to German and French equivalents.
- EU Green Deal Packaging Incentives:Extended producer responsibility schemes reward compostable and recycled-content formats with reduced compliance fees.
- Direct-to-Restaurant Distribution:Bypassing distributor markups via refrigerated logistics partnerships with regional foodservice operators preserves margin.
Industry Challenges
- Thermal Process Engineering Talent Scarcity:Acidified food specialists with 21 CFR 114 compliance experience command premium compensation that strains mid-cap R&D budgets.
- BIS Certification Timeline Compression:Indian-manufactured variants face extended laboratory testing queues that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaged Zhug Market |
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Zhug, Red Zhug, Mild Zhug, Spicy Zhug Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Foodservice Packaging Type: Squeeze Bottles, Glass Jars, Pouches, Jars End User: Restaurants, Households, Caterers, Food Manufacturers |
| Companies Covered | Sabra Dipping Company, Grecian Delight Foods, Steenbergs, Chili Food, Zahavi Hakerem, WholeSpice, Conagra Brands, Hormel Foods Corporation, Kikkoman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaged Zhug Market Evolving Landscape
Refrigerated supply chain infrastructure and formulation science are converging to expand zhug's addressable occasions beyond traditional table-sauce positioning into marinade and cooking-ingredient categories.
High-pressure processing technology is modularizing clean-label pasteurization workflows. Mid-scale manufacturers in California and Texas adopt HPP units to achieve ambient-stable pH targets without thermal degradation of cilantro volatile compounds. This capability compression enables regional brands to compete on shelf-life parity with national processors.
EU Green Deal packaging waste directives are forcing material format decisions across European retail channels. Extended producer responsibility schemes impose cost penalties on conventional plastic squeeze bottles while rewarding glass and compostable alternatives. Premium zhug positioning in Germany and France now requires substrate credentials that mass-market tiers cannot absorb.
Foodservice procurement is consolidating around multi-year condiment supply agreements that bundle zhug with tahini and hummus portfolios. Independent Mediterranean restaurants in Chicago and Houston increasingly source through broadline distributors rather than ethnic-specialty importers. This channel compression rewards processors with existing refrigerated distribution density.
Packaged Zhug Market Segmentation
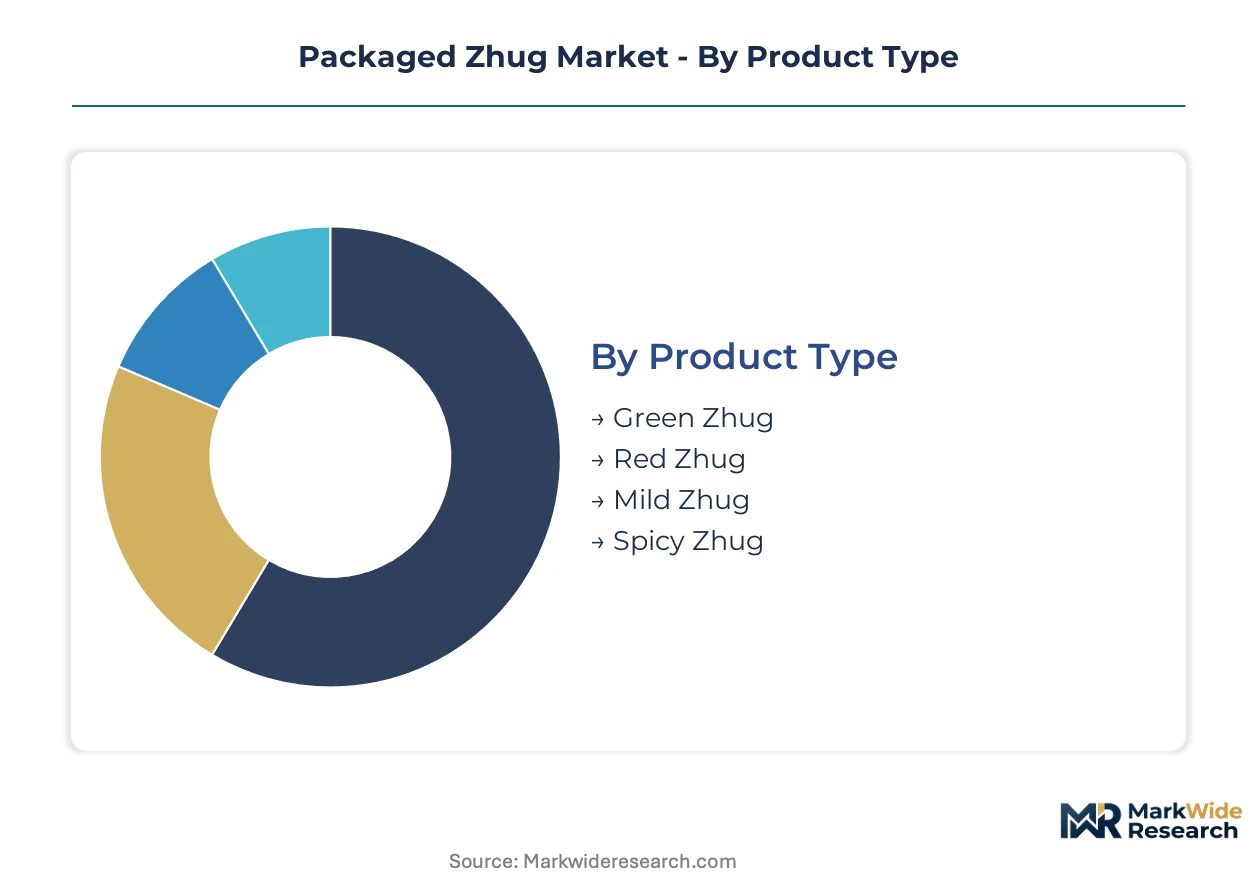
Segmentation in the packaged zhug market reveals divergent compliance burdens and margin architectures across product formulations and channel pathways. FDA acidified food regulations under 21 CFR 114 apply unevenly across shelf-stable versus refrigerated variants, while EU Green Deal packaging directives reshape cost structures by substrate choice.
Product Type:
FDA 21 CFR 114 thermal processing requirements apply universally across all variants, though pH stability thresholds vary by chili intensity and oil emulsion ratios.
- Green Zhug:Fresh cilantro and green chili emulsion with cardamom and cumin, typically achieving pH 4.2-4.5 for ambient stability. Demand concentrates in United States metropolitan clusters—Michigan, California, and New York—where Mediterranean and Middle Eastern diaspora communities sustain baseline volume. Visual differentiation on retail shelves drives placement priority in specialty food retailers.
- Spicy Zhug:Elevated Scoville profiles from serrano or habanero varieties, requiring modified thermal protocols to preserve volatile compounds. Foodservice channels in Chicago and Houston generate disproportionate margin contribution as Mediterranean restaurant chains adopt multi-year condiment supply bundles.
- Red Zhug:Dried chili base with deeper umami extraction, favored by food manufacturers seeking marinade ingredient stability.
- Mild Zhug:Reduced heat profile broadening household penetration among heat-averse consumers in European markets.
Leading the category by volume: Green Zhug. Expanding most quickly: Spicy Zhug.
Distribution Channel:
Channel selection dictates working capital intensity and regulatory exposure, with refrigerated logistics requirements fragmenting margin structures between mass-market and premium tiers.
- Supermarkets:Sabra Dipping Company leverages established hummus distribution networks to secure refrigerated placement for zhug variants in mainstream United States retail. Clean-label formulation credentials determine shelf authorization under EFSA additive frameworks.
- Specialty Stores:Glass jar formats command price premiums where artisanal provenance and transparent ingredient sourcing anchor positioning. Steenbergs extends organic spice sourcing reputation into this channel through ethical supply chain narratives.
- Online Retailers:Direct-to-consumer fulfillment bypasses distributor markups but requires cold-chain infrastructure investment.
- Foodservice:Broadline distributor consolidation in Chicago and Houston compresses ethnic-specialty importer margins.
Supermarkets dominate absolute volume. Specialty stores generate highest per-unit margin.
Packaging Type:
Material format decisions increasingly reflect extended producer responsibility compliance costs rather than purely functional requirements.
- Squeeze Bottles:Polyethylene formats lead household segment unit sales for convenience-driven application. EU Green Deal packaging waste directives impose cost penalties on conventional plastic substrates that mass-market tiers struggle to absorb.
- Glass Jars:Premium positioning substrate concentrated in Italian and Spanish supply bases, exposing brands to single-region disruption risk. Compostable and recycled-content alternatives gain reduced compliance fees under European extended producer responsibility schemes.
- Pouches:Flexible formats emerging in foodservice bulk procurement for marinade and cooking-ingredient applications.
- Jars:Standard ambient-stable formats for shelf-stable variants meeting FDA acidified food regulations.
Squeeze bottles command household volume leadership. Glass jars sustain premium positioning.
End User:
End-use concentration determines formulation complexity and certification burden, with institutional buyers imposing stricter documentation requirements than household segments.
- Restaurants:Independent Mediterranean operators in Houston and Chicago increasingly source through broadline distributors rather than ethnic-specialty importers. Multi-year condiment supply agreements bundle zhug with tahini and hummus portfolios, compressing standalone supplier margins.
- Households:Convenience-driven application favors squeeze bottle formats and milder heat profiles. United States metropolitan areas with established diaspora communities sustain repeat purchase velocity.
- Caterers:Volume procurement with formulation consistency requirements favoring pouch and jar formats for event-scale preparation.
- Food Manufacturers:Ingredient-grade specifications for marinade and sauce incorporation, requiring BIS certification for Indian-sourced variants.
Restaurants anchor institutional volume. Households represent the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's metropolitan corridor anchors North American zhug demand through concentrated Middle Eastern diaspora communities and established Mediterranean restaurant networks.
United States
Michigan, California, and New York sustain baseline volume through diaspora concentration and foodservice adoption. FDA acidified food regulations under 21 CFR 114 govern thermal processing for shelf-stable distribution. Chicago's independent Mediterranean restaurants increasingly source zhug through broadline distributors rather than ethnic-specialty importers.
Germany
Specialty condiment shelf space in German supermarkets exceeds British and French equivalents, driving placement priority for premium variants. EU Green Deal packaging waste directives impose cost penalties on conventional plastic substrates. Berlin's retail channels reward compostable and recycled-content formats with reduced extended producer responsibility fees.
United Kingdom
Specialty condiment penetration in British supermarkets remains underdeveloped relative to continental European markets, creating whitespace for entrants. EFSA clean-label additive authorization frameworks shape formulation decisions for retail authorization. London's foodservice distributors are consolidating procurement around multi-year condiment supply bundles.
France
Glass jar formats command price premiums in French specialty retail where artisanal provenance credentials determine positioning. EU Green Deal sustainability targets for food packaging decouple conventional plastic formats from premium zhug positioning. Parisian specialty food retailers expand shelf space for Middle Eastern condiments as consumer palates diversify.
India
BIS certification requirements affect market access for Indian-manufactured zhug variants seeking formal retail distribution in target export markets. Extended laboratory testing queues compress entry timelines for processors. Maharashtra's food manufacturing clusters face talent scarcity for acidified food specialists with compliance experience.
Packaged Zhug Market Competitive Landscape
The competitive structure tilts toward established Mediterranean condiment specialists leveraging refrigerated distribution density. Market participation fragments across hummus-centric portfolio players, organic spice sourcing specialists, and authentic heritage-positioned brands. Three archetypes dominate: refrigerated placement specialists, clean-label organic purveyors, and authentic Mediterranean credential holders. Capacity expansion in high-pressure processing technology and strategic partnerships with broadline foodservice distributors represent the primary competitive vectors.
Among refrigerated distribution specialists, Sabra Dipping Company occupies a position exemplifying hummus-network leverage into mainstream supermarket placement. Within the authentic heritage tier, Grecian Delight Foods anchors Mediterranean condiment credibility competing on provenance rather than price. Steenbergs represents the organic spice sourcing archetype, extending ethical supply chain reputation through transparent procurement narratives into premium specialty retail channels.
| Leading Market Players |
|---|
| Sabra Dipping Company |
| Grecian Delight Foods |
| Steenbergs |
| Chili Food |
| Zahavi Hakerem |
| WholeSpice |
| Conagra Brands |
| Hormel Foods Corporation |
| Kikkoman Corporation |
| Others |
Value Network & Pricing Analysis
Captive sourcing of glass jar substrates from Italian and Spanish supply bases anchors premium zhug positioning while simultaneously constraining pricing flexibility for mid-tier entrants. FDA acidified food regulations under 21 CFR 114 impose thermal processing investments that mass-market processors cannot amortize, compressing competitive intensity at the economy tier and preserving margin pools for compliant incumbents.
Pricing Analysis
Outcome-based pricing tied to clean-label shelf-life performance anchors premium zhug tiers, with three-tier pricing structure across premium, standard, and economy levels stratifying by certification grade and thermal process sophistication. Glass jar formats with organic spice sourcing credentials command substantial premiums in specialty retail, while polyethylene squeeze bottles face downward price pressure from EU Green Deal packaging compliance costs. Foodservice buyers exhibit lowest price sensitivity due to marinade application throughput requirements, whereas household segments in metropolitan diaspora clusters drive volume through repeat purchase velocity rather than premium positioning.
Supply Chain Analysis
EU Green Deal domestic-content mandates for recycled packaging substrates are reshaping sourcing toward compostable alternatives that fragment cost structures between European and North American production footprints. Fresh chili inputs concentrate in Mexico and California growing regions, with cardamom and cumin sourcing anchored in Indian and Guatemalan supply bases. Single-region glass jar supply concentration in Italy and Spain exposes brands to disruption risk from logistics chokepoints. Distribution runs through refrigerated broadline networks for foodservice and ethnic-specialty importers for independent restaurant segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA acidified food regulations under 21 CFR 114 erect a formidable cost-of-compliance barrier that moats compliant processors from commodity condiment competition, rewarding thermal process engineering investments with sustained shelf authorization and foodservice procurement access.
For Market Incumbents: To counter high-pressure processing technology modularization by California and Texas regional competitors, Sabra Dipping Company and Grecian Delight Foods should deepen backward integration into organic spice sourcing and expand captive high-pressure processing capacity. Channel control through multi-year condiment supply bundles with broadline distributors preserves margin against ethnic-specialty importer compression. For New Entrants and Emerging Players: Begin with United Kingdom retail underpenetration, where specialty condiment shelf space in British supermarkets remains underdeveloped relative to German and French equivalents. Direct-to-restaurant distribution partnerships with Chicago and Houston Mediterranean restaurant networks bypass distributor markups while building refrigerated logistics credibility for eventual retail expansion. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by hummus-centric portfolio players seeking refrigerated condiment density, with long-term viability hinging on clean-label thermal process capabilities rather than commodity formulation scale. Monitor EU Green Deal packaging waste directive implementation timelines as the inflection signal for substrate format winners.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | Enables clean-label pasteurization without thermal degradation of cilantro volatile compounds. |
| Backward Integration into Organic Spice Sourcing | Secures transparent procurement narratives that Steenbergs leverages for premium specialty retail placement. |
| Refrigerated Broadline Distribution Partnerships | Compresses ethnic-specialty importer margins in Chicago and Houston foodservice consolidation. |
| Compostable Packaging Format Transition | Captures reduced extended producer responsibility fees under EU Green Deal directives in Berlin retail channels. |
| Direct-to-Restaurant Logistics Infrastructure | Bypasses distributor markups while building cold-chain credibility for household segment expansion. |
Research Methodology
Trade databases, customs records, and FDA 21 CFR 114 filing repositories formed the secondary backbone, supplemented by primary interviews with thermal process engineers at acidified food manufacturers, category buyers at specialty food retailers, procurement managers at broadline foodservice distributors, and R&D directors at Mediterranean condiment processors. Bottom-up volume triangulation across product type, packaging format, and distribution channel segments converged with top-down value estimates derived from retail audit data and foodservice procurement contract analysis.
Historical trendline analysis across the analysis window established baseline growth trajectories, with CAGR derivation reflecting segment-specific demand elasticity for green versus spicy zhug variants, refrigerated versus shelf-stable format adoption rates, and foodservice marinade application expansion. Modeled dimensions included product formulation intensity, packaging substrate compliance tier, channel refrigeration requirements, and diaspora community concentration density as geographic demand drivers.
Underlying measurement precision varies by segment; foodservice procurement volumes carry tighter precision than direct-to-consumer online retail estimates due to consolidated buyer transparency. Forecasts reflect assumptions regarding EFSA additive authorization continuity and chili input price volatility. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
On-The-Go Breakfast Cereals Market
Packaged Foods
Canned Food Market
Packaged Foods
Reduced Fat Packaged Food Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Food and Beverages Market
Packaged Foods
Sugar Free Cookies Market
Packaged Foods
Burritos Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Pasta and Noodles Market
Packaged Foods
North America Pasta Market
Packaged Foods
Cookie Butter Spread Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Private Label Food and Beverage Market