
 Dinner Ready-To-Eat (RTE) Food Market | 2026-2036
Dinner Ready-To-Eat (RTE) Food Market Size, Share, and Industry Trends Forecast 2026-2036
Dinner Ready-To-Eat (RTE) Food Market Outlook
Modular meal bundling is repositioning how consumers assemble complete dinner solutions from component RTE items rather than single-serve packages. Nestlé S.A. leverages its global frozen and shelf-stable portfolio to dominate multi-format bundling across retail channels. Conagra Brands, Inc. anchors its competitive stance through specialized microwaveable platforms and streamlined manufacturing scale. Kraft Heinz Company differentiates via brand equity in comfort-oriented entrees and controlled distribution through mass retail partnerships.
Dinner Ready-To-Eat (RTE) Food comprises fully prepared, thermally processed or flash-frozen meal solutions requiring minimal consumer preparation beyond reheating, typically formulated with protein, starch, and vegetable components in standardized portion configurations. These products serve industrial and commercial purposes by eliminating cooking labor, reducing food waste through precise portioning, and extending edible shelf life through retort, blast-freezing, or modified-atmosphere packaging techniques. Frozen dinners command the largest volume position within product type segmentation due to entrenched freezer-aisle infrastructure and consumer familiarity, while shelf-stable entrees represent the fastest-expanding category driven by ambient distribution economics and emergency-preparedness purchasing. The delivery model dimension shows subscription services capturing disproportionate margin pools through recurring revenue structures and direct customer data access, though retail stores sustain the dominant transaction volume.
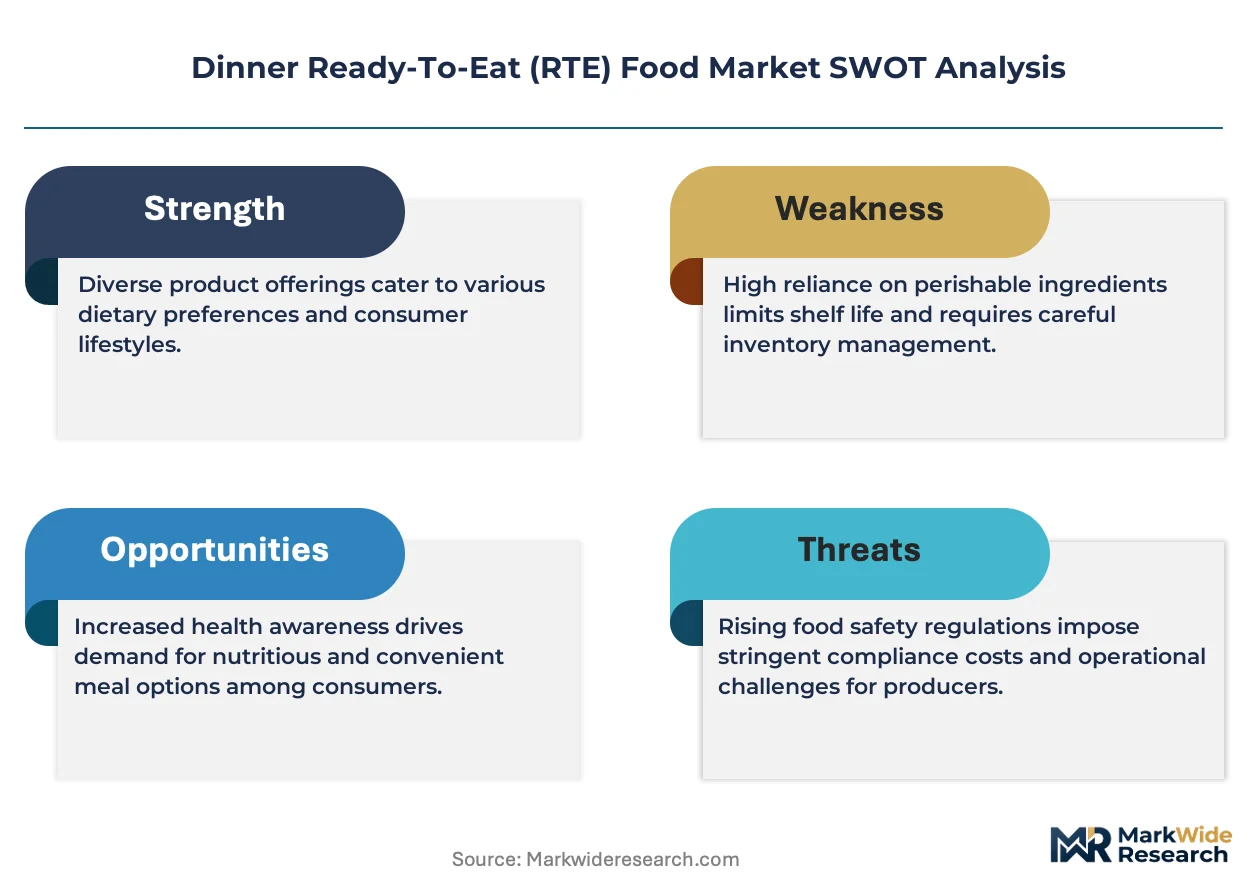
The FDA governs nutritional labeling, pathogen control, and ingredient disclosure for RTE dinner products distributed in the United States, while USDA oversight applies to meat- and poultry-containing formulations through specific inspection protocols. State-level health departments supplement federal frameworks with additional refrigeration and handling requirements that shape regional distribution feasibility. EFSA and national regulators across Europe enforce distinct additive thresholds and recycling-content packaging rules that condition market access for exporters. Stakeholders must monitor evolving sodium and added-sugar threshold proposals across multiple jurisdictions, as compliance redesign costs will determine which product lines maintain shelf placement without reformulation-driven margin erosion.
Market Dynamics
FDA sodium reduction mandates and updated Nutrition Facts labeling requirements are forcing reformulation across protein-starch-vegetable configurations, compressing margin structures for manufacturers reliant on legacy seasoning systems.
Growth Catalysts
- Dual-income household time scarcity:Working parents in the United States allocate fewer than 30 minutes to meal preparation on weeknights, elevating complete dinner solutions over component cooking.
- REACH packaging compliance:European recycling-content thresholds for plastic trays are accelerating fiber-based and aluminum alternatives that extend ambient shelf stability.
- Blast-freezing technology:Cryogenic tunnel systems preserve vegetable texture integrity previously degraded by mechanical freezing, expanding acceptable quality thresholds.
Market Restraints
- Input cost volatility:Chicken and beef protein inputs fluctuate with feed grain prices and processing plant capacity constraints in the Midwest United States.
- Supply concentration risk:Modified-atmosphere packaging film production clusters in Germany and South Korea, creating single-source dependency for shelf-stable entree exporters.
- Technical limitation:Retort processing degrades cruciferous vegetable color and mouthfeel, limiting nutritional completeness claims in ambient formats.
Strategic Opportunities
- Subscription channel expansion:Direct-to-consumer platforms capture recurring revenue and first-party consumption data unavailable through retail intermediaries.
- IRA clean energy incentives:United States tax credits for solar-powered cold storage reduce distribution center operating costs in Texas and Arizona.
- High-pressure processing convergence:Cold pasteurization extends refrigerated shelf life without thermal degradation, enabling cleaner-label positioning.
Industry Challenges
- Reformulation timeline compression:FDA sodium phase-down deadlines require R&D cycles that outpace existing flavor masking technology maturity.
- Cold-chain certification complexity:HACCP validation for new co-packing facilities delays regional expansion by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dinner Ready-To-Eat (RTE) Food Market |
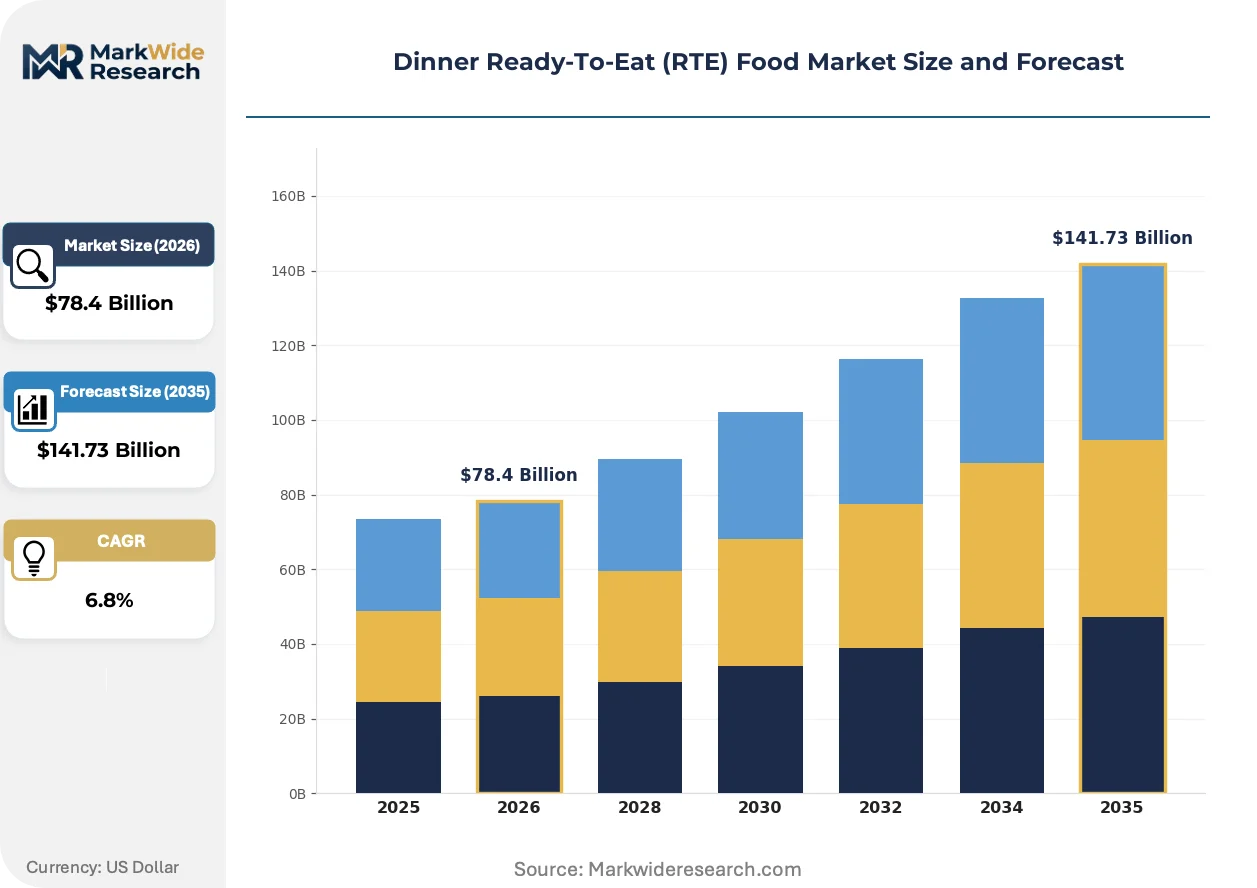
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Meals, Frozen Dinners, Shelf-Stable Entrees, Microwaveable Options End User: Busy Professionals, Students, Families, Seniors Delivery Model: Direct-to-Consumer, Retail Stores, Online Marketplaces, Subscription Services Price Tier: Premium, Mid-Range, Economy, Value |
| Companies Covered | Nestlé S.A., Conagra Brands, Inc., Kraft Heinz Company, General Mills, Inc., Hormel Foods Corporation, Tyson Foods, Inc., Campbell Soup Company, Unilever PLC, Nomad Foods Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dinner Ready-To-Eat (RTE) Food Market Strategic Shifts
Active packaging systems and precision thermal processing are compressing the quality gap between restaurant-prepared and factory-manufactured dinner solutions.
High-pressure processing is converging with sous-vide protein staging to eliminate pathogen risk without overcooking. Premium meal-kit assemblers in California and New York are adopting these hybrid systems to support 45-day refrigerated shelf claims. The technology convergence is collapsing the historical trade-off between food safety assurance and sensory quality.
EFSA additive threshold reviews are tightening benzoate and nitrite allowances across ready-to-eat meat formulations. Manufacturers serving the European Union must reformulate preservation systems or sacrifice ambient distribution economics. The regulatory pressure is most acute in shelf-stable entree categories where clean-label alternatives command 12-18% manufacturing cost premiums.
Modular bundling behavior is displacing single-serve package preference among suburban households with children. Retailers are responding with mix-and-match freezer sections that separate proteins, starches, and vegetables for at-home assembly. This consumption-pattern shift concentrates in the United States where expanded cold-chain retail infrastructure supports componentized merchandising.
Dinner Ready-To-Eat (RTE) Food Market Segmentation
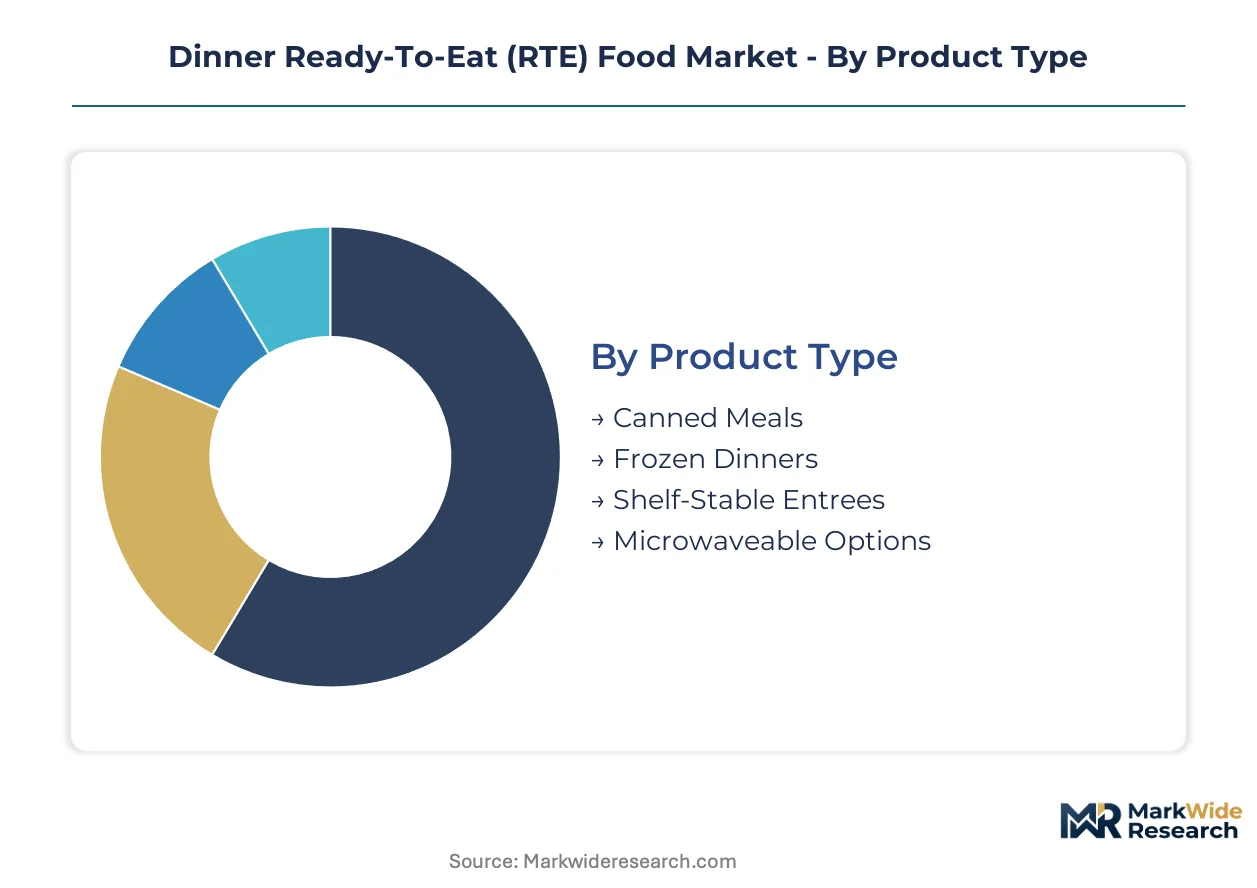
Segmentation in the Dinner RTE Food Market reveals how supply-side capabilities and distribution economics partition demand across format, user, and channel dimensions. Manufacturers configure production lines and cold-chain investments around specific segment requirements rather than pursuing universal coverage.
Product Type:
Supply concentration for thermal processing equipment and freezer-aisle infrastructure shapes competitive positioning across product formats.
- Frozen Dinners:Blast-frozen protein-starch-vegetable combinations packaged in multi-compartment trays. Demand clusters in suburban United States households with full-size freezer capacity, supported by entrenched retail aisle infrastructure and established replenishment logistics.
- Shelf-Stable Entrees:Retort-pouched or tray-sealed meals achieving 12-24 month ambient stability through high-temperature sterilization. Adoption accelerates in emergency-preparedness purchasing and military/institutional procurement where refrigeration is unavailable.
- Canned Meals:Traditional metal-container packaging with extended shelf life but reduced texture quality. Survives in value-oriented retail and food-bank distribution channels.
- Microwaveable Options:Susceptor-equipped packaging enabling rapid reheating without conventional oven transfer. Concentrates in workplace breakroom and college dormitory consumption occasions.
Frozen Dinners absorbs the bulk of installed capacity; Shelf-Stable Entrees is expanding most quickly.
End User:
Time scarcity and cooking skill deficits create distinct user segments with divergent willingness-to-pay and format preferences.
- Busy Professionals:Dual-income households with sub-30-minute weeknight preparation windows. Demand concentrates in premium frozen and subscription-delivered formats where convenience commands price tolerance.
- Families:Multi-person households seeking portion-scalable solutions with child-acceptable flavor profiles. Volume concentrates in mid-range frozen multi-packs and modular component systems.
- Students:Price-constrained, storage-limited consumers in dormitory or shared housing. Shelf-stable and microwaveable formats dominate; bulk purchasing and promotional sensitivity shape behavior.
- Seniors:Single-serve preference driven by household size reduction and chewing/digestion considerations. Soft-texture frozen entrees and sodium-controlled shelf-stable options show concentration.
Families captures the greatest transaction volume; Busy Professionals generates the steepest expansion trajectory.
Delivery Model:
Channel economics and data access privileges stratify margin capture and customer relationship depth.
- Retail Stores:Mass-market and specialty grocers with cold-chain display infrastructure. Sustains dominant transaction volume through impulse purchasing and established shopping rituals.
- Subscription Services:Direct-to-consumer platforms with recurring revenue structures and first-party consumption data. Captures disproportionate margin pools through personalization and inventory pre-commitment.
- Online Marketplaces:Third-party platforms aggregating multiple brands with fulfillment through retail partners or dedicated warehouses. Growth concentrates in pantry-loading purchase occasions.
- Direct-to-Consumer:Manufacturer-owned channels bypassing retail intermediaries. Emerging as a testbed for limited-edition and premium positioning before retail rollout.
Retail Stores maintains the largest installed base; Subscription Services climbs the fastest.
Price Tier:
Ingredient quality, portion size, and packaging sophistication stratify manufacturing cost structures and margin profiles.
- Premium:Restaurant-equivalent positioning with chef-developed recipes, premium proteins, and sustainable packaging. Concentrates in coastal United States metro markets and subscription channels.
- Mid-Range:Mainstream branded offerings balancing quality signals with mass-market accessibility. Dominates national retail distribution and promotional calendar activity.
- Economy:Private-label and value-brand positioning with simplified formulations and basic packaging. Volume concentrates in discount retail and food-service diversion channels.
- Value:Aggressive price positioning through ingredient substitution and reduced portion sizes. Serves extreme price sensitivity in institutional and emergency food assistance contexts.
Mid-Range commands the greatest production throughput; Premium gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in the United States and Germany while consumption growth accelerates across emerging Asian markets. Cold-chain infrastructure investments in China and India are redrawing distribution economics for frozen formats. Regulatory divergence between FDA sodium mandates and EFSA additive thresholds is fragmenting formulation strategies by destination market.
United States
Dual-income households in suburban corridors drive frozen dinner volume through mass retail channels. FDA updated Nutrition Facts labeling and sodium reduction phase-downs compress reformulation timelines for legacy product lines. Chicago and Omaha processing clusters concentrate blast-freezing capacity serving national distribution networks.
Germany
REACH packaging compliance thresholds accelerate fiber-based tray adoption among exporters serving EU markets. EFSA benzoate and nitrite reviews force preservation system redesigns in shelf-stable meat formulations. The Ruhr industrial basin hosts modified-atmosphere packaging film production serving continental supply chains.
China
Urban middle-class expansion in tier-one cities elevates premium frozen entree demand through e-commerce platforms. SAMR food safety inspections intensify for imported RTE products at Shanghai and Shenzhen port facilities. Yangtze River Delta cold storage construction reduces last-mile distribution costs for temperature-sensitive formats.
Japan
Aging demographics and single-person households sustain demand for portion-controlled, soft-texture entrees. METI energy efficiency standards shape frozen logistics infrastructure investments in the Kanto region. Tokyo-Osaka corridor convenience store chains anchor high-frequency replenishment for microwaveable formats.
India
Organized retail penetration in Mumbai and Delhi NCR expands freezer-aisle infrastructure for branded frozen dinners. FSSAI labeling and additive regulations tighten for imported shelf-stable formulations. Gujarat and Maharashtra processing zones develop retort capacity targeting institutional and emergency-preparedment procurement channels.
Dinner Ready-To-Eat (RTE) Food Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across format and channel dimensions. The market exhibits tiered consolidation with multinational packaged food corporations commanding retail shelf space while regional processors capture contract manufacturing volumes. Three archetypes dominate: portfolio conglomerates leveraging cross-category distribution, protein-integrated players with captive raw material access, and subscription-native platforms built on direct consumer relationships. Capacity expansion and portfolio diversification through bolt-on acquisitions represent the primary competitive vectors as sodium reformulation deadlines compress R&D resource allocation.
Within the portfolio conglomerate tier, Nestlé S.A. and Unilever PLC exemplify scale-driven positioning across frozen and shelf-stable formats. Conagra Brands, Inc. occupies a specialist position emphasizing microwaveable platform development and manufacturing throughput optimization. These three entities anchor distinct strategic postures: Nestlé represents global multi-format bundling capability, Unilever exemplifies European-originated sustainability-forward positioning, and Conagra illustrates North American-focused operational specialization.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Conagra Brands, Inc. |
| Kraft Heinz Company |
| General Mills, Inc. |
| Hormel Foods Corporation |
| Tyson Foods, Inc. |
| Campbell Soup Company |
| Unilever PLC |
| Nomad Foods Limited |
| Others |
Value Chain & Pricing Dynamics
REACH packaging compliance thresholds gate qualified supply for European market access and anchor premium-tier pricing power for manufacturers investing in fiber-based tray alternatives. Manufacturers lacking certified sustainable packaging face exclusion from EU retail channels while compliant producers capture 12-18% manufacturing cost premiums that transmit through to shelf pricing.
Pricing Analysis
Margin tightening in mid-range frozen formats reflects sodium reformulation R&D cycles compressing legacy product profitability. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein quality grade and FDA nutritional certification tier. Cost-down pressure on economy segments accelerates because private-label substitution erodes branded shelf space. Students and price-constrained institutional buyers exhibit highest price sensitivity while dual-income busy professionals tolerate premium positioning.
Supply Chain Analysis
Modified-atmosphere packaging film supply rests on German and South Korean specialty chemical producers with limited qualified alternatives. Chicken and beef protein inputs draw from Midwest United States processing clusters while blast-freezing equipment concentrates in Chicago and Omaha manufacturing zones. Single-source dependency for shelf-stable entree barrier films creates vulnerability to regional logistics disruption. Distribution runs through mass retail cold-chain infrastructure with subscription platforms building parallel direct-to-consumer fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blast-freezing capacity scarcity in the United States props pricing power for manufacturers with secured cryogenic tunnel throughput, creating a supply-constrained market structure favoring incumbent expansion.
For Market Incumbents: Cement market position through backward integration into captive protein processing and accelerated sodium-reduction R&D investment ahead of FDA phase-down deadlines. Subscription-native entrants threaten recurring revenue capture; defend through exclusive retail partnerships and loyalty program data accumulation. For New Entrants and Emerging Players: Direct-to-consumer platforms offer the lowest barrier route for shelf-stable entree testing before mass retail rollout. Modular component bundling remains underpenetrated in suburban family segments; target this white space with mix-and-match protein-starch-vegetable configurations. Launch through regional cold-chain partnerships to bypass national distribution infrastructure gaps. For Investors and Strategic Acquirers: FDA sodium mandate compliance announcements are the leading indicator that reformulation-capable assets will command acquisition premiums. Five-to-ten year viability hinges on clean-label technology portfolios and subscription channel customer data assets. Monitor EFSA additive threshold reviews as signal for European market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Cold pasteurization extends refrigerated shelf life without thermal degradation for cleaner-label positioning. |
| Subscription Channel Expansion | Direct-to-consumer platforms capture recurring revenue and first-party consumption data unavailable through retail. |
| Fiber-Based Packaging Transition | REACH-compliant tray alternatives secure EU market access and support premium-tier pricing claims. |
| Blast-Freezing Capacity Addition | Cryogenic tunnel systems preserve vegetable texture integrity previously degraded by mechanical freezing methods. |
| Modular Component Bundling | Mix-and-match freezer sections separate proteins, starches, and vegetables for at-home assembly by suburban families. |
Study Parameters
Independent corroboration across brand managers at diversified food conglomerates, category buyers at mass retail chains, and supply planners at cold-chain logistics operators underwrites the qualitative findings. Secondary validation draws from FDA sodium mandate filings, USDA inspection protocol updates, Nielsen retail audit data, and SEC 10-K disclosures by packaged food manufacturers. Bottom-up segment sizing triangulates against top-down macroeconomic consumption indicators.
Rate-of-change decomposition across product format, end-user archetype, delivery channel, and price tier dimensions structures the analytical framework. CAGRs derive from segment-level volume trajectories and value-per-unit trends across the projection horizon. Forecast inputs incorporate blast-freezing capacity expansion timelines, REACH packaging compliance adoption curves, and subscription platform customer acquisition costs.
The model holds under stable cold-chain infrastructure investment and consistent regulatory phase-down schedules; deviation in feed grain price volatility or modified-atmosphere film supply disruption would shift volume and value outputs. Forecasts reflect documented assumptions about dual-income household time scarcity persistence and sodium reduction technology maturity. A small set of named triggers—EFSA additive threshold finalization, IRA clean energy credit utilization rates, and SAMR import inspection intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Chestnut Flour Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
Convenience Food Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Global Aseptic Packaging in Food Market
Packaged Foods
US Canned Foods Market
Packaged Foods
Microwavable Foods Market
Packaged Foods
Canned Tropical Fruit Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Europe Food Spread Market
Packaged Foods
Sugar-Free Biscuits and Cookies Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Wet Food Pouch Market
Packaged Foods
Quinoa Pasta Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Air-Dried Food Market