
 Protein-Based Fat Replacer Market | 2026-2036
Protein-Based Fat Replacer Market Size, Share, and Industry Trends Forecast 2026-2036
Protein-Based Fat Replacer Market Analytics
The EU Green Deal is expanding the addressable market for protein-based fat replacers as European food manufacturers face mandatory front-of-pack nutritional labeling requirements. Cargill Incorporated leverages its integrated protein supply chain to deliver consistent whey-based replacer volumes across the continent. Fonterra Co-operative Group Limited anchors its position through dairy protein specialization and New Zealand-origin sourcing credibility. Kerry Group differentiates via flavor-masked protein systems that preserve sensory profiles in reduced-fat formulations.
Protein-based fat replacers comprise functional ingredients, typically whey or plant-derived proteins processed into microparticulated or emulsion-stabilizing forms, that mimic the mouthfeel and texture of fats while delivering substantially lower caloric density. Emulsifiers and stabilizers dominate product type demand as bakery and dairy applications require precise fat mimetic behavior under thermal stress. Hydrocolloids represent the fastest-growing category where meat product reformulation drives uptake of synergistic protein-gum systems for juiciness retention.
REACH compliance governs chemical additive thresholds in European protein fat replacer formulations, while EFSA nutritional claims standards dictate permissible health marketing on reduced-fat products. FDA GRAS self-determination shapes US market entry pathways for novel protein hydrolysate replacers, creating divergence in approval timelines between jurisdictions. Stakeholders must monitor evolving front-of-pack labeling mandates across multiple jurisdictions to anticipate reformulation cycle timing and secure early-mover positioning in next-generation clean-label fat replacement platforms.
Market Dynamics
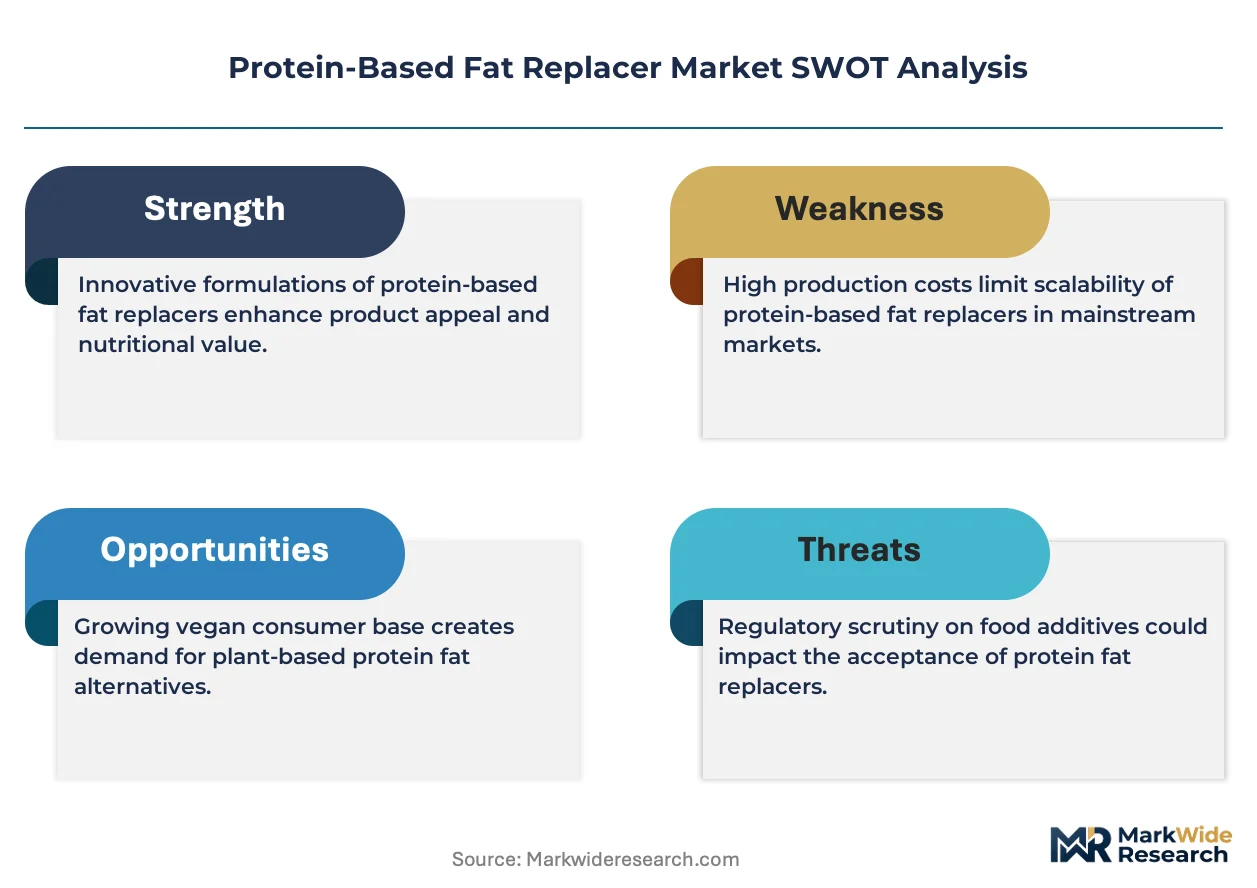
EU Green Deal nutritional labeling mandates are forcing dairy and bakery manufacturers to accelerate reformulation cycles, compressing supplier qualification timelines and privileging established protein fat replacer platforms with proven clean-label credentials.
Growth Catalysts
- REACH-compliant emulsifier systems:European food manufacturers face mandatory disclosure thresholds for chemical additives, expanding demand for protein-based alternatives that bypass ECHA scrutiny.
- Dairy product reformulation:Reduced-fat cheese and yogurt applications in Germany and France are absorbing microparticulated whey proteins at accelerated rates.
- Clean-label bakery clusters:Artisan bread and pastry producers in Copenhagen and Amsterdam are specifying protein-gum hybrid systems for moisture retention without synthetic stabilizers.
Market Restraints
- Whey protein concentrate volatility:New Zealand dairy commodity pricing swings transmit directly to replacer formulation costs, squeezing processor margins during peak milk production cycles.
- EFSA health claim substantiation:Reduced-fat product marketing requires clinical validation dossiers that extend launch timelines by 18-24 months.
- Plant protein functionality gaps:Pea and fava protein isolates exhibit inferior emulsion stability under retort conditions, limiting penetration into ambient-stable prepared meals.
Strategic Opportunities
- Meat analog white space:Juiciness retention in hybrid and plant-based sausages remains underaddressed by current protein-fat hybrid systems.
- CSRD-aligned sourcing:Scope 3 emissions disclosure requirements favor regional European protein suppliers with transparent farm-to-ingredient traceability.
- Precision fermentation lipids:Convergence of microbial protein production with tailored fat mimetics enables next-generation sensory matching in premium ice cream.
Industry Challenges
- Food technologist scarcity:Formulation expertise spanning protein chemistry, rheology, and sensory science concentrates in Netherlands and Danish research clusters.
- Clean-label certification backlog:Third-party non-GMO and organic validations face 6-9 month queues at accredited European bodies.
- Legacy equipment retrofitting:Existing spray-drying infrastructure requires modification to handle microparticulated protein slurries without agglomeration defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Protein-Based Fat Replacer Market |
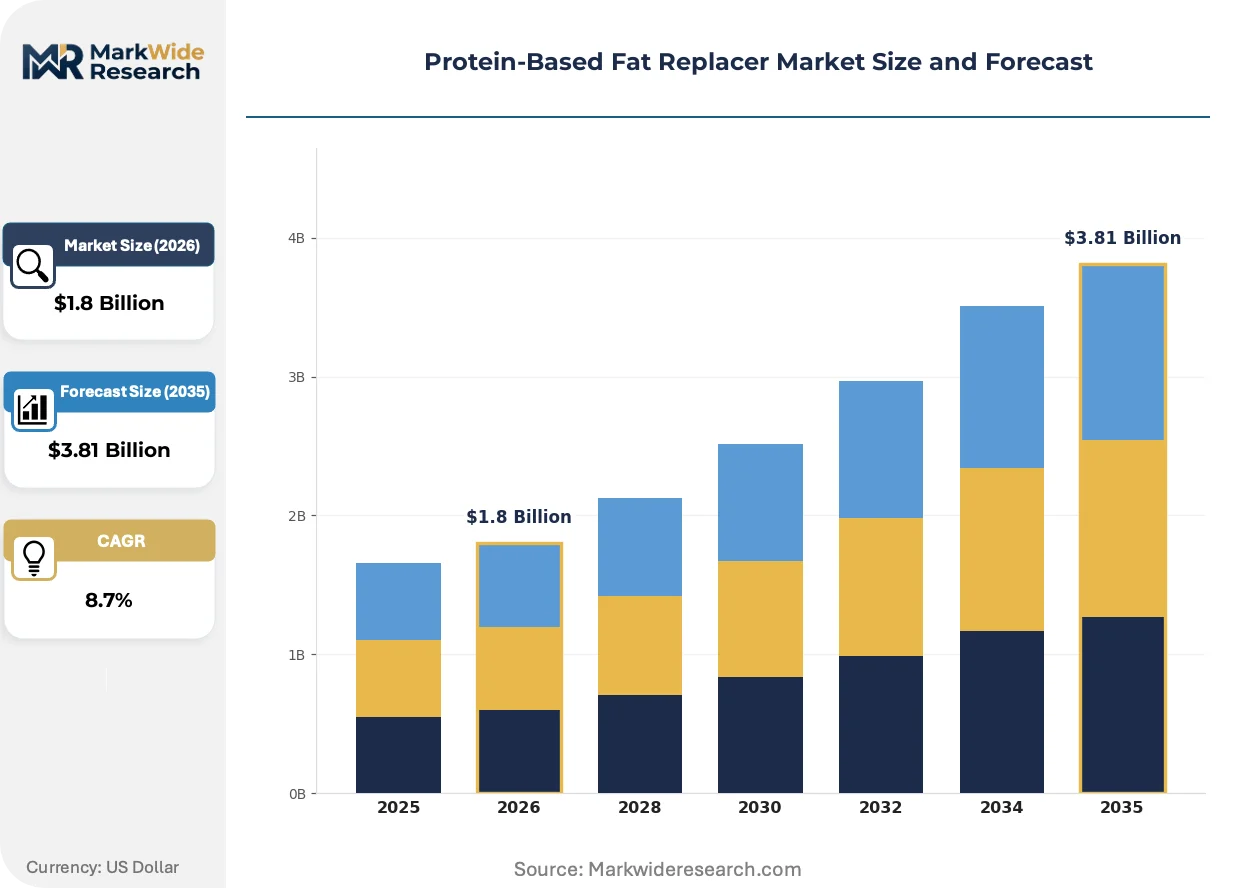
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Stabilizers, Thickeners, Hydrocolloids Application: Dairy Products, Bakery, Meat Products, Snacks Form: Powder, Liquid, Granular, Sheet End User: Food Manufacturers, Restaurants, Catering Services, Retailers |
| Companies Covered | Ingredion Incorporated, Fonterra Co-operative Group Limited, Cargill Incorporated, Royal Avebe, Arla Foods Ingredients Group, Archer Daniels Midland Company, Tate & Lyle, CP Kelco, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Protein-Based Fat Replacer Market Evolving Landscape
Microparticulation technology is compressing the performance gap between protein fat replacers and conventional fats, while regulatory disclosure mandates and procurement centralization are restructuring supplier-buyer relationships across European food manufacturing.
Algae-derived protein hydrolysates are overtaking conventional whey microparticles in premium frozen dessert applications. Italian gelato manufacturers have adopted these systems for thermal stability under display case conditions. The structural consequence is a bifurcation between commodity whey replacers and high-value marine protein platforms.
EU Green Deal front-of-pack Nutri-Score requirements are compelling reformulation investments across French and German retail channels. Manufacturers must achieve B-grade or higher ratings to maintain shelf positioning in major supermarket chains. Bakery and dairy segments are responding by accelerating supplier transitions to protein-based fat reduction systems with documented clean-label status.
Centralized procurement through pan-European food manufacturing groups is consolidating supplier rosters and extending contract durations. Category managers at multinational dairy processors now mandate multi-year volume commitments with price collars. This pattern is most visible in German private-label yogurt production, where three processor groups control 60% of protein replacer sourcing decisions.
Protein-Based Fat Replacer Market Segmentation
Protein-based fat replacer procurement diverges sharply between commodity-scale dairy processors seeking volume consistency and artisanal bakeries demanding tailored rheological profiles. Formulation complexity and regulatory disclosure thresholds fragment supplier specifications across end-use categories.
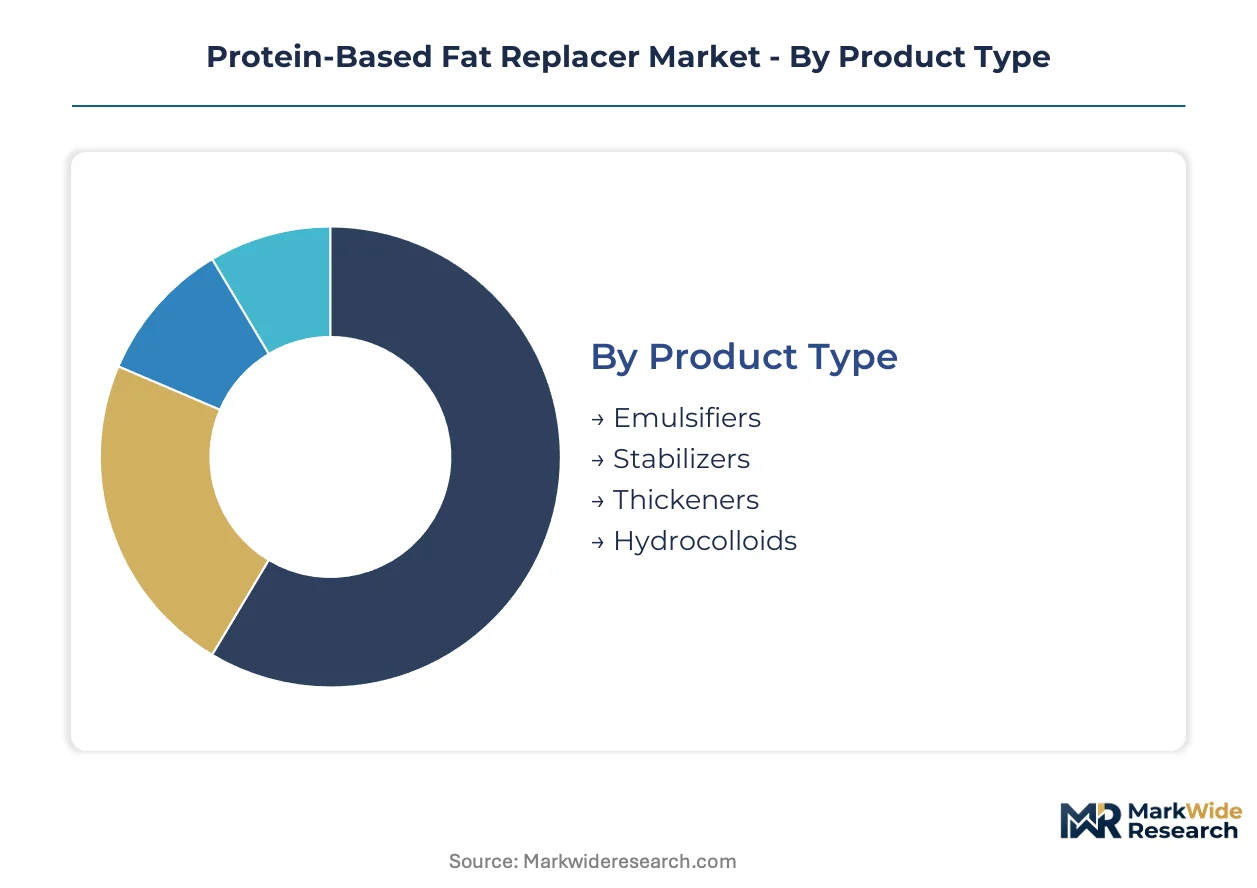
Product Type:
Standardized emulsifier platforms dominate high-volume dairy contracts, while hydrocolloid blends attract premium positioning through customized protein-gum synergies.
- Emulsifiers:Microparticulated whey proteins and modified dairy proteins stabilize oil-in-water emulsions under thermal stress. Dairy processors in Germany specify these systems for reduced-fat yogurt and cheese applications where EFSA nutritional claim substantiation drives clean-label procurement.
- Stabilizers:Protein-polysaccharide complexes prevent phase separation in retort-processed prepared meals. REACH-compliant formulations bypass ECHA disclosure thresholds, expanding uptake among French and Dutch manufacturers facing mandatory additive transparency.
- Thickeners:Concentrated protein isolates build viscosity in low-fat salad dressings and spreads.
- Hydrocolloids:Synergistic protein-gum systems for juiciness retention in meat reformulation are gaining share fastest in sausage and prepared meat segments.
Most installed capacity flows through Emulsifiers. Expansion is steepest in Hydrocolloids.
Application:
Volume concentration in mature dairy segments contrasts with margin expansion in meat analog development.
- Dairy Products:Reduced-fat cheese, yogurt, and ice cream formulations absorb microparticulated whey proteins at scale. German private-label processors mandate multi-year volume commitments with price collars, consolidating supplier rosters.
- Bakery:Artisan bread and pastry producers in Copenhagen and Amsterdam specify protein-gum hybrids for moisture retention without synthetic stabilizers.
- Meat Products:Hybrid and plant-based sausage applications remain underaddressed by current protein-fat systems.
- Snacks:Extruded protein crisps and reduced-fat savory formulations utilize emulsion-stabilizing replacers.
Dairy Products anchor current volume. Meat Products offer the steepest expansion trajectory.
Form:
Dry powder logistics favor continental distribution, while liquid concentrates reduce hydration steps for integrated dairy processors.
- Powder:Spray-dried microparticulated proteins dominate intercontinental shipping and extended shelf-life requirements. Legacy equipment retrofitting challenges constrain smaller European processors.
- Liquid:Ready-to-use protein slurries eliminate hydration variables in continuous dairy processing lines.
- Granular:Controlled particle size distributions for specific mouthfeel targeting in premium applications.
- Sheet:Structured protein matrices for layered bakery applications and fat replacement in laminated doughs.
Powder commands the majority of installed throughput. Liquid is climbing the fastest as dairy processors integrate inline dosing systems.
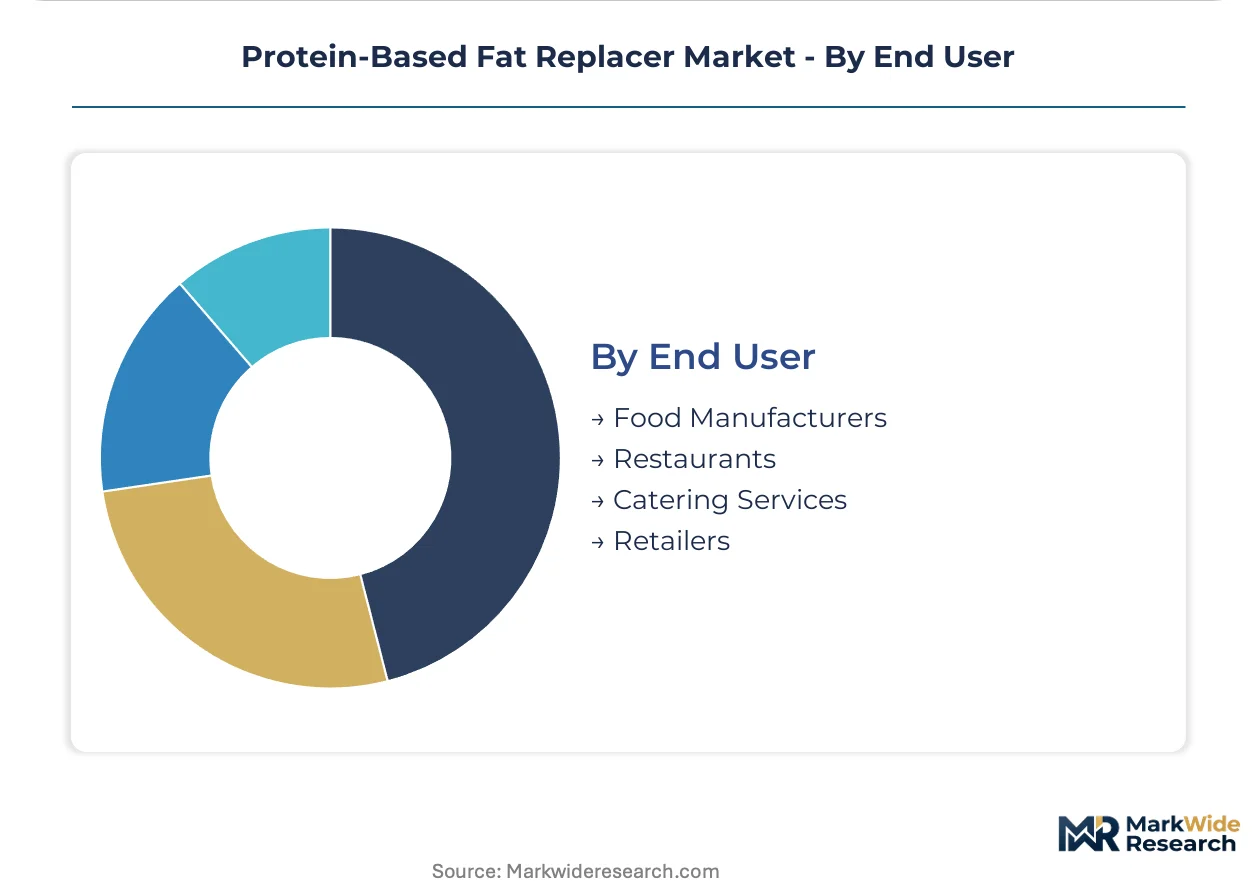
End User:
Centralized procurement through pan-European manufacturing groups privileges established suppliers, while foodservice channels demand flexible minimum order quantities.
- Food Manufacturers:Multinational dairy and bakery processors dominate volume absorption. Three German processor groups control the majority of protein replacer sourcing decisions through consolidated tender processes.
- Restaurants:High-end culinary applications specify premium protein-fat systems for menu differentiation.
- Catering Services:Institutional feeding contracts prioritize cost-stable emulsifier platforms with documented allergen management.
- Retailers:Private-label development teams at major supermarket chains drive reformulation to achieve EU Green Deal Nutri-Score B-grade ratings.
Food Manufacturers absorb most installed capacity. Retailers are expanding procurement most quickly as front-of-pack labeling mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protein-based fat replacer technology originated in European dairy research clusters during the 1980s, with microparticulated whey protein development pioneered at Wageningen University and subsequent commercialization through Dutch and Danish ingredient houses. This historical foundation established northwestern Europe as the enduring center of formulation expertise and regulatory standards-setting.
Germany
Private-label yogurt processors in Bavaria and North Rhine-Westphalia absorb the continent's largest volumes of microparticulated whey proteins. EFSA nutritional claim substantiation requirements compress supplier qualification timelines to 12-18 months. The Cologne-Düsseldorf corridor hosts concentrated reformulation laboratories serving pan-European dairy brands.
France
Artisan cheese makers in the Auvergne-Rhône-Alpes region deploy protein-fat hybrid systems for reduced-fat Comté and Emmental variants. EU Green Deal Nutri-Score B-grade mandates drive supermarket chain procurement shifts. Paris-based food technology clusters specialize in flavor-masked protein systems for premium applications.
Netherlands
Wageningen University-affiliated ingredient houses anchor global emulsifier innovation pipelines. REACH-compliant formulation standards developed here propagate across European manufacturing. The Eindhoven food processing equipment corridor supplies microparticulation spray-drying infrastructure continent-wide.
United States
Midwest dairy cooperatives scale whey protein concentrate output for domestic replacer formulation. FDA GRAS self-determination pathways accelerate novel protein hydrolysate approvals versus European timelines. Chicago-area food manufacturers integrate liquid protein slurry dosing into continuous processing lines.
Denmark
Copenhagen-based artisan bakeries specify protein-gum hybrid systems for moisture retention in clean-label pastries. CSRD-aligned Scope 3 emissions disclosure requirements favor regional suppliers with transparent farm-to-ingredient traceability. Danish Technological Institute facilities host concentrated rheology and sensory science expertise.
Protein-Based Fat Replacer Market Competitive Landscape
Capital-heavy dairy processors compete with asset-light ingredient designers for control of protein fat replacer value chains. The supplier base concentrates around three tiers: multinational diversified ingredient houses, dairy cooperative-owned specialists, and regional hydrocolloid blenders. Dominant competitive moves include backward integration into milk protein fractionation and strategic partnerships with precision fermentation startups.
Within the dairy cooperative tier, Fonterra Co-operative Group Limited and Arla Foods Ingredients Group exemplify New Zealand and European-origin sourcing credibility. Among diversified ingredient houses, Cargill Incorporated and Kerry Group occupy positions spanning emulsifier systems and flavor-masked protein platforms. Royal Avebe represents the potato protein specialization archetype, leveraging regional starch industry proximity.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Fonterra Co-operative Group Limited |
| Cargill Incorporated |
| Royal Avebe |
| Arla Foods Ingredients Group |
| Archer Daniels Midland Company |
| Tate & Lyle |
| CP Kelco |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Multi-year volume commitments mandated by German private-label yogurt processors are compressing supplier margins and forcing consolidation toward integrated dairy protein fractionators with captive whey concentrate supply. This procurement centralization privileges scale players while squeezing regional blenders on price realization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates marine protein hydrolysates from whey microparticles and commodity dairy concentrates. Price differentiation tracks certification grade and volume scale, with REACH-compliant clean-label premiums widening against conventional emulsifiers. Cost compression in commodity whey tiers is intensifying because New Zealand dairy commodity pricing transmits directly to formulation economics. Food manufacturers represent the most price-sensitive buyers, while premium gelato producers exhibit lowest sensitivity due to sensory performance requirements.
Supply Chain Analysis
EU Green Deal Scope 3 emissions disclosure requirements are reshaping sourcing toward regional European suppliers with transparent farm-to-ingredient traceability. Manufacturing concentrates in Germany, the Netherlands, and Denmark, with New Zealand anchoring whey protein concentrate feedstock. Raw material dependencies center on milk protein fractionation outputs, algae cultivation biomass, and precision fermentation microbial stocks. Single-source vulnerability runs through New Zealand dairy commodity cycles. Distribution runs through pan-European ingredient houses with centralized tender management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protein-based fat replacer market functions as a stable compounder, with EU Green Deal labeling mandates driving sustained reformulation investment cycles across European food manufacturing.
For Market Incumbents: Anticipate margin compression from whey protein concentrate volatility by securing backward integration into milk protein fractionation or long-term offtake agreements with New Zealand cooperatives. Prioritize CSRD-aligned Scope 3 emissions disclosure capabilities to defend position against regional European challengers. Precision fermentation lipid partnerships represent the critical R&D lever for next-generation sensory matching. For New Entrants and Emerging Players: Direct-to-foodservice digital channels offer the most penetrable route for artisan bakery specialists seeking flexible minimum order quantities outside consolidated procurement rosters. Target Copenhagen and Amsterdam clean-label clusters with protein-gum hybrid systems for moisture retention. Meat analog white space in hybrid sausage juiciness retention remains underaddressed by incumbent platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation startups converging microbial protein production with tailored fat mimetics. The five-to-ten year viability window favors acquisition targets with demonstrated EFSA nutritional claim substantiation dossiers and established clean-label certification. Watch for inflection when front-of-pack Nutri-Score mandates expand beyond France and Germany into additional EU member states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milk Protein Fractionation | Captive whey concentrate supply insulates margin pressure from New Zealand commodity cycles. |
| Precision Fermentation Partnership | Microbial lipid production enables premium sensory matching in ice cream applications. |
| CSRD-Aligned Scope 3 Traceability Investment | Farm-to-ingredient transparency meets EU Green Deal procurement specifications. |
| EFSA Nutritional Claim Dossier Development | Clinical validation accelerates reduced-fat product launch timelines by 18-24 months. |
| Regional European Sourcing Consolidation | Proximity production reduces transport emissions for Dutch and Danish bakery clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dairy processor procurement leads, food technologists at reformulation laboratories, hydrocolloid blenders, and EFSA regulatory affairs specialists with secondary validation. Sources included EU customs trade data, EFSA health claim registers, dairy cooperative production disclosures, and SEC filings from listed ingredient houses. Bottom-up volume modeling and top-down market sizing triangulated across these inputs.
Historical reference periods anchored the projection framework across the analysis window, with segmentation modeling across product type, application, form, and end-user category. CAGRs derived from trend extrapolation adjusted for regulatory cycle timing and procurement centralization patterns. Industry-specific forecast inputs incorporated REACH compliance thresholds and Nutri-Score reformulation investment curves.
The model assumes a particular technology adoption path; alternative pathways for precision fermentation lipids would alter the outlook if microbial production costs compress faster than projected. Forecasts reflect assumptions on EFSA claim substantiation timelines and EU Green Deal labeling expansion schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food and Beverage
Emergency Hangover Product Market
Functional Food and Beverage
North America Functional Beverage Market
Functional Food and Beverage
Protein Water Market
Functional Food and Beverage
Hiking Functional Energy Bars Market
Functional Food and Beverage
Functional Powdered Lipids Market
Functional Food and Beverage
Global Functional Drinks Market
Functional Food and Beverage
Europe Functional Water Market
Functional Food and Beverage
GCC Functional Food Market
Functional Food and Beverage
Asia-Pacific Protein Bar Market
Functional Food and Beverage
North America Protein Bar Market
Functional Food and Beverage
Europe Medical Foods Market
Functional Food and Beverage
Flavored and Functional Water Market
Functional Food and Beverage
Functional Soda Market
Functional Food and Beverage
Asia-Pacific Functional Water Market
Functional Food and Beverage
Probiotic Drink Market
Functional Food and Beverage
Low Fat Smoothies Market