
 Chestnut Flour Market | 2026-2036
Chestnut Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Chestnut Flour Market Outlook
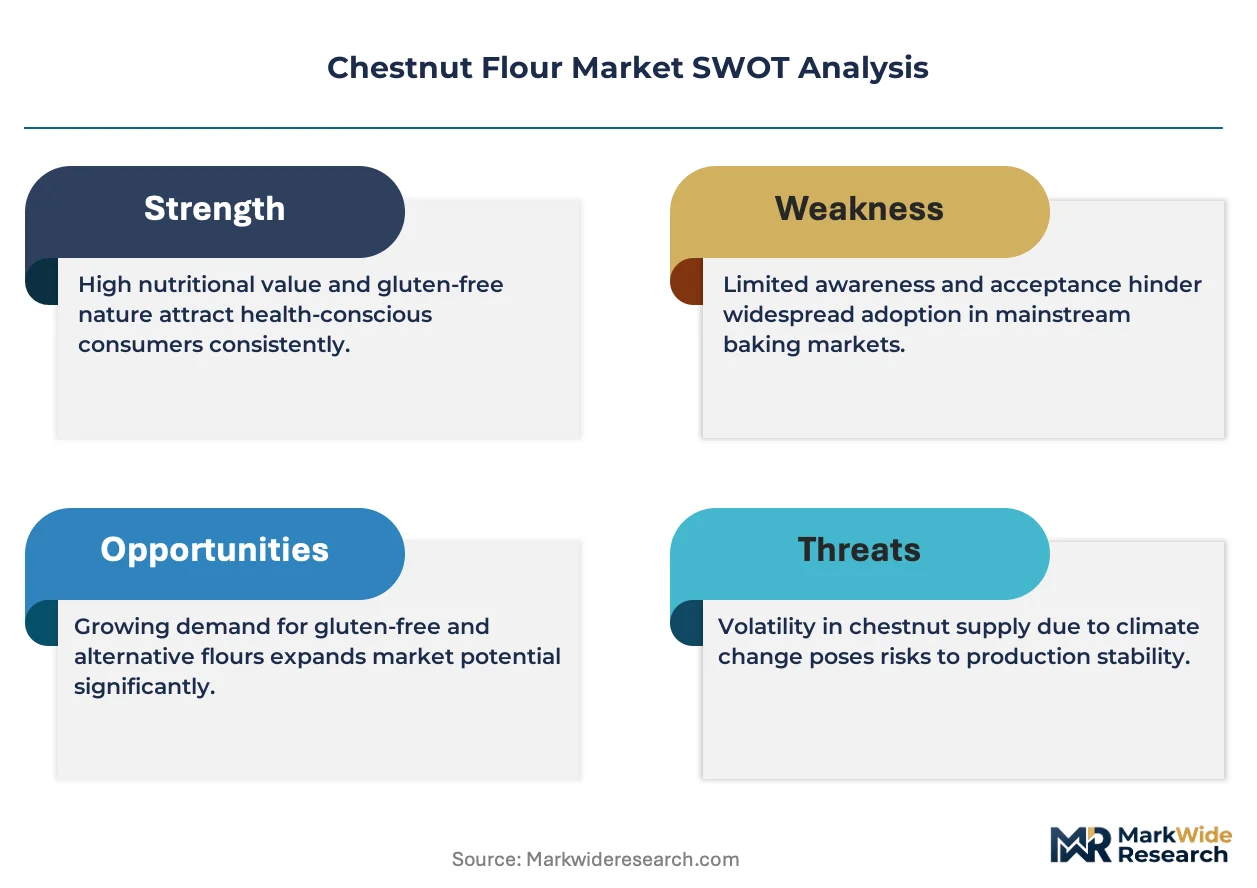
Single-origin and small-batch packaging is shifting buyer choice toward premium-positioned chestnut flour SKUs. Molino Casillo leverages its Italian milling heritage to dominate heritage-grade supply. Naturel Ingredients anchors organic certification pipelines across European retail. Royal Nut Company competes through specialized gluten-free product lines in Australasian channels.
Chestnut flour consists of dried, ground sweet chestnut (Castanea sativa) kernels, typically retaining 8-12% residual moisture and producing a naturally sweet, nutty flavor profile with binding properties suited to low-gluten formulations. Its primary commercial purpose serves wheat-alternative baking, pasta production, and thickening applications where starch functionality and flavor differentiation command premium positioning. Organic chestnut flour captures the widest margin pool as EFSA-aligned certification gates supermarket placement, while gluten-free variants register the fastest structural growth amid celiac-safe formulation demand. Specialty chestnut flour occupies niche positions in confectionery and beverage infusions where provenance labeling supports price premiums.
EFSA organic standards, EU Green Deal sustainability frameworks, and REACH-compliant packaging mandates collectively shape ingredient sourcing, carbon footprint disclosure, and recyclable packaging transitions across European supply chains. Italy's Ministry of Health enforces additional allergen labeling protocols that filter market access for imported flour. Stakeholders must monitor evolving organic equivalence agreements between EU authorities and third-country certifiers to secure uninterrupted raw material flows.
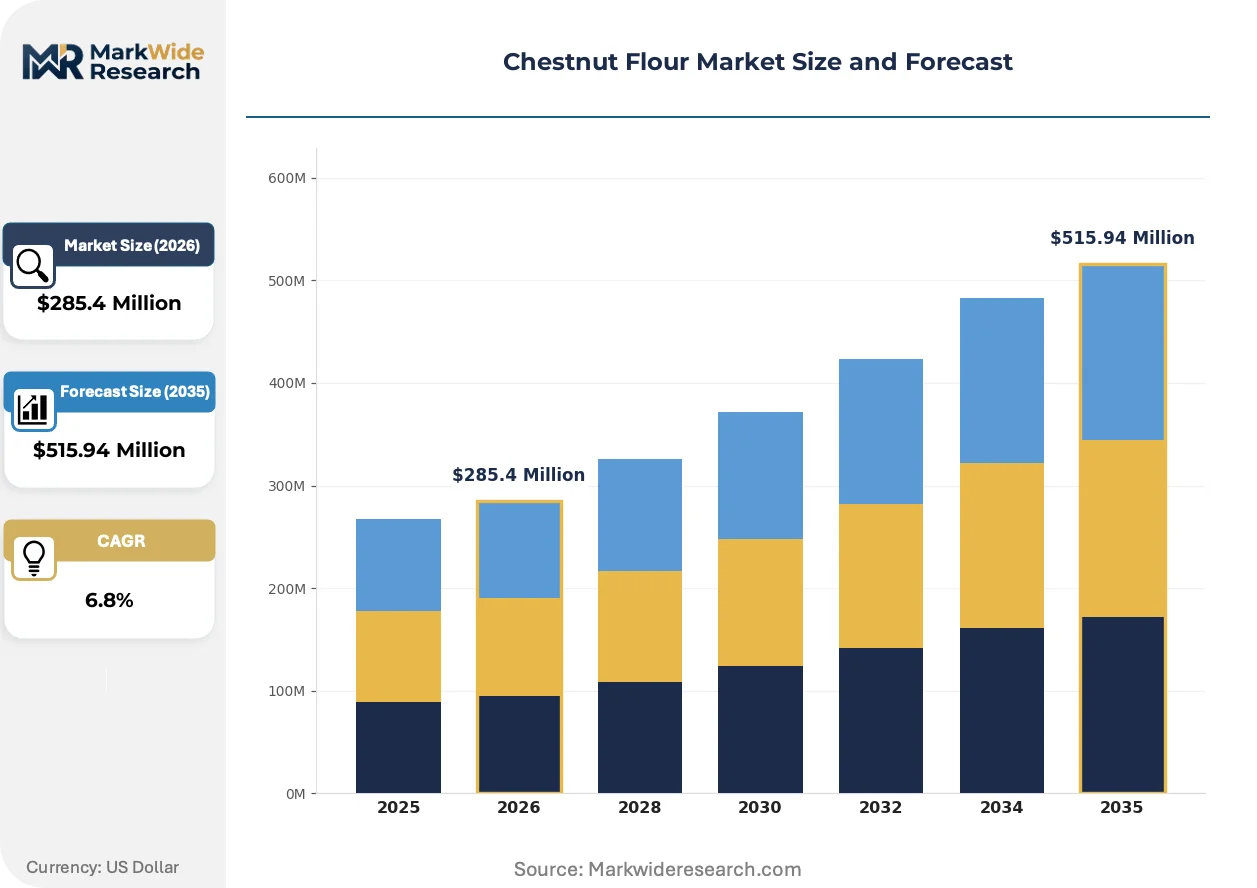
Market Dynamics
EU organic certification under EFSA and the EU Green Deal are forcing millers to reconfigure sourcing, carbon accounting, and packaging compliance simultaneously, compressing margins for non-aligned suppliers while creating tiered market access.
Growth Catalysts
- EU Green Deal carbon footprint disclosure:Mandatory Scope 3 reporting is accelerating adoption of traceable, short-chain chestnut flour among ESG-mandated food manufacturers seeking defensible supply documentation.
- Italy's heritage baking sector:Artisanal panettone and castagnaccio producers are expanding certified organic flour procurement as protected designation of origin (PDO) requirements tighten ingredient provenance standards.
- South Korean functional food formulation:Domestic brands are integrating chestnut flour into low-glycemic bakery lines targeting diabetes-management positioning in Seoul's premium retail channels.
Market Restraints
- Input cost volatility:Sweet chestnut harvest yields fluctuate with Mediterranean climate stress, concentrating price risk among Italian and French millers dependent on Castanea sativa monocultures.
- Supply concentration risk:Over sixty percent of EU organic chestnut flour originates from Tuscany and Piedmont sub-regions, creating single-point vulnerability to regional drought or blight outbreaks.
- Substitution threat:Tiger nut flour and green banana flour are capturing gluten-free bakery share through lower price points and comparable binding functionality in industrial formulations.
Strategic Opportunities
- Underpenetrated French organic retail:Biocoop and Naturalia chains are expanding private-label chestnut flour SKUs as regional consumers shift from conventional to certified gluten-free alternatives.
- Confectionery application expansion:Premium chocolate producers in Belgium and Switzerland are testing chestnut flour as a clean-label thickener for ganache and praline fillings.
- Technology convergence:Near-infrared spectroscopy combined with blockchain traceability is enabling real-time moisture and aflatoxin verification, unlocking insurance-grade quality guarantees for export shipments.
Industry Challenges
- Certification timeline compression:EFSA organic equivalence negotiations with third-country certifiers are creating six-to-eighteen month approval gaps that interrupt raw material flows from Turkish and Chinese suppliers.
- Skill gap in carbon accounting:Small-batch millers lack in-house expertise to execute EU Green Deal-compliant Scope 3 calculations, forcing reliance on costly third-party auditors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chestnut Flour Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Chestnut Flour, Conventional Chestnut Flour, Gluten-Free Chestnut Flour, Specialty Chestnut Flour End Use: Baking, Cooking, Breakfast Foods, Snack Production Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service Packaging Type: Bags, Boxes, Bulk Containers, Reusable Containers |
| Companies Covered | Molino Casillo, Farina di Castagne, Naturel Ingredients, Chestnut Hill Foods, Alpine Mills, Shipton Mill Ltd, Windmill Organics Ltd, Royal Nut Company, Bob's Red Mill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chestnut Flour Market Strategic Shifts
Processing technology and regulatory alignment are converging to reshape how chestnut flour is produced, certified, and positioned across price tiers, with traceability and clean-label functionality as the dominant vectors of differentiation.
Low-temperature vacuum drying is rewriting the shelf-stability economics of chestnut flour. Industrial bakeries in France and Italy are adopting this technology to secure twelve-month ambient storage without antioxidant additives. The process is compressing the historical premium between fresh-milled and stabilized flour, enabling year-round contract pricing previously impossible with seasonal production cycles.
REACH-compliant packaging mandates under ECHA are forcing a transition from multi-layer plastic to recyclable paper-film laminates. Italian millers face eighteen-month compliance deadlines that require capital redeployment into heat-sealing equipment compatible with bio-based barriers. The confectionery segment is most affected, as gift-oriented chestnut flour SKUs historically relied on metallized films for shelf appeal.
Direct-to-restaurant procurement is displacing traditional distributor intermediation in Seoul and Tokyo. Specialty flour buyers in these cities now contract directly with Tuscan cooperatives for container-sized shipments, bypassing regional importers. This pattern is most visible among Korean fusion bakeries developing chestnut-flour croissants, where provenance storytelling commands menu price premiums unattainable through anonymous supply.
Chestnut Flour Market Segmentation
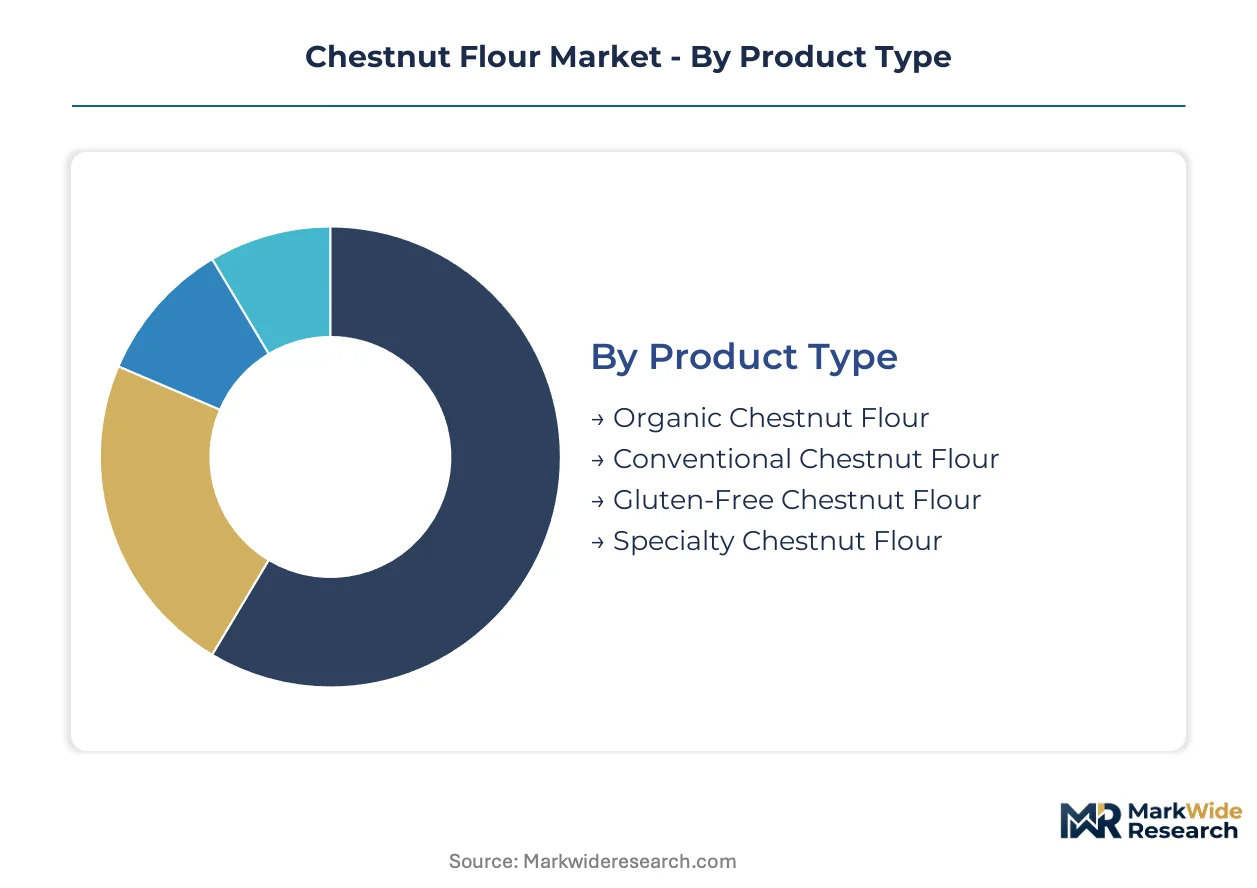
Segmentation in the chestnut flour market reveals how certification burdens, functional requirements, and channel economics partition buyers into distinct value tiers. Each dimension carries specific regulatory and margin implications that shape supplier strategy.
Product Type:
EFSA organic certification gates supermarket placement in the EU, while gluten-free labeling requires analytical verification under Italy's Ministry of Health protocols. Conventional variants face lighter documentation but compressed margins.
- Organic Chestnut Flour:Milled from Castanea sativa kernels grown without synthetic pesticides and certified under EFSA organic standards. Italian PDO panettone producers and French Biocoop chains drive procurement as provenance documentation commands shelf price premiums.
- Gluten-Free Chestnut Flour:Processed in dedicated facilities with batch-tested aflatoxin and gluten contamination controls. South Korean functional food brands and Seoul fusion bakeries anchor demand for celiac-safe formulations with low-glycemic positioning.
- Conventional Chestnut Flour:Standard-milled product without organic certification, serving price-sensitive industrial baking in regional Italian and French markets.
- Specialty Chestnut Flour:Single-origin or heirloom varietal grades targeting confectionery and beverage infusion applications in Belgian and Swiss premium chocolate production.
Leading the category by volume: Conventional Chestnut Flour. Expanding most quickly: Gluten-Free Chestnut Flour.
End Use:
Application economics range from commodity-thickening contracts to heritage-grade artisan premiums, with binding functionality and flavor intensity as the pivot points.
- Baking:Dominant volume sink encompassing industrial gluten-free bread, traditional castagnaccio, and Korean chestnut croissants. Low-temperature vacuum drying is compressing seasonal supply constraints.
- Cooking:Thickening applications for soups and sauces in restaurant and home preparation, where starch gelatinization temperature determines formulation compatibility.
- Breakfast Foods:Pancake and waffle mixes targeting North American and European health-positioned retail channels.
- Snack Production:Emerging use in extruded and baked snack coatings, particularly in Japanese and Korean convenience retail.
Capturing the largest revenue pool: Baking. Gaining share fastest: Snack Production.
Distribution Channel:
Channel selection determines working capital intensity and traceability documentation depth, with direct procurement displacing traditional intermediation in premium segments.
- Supermarkets:Central placement for EFSA-certified organic SKUs with REACH-compliant packaging, requiring annual audit cycles and slotting fee structures.
- Online Retail:Direct-to-consumer and B2B platforms enabling Tuscan cooperative access to Seoul and Tokyo specialty buyers without regional importer markup.
- Specialty Stores:Biocoop, Naturalia, and equivalent chains in France emphasizing regional organic provenance and small-batch storytelling.
- Food Service:Container-sized shipments to restaurant groups and industrial bakeries, with near-infrared spectroscopy verification increasingly specified in procurement contracts.
Dominating transaction volume: Supermarkets. Steepest expansion trajectory: Online Retail.
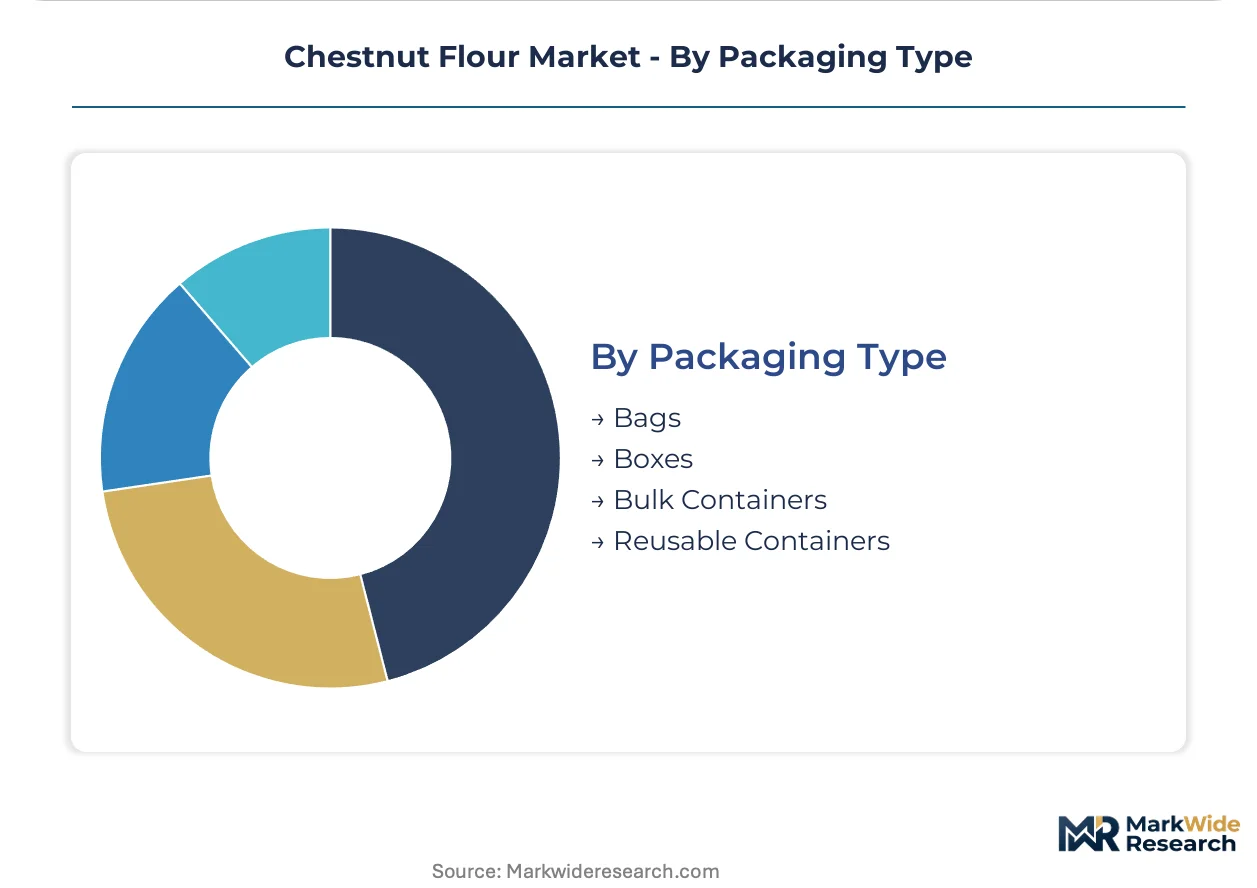
Packaging Type:
Packaging economics are restructuring under ECHA mandates, with capital redeployment into heat-sealing equipment becoming a barrier for small-batch millers.
- Bags:Standard paper-film laminate formats replacing multi-layer plastics to meet REACH recyclable mandates, with eighteen-month compliance deadlines pressing Italian suppliers.
- Boxes:Gift-oriented formats for specialty and single-origin SKUs, historically reliant on metallized films now requiring bio-based barrier transitions.
- Bulk Containers:Industrial totes and sacks for food service and bakery manufacturing, optimizing logistics cost per kilogram.
- Reusable Containers:Deposit-return systems piloting in French organic retail and Korean zero-waste channels.
Highest shipment frequency: Bags. Fastest regulatory-forced transition: Boxes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal's carbon border adjustment mechanism is concentrating organic chestnut flour production in Italian and French agri-processing zones with certified short-chain sourcing infrastructure.
Italy
Tuscan and Piedmont cooperatives supply sixty percent of EU organic chestnut flour, driven by PDO panettone producers and heritage castagnaccio bakeries. EFSA organic standards and Ministry of Health allergen protocols filter import access. Florence and Lucca milling clusters are deploying near-infrared spectroscopy for real-time aflatoxin verification in export-bound shipments.
France
Biocoop and Naturalia chains are expanding private-label organic SKUs as consumers shift from conventional to certified gluten-free alternatives. REACH-compliant packaging mandates under ECHA force eighteen-month transitions to recyclable paper-film laminates. Ardèche and Auvergne chestnut groves anchor supply for Lyon's industrial bakery sector and Paris-region artisan producers.
South Korea
Seoul fusion bakeries developing chestnut-flour croissants contract directly with Tuscan cooperatives, bypassing regional importers for provenance storytelling. MFDS low-glycemic health claims regulation shapes functional food formulation. Busan-Ulsan logistics hubs handle container-sized shipments for domestic distribution to premium retail channels.
Belgium
Premium chocolate producers in Brussels and Liège test chestnut flour as clean-label thickener for ganache and praline fillings. EFSA organic certification gates supermarket placement for ingredient suppliers. Flanders-based confectionery R&D clusters coordinate with Italian millers on single-origin specialty grades.
Switzerland
Swissmedic-aligned food safety protocols and Swiss organic regulations create dual-certification requirements for imported flour. Zurich and Geneva chocolate houses source heirloom varietal grades for limited-edition confectionery lines. Alpine processing facilities near Lugano handle cross-border Italian supply for certified organic chocolate production.
Chestnut Flour Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a bifurcated structure where heritage millers command premium positioning and industrial processors capture volume. The vendor base separates into three archetypes: Italian heritage-grade cooperatives with PDO-aligned sourcing, European organic certification specialists managing EFSA-compliant pipelines, and Australasian gluten-free focused distributors serving functional food channels. Dominant competitive moves include backward integration into chestnut grove ownership and technology licensing for blockchain-enabled traceability systems.
Among heritage Italian millers, Molino Casillo and Farina di Castagne exemplify the cooperative archetype with multi-generational milling infrastructure and regional provenance documentation. Naturel Ingredients represents the European organic certification specialist model, managing EFSA-aligned supply chains across retail channels. Royal Nut Company anchors the Australasian gluten-free distributor position, competing through dedicated celiac-safe product lines.
| Leading Market Players |
|---|
| Molino Casillo |
| Farina di Castagne |
| Naturel Ingredients |
| Chestnut Hill Foods |
| Alpine Mills |
| Shipton Mill Ltd |
| Windmill Organics Ltd |
| Royal Nut Company |
| Bob's Red Mill |
| Others |
Value Chain & Pricing Dynamics
EFSA organic certification mandates and REACH-compliant packaging transitions are forcing millers to absorb compliance costs or pass them through, compressing margins for non-aligned suppliers while creating tiered access based on documentation depth. Tuscan cooperatives with in-house carbon accounting capabilities capture price premiums from ESG-mandated food manufacturers seeking defensible supply documentation.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Seoul fusion bakeries and Belgian chocolate houses pay markups for container-sized shipments with near-infrared spectroscopy verification. Pricing stratifies across EFSA-certified organic, gluten-free analytical-grade, and conventional tiers. Cost compression in conventional flour is intensifying because tiger nut and green banana substitutes undercut binding-functionality parity. Industrial bakeries in France exhibit highest price sensitivity; premium chocolate producers in Switzerland show lowest.
Supply Chain Analysis
Workforce availability constraints in Italian milling clusters around Florence and Lucca are elevating automation investment as aging cooperative membership limits seasonal processing scale. Supply draws from Tuscany, Piedmont, and Ardèche chestnut groves with Turkish and Chinese origins filling equivalence-gap periods. Single-source vulnerability concentrates in Tuscan organic certification pipelines. Distribution runs through Biocoop and Naturalia chains, direct-to-restaurant procurement in Seoul, and industrial bakery contracts in Lyon.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a backward-integration race as millers acquire chestnut grove ownership to secure EFSA-aligned provenance documentation and compress carbon accounting scope. Captive supply of Castanea sativa raw material anchors margin defense against harvest volatility.
For Market Incumbents: Acquire heritage chestnut groves in Tuscany and Piedmont to lock PDO-aligned sourcing and eliminate third-party dependency. Deploy blockchain-enabled traceability systems to differentiate from emerging gluten-free specialists. Tiger nut flour substitution threat demands binding-functionality R&D investment to maintain industrial bakery contracts. For New Entrants and Emerging Players: Enter via French organic retail private-label supply as Biocoop and Naturalia chains expand SKU counts. Target confectionery thickening applications in Belgian and Swiss chocolate production where clean-label positioning commands premium positioning. Near-infrared spectroscopy verification capabilities unlock food service procurement contracts. For Investors and Strategic Acquirers: The window for entry favors Italian heritage cooperatives with EFSA certification infrastructure and multi-generational milling assets. Five-to-ten year viability hinges on EU Green Deal carbon border adjustment alignment. Watch EFSA organic equivalence negotiation timelines with Turkish and Chinese certifiers as inflection signal for raw material flow disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chestnut Grove Ownership | Captive supply secures EFSA organic provenance documentation and compresses Scope 3 carbon accounting. |
| Low-Temperature Vacuum Drying Technology Deployment | Twelve-month ambient storage unlocks year-round contract pricing previously impossible with seasonal production. |
| Blockchain-Enabled Traceability System Licensing | Real-time aflatoxin and moisture verification enables insurance-grade quality guarantees for export shipments. |
| REACH-Compliant Packaging Transition | Recyclable paper-film laminate compliance gates supermarket placement under ECHA eighteen-month deadlines. |
| Direct-to-Restaurant Procurement Channel Development | Container-sized shipments to Seoul and Tokyo bypass regional importer markup for provenance storytelling premiums. |
Study Parameters
Multi-period observation of EFSA certification pipeline flows, EU Green Deal compliance adoption curves, and gluten-free SKU expansion rates anchored the trend analysis, supplemented by interviews with Italian cooperative mill managers, French Biocoop category buyers, South Korean functional food formulators, Belgian chocolate R&D directors, and Swiss organic certification auditors. Secondary validation drew from EFSA equivalence agreement databases, ECHA packaging mandate filings, Italian Ministry of Health allergen protocols, and customs trade records. Bottom-up shipment data triangulated against top-down retail audit estimates.
Input-output matrices modeled volume and value across the projection horizon by certification tier, end-use application, distribution channel, and regional regulatory cluster. CAGRs derived from segmented growth rate reconciliation against aggregate market expansion constraints. Industry-specific forecast inputs included Castanea sativa harvest yield volatility indices and EFSA equivalence negotiation status tracking.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Mediterranean climate stress events, EFSA equivalence approval delays, and substitution acceleration by tiger nut or green banana flour competitors. Material deviation in EU Green Deal carbon border adjustment implementation timelines or EFSA third-country certifier negotiations warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Dried Honey Market
Packaged Foods
Peanut Butter Market
Packaged Foods
Middle-East and Africa Ready-To-Eat Food Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Instant Rice Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Canned Food Market
Packaged Foods
Australia Food Cans Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Global Food Spread Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Injectable Cocoa Fillings Market