
 Asia-Pacific Sweet Biscuits Market | 2026-2036
Asia-Pacific Sweet Biscuits Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sweet Biscuits Market Outlook
Subscription-based replenishment programs for household biscuit packs is consolidating recurring revenue streams across major producers. Parle Products leverages its rural distribution depth to sustain volume leadership in India's mass-market segments. Meiji Co. anchors premium chocolate biscuit positioning through controlled retail presence in Japan and selective Southeast Asian expansion. Mondelez International competes on global brand equity while navigating localized flavor adaptations.
Sweet biscuits comprise wheat-flour-based baked goods containing added sugars, fats, and flavoring agents, typically achieving moisture content below five percent for shelf stability and crisp texture; manufacturers employ rotary molding or wire-cut processes before baking in tunnel ovens at 180–220°C to produce ready-to-eat snack items. Chocolate biscuits dominate value contribution due to premium positioning and gifting occasions across the region. Cream-filled biscuits capture growth in child-oriented and impulse-purchase channels where single-serve pricing drives trial. Wafer biscuits occupy a mature volume tier with thin margins concentrated in Southeast Asian price-sensitive markets.
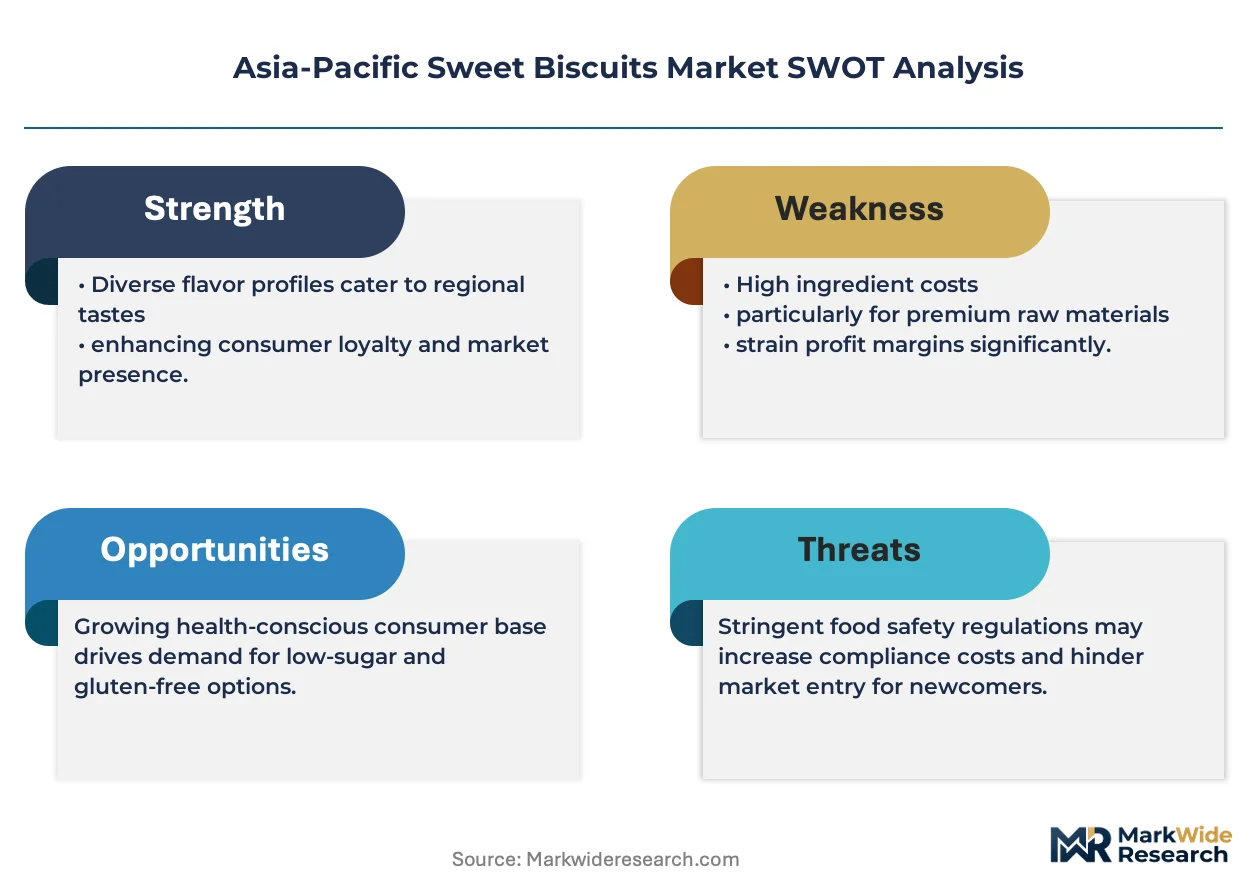
FSSAI in India enforces labeling and fortification standards that push reformulation investments, while Japan's Consumer Affairs Agency monitors calorie and allergen declarations affecting import eligibility. Indonesia's BPOM registration requirements for processed foods extend market access timelines for new entrants. Stakeholders must weigh regulatory compliance costs against localization depth when prioritizing country entry sequences.
Market Dynamics
FSSAI fortification mandates in India are forcing wholesale reformulation of mass-market biscuit portfolios, while Indonesia's BPOM registration timelines extend market access barriers for new entrants. These regulatory pressures compound with raw material cost volatility to reshape competitive economics across the region.
Growth Catalysts
- Urban snack consumption:Tier-2 Indian cities and Indonesia's Java corridor concentrate rising disposable incomes and modern retail penetration, expanding addressable households for packaged biscuits.
- Fortification compliance:FSSAI micronutrient mandates create product differentiation opportunities for early reformulators while phasing out non-compliant regional competitors.
- Chocolate biscuit premiumization:Gifting occasions and impulse channels in Southeast Asian metro areas elevate value-per-unit through portion-controlled and premium-positioned SKUs.
Market Restraints
- Wheat and palm oil input volatility:Price swings in these core commodities compress margin predictability for volume-tier producers dependent on thin pricing spreads.
- Wafer category margin erosion:Southeast Asian price-sensitive markets lock wafer biscuits into commoditized competition with limited brand loyalty or premium extraction potential.
- Single-serve packaging cost inflation:Film and laminate material costs rise faster than retail price acceptance in impulse channels, squeezing unit economics.
Strategic Opportunities
- Subscription replenishment models:E-commerce platforms and direct-to-household programs in Indian urban centers capture recurring revenue and reduce trade promotion dependency.
- Clean-label reformulation:Japan's Consumer Affairs Agency allergen disclosure standards create export-ready positioning for manufacturers achieving early compliance.
- Cream-filled segment expansion:Child-oriented channels and school-adjacent retail in Indonesia offer underexploited distribution depth beyond traditional grocery.
Industry Challenges
- Reformulation R&D timelines:FSSAI nutrient retention requirements demand extended stability testing that delays product launches and ties up technical personnel.
- Legacy distributor integration:Modern trade expansion in India requires reconciling traditional wholesale credit systems with organized retail payment terms and data-sharing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sweet Biscuits Market |
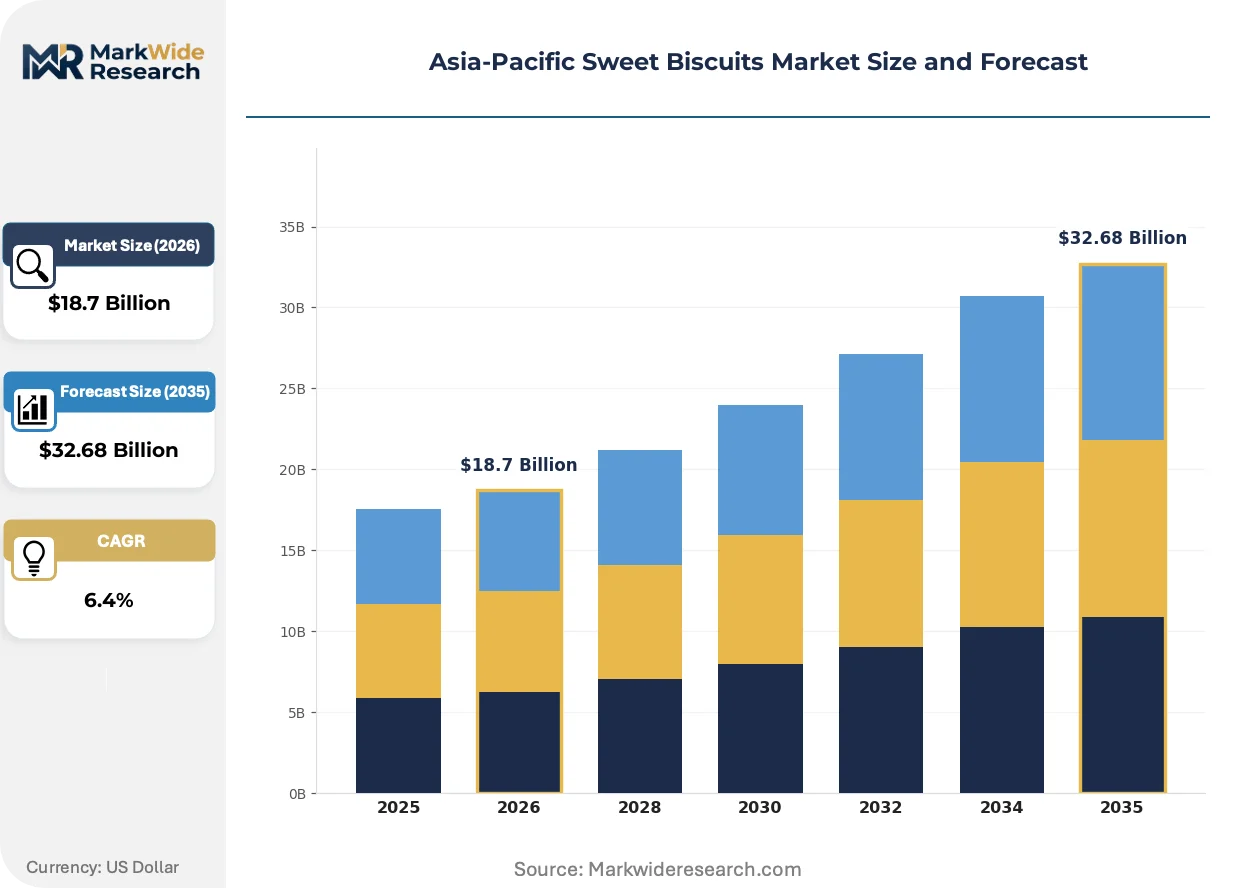
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Biscuits, Cream-Filled Biscuits, Digestive Biscuits, Wafer Biscuits Distribution Channel: Supermarkets, Hypermarkets, Online Retail, Convenience Stores Customer Type: Children, Adults, Health-Conscious Consumers, Snack Enthusiasts Packaging Type: Box, Resealable Bags, Pouches, Plastic Containers |
| Companies Covered | Parle Products, Meiji Co., Mondelez International, Orion Corp, Lotte Co., ITC Limited, Fujiya Co., PT Mayora Indah, Britannia Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sweet Biscuits Market Strategic Shifts
Reformulation science and channel digitization are converging to alter how biscuits reach consumers and what nutritional claims manufacturers can credibly support. These shifts favor capitalized players with in-house technical capabilities and direct consumer relationships.
Enzyme-based fat reduction technology is overtaking traditional shortening systems in premium biscuit production. Japanese and South Korean manufacturers deploy these processes to achieve calorie reduction targets without texture degradation. The structural consequence is compressing the premium-mass boundary as mid-tier producers license comparable enzymatic solutions.
FSSAI's 2024 micronutrient fortification scope expansion mandates iron, folic acid, and vitamin B12 inclusion in all wheat-based packaged biscuits sold in India. Industrial consequence includes mandatory reformulation investments and third-party testing certification for existing product lines. Mass-market producers serving rural distribution networks face the steepest compliance cost absorption challenges.
Quick-commerce platforms are fragmenting traditional wholesale-distributor relationships in Indian metropolitan areas. Dark-store networks and 10-minute delivery promises displace kirana-store bulk purchasing for urban households with storage constraints. This pattern concentrates most visibly in Mumbai, Bangalore, and Delhi NCR where platform subsidies currently mask true logistics costs.
Asia-Pacific Sweet Biscuits Market Segmentation
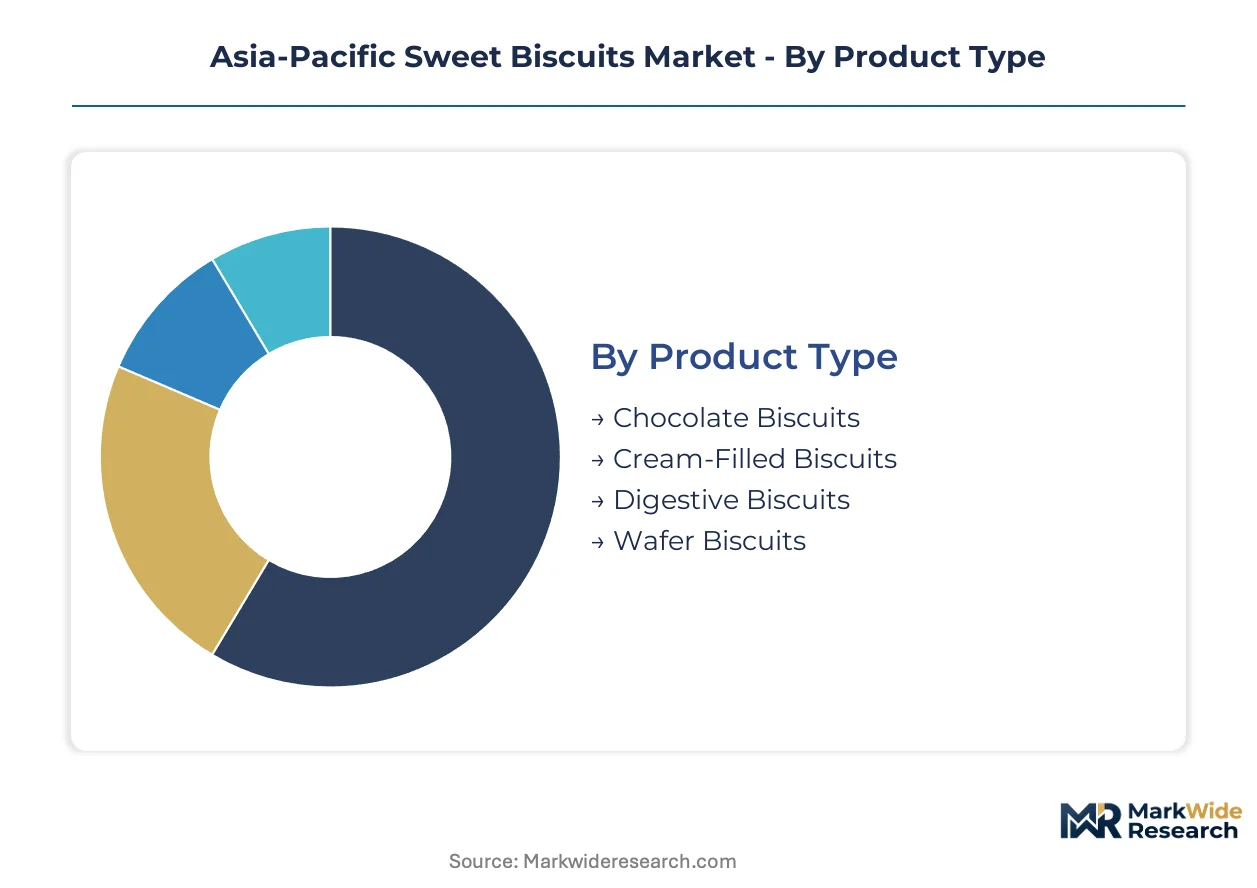
Sweet biscuit manufacturers calibrate portfolio investments across four distinct segmentation axes. Each dimension carries unique regulatory exposure, margin profiles, and channel access requirements that determine competitive positioning in Asia-Pacific markets.
Product Type:
FSSAI fortification mandates apply differentially across product categories, with wheat-based formulations facing the heaviest compliance burden while chocolate-coated variants trigger separate allergen labeling protocols under Japan's Consumer Affairs Agency.
- Chocolate Biscuits:Cocoa-butter-based coatings with premium positioning command gifting-channel margins in Southeast Asian metros. Demand concentrates in Indonesia's Java corridor where impulse purchases drive single-serve velocity.
- Cream-Filled Biscuits:Sandwich constructions with fat-based fillings achieve higher per-unit pricing in child-oriented channels. India's tier-2 cities show concentrated growth as modern retail expands beyond Mumbai and Delhi NCR.
- Digestive Biscuits:Whole-wheat formulations with fiber claims attract health-conscious positioning under FSSAI's expanded micronutrient scope.
- Wafer Biscuits:Layered thin-sheet constructions dominate Southeast Asian price-sensitive markets with thin margin structures.
Wafer biscuits sit at the top of the volume ranking, with cream-filled biscuits climbing the fastest.
Distribution Channel:
Channel selection determines working capital intensity and data transparency, with modern trade formats demanding organized payment terms while traditional wholesale maintains credit-based relationships.
- Supermarkets:Self-service formats with extended SKU assortments drive premium biscuit trial through visual merchandising. Shelf-space negotiations in India's organized retail sector increasingly require scan-data sharing.
- Hypermarkets:Large-format destinations with bulk-pack positioning capture household replenishment trips. Indonesia's urban centers concentrate hypermarket expansion as foreign operators deepen Java penetration.
- Online Retail:Quick-commerce platforms with dark-store networks fragment traditional distributor relationships in Indian metros.
- Convenience Stores:Small-footprint formats with immediate consumption focus dominate single-serve biscuit velocity.
Convenience stores maintain the highest transaction frequency, though online retail is expanding most quickly.
Customer Type:
Demographic targeting shapes formulation priorities, with children driving cream-filled adoption while health-conscious segments pull toward digestive and reduced-sugar variants.
- Children:Sugar-forward formulations with licensed character packaging dominate school-adjacent retail in Indonesia. Parental purchase decisions increasingly weigh FSSAI fortification claims as nutritional signaling.
- Adults:Occasion-based consumption spans workplace snacking and tea-time rituals across Indian urban households.
- Health-Conscious Consumers:Fiber and protein claims attract premium pricing in Japan's aging demographic segments.
- Snack Enthusiasts:Flavor novelty seekers drive limited-edition launches and cross-category trial in Southeast Asian metros.
Adults represent the largest addressable base, with health-conscious consumers gaining share fastest.
Packaging Type:
Material selection directly impacts shelf-life engineering and logistics economics, with film laminate costs rising faster than retail price acceptance in impulse channels.
- Box:Rigid paperboard constructions with gift-appropriate aesthetics dominate premium chocolate biscuit occasions. Japanese retail channels favor box formats for seasonal gifting with strict dimensional standards for automated shelving.
- Resealable Bags:Zip-lock film constructions with moisture barriers support household replenishment and portion control. Indian urban households with storage constraints favor smaller resealable formats over bulk containers.
- Pouches:Flexible film with heat-sealed closures achieves lowest per-unit packaging cost for mass-market wafers.
- Plastic Containers:Rigid PET or PP constructions with threaded lids command durability premiums for transport and reuse.
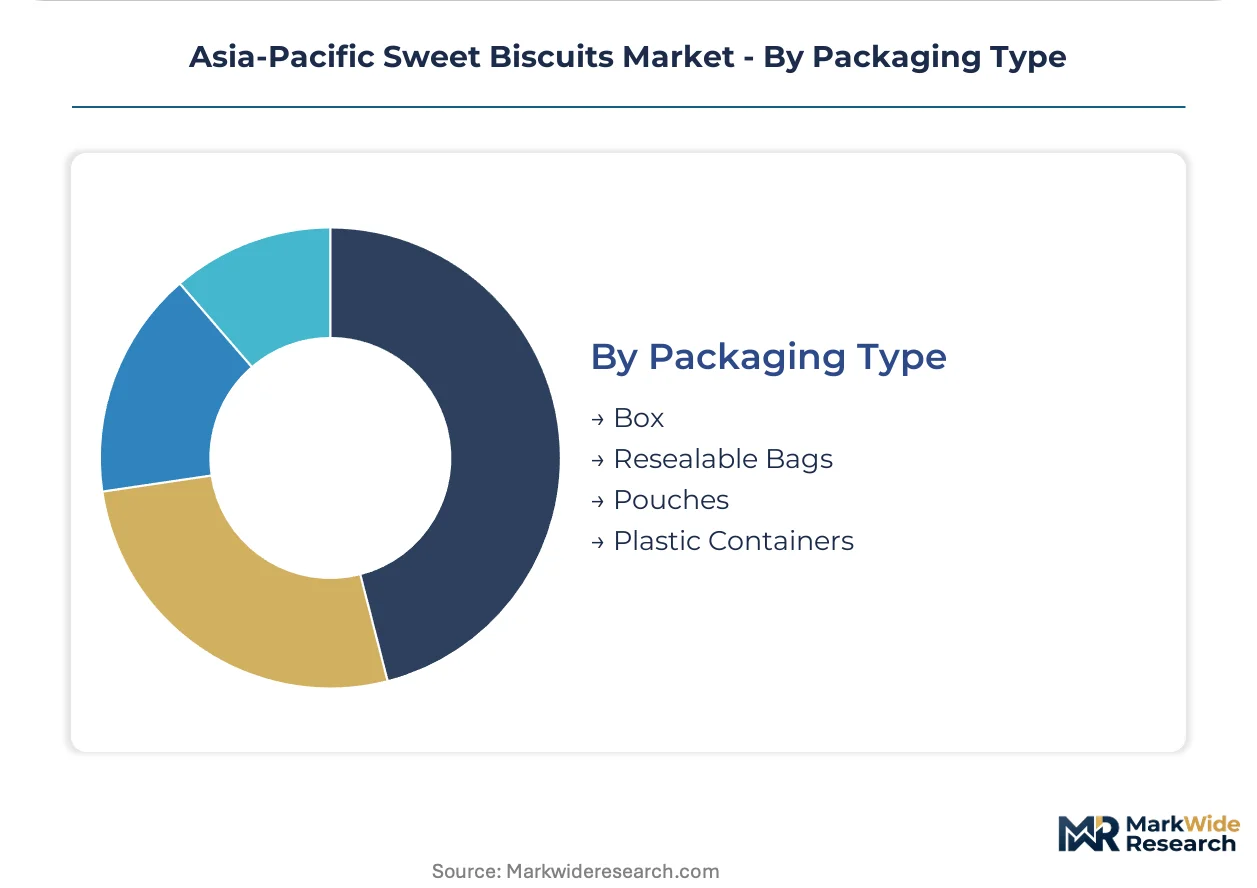
Pouches lead in shipment volume, with resealable bags showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's FSSAI fortification mandates are accelerating product reformulation faster than Indonesia's BPOM registration timelines are extending market access for new entrants. This regulatory divergence creates contrasting competitive dynamics across the region's two largest volume markets.
India
Tier-2 cities including Pune, Ahmedabad, and Kochi concentrate rising disposable incomes and modern retail penetration. FSSAI's 2024 micronutrient scope expansion mandates iron, folic acid, and vitamin B12 inclusion in all wheat-based packaged biscuits. Parle Products leverages its rural distribution depth across Maharashtra and Gujarat to sustain volume leadership while absorbing compliance costs.
Indonesia
Java corridor urban centers Jakarta, Surabaya, and Bandung drive impulse-purchase velocity for single-serve chocolate biscuits. BPOM registration requirements for processed foods extend market access timelines by 12-18 months for new entrants. PT Mayora Indah anchors production capacity in Bekasi and Cikarang industrial zones to serve domestic and export demand.
Japan
Aging demographic segments in Tokyo, Osaka, and Nagoya pull toward reduced-sugar and fiber-forward digestive biscuit variants. The Consumer Affairs Agency monitors calorie and allergen declarations affecting import eligibility for regional exporters. Meiji Co. controls retail presence in Kanto and Kansai regions through selective convenience store partnerships.
South Korea
Seoul Capital Area snack enthusiasts drive flavor novelty and limited-edition launches through quick-commerce platforms. MFDS allergen disclosure standards create export-ready positioning for manufacturers achieving early compliance. Orion Corp concentrates premium chocolate biscuit production in Gyeonggi-do facilities serving domestic and Southeast Asian markets.
China
Yangtze River Delta metropolitan clusters Shanghai, Hangzhou, and Nanjing concentrate gifting-channel demand for premium box-format biscuits. SAMR food labeling regulations and GB standards enforcement shape import eligibility for regional brands. Lotte Co. maintains selective retail presence in eastern coastal cities despite broader market access constraints.
Asia-Pacific Sweet Biscuits Market Competitive Environment
Top-tier vendors anchor premium chocolate and cream-filled segments, while mid-tier regional specialists compete on localized flavor adaptations and rural distribution density. The market structure fragments across multinational CPG conglomerates with global brand equity, diversified Asian food conglomerates with integrated supply chains, and single-category specialists with deep channel relationships. Two dominant competitive moves are subscription-based replenishment program launches and FSSAI-compliant reformulation investments that phase out non-compliant regional competitors.
Within the multinational conglomerate tier, Mondelez International and Lotte Co. represent archetypes of global brand leverage competing against localized portfolio depth. Among India-based diversified food groups, ITC Limited and Britannia Industries exemplify rural distribution scale confronting modern trade transition costs. Parle Products occupies a distinct position as a family-owned mass-market specialist with unmatched kirana-store penetration.
| Leading Market Players |
|---|
| Parle Products |
| Meiji Co. |
| Mondelez International |
| Orion Corp |
| Lotte Co. |
| ITC Limited |
| Fujiya Co. |
| PT Mayora Indah |
| Britannia Industries |
| Others |
Value Chain & Pricing Dynamics
Wheat futures and palm oil benchmarks on the Bursa Malaysia Derivatives Exchange cascade through Asia-Pacific biscuit manufacturing into three distinct pricing tiers, with commodity volatility compressing margins for mass-market producers while premium chocolate segments absorb cost pass-through more readily.
Pricing Analysis
Capacity additions in Indonesia's Bekasi and Cikarang industrial zones are reshaping price floors for wafer and cream-filled categories. Three-tier pricing structure across premium, standard, and economy levels separates gifting-channel chocolate biscuits from household replenishment packs and single-serve impulse items. Price differentiation hinges on fortification certification status under FSSAI mandates and brand equity in modern trade channels. Cost compression in economy-tier wafers is intensifying because film laminate input costs outpace retail price acceptance in Southeast Asian convenience stores, making rural Indian distributors the most price-sensitive buyer segment while Japanese metro consumers show least elasticity.
Supply Chain Analysis
Workforce availability in Maharashtra and Gujarat biscuit corridors underpins Parle Products' rural distribution density, while technical talent concentration in Japan's Kanto region sustains Meiji Co.'s enzymatic fat-reduction capabilities. Manufacturing gravity centers on India, Indonesia, and Japan, with wheat flour and cocoa butter supply anchored in Australian grain exports and West African bean sourcing. Single-source vulnerability in palm oil inputs from Malaysian and Indonesian estates exposes margin predictability to El Niño disruption. Distribution runs through layered wholesale-credit systems in Indian tier-2 cities and quick-commerce dark stores in Seoul and Mumbai metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI compliance cost differentials between India's mass-market producers and Indonesia's export-oriented manufacturers create geographic-arbitrage conditions for capital deployment, with regulatory timing gaps offering 12-18 month competitive windows.
For Market Incumbents: Anchor fortification-compliant reformulation as a competitive moat against regional challengers lacking technical R&D scale. Absorb FSSAI testing certification costs to accelerate product launches while smaller competitors face extended stability timelines. Prioritize backward integration into wheat flour milling in Maharashtra and Gujarat to buffer commodity volatility. For New Entrants and Emerging Players: Quick-commerce platform partnerships offer the lowest-friction route to bypass entrenched wholesale-distributor relationships in Indian metropolitan areas. Target Indonesia's school-adjacent retail channels for cream-filled biscuit penetration where BPOM registration barriers have already filtered out non-compliant regional brands. Deploy subscription-based household replenishment models to capture recurring revenue without kirana-store credit system complexity. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Indian producers possessing FSSAI-compliant portfolios and underexploited modern trade relationships. Five-to-ten year viability favors manufacturers with in-house enzymatic processing capabilities transferable across product lines. Watch quick-commerce subsidy withdrawal in Mumbai and Bangalore as the inflection signal for true logistics cost exposure and margin normalization.| Strategic Initiative | Industry Significance |
|---|---|
| FSSAI-Compliant Reformulation | Mandatory micronutrient inclusion phases out non-compliant regional competitors across Indian mass-market segments. |
| Quick-Commerce Platform Integration | Dark-store networks in Mumbai and Delhi NCR displace traditional kirana-store bulk purchasing for urban households. |
| Enzymatic Fat-Reduction Licensing | Japanese and South Korean process technology transfers compress premium-mass boundary for mid-tier producers. |
| Subscription Replenishment Launch | Direct-to-household programs in Indian tier-2 cities reduce trade promotion dependency and capture recurring revenue. |
| Indonesia School-Channel Expansion | Child-oriented retail adjacent to educational institutions offers underexploited distribution depth beyond traditional grocery. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with brand managers at Parle Products and Meiji Co., category buyers at Indian organized retail chains, supply planners at Indonesian manufacturers, and channel sales heads across Southeast Asian distributors with secondary validation from FSSAI fortification notifications, BPOM registration databases, Bursa Malaysia palm oil futures data, and Nielsen retail audit coverage of Indian biscuit velocity.
Segment-weighting approaches applied product-type, distribution-channel, and customer-type dimensions across the modeling period, with chocolate biscuit premiumization and wafer commoditization trends informing differential growth assumptions. CAGRs derived from bottom-up SKU-level volume builds reconciled against top-down category spend projections, incorporating regulatory compliance cost trajectories and quick-commerce penetration curves as industry-specific forecast inputs.
The model assumes a particular technology adoption path for enzyme-based fat reduction; alternative pathways for clean-label reformulation would alter the outlook. Forecasts reflect assumptions about FSSAI enforcement consistency and BPOM registration timeline stability. Material deviation in wheat-palm oil price correlation or quick-commerce subsidy withdrawal velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Convenience Food Market
Packaged Foods
Man-Made Sausage Casing Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Europe Ready-To-Eat Food Market
Packaged Foods
Instant Noodles Market
Packaged Foods
North America Pasta Market
Packaged Foods
Tortilla Market
Packaged Foods
Instant Cereals Market
Packaged Foods
North America Ready-To-Eat Food Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Instant Rice Market
Packaged Foods
Packaged Corn on the Cob Market
Packaged Foods
Jams and Spreads Market
Packaged Foods
Middle-East and Africa Ready-To-Eat Food Market