
 Reduced Fat Meat Market | 2026-2036
Reduced Fat Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Reduced Fat Meat Market Intelligence
Buyer concentration in the food service channel is broadening as regional restaurant chains and institutional caterers enter the reduced-fat meat category alongside established national operators. Tyson Foods leverages its integrated poultry supply chain to secure consistent volume for lower-fat breast-meat formulations. Hormel Foods anchors its position through branded retail lines that emphasize precise fat-content claims on packaging. JBS competes with beef-focused trimming technologies that deliver standardized lean-to-fat ratios for processor clients.
Reduced fat meat denotes animal protein products where intrinsic fat content has been lowered through selective raw-material sourcing, mechanical separation, or controlled processing to achieve specified compositional targets, typically delivering less than ten percent fat by weight in finished retail form. Its primary commercial purpose is to serve health-oriented consumers and regulated institutional nutrition programs without fully displacing conventional meat from the plate. Turkey and chicken dominate product-type volume due to inherently leaner muscle composition and lower reformulation costs relative to beef or pork. Modified atmosphere packaging extends shelf life sufficiently to support the wider distribution networks that reduced-fat lines now require, while vacuum-packed formats occupy the premium tier where fat-content precision commands higher unit margins.
The FDA governs nutrition-fact panel accuracy and health-claim substantiation for reduced-fat meat sold in the United States, while the USDA oversees slaughter and processing standards that directly affect achievable fat levels. In Europe, EFSA evaluates nutrient-profiling systems that member states use to restrict or promote reduced-fat product placement on retail shelves. Stakeholders must monitor whether pending front-of-pack regulations in additional jurisdictions will harmonize around fat-specific thresholds or fragment into incompatible national schemes.
Market Dynamics
The FDA's updated nutrition labeling requirements and the EU's Nutri-Score front-of-pack system are forcing processors to reformulate products and recalibrate communication strategies around fat content, reshaping competitive positioning across retail and food service channels.
Growth Catalysts
- Front-of-Pack Mandates:The EU's Nutri-Score system incentivizes processors to achieve favorable fat-content ratings, driving investment in trimming technologies and lean-muscle sourcing protocols across Germany, France, and Spain.
- Food Service Health Menus:Regional restaurant chains and institutional caterers in the United States are expanding reduced-fat protein options to capture health-conscious diners and comply with school nutrition standards.
- Mechanical Separation Advances:Precision blade systems and centrifugal fat-removal equipment are lowering reformulation costs for beef and pork processors, narrowing the cost gap with inherently leaner poultry.
Market Restraints
- Feed Cost Volatility:Corn and soybean price swings directly compress margins for lean-meat production, as achieving target fat ratios requires longer feeding cycles and premium feed formulations.
- Processing Concentration:A limited pool of USDA-certified facilities capable of precise fat-content certification creates bottlenecks for mid-size processors seeking to enter reduced-fat retail lines.
- Sensory Trade-Offs:Consumer acceptance of reduced-fat beef and pork remains constrained by moisture-loss and texture degradation that mechanical trimming introduces compared to conventional cuts.
Strategic Opportunities
- Private-Label Expansion:German retail chains have demonstrated that reduced-fat fresh meat can anchor store-brand protein portfolios, creating a replicable model for operators in Poland and the Netherlands.
- Modified Atmosphere Packaging:MAP technology convergence with vacuum-sealed formats is extending shelf life sufficiently to support e-commerce distribution of precision-fat products.
- Institutional Nutrition Programs:USDA school lunch guidelines and EU public procurement standards are mandating lean-protein thresholds, creating contracted volume pipelines for certified suppliers.
Industry Challenges
- Cross-Functional Talent Scarcity:The intersection of meat science, regulatory compliance, and packaging engineering requires hybrid expertise that existing training pipelines rarely produce.
- Certification Timeline Compression:FDA health-claim substantiation and USDA process verification create 12-to-18-month approval windows that delay product launches and tie up working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reduced Fat Meat Market |
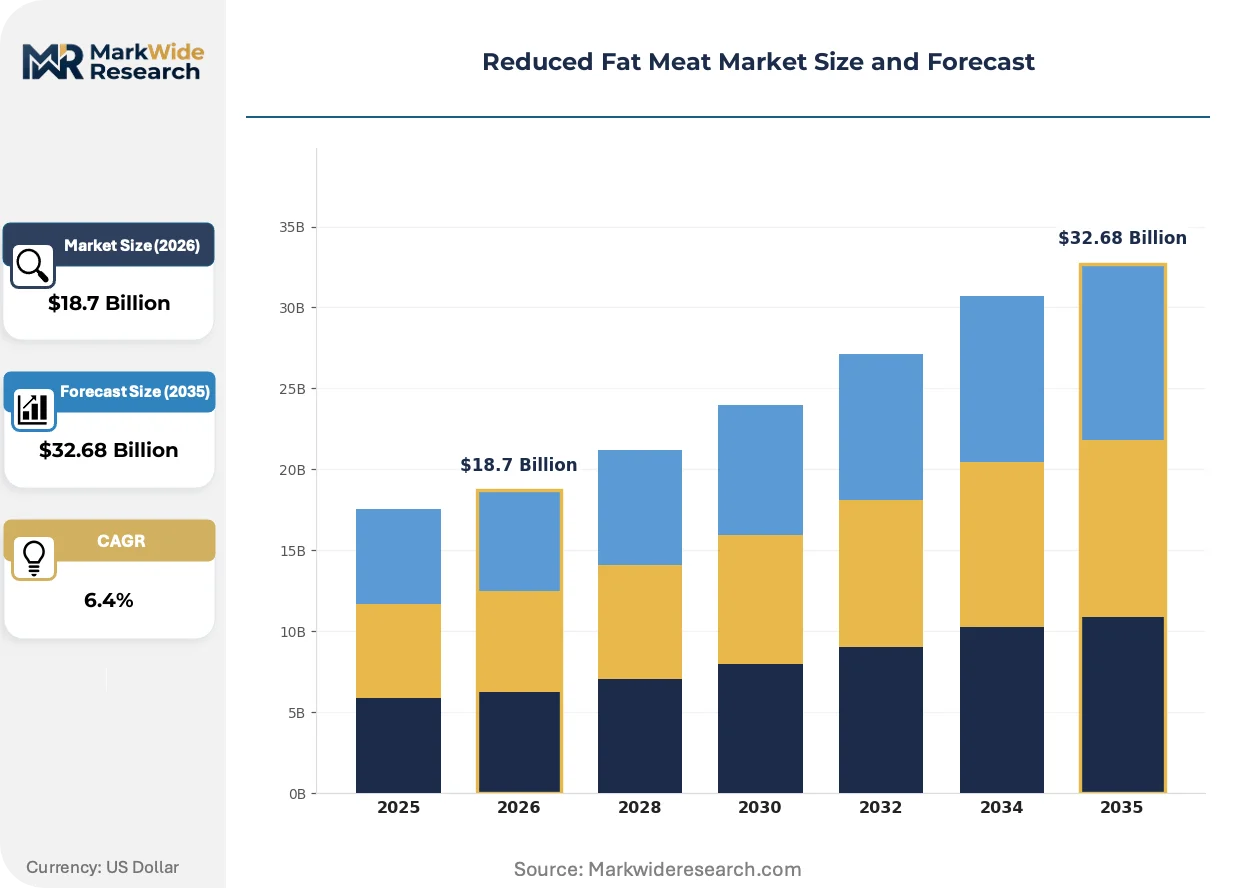
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Turkey, Chicken, Beef, Pork, Lamb Processing Method: Grilling, Smoking, Roasting, Steaming, Baking Packaging Type: Vacuum Packed, Modified Atmosphere, Canned, Tray Packed, Skin Packed End User: Supermarkets, Food Service, Convenience Stores, Specialty Butchers |
| Companies Covered | Tyson Foods, Hormel Foods, Beyond Meat Inc., Quorn Foods, Cargill, Impossible Foods, JBS, Gardein Protein International, Maple Leaf Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reduced Fat Meat Market Strategic Shifts & Innovations
Reformulation technologies and packaging systems are converging to solve the shelf-life and sensory-quality constraints that historically limited reduced-fat meat distribution beyond regional cold chains.
Precision blade trimming systems integrated with real-time compositional analysis are modularizing production lines across mid-cap beef and pork processors. Food service distributors with centralized commissary operations are adopting these configurations fastest, enabling standardized lean-to-fat ratios across multi-state delivery networks. This modularity is compressing the minimum efficient scale for reduced-fat product entry, fragmenting what was once concentrated national supply.
EFSA's evaluation of nutrient-profiling systems is reshaping how member states restrict or promote reduced-fat placement on retail shelves. The industrial consequence is a patchwork of national implementation timelines that forces pan-European processors to maintain multiple label variants and formulation specifications. Germany's early Nutri-Score adoption has made it the testbed for fat-specific threshold calibration, with processors there adjusting faster than counterparts in Italy or Eastern Europe.
Health-conscious dining is rotating procurement authority from commodity buyers toward nutrition-certified sourcing managers within regional restaurant chains. These managers are unbundling after-sales service expectations, demanding supplier-provided menu-nutrition data and staff training rather than traditional volume rebates. This shift is most visible in the United States, where fast-casual chains are building direct relationships with processors capable of certifying precise fat-content claims for digital menu transparency.
Reduced Fat Meat Market Segmentation
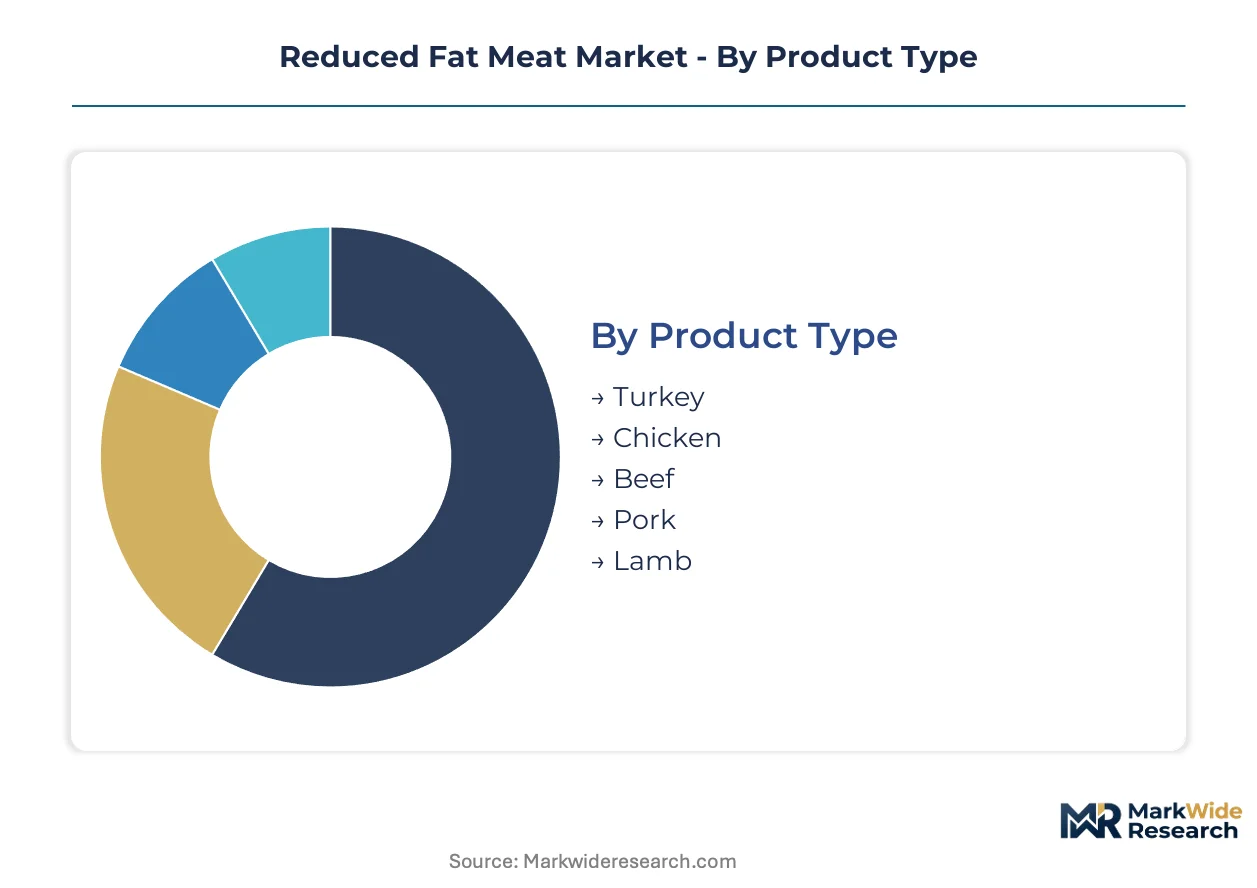
Segmentation in reduced fat meat reveals how processors balance inherent leanness against reformulation costs across species, while packaging and channel choices determine margin capture and geographic reach. Understanding these divides clarifies where technology investments yield competitive advantage versus commodity positioning.
Product Type:
Turkey and chicken occupy standalone reduced-fat applications where minimal processing preserves natural specifications, while beef and pork require embedded mechanical systems to achieve comparable fat targets.
- Turkey:Naturally lean breast meat delivers sub-3% fat content without trimming intervention. German retail chains anchor private-label portfolios around turkey cuts, capitalizing on EU Nutri-Score favorable ratings to drive placement in health-focused store zones.
- Chicken:Poultry processors achieve standardized sub-10% fat ratios through controlled feed regimens and selective muscle harvesting. Tyson Foods leverages integrated supply chains to secure volume for food service distributors supplying U.S. regional restaurant chains with certified lean-protein specifications.
- Beef:Mechanical blade trimming and centrifugal separation reduce intramuscular fat to target thresholds. JBS deploys precision trimming technologies for processor clients requiring standardized lean-to-fat ratios in multi-state delivery networks.
- Pork:Selective raw-material sourcing from leaner genetic lines combines with controlled processing to meet reduced-fat claims. Hormel Foods emphasizes precise fat-content packaging declarations for retail differentiation.
- Lamb:Inherently higher fat composition limits commercial reduced-fat penetration to specialized health-oriented channels and institutional nutrition programs with strict procurement standards.
Turkey leads volumes today; beef is gaining share fastest as mechanical trimming technologies narrow the cost gap with poultry.
Processing Method:
Cost tier separation distinguishes capital-intensive thermal methods commanding premium positioning from lower-infrastructure approaches serving commodity channels.
- Grilling:Direct high-heat exposure renders surface fat while preserving moisture through rapid cook cycles. U.S. fast-casual chains specify grilled reduced-fat proteins for menu transparency and health-claim substantiation.
- Smoking:Extended low-temperature exposure with controlled airflow develops flavor compounds that compensate for fat-reduced sensory profiles. Regional barbecue specialists in the American South differentiate through proprietary smoke profiles.
- Roasting:Dry-heat circulation achieves uniform internal temperature with minimal fat retention, suiting institutional batch production for USDA school lunch programs.
- Steaming:Moist-heat transfer without direct flame contact preserves water-soluble nutrients while eliminating added fats. European hospital and elder-care catering contracts specify steamed preparations for regulated nutrition compliance.
- Baking:Enclosed dry-heat environments suit portion-controlled retail products where consistent finished specifications support front-of-pack fat-content claims.
Grilling dominates food service procurement; smoking commands the steepest expansion trajectory as flavor differentiation offsets sensory trade-offs in reduced-fat formulations.
Packaging Type:
Application context determines whether shelf-life extension or premium presentation takes priority in format selection.
- Vacuum Packed:Oxygen elimination extends refrigerated shelf life while compressing product for efficient logistics. Precision-fat products command higher unit margins in this format where compositional accuracy justifies premium positioning.
- Modified Atmosphere:Controlled gas mixtures balance aerobic and anaerobic preservation needs. MAP convergence with vacuum-sealed formats now supports e-commerce distribution of precision-fat products beyond regional cold chains.
- Canned:Thermal sterilization enables ambient storage for institutional procurement with extended supply security requirements.
- Tray Packed:Overwrapped foam or fiber trays dominate high-velocity retail environments where visibility and handling convenience outweigh extended shelf-life needs.
- Skin Packed:Tight film adhesion to product contours enhances retail presentation while reducing headspace gas exchange for moderate shelf-life extension.
Vacuum-packed formats anchor premium retail tiers; modified atmosphere packaging is expanding most quickly as distribution networks widen.
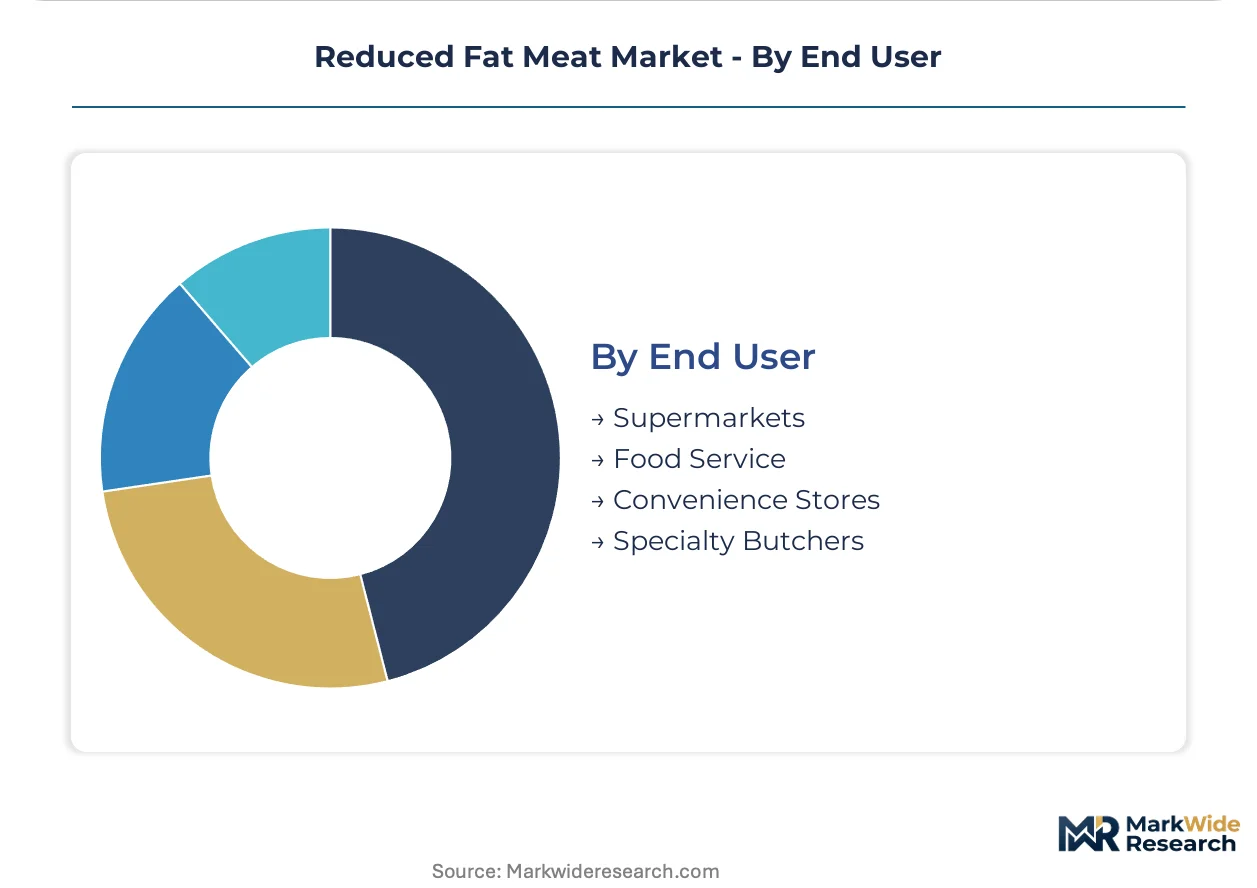
End User:
Customer type fragmentation separates price-sensitive volume channels from specification-intensive contracted supply relationships.
- Supermarkets:Private-label reduced-fat meat anchors protein portfolios in German retail chains, with Nutri-Score labeling driving placement decisions. Store-brand specifications increasingly demand supplier-provided compositional certification.
- Food Service:Regional restaurant chains and institutional caterers expand reduced-fat menu offerings as nutrition-certified sourcing managers displace traditional commodity buyers. USDA school lunch guidelines mandate lean-protein thresholds creating contracted volume pipelines.
- Convenience Stores:Grab-and-go prepared protein formats require packaging configurations supporting limited refrigeration infrastructure and rapid inventory turnover.
- Specialty Butchers:Artisan positioning emphasizes transparent sourcing and custom trimming to individual fat-content preferences, commanding margin premiums through service differentiation rather than scale.
Supermarkets move the highest absolute volumes; food service channels are climbing the fastest as health-menu expansion penetrates regional operator networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's retail chains have made reduced-fat fresh meat a core private-label category, while the United States drives food service innovation through health-menu expansion at regional restaurant chains.
United States
Regional restaurant chains and institutional caterers are expanding reduced-fat protein options to capture health-conscious diners. The FDA governs nutrition-fact panel accuracy and health-claim substantiation for reduced-fat meat products. Chicago-based food service distributors are adopting precision blade trimming systems to standardize lean-to-fat ratios across multi-state delivery networks.
Germany
Retail chains anchor private-label portfolios around reduced-fat turkey and chicken cuts, capitalizing on EU Nutri-Score favorable ratings. EFSA evaluates nutrient-profiling systems that member states use to restrict or promote product placement on retail shelves. Berlin and Munich processors are adjusting formulation specifications faster than counterparts in Southern Europe, making the country a testbed for fat-specific threshold calibration.
United Kingdom
Supermarkets are demanding supplier-provided compositional certification for store-brand reduced-fat meat specifications. The country's national food regulator oversees labeling standards aligned with evolving EU-derived frameworks. London and the Southeast England retail corridor are driving placement decisions for health-focused protein zones in major grocery chains.
France
Food service operators are expanding reduced-fat menu offerings as health-conscious dining gains traction in urban centers. The EU Nutri-Score front-of-pack system incentivizes processors to achieve favorable fat-content ratings. Parisian institutional caterers are specifying lean-protein thresholds for contracted volume pipelines serving school nutrition programs.
Canada
Health Canada oversees nutrition labeling and health-claim substantiation for reduced-fat meat products sold domestically. Maple Leaf Foods anchors its position through branded retail lines emphasizing precise fat-content claims. Toronto and Montreal processors are investing in modified atmosphere packaging to extend shelf life for precision-fat products distributed beyond regional cold chains.
Reduced Fat Meat Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base spans integrated protein giants with captive supply chains, mid-cap processors leveraging modular trimming technologies, and plant-based entrants reformulating analog products to capture health-oriented consumers. Two strategic archetypes dominate: scale-driven integrators controlling raw material through slaughter operations, and technology-focused processors deploying precision fat-removal equipment. Competitive moves center on backward integration into lean-muscle sourcing and geographic expansion of certified production capacity.
Within the integrated protein tier, Tyson Foods and JBS exemplify scale-driven archetypes with slaughter-to-retail control. Hormel Foods occupies a position emphasizing branded retail differentiation through precise packaging declarations. Among plant-based entrants, Beyond Meat Inc. and Impossible Foods represent reformulation-focused competitors targeting health-conscious consumers seeking alternatives to conventional meat. Maple Leaf Foods anchors the mid-cap processor segment with hybrid conventional and alternative protein portfolios. These five entities collectively illustrate the competitive spectrum from commodity scale to specialized health-positioning.
| Leading Market Players |
|---|
| Tyson Foods |
| Hormel Foods |
| Beyond Meat Inc. |
| Quorn Foods |
| Cargill |
| Impossible Foods |
| JBS |
| Gardein Protein International |
| Maple Leaf Foods |
| Others |
Cost & Logistics Intelligence
Precision blade trimming systems and centrifugal fat-removal equipment are compressing production economics while redistributing bargaining power from integrated slaughterhouses toward mid-cap processors capable of modular line configurations. This technology diffusion simultaneously lowers entry thresholds and fragments pricing power across the value chain.
Pricing Analysis
Capacity additions in Brazil and Germany are reshaping price floors for standardized lean-to-fat ratio products, forcing incumbent processors to absorb feed cost volatility rather than pass through increases. Three-tier pricing structure across premium certified, standard commercial, and economy private-label levels stratifies according to USDA process verification status and precision-fat certification. Pricing pressure stems from corn and soybean price swings that compress margins for lean-meat production requiring longer feeding cycles. Institutional caterers exhibit highest price sensitivity due to contracted volume pipelines with fixed reimbursement rates, while specialty butchers command premium tolerance through transparent sourcing narratives.
Supply Chain Analysis
USDA process verification and FDA health-claim substantiation function as gating mechanisms that restrict certified production to a limited pool of facilities, creating supply bottlenecks for mid-size processors. Raw material sourcing concentrates in the United States, Brazil, and Germany, where integrated protein giants control captive slaughter operations and lean-muscle allocation. Feed inputs—corn, soybean meal, and alternative protein formulations—constitute the primary cost components subject to commodity volatility. Single-source vulnerability runs through USDA-certified facilities capable of precise fat-content certification. Distribution runs through food service distributors with centralized commissary operations and retail chains with direct processor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where the FDA's updated nutrition labeling requirements and the EU's Nutri-Score front-of-pack system continuously ratchet demand for certified reduced-fat formulations.
For Market Incumbents: To counter margin compression from feed cost volatility and technology diffusion to mid-cap competitors, Tyson Foods and JBS should deepen backward integration into lean-muscle sourcing through selective breeding programs and premium feed formulation captive supply. Hormel Foods must reinforce branded retail differentiation by investing in real-time compositional analysis certification that substantiates precise fat-content claims against private-label encroachment. For New Entrants and Emerging Players: Modular precision trimming technologies offer entry pathways into the food service distributor segment where regional restaurant chains demand standardized lean-to-fat ratios but lack national supplier relationships. Poland and the Netherlands present the most penetrable geographies for private-label replication of Germany's reduced-fat fresh meat retail model. A technology-first go-to-market angle should emphasize supplier-provided menu-nutrition data and staff training to capture procurement authority from nutrition-certified sourcing managers. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap processors with USDA-certified facilities and modular trimming capabilities but underdeveloped branded retail presence. Long-term viability hinges on regulatory compliance infrastructure that becomes irreplicable as certification timelines compress and talent scarcity intensifies. The signal to watch is front-of-pack regulation harmonization—convergence around fat-specific thresholds would advantage scaled processors, while fragmentation would reward agile regional specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lean-Muscle Sourcing | Selective breeding programs in Iowa and São Paulo secure premium feed formulation captive supply. |
| Precision Trimming Technology Deployment | Real-time compositional analysis modularizes production lines for standardized fat-ratio certification. |
| Private-Label Portfolio Expansion | German retail chains demonstrate reduced-fat fresh meat anchors store-brand protein portfolios. |
| Modified Atmosphere Packaging Convergence | MAP technology extends shelf life for e-commerce distribution beyond regional cold chains. |
| Institutional Nutrition Program Certification | USDA school lunch guidelines create contracted volume pipelines for lean-protein threshold compliance. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with meat science directors at integrated protein processors, regulatory affairs leads navigating FDA and USDA approval pathways, procurement managers at regional restaurant chains, and packaging engineering specialists developing modified atmosphere formats. Secondary validation drew from FDA nutrition labeling guidance documents, USDA process verification records, EFSA nutrient-profiling evaluations, EU Nutri-Score implementation reports, and customs data tracking lean-muscle trade flows. Bottom-up facility capacity modeling and top-down consumption pattern analysis were triangulated against cross-referenced stakeholder inputs.
Comparable historical reference periods anchored volume and value projections across the analysis window, with growth trajectories derived from segmented modeling across product type, processing method, packaging format, and end-user channel dimensions. Species-specific fat-content thresholds, mechanical trimming technology adoption curves, and regulatory implementation timelines constituted primary forecast inputs. CAGRs were computed from annualized progression rates validated against capacity expansion announcements and certification pipeline data.
The model holds under stable feed cost regimes and incremental regulatory tightening; deviation in corn and soybean price volatility or abrupt front-of-pack mandate harmonization would shift volume projections. Forecasts reflect documented assumptions regarding technology diffusion rates and certification timeline compression. A model refresh is warranted upon material change in EU member state Nutri-Score adoption patterns or USDA facility certification capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Beef Bone Broth Market
Meat Products
Global Beef Market
Meat Products
Shark Meat Market
Meat Products
South Africa Processed Meat Market
Meat Products
Low-Fat Ham Market
Meat Products
Beef Fat Powder Market
Meat Products
Canned Beef Market
Meat Products
Meat Packaging Market
Meat Products
Germany Poultry Meat Market
Meat Products
Mexico Meat Products Market
Meat Products
Animal Protein Market
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
United States Animal Protein Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Fresh Organic Chicken Market
Meat Products
India Poultry Meat Market