
 Low-Fat Sweets Market | 2026-2036
Low-Fat Sweets Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Fat Sweets Market Analytics
Millennial households seeking permissible indulgence is unwinding the traditional family-targeted positioning that long defined mass-market confectionery. Danone S.A. leverages its dairy-based formulation expertise to anchor premium low-fat frozen dessert lines in European retail. Mondelez International competes through scaled chocolate manufacturing that extends reduced-fat bar formats across conventional grocery channels. Nestle differentiates via integrated supply chain control over proprietary fat-mimetic ingredient sourcing.
Low-fat sweets are confectionery and dessert products formulated with substantially reduced lipid content, typically achieved through fat replacer systems such as maltodextrin-protein complexes, modified food starches, or water-in-oil emulsion restructuring that preserves mouthfeel while delivering under three grams of fat per standard serving; their primary commercial purpose centers on satisfying hedonic cravings within calorie-controlled dietary frameworks. Chocolate Bars and Ice Cream occupy the dominant margin pools, with the former benefiting from cocoa butter reduction technologies and the latter from aeration and protein-stabilization advances that maintain creaminess. Gummy Candies represent the fastest-growing product type as gelatin-alternative hydrocolloids enable fat-free formulation with clean-label positioning.
FDA nutrition labeling requirements and the EU Nutrition and Health Claims Regulation shape permissible marketing language around fat reduction, while FSSAI's progressive tightening of packaged food fat thresholds in India is redirecting multinational reformulation roadmaps. Health Canada and EFSA both scrutinize novel fat replacer safety dossiers, creating variable speed-to-market across jurisdictions. Stakeholders must monitor evolving front-of-package warning systems and sugar-reduction mandates that increasingly couple with fat-content thresholds to determine viable product architecture.
Market Dynamics
Reformulation pipelines now pivot on erythritol-stevia blends as primary sweetening architecture, forcing incumbent sugar alcohol suppliers to defend volume positions against clean-label alternatives.
Growth Catalysts
- EU Nutrition and Health Claims Regulation:Permissible fat-reduction marketing language drives portfolio reallocation toward compliant SKUs in German and French retail channels.
- Protein-stabilization advances:Aeration technologies enable ice cream formulations under three grams fat per serving without creaminess degradation.
- Millennial household purchasing concentration:Health-conscious cohorts now control primary confectionery procurement decisions, favoring permissible indulgence positioning.
Market Restraints
- Cocoa butter volatility:Chocolate bar margins compress when cocoa butter futures spike, constraining reduced-fat line expansion.
- EFSA novel food dossier timelines:Fat replacer approvals stretch eighteen to thirty-six months, delaying North American formulation launches in EU markets.
- Full-fat artisanal substitution:Premium confectionery segments retain consumer preference where fat carries flavor signaling.
Strategic Opportunities
- FSSAI fat threshold tightening:India's progressive packaged food standards redirect multinational reformulation roadmaps toward export-ready low-fat architectures.
- Gelatin-alternative hydrocolloids:Pectin and agar-agar convergence enables clean-label gummy candy platforms with zero fat content.
- D2C subscription channels:Direct-to-consumer sampling bypasses conventional grocery slotting fees for emerging low-fat brands.
Industry Challenges
- Cross-functional formulation talent scarcity:Food scientists possessing both lipid chemistry and sensory profiling expertise command premium compensation.
- Legacy equipment retrofitting costs:Aeration and emulsion restructuring lines require seven-figure capital deployment for commercial-scale production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Fat Sweets Market |
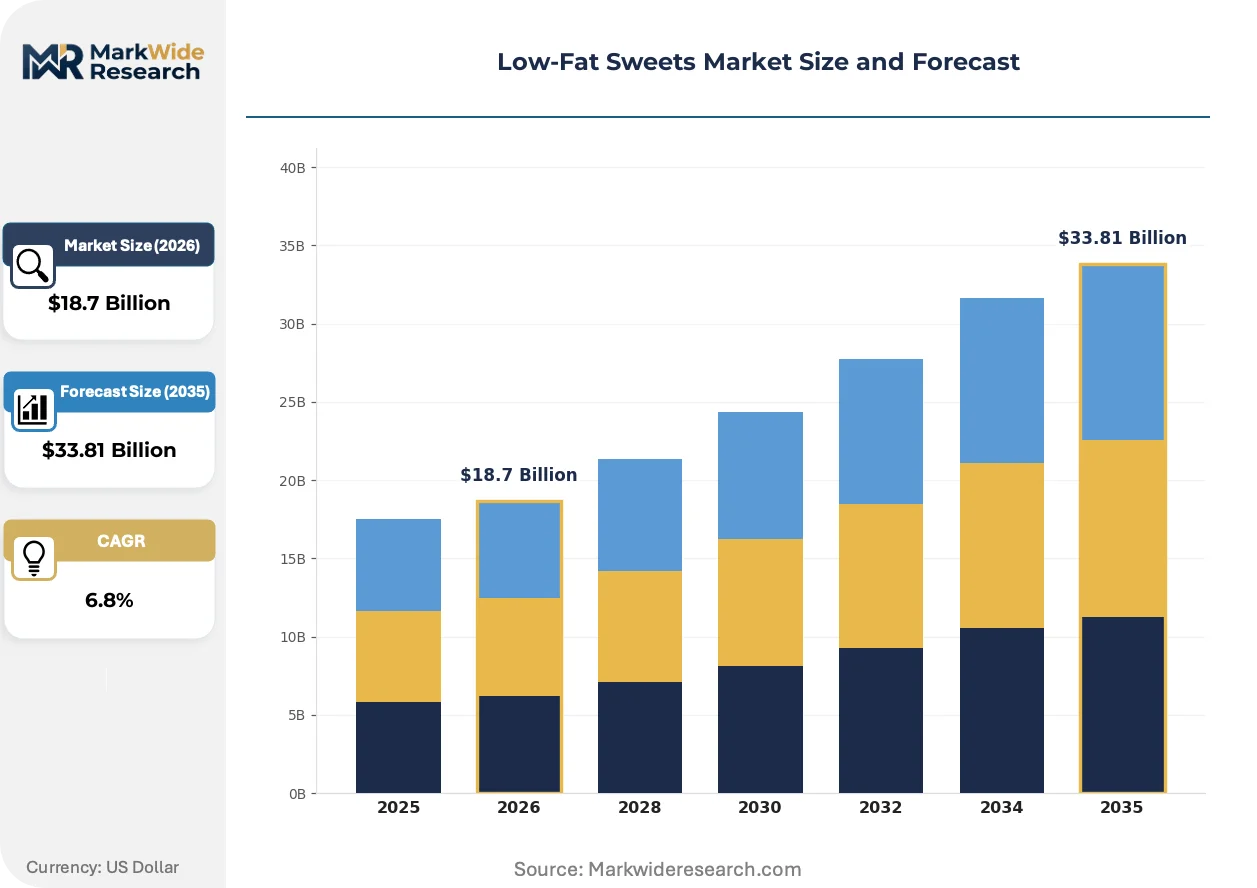
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Bars, Cookies, Gummy Candies, Ice Cream Ingredient Type: Stevia, Sucralose, Erythritol, Agave Nectar Distribution Channel: Supermarkets, Online Retail, Health Stores, Convenience Stores Consumer Type: Health-Conscious Individuals, Weight Watchers, Fitness Enthusiasts, Families |
| Companies Covered | Danone S.A., Unilever, General Mills, Mondelez International, Chobani, Halo Top Creamery, PepsiCo, Kellogg Company, Nestle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Fat Sweets Market Evolving Landscape
Clean-label ingredient architectures are compressing traditional formulation timelines while regulatory front-of-package warning systems force simultaneous fat and sugar reduction in single product generations.
Erythritol-stevia hybrid sweetening systems is supplanting maltitol and sorbitol in North American and European portfolios. Mid-sized confectionery manufacturers are adopting these blends at accelerated cadence to meet retailer clean-label mandates. The shift is compressing contract manufacturing capacity for legacy sugar alcohol processing.
Health Canada's scrutiny of novel fat replacer safety dossiers is extending pre-market approval timelines beyond comparable FDA pathways. Manufacturers now sequence launch strategies to prioritize US market entry before Canadian regulatory submission. Reduced-fat frozen dessert categories face the most pronounced timeline disadvantages.
Retail buyer consolidation is concentrating shelf-space negotiations around three to five national account managers per major grocery chain. Emerging low-fat brands now bypass traditional broker networks in favor of direct category manager relationships. Germany and the United Kingdom exhibit the most compressed supplier rostering dynamics.
Low-Fat Sweets Market Segmentation
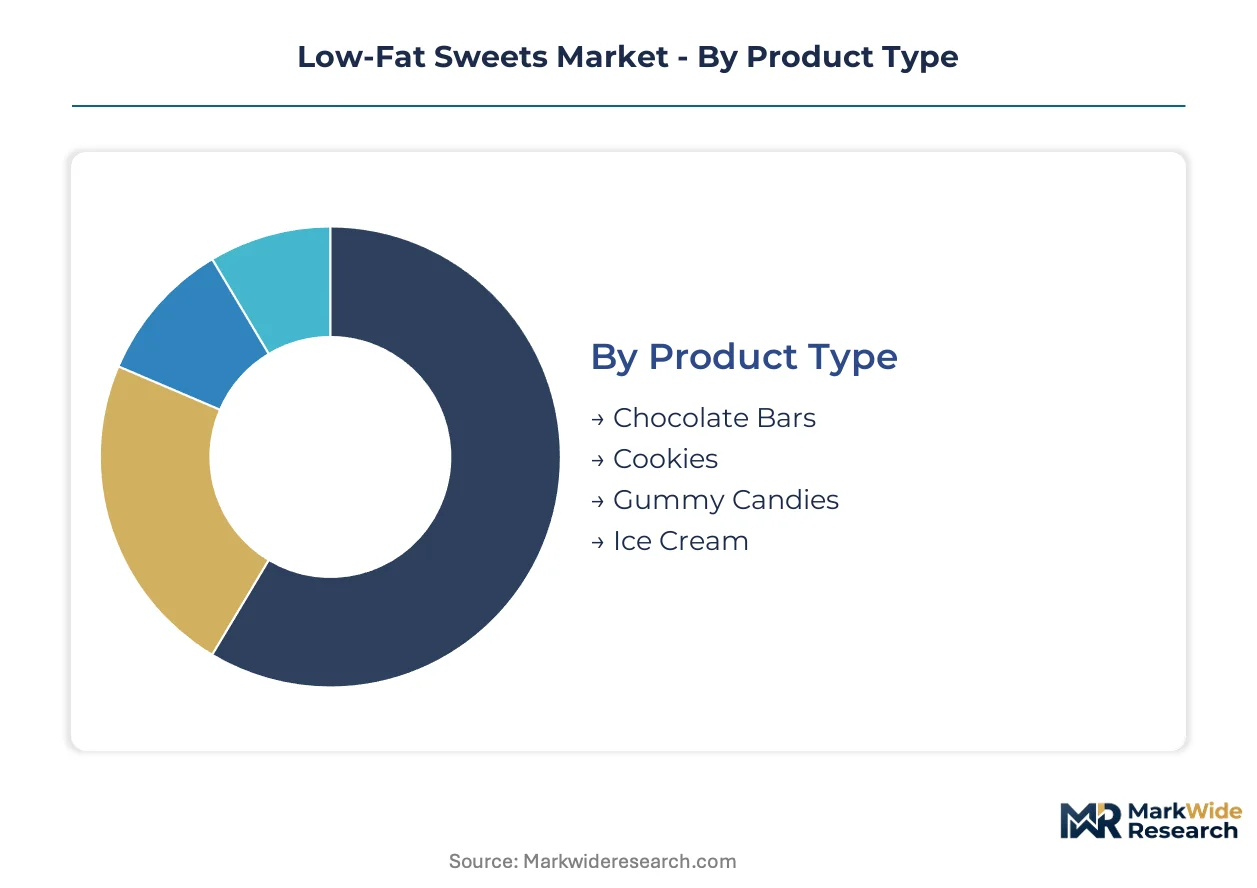
Low-fat sweets manufacturers configure product portfolios across four distinct segmentation axes to capture divergent consumer willingness-to-pay and channel economics. Each category reveals where formulation investments concentrate and how regulatory compliance costs distribute across market tiers.
Product Type:
Chocolate Bars and Ice Cream command the deepest margin pools, driven by cocoa butter reduction technologies and aeration patents that protect premium pricing.
- Chocolate Bars:Cocoa butter displacement through structured emulsions and protein-fat complexes preserves snap and melt profiles under three grams fat per serving. German and Swiss retail channels concentrate demand for reduced-fat dark variants where clean-label positioning commands shelf space.
- Ice Cream:Protein-stabilized aeration and modified starch systems replicate creaminess without dairy fat loading. North American households seeking permissible indulgence drive volume, though EFSA novel food dossier timelines delay European reformulation launches.
- Cookies:Fat replacer systems using maltodextrin-protein matrices achieve texture parity in reduced-fat formats.
- Gummy Candies:Pectin and agar-agar hydrocolloids enable zero-fat formulation with clean-label positioning.
The dominant share belongs to Chocolate Bars, while Gummy Candies is closing the gap fastest.
Ingredient Type:
Cost tier stratification separates premium natural extracts from commodity synthetic alternatives, with patent-protected blends capturing formulation services revenue.
- Erythritol:Bulk sweetening with cooling effect and zero glycemic impact; erythritol-stevia hybrid systems now displace maltitol across North American portfolios. Clean-label mandates from major US grocery retailers accelerate contract manufacturing conversion.
- Stevia:Reb M and Reb D glycoside advances eliminate bitter aftertaste in high-intensity applications. European confectionery lines favor stevia-sucralose blends where EU Health Claims Regulation compliance requires natural positioning.
- Sucralose:Heat-stable synthetic sweetener dominating cost-sensitive baked applications.
- Agave Nectar:Fructose-rich syrup with organic certification appeal in Mexican and US Southwest markets.
Erythritol holds volume leadership, though Stevia exhibits the steepest expansion trajectory.
Distribution Channel:
Channel concentration determines slotting fee exposure and direct consumer data capture capabilities.
- Supermarkets:National account manager consolidation in Germany and the United Kingdom compresses supplier rosters to three to five per chain. Reduced-fat lines compete for shelf space through promotional fund commitments and category captain arrangements.
- Online Retail:Direct-to-consumer subscription models bypass conventional grocery slotting fees for emerging brands. Health-conscious millennial households drive repeat purchase algorithms through personalized permissible indulgence curation.
- Health Stores:Premium positioning channels with educated staff driving trial conversion.
- Convenience Stores:Impulse-driven single-serve formats with limited reduced-fat SKU penetration.
Supermarkets retain the dominant position, while Online Retail is gaining share fastest.
Consumer Type:
Application-specific need states separate medical-adjacent weight management from lifestyle-oriented fitness positioning.
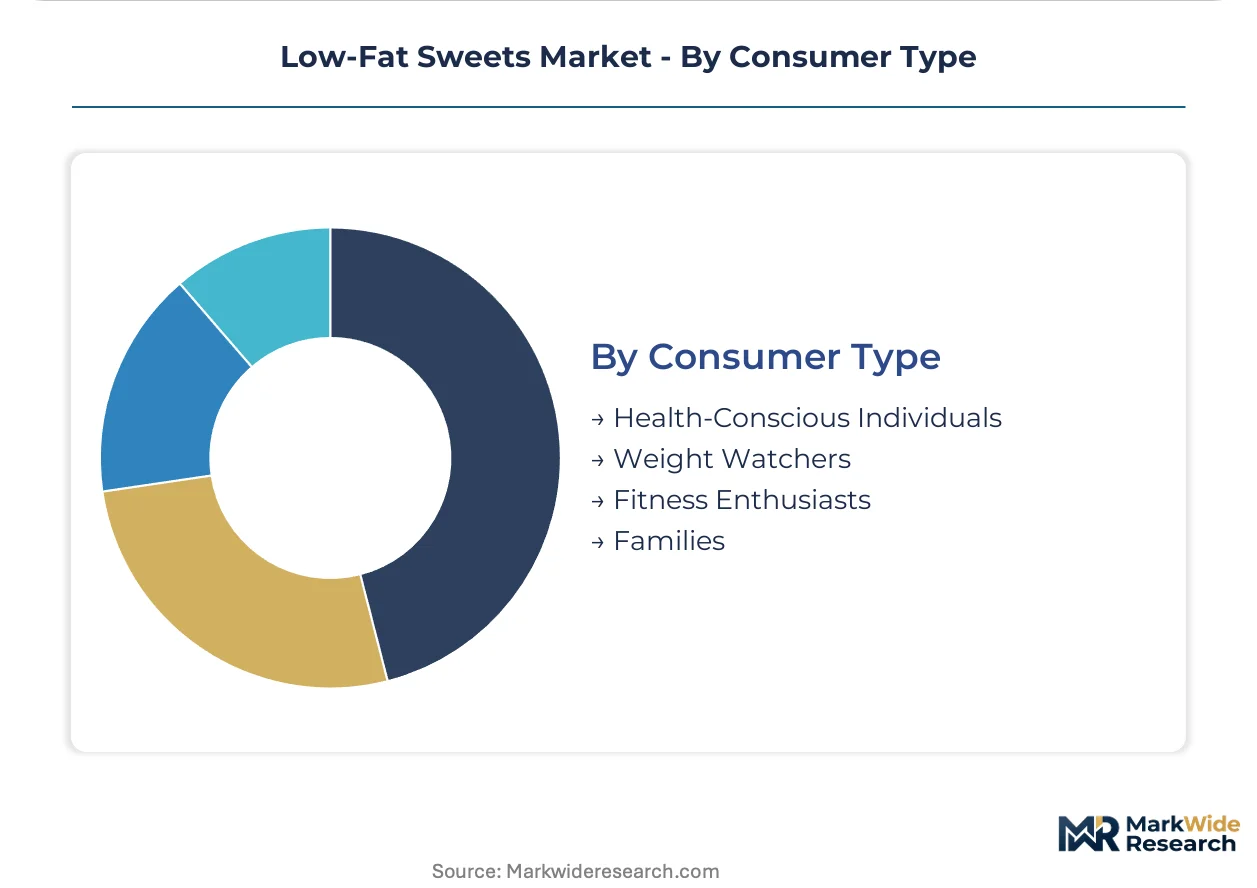
- Health-Conscious Individuals:Millennial cohorts controlling primary household purchasing decisions seek hedonic satisfaction within calorie-controlled frameworks. Permissible indulgence marketing language drives portfolio reallocation toward compliant SKUs.
- Weight Watchers:Structured program participants requiring precise macronutrient tracking and portion-controlled formats. Point-system compatibility determines product trial and loyalty in US and UK markets.
- Fitness Enthusiasts:Protein-fortified low-fat desserts targeting post-workout recovery occasions.
- Families:Traditional household-targeted positioning unwinding as health-conscious parents substitute personal indulgence for family-pack purchasing.
Health-Conscious Individuals command the dominant segment, while Fitness Enthusiasts is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German reformulated confectionery exports flow into French and UK retail channels, establishing a westward trade corridor that shapes EU low-fat sweets distribution patterns.
United States
Millennial household purchasing concentration drives permissible indulgence positioning across supermarket and direct-to-consumer channels. FDA nutrition labeling requirements enforce strict fat-reduction claim substantiation, compressing marketing language options. Chicago and Minneapolis-St. Paul anchor major dairy-based frozen dessert manufacturing clusters where aeration technology patents concentrate.
Germany
Health-conscious consumers dominate confectionery procurement decisions, favoring clean-label reduced-fat chocolate variants. EU Nutrition and Health Claims Regulation compliance mandates precise formulation documentation for shelf space access. Cologne and Hamburg host multinational brand reformulation centers where erythritol-stevia blend adoption accelerates fastest.
United Kingdom
Weight management program participants create structured demand for portion-controlled low-fat formats. EFSA novel food dossier timelines delay fat replacer approvals, sequencing launch strategies behind US market entry. London and the Midlands concentrate retail buyer consolidation, compressing supplier rosters to three to five national account managers per major grocery chain.
India
Rising health awareness among urban middle-class households redirects multinational reformulation roadmaps toward export-ready architectures. FSSAI progressive tightening of packaged food fat thresholds forces simultaneous sugar and fat reduction in single product generations. Mumbai and Bangalore emerge as testing grounds for clean-label gummy candy platforms using pectin and agar-agar hydrocolloids.
Canada
Cross-border retail integration channels US-manufactured reduced-fat lines into Ontario and Quebec distribution networks. Health Canada scrutiny of novel fat replacer safety dossiers extends pre-market approval timelines beyond comparable FDA pathways. Toronto anchors the primary frozen dessert reformulation activity, though regulatory sequencing disadvantages delay category expansion relative to US markets.
Low-Fat Sweets Market Competitive Landscape
Player mix skews toward multinational conglomerates with integrated dairy supply chains and specialized low-fat dessert challengers. Tiered concentration separates scale-driven chocolate manufacturers from agile frozen dessert innovators. Strategic archetypes include dairy-based formulation specialists, cocoa butter reduction technology holders, and direct-to-consumer subscription pioneers. Dominant competitive moves encompass portfolio reallocation toward clean-label architectures and backward integration into proprietary fat-mimetic ingredient sourcing.
Within the multinational conglomerate tier, Danone S.A., Mondelez International, and Nestle occupy anchor positions. Danone exemplifies dairy-based formulation expertise leveraged for premium frozen dessert lines. Mondelez represents scaled chocolate manufacturing capability extended across reduced-fat bar formats. Nestle anchors integrated supply chain control over captive fat-mimetic ingredient sourcing. These three entities collectively illustrate the competitive tension between dairy-rooted and confectionery-rooted low-fat sweets strategies.
| Leading Market Players |
|---|
| Danone S.A. |
| Unilever |
| General Mills |
| Mondelez International |
| Chobani |
| Halo Top Creamery |
| PepsiCo |
| Kellogg Company |
| Nestle |
| Others |
Value Network & Pricing Analysis
Ninety-day cocoa butter futures volatility compresses margin buffers across reduced-fat chocolate manufacturing, concentrating pricing power with integrated processors holding captive emulsion-technology assets while forcing toll-manufacturers toward commodity contract structures.
Pricing Analysis
Prior-generation maltitol-sorbitol formulations trade at steep discounts to current erythritol-stevia hybrid architectures, while next-generation pectin-agar gummy platforms command premium positioning. Three-tier pricing structure across premium clean-label, standard reformulated, and economy conventional tiers separates stevia-reb-M formulations from legacy sugar alcohols. Cost compression in standard tiers intensifies because contract manufacturing capacity constraints limit volume scaling. Health-conscious millennial households show lowest price sensitivity for permissible indulgence positioning, while family-pack purchasers in conventional grocery channels exhibit highest elasticity.
Supply Chain Analysis
Forty-five to sixty-day erythritol inventory cycles in North American contract manufacturing reflect just-in-time sourcing from Chinese and Thai fermentation facilities, with stevia leaf extraction concentrated in Paraguay and Kenyan cultivation zones. Fat replacer systems draw from modified potato starch processors in the Netherlands and maltodextrin-protein complex suppliers in Germany. Single-source vulnerability sits with erythritol fermentation capacity concentrated among three major producers. Distribution runs through national account manager consolidation at German and UK retail headquarters, bypassing traditional broker networks for direct category access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label sweetening architecture disruption is accelerating portfolio reallocation, with FSSAI fat-threshold tightening in India creating regulatory pull-through for export-ready low-fat formulations.
For Market Incumbents: Secure captive supply of proprietary fat-mimetic ingredients through backward integration into modified starch and protein-stabilization technology holders. Defend shelf space through category captain arrangements with consolidated German and UK retail buyers, while accelerating erythritol-stevia blend conversion ahead of clean-label mandate deadlines.
For New Entrants and Emerging Players: Anchor in direct-to-consumer subscription channels to bypass seven-figure slotting fees and national account manager gatekeeping at major grocery chains. Target health-conscious millennial households with personalized permissible indulgence curation algorithms, leveraging pectin-agar gummy platforms for zero-fat clean-label differentiation.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerates spinning non-core reduced-fat dessert lines amid portfolio consolidation. Long-term viability hinges on regulatory compliance capabilities spanning FDA, EFSA, and FSSAI dossier management. Watch EFSA novel food approval timelines as inflection signal for European market entry sequencing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Pipeline | Erythritol-stevia blend adoption accelerates ahead of retailer mandate deadlines in North America. |
| Direct-to-Consumer Channel Launch | Subscription models bypass slotting fee barriers and capture millennial household repeat purchase data. |
| Backward Integration into Fat Replacers | Captive supply of modified starch systems protects margin compression from commodity input volatility. |
| Regulatory Dossier Pre-Positioning | EFSA and Health Canada submission sequencing determines European and Canadian market entry timing. |
| Gelatin-Alternative Gummy Platform | Pectin-agar hydrocolloid convergence enables zero-fat clean-label positioning in fastest-growing segment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across formulation scientists at Danone, Mondelez, and Nestle reformulation centers, category buyers at German and UK retail headquarters, and contract manufacturing procurement leads. Secondary validation drew from FDA GRAS notifications, EFSA novel food dossier filings, FSSAI packaged food standards updates, and Nielsen retail audit data. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure models.
Across the analysis window, projections integrated product-type segmentation by chocolate bar, ice cream, cookie, and gummy candy formats; ingredient-type tiers spanning erythritol, stevia, and sucralose architectures; and distribution channel splits between supermarket, online retail, and health store pathways. CAGRs were derived from historical trajectory analysis adjusted for regulatory inflection points and clean-label adoption curves. Millennial household purchasing concentration and permissible indulgence positioning velocity served as primary demand-side forecast inputs.
Material uncertainties — cocoa butter commodity spikes, EFSA approval timeline extensions, and front-of-package warning system expansions — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory compliance maintenance and clean-label mandate adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Gum Base Candy Market
Confectionery
Europe Dark Chocolate Market
Confectionery
Europe Caramel Chocolate Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
Organic Chocolate Confectionery Market
Confectionery
Global Mochi Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Asia Pacific and Latin America Sugar Confectionery Market
Confectionery
Non-Chocolate Candy Market
Confectionery
Licorice Candy Market
Confectionery
Truffle Chocolate Market
Confectionery
Functional Confectionery Market
Confectionery
Brain Mint Market
Confectionery
Low Calorie Keto Desserts Market