
 Pastry Fillings Market | 2026-2036
Pastry Fillings Market Size, Share, and Industry Trends Forecast 2026-2036
Pastry Fillings Market Analytics
The capital-intensity divergence between industrial-scale producers and artisan suppliers is bifurcating competitive dynamics in pastry fillings. Dawn Foods leverages integrated fruit processing infrastructure across North American bakery channels. Puratos Group sustains R&D intensity in enzyme-stabilized cream systems for European industrial bakers. AGRANA Beteiligungs-AG anchors its position through backward integration into Central European fruit concentrate supply.
Pastry fillings denote viscous or semi-solid preparations—typically 40-75% soluble solids for fruit bases, emulsified fat-water matrices for creams—engineered for thermal stability during baking and sheeting operations. Their primary commercial purpose centers on delivering consistent flavor release, moisture retention, and structural integrity in laminated, choux, and shortcrust applications. Fruit fillings lead volume globally due to universal bakery application, while chocolate fillings command premium positioning in patisserie and foodservice channels. Powdered form segments are gaining traction in artisan and small-batch settings where reconstitution flexibility reduces cold-chain dependency.
FDA oversight of GRAS determinations and EFSA evaluations under the EU Food Information to Consumers Regulation shape permissible additive portfolios and front-of-pack labeling claims for transnational suppliers. BIS standards in India and FSSAI fortification guidelines further fragment compliance requirements for exporters. Stakeholders must monitor evolving sugar-reduction mandates and novel sweetener approval pathways across their priority jurisdictions.
Market Dynamics
Clean-label reformulations under FDA and EFSA guidance are bifurcating supplier capabilities, forcing capital upgrades for enzyme-stabilized cream systems and cold-aseptic fruit processing while artisan bakers pivot to powdered reconstitution formats.
Growth Catalysts
- EFSA Food Information to Consumers Regulation:Mandatory front-of-pack disclosure is accelerating clean-label R&D investments among industrial bakers seeking competitive differentiation in European retail channels.
- Artisan bakery channel expansion:Specialty chains are diversifying filled pastry portfolios, creating pull-through demand for high-viscosity fruit bases with extended ambient stability.
- Enzymatic stabilization technology:Lipase-modified cream systems are reducing emulsifier dependency, enabling trans-fat-free formulations that meet tightening cardiovascular health guidelines.
Market Restraints
- Central European fruit concentrate supply concentration:Backward-integrated processors dominate strawberry and apricot pulp sourcing, creating margin pressure for independent filling compounders.
- Cold-chain infrastructure gaps:Cream-based fillings require uninterrupted refrigerated distribution, limiting penetration into emerging markets with unreliable logistics networks.
- Sugar reduction mandates:France's nutritional profiling system and UK HFSS regulations are compressing permissible sweetness levels in formulations targeting children.
Strategic Opportunities
- India FSSAI fortification guidelines:Micronutrient-enriched pastry fillings for school feeding programs represent an underdeveloped white space with government procurement scale.
- Plant-based fat emulsion convergence:Combination of oleogel technology and cultured dairy proteins is enabling vegan cream fillings with equivalent mouthfeel to butter-based systems.
- Direct-to-artist e-commerce channels:Specialty ingredient platforms are disintermediating traditional foodservice distributors for small-batch bakery operators.
Industry Challenges
- Clean-label formulation expertise scarcity:Industrial food scientists with simultaneous competence in enzyme technology and sensory mapping command premium compensation, constraining mid-tier supplier expansion.
- Multi-jurisdiction additive approval timelines:Novel sweeteners face staggered GRAS, EFSA novel food, and FSSAI safety evaluations, delaying synchronized product launches across priority markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pastry Fillings Market |
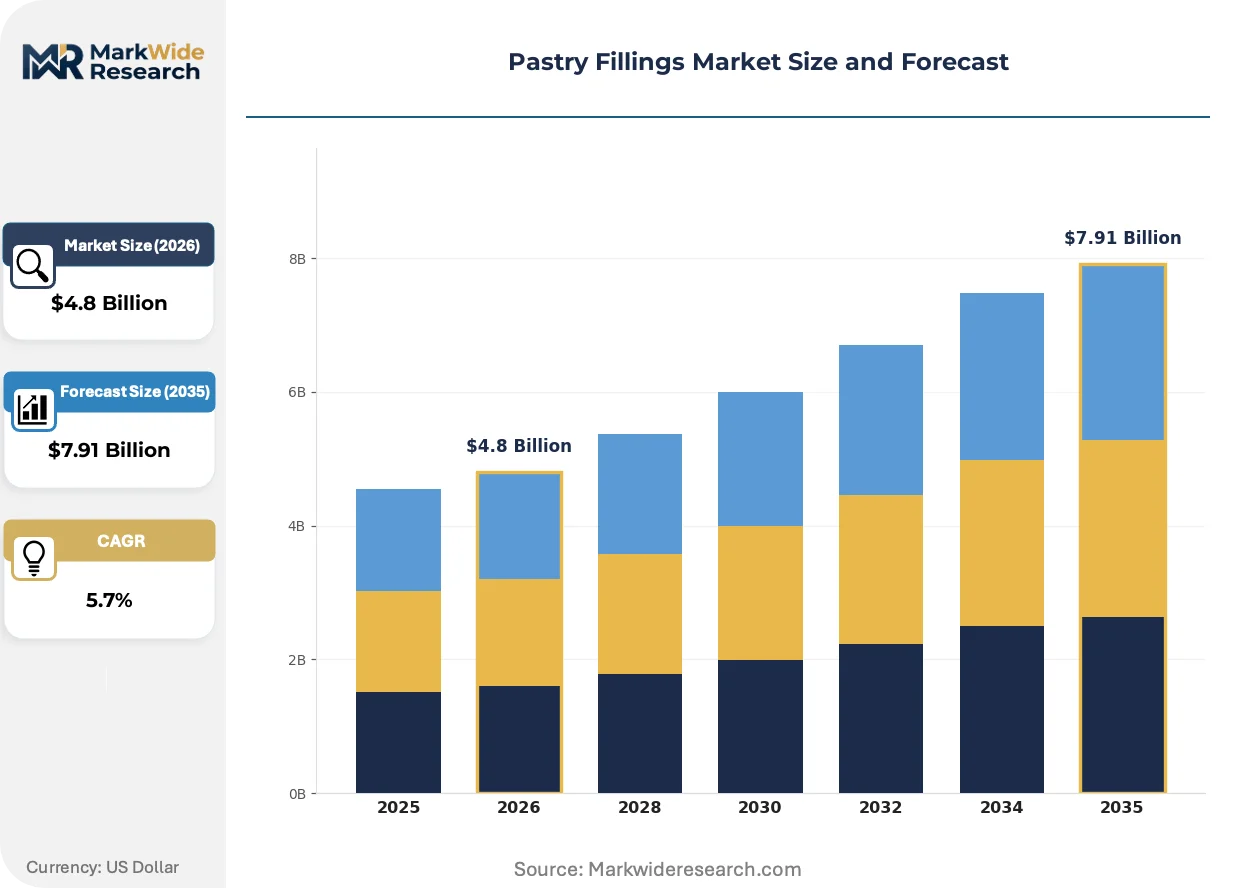
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Fillings, Cream Fillings, Chocolate Fillings, Nut Fillings Form: Liquid, Solid, Powdered, Paste Sweetness Level: Sweet, Semi-Sweet, Unsweetened, Savory Packaging Type: Tubs, Pouches, Jars, Canisters |
| Companies Covered | Dawn Foods, Puratos Group, AGRANA Beteiligungs-AG, Zentis, Barry Callebaut, Cargill, Archer Daniels Midland Company, Avebe, Bakels Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pastry Fillings Market Evolving Landscape
Active reformulation of fat-water matrices and fruit preservation chemistry is compressing traditional additive portfolios while expanding permissible clean-label claims across laminated and choux applications.
High-pressure processing for fruit fillings is supplanting thermal pasteurization in premium patisserie supply chains. European artisan bakeries are adopting HPP-treated strawberry and raspberry bases at accelerating rates. This shift is enabling 90-day ambient shelf life without synthetic preservatives, compressing the addressable market for traditional chemically stabilized alternatives.
REACH restrictions on titanium dioxide are forcing pigment reformulation in white cream fillings and decorative glazes. Industrial compounders are migrating to calcium carbonate and starch-based opacifier blends. French and German industrial bakers face the most acute compliance deadlines, with reformulated products already entering validation trials for 2025 retail resets.
Specification-driven procurement is consolidating buyer power among multinational bakery groups. Category managers are unbundling filling supply from flour and shortening contracts, introducing competitive tender cycles every 18-24 months. This pattern is most pronounced in the United States, where Dawn Foods and regional co-ops are restructuring vendor panels to reward dual-source flexibility.
Pastry Fillings Market Segmentation
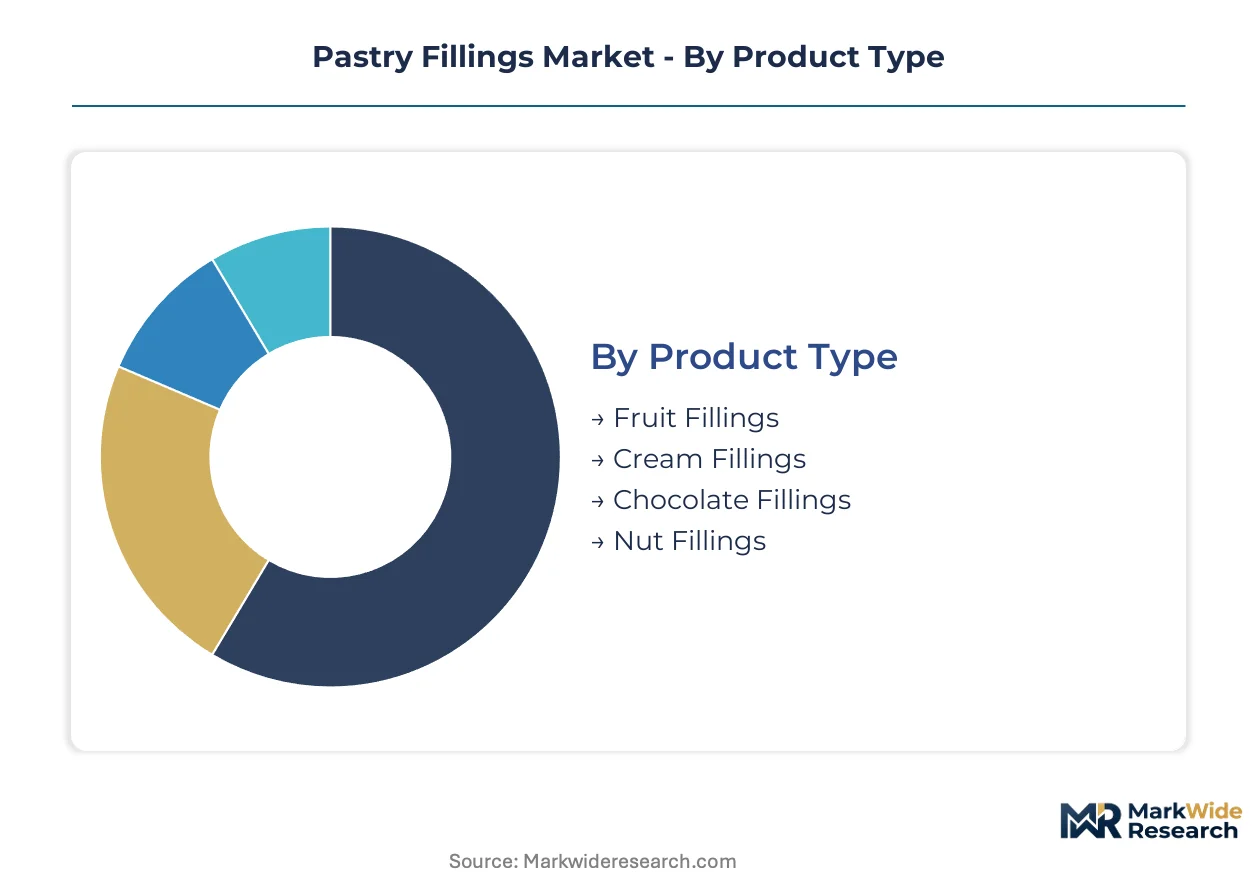
Pastry filling suppliers configure production lines around viscosity specifications and thermal stability requirements that vary sharply by end-use application. Segmentation discipline separates commodity volume plays from premium positioning in patisserie and artisan channels.
Product Type:
FDA GRAS determinations for fruit acidulants and EFSA enzyme approvals for cream stabilization create divergent compliance burdens across these four categories.
- Fruit Fillings:Aqueous suspensions of 40-75% soluble solids, pH-adjusted for thermal stability in laminated dough applications. Industrial bakeries in France and Germany account for the dominant share of strawberry and apricot pulp demand, pulled by clean-label reformulation mandates under EFSA guidance.
- Cream Fillings:Emulsified fat-water matrices stabilized by lipase-modified proteins or traditional emulsifier systems. Cold-chain dependency limits penetration into Indian and Brazilian markets with unreliable refrigerated distribution, though enzymatic stabilization is reducing this constraint.
- Chocolate Fillings:Cocoa butter-based or compound coatings with defined melting profiles for enrobing and injection. Premium patisserie channels in Paris and Milan drive specification intensity.
- Nut Fillings:Ground paste or praline suspensions with controlled particle size for sheeting compatibility. California almond and Turkish hazelnut supply chains anchor sourcing.
Fruit fillings handle the majority of throughput; cream fillings are expanding most quickly on share as enzyme-stabilized formulations penetrate trans-fat-free mandates.
Form:
Cost-to-serve economics bifurcate between cold-chain-dependent liquid formats and ambient-stable alternatives that reduce logistics expenditure.
- Liquid:Pumpable fruit or cream preparations for automated depositing equipment. Industrial-scale bakeries in the United States favor this format for high-speed laminating lines.
- Solid:Chunk or piece inclusions for textural contrast. Frozen fruit pieces for Danish applications dominate this niche.
- Powdered:Dehydrated bases requiring reconstitution, eliminating refrigeration requirements. Artisan bakeries and small-batch operators in India and Southeast Asia are adopting this format fastest to bypass cold-chain gaps.
- Paste:High-viscosity preparations for manual or semi-automated application. European craft bakeries specify this form for choux and tartlet production.
Liquid forms capture the greatest volume; powdered forms are climbing the fastest as emerging market logistics constrain cream-based alternatives.
Sweetness Level:
Application requirements and health-regulatory pressure are fragmenting formulation targets across the sweetness spectrum.
- Sweet:Standard sucrose or glucose-fructose formulations for conventional pastry applications. Mass-market retail channels in the United States and Germany remain the core demand center.
- Semi-Sweet:Reduced sugar levels targeting adult palates in premium positioning. French nutritional profiling compliance is accelerating reformulation toward this tier.
- Unsweetened:Base preparations allowing downstream sweetener addition by bakery operators. Foodservice distributors favor this flexibility for custom contract manufacturing.
- Savory:Cheese, herb, or vegetable-based matrices for non-dessert applications. Quiche and savory tart growth in UK and Australian café channels is pulling demand.
Sweet formulations dominate current throughput; semi-sweet variants are gaining share fastest under sugar-reduction mandates.
Packaging Type:
Customer scale and handling automation requirements determine packaging selection, with sustainability pressures reshaping material specifications.
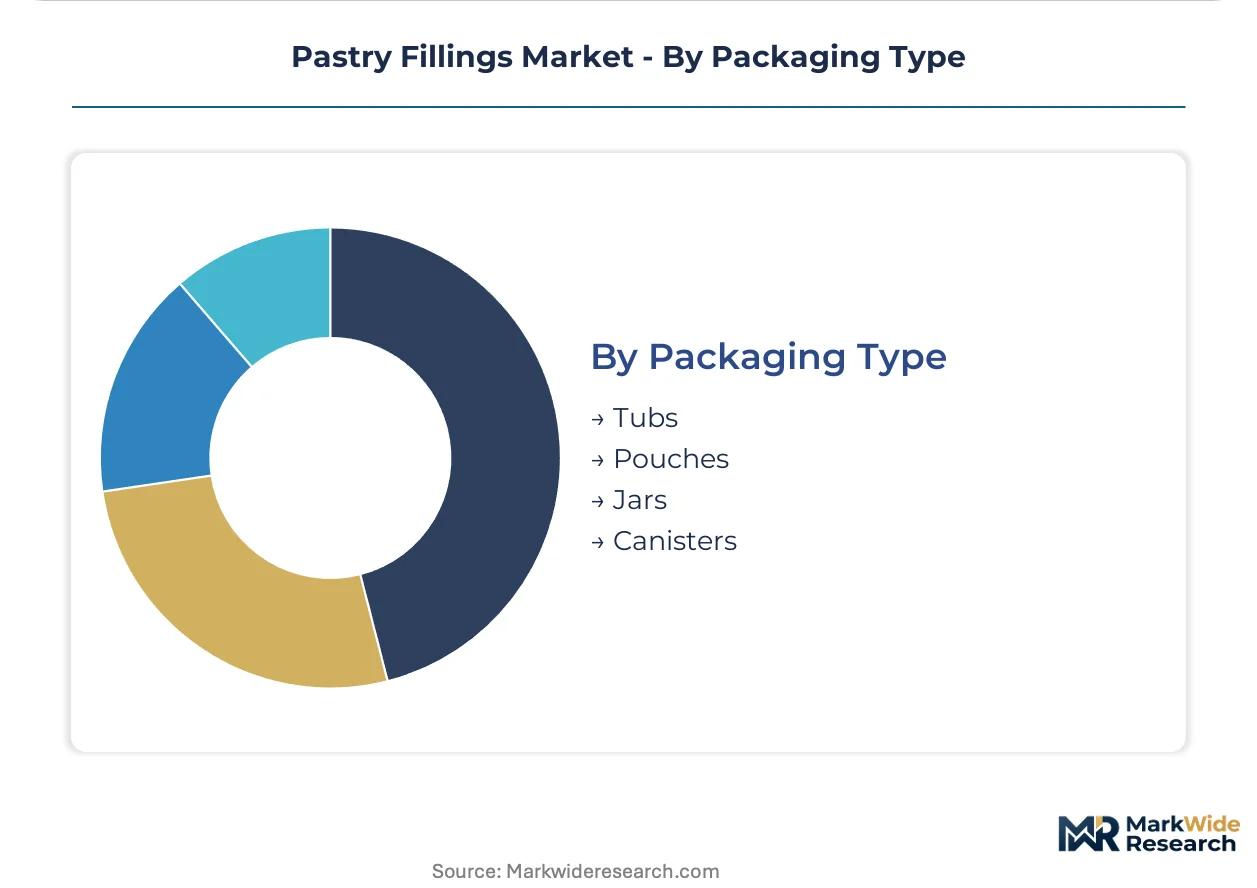
- Tubs:Rigid plastic or composite containers for foodservice and industrial bulk handling. High-volume bakery manufacturing facilities in Germany and the United States specify this format for automated unscrambling and filling lines.
- Pouches:Flexible film structures with fitments or tear-notches for portion control and reduced material intensity. REACH-compliant barrier films are becoming mandatory for European supply.
- Jars:Glass or PET containers for retail and specialty channels requiring premium shelf presentation. Artisan bakery direct-to-consumer sales favor this format.
- Canisters:Metal or rigid composite cylinders for extended shelf-life dry fillings. Powdered fruit and cream bases for institutional catering deploy this packaging.
Tubs manage the greatest volume throughput; pouches are expanding fastest as sustainability targets and logistics efficiency reshape procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in France and Germany where clean-label mandates command premium formulations, while United States buyers leverage scale procurement to compress supplier margins. This asymmetry shapes capital allocation across the competitive landscape.
United States
Industrial bakeries in Chicago and Minneapolis-St. Paul drive automated depositing demand for high-viscosity liquid formats. FDA GRAS determinations for modified starch systems influence reformulation timelines. Dawn Foods anchors North American supply through integrated fruit processing infrastructure across Midwest manufacturing corridors.
Germany
REACH restrictions on titanium dioxide accelerate white cream filling reformulation ahead of 2025 compliance deadlines. EFSA enzyme approvals for lipase-modified stabilization enable trans-fat-free cream systems. Industrial clusters in Bavaria and North Rhine-Westphalia validate next-generation opacifier blends for laminated dough applications.
France
Nutritional profiling compliance compresses permissible sweetness levels in children-targeted formulations, pulling semi-sweet variant development. Paris and Lyon patisserie channels drive specification intensity for premium chocolate fillings. Auvergne-Rhône-Alpes concentrates artisan bakery chain expansion with extended ambient stability requirements.
India
FSSAI fortification guidelines create procurement scale for micronutrient-enriched fillings in school feeding programs. Powdered reconstitution formats bypass cold-chain gaps in Maharashtra and Karnataka logistics networks. Mumbai and Bangalore bakery clusters adopt dehydrated bases fastest among emerging market operators.
Italy
Premium patisserie positioning in Milan sustains cocoa butter-based chocolate filling demand with defined melting profiles. Artisan sheeting compatibility requirements concentrate nut paste procurement from Piedmont hazelnut supply chains. Lombardy industrial bakers specify controlled particle size for laminated applications.
Pastry Fillings Market Competitive Landscape
Concentration sits with backward-integrated fruit processors and enzyme technology specialists who control critical input supply and stabilization IP. The competitive structure tiers across three archetypes: multinational ingredient conglomerates with captive distribution, regional specialists with vertical fruit pulp integration, and technology-forward compounders with clean-label R&D capabilities. Dominant competitive moves include portfolio diversification into plant-based fat emulsions and geographic expansion through direct-to-artisan e-commerce channels.
Within the integrated processor tier, Dawn Foods and AGRANA Beteiligungs-AG exemplify archetypes combining upstream fruit concentrate control with downstream bakery channel access. Puratos Group occupies a position on the enzyme stabilization vector, representing R&D-intensive specialists developing lipase-modified cream systems for trans-fat-free mandates. These three anchors span North American, Central European, and technology-forward competitive positions respectively.
| Leading Market Players |
|---|
| Dawn Foods |
| Puratos Group |
| AGRANA Beteiligungs-AG |
| Zentis |
| Barry Callebaut |
| Cargill |
| Archer Daniels Midland Company |
| Avebe |
| Bakels Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for Central European fruit concentrate lock in both supply access and price visibility for industrial compounders, while artisan bakers pivot to spot-market powdered formats to escape cold-chain cost escalation. This contract-structure divergence bifurcates margin profiles across the value chain.
Pricing Analysis
Configured-to-order pricing for enzyme-stabilized cream systems commands a 15-25% premium over standard fruit filling formulations, reflecting R&D amortization and clean-label certification costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal stability grade and organic certification status. Pricing pressure stems from sugar-reduction mandates compressing formulation flexibility in France and the United Kingdom. Mass-market retail channels in Germany exhibit the highest price sensitivity, while Paris patisserie buyers prioritize specification compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Hamburg and Rotterdam port congestion elevate landed costs for cocoa butter and hazelnut paste shipments entering European compounding facilities. Supply concentrates in Germany, France, and the United States for industrial-scale production, with India and Turkey anchoring emerging-market sourcing growth. Raw material dependencies center on Central European strawberry and apricot pulp, Malaysian palm oil fractions, and West African cocoa mass. Single-source vulnerability in lipase enzyme supply creates formulation bottlenecks for trans-fat-free cream systems. Distribution runs through foodservice distributors and direct-to-artisan e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pastry fillings sit in early-cycle expansion as clean-label reformulation mandates accelerate replacement demand across European industrial bakeries. Powdered format adoption in cold-chain-constrained markets extends the addressable frontier.
For Market Incumbents: Fortify backward integration into fruit concentrate supply and enzyme stabilization IP to defend margin position against regional specialists. Prioritize capacity addition in Bavaria and North Rhine-Westphalia to capture REACH-compliant reformulation demand. Channel control through direct-to-artisan platforms offsets distributor consolidation pressure. For New Entrants and Emerging Players: Direct-to-artisan e-commerce service layers where incumbents under-serve small-batch operators present the most penetrable white space. Target Maharashtra and Karnataka bakery clusters with micronutrient-enriched powdered bases for FSSAI school feeding procurement. Plant-based fat emulsion convergence offers a differentiated go-to-market angle for vegan cream formulations. For Investors and Strategic Acquirers: Capital is best deployed toward technology-forward compounders with clean-label R&D capabilities and captive enzyme stabilization IP. Long-term viability across a 5-10 year window hinges on regulatory compliance agility rather than commodity scale. The signal to watch is staggered novel sweetener approval timelines across FDA, EFSA, and FSSAI jurisdictions as an inflection indicator for synchronized product launch feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fruit Concentrate Supply | Captive sourcing from Central European pulp processors secures margin control against supply concentration. |
| Enzyme Stabilization R&D Investment | Lipase-modified cream systems enable trans-fat-free formulations under tightening EFSA cardiovascular guidelines. |
| Powdered Format Portfolio Expansion | Ambient-stable reconstitution bases bypass cold-chain gaps in Indian and Southeast Asian logistics networks. |
| Direct-to-Artisan E-Commerce Channel Development | Specialty ingredient platforms disintermediate traditional foodservice distributors for small-batch operators. |
| Plant-Based Fat Emulsion Convergence | Oleogel technology combined with cultured dairy proteins replicates butter-based mouthfeel in vegan fillings. |
Research Methodology
Initial hypotheses were tested against primary input from industrial bakery procurement managers, artisan chain operators, foodservice distribution executives, and regulatory affairs specialists, then refined through secondary validation. FDA GRAS determination databases, EFSA novel food registers, FSSAI fortification guidelines, and customs trade records provided triangulation anchors. Bottom-up volume modeling across product type, form, sweetness level, and packaging format converged with top-down market sizing.
Variance decomposition isolates volume, price, and mix effects across the projection horizon. Segmentation dimensions modeled include product type, form specification, sweetness tier, packaging format, and end-use channel. CAGRs derive from segment-level growth trajectory analysis incorporating enzyme adoption curves, clean-label reformulation timelines, and cold-chain infrastructure development patterns. Industry-specific inputs span REACH compliance deadlines and school feeding program procurement scale.
Underlying assumptions cover regulatory approval continuity, fruit crop yield stability, and enzyme supply security, with deviation risk concentrated in novel sweetener evaluation delays and logistics infrastructure gaps. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Europe Food Spread Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Mexico Packaged Food Products Market
Packaged Foods
Middle-East and Africa Ready-To-Eat Food Market
Packaged Foods
Instant Cereals Market
Packaged Foods
United States Online Grocery Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Global Dessert Mixes Market
Packaged Foods
Burritos Market
Packaged Foods
India Instant Noodles Market
Packaged Foods
Iran Breakfast Cereals Market
Packaged Foods
Bangladesh Instant Noodles Market
Packaged Foods
Packaged Corn on the Cob Market