
 Global Packed Food Market | 2026-2036
Global Packed Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Packed Food Market Analysis
Clean-label formulation technology is rewriting how manufacturers design ingredient panels and shelf-stable recipes. Nestlé leverages its R&D network to reformulate legacy products with shorter ingredient lists. PepsiCo anchors its portfolio around reduced-sodium and no-artificial-color commitments across snack and beverage divisions. Unilever differentiates through precision fermentation and plant-based preservation systems in its European and Asian production lines.
Global packed food encompasses thermally processed, shelf-stable, or refrigerated edible products sealed in protective packaging to extend safety and sensory stability through controlled atmosphere, aseptic filling, or retort sterilization; these items serve commercial and residential buyers requiring convenience, portion control, and minimal preparation. Ready-to-eat meals command the widest margin pool as urban households trade cooking time for prepared solutions. Snack bars represent the fastest-growing product type as protein-fortified and functional-positioned formats expand in pharmacy and fitness channels. Retort pouches are displacing metal cans in ambient segments due to lighter logistics profiles and microwave compatibility.
The FDA modernizes nutrition labeling and bioengineered disclosure standards while the EU Green Deal drives packaging recyclability mandates and deforestation-free supply chain verification; these frameworks elevate compliance costs but also lock out informal competitors lacking traceability infrastructure. India's FSSAI enforces progressively stricter additive limits and fortification norms for processed staples. Stakeholders must monitor how divergent shelf-life standards between jurisdictions reshape export qualification requirements and regional manufacturing location decisions.
Market Dynamics
Clean-label mandates from the EU Green Deal and FDA modernization are compressing formulation cycles while cold-chain infrastructure investments in India, Brazil, and Indonesia unlock new demand pools for temperature-sensitive formats.
Growth Catalysts
- EU Green Deal packaging recyclability mandates:These rules accelerate retort pouch adoption as manufacturers abandon multi-material laminates for mono-polymer alternatives that simplify end-of-life sorting.
- Urban working households:Dual-income families in São Paulo, Mumbai, and Jakarta trade cooking time for ready-to-eat meals, expanding the highest-margin product category.
- Precision fermentation:This biotechnology enables plant-based preservation systems that replace synthetic additives while maintaining shelf stability.
Market Restraints
- Aluminum and polymer input cost volatility:Metal can and flexible packaging producers face margin compression when commodity resin and sheet aluminum prices spike.
- Cold-chain infrastructure gaps:Last-mile refrigeration deficits in tier-2 Indonesian cities and northern Indian states limit chilled product penetration.
- Deforestation-free supply chain verification:EU Green Deal requirements impose traceability costs that informal competitors cannot absorb, but also burden compliant firms with audit expenses.
Strategic Opportunities
- Pharmacy and fitness channel expansion:Protein-fortified snack bars gain shelf space in drugstore chains and gym retail, bypassing traditional grocery slotting fees.
- India's FSSAI fortification norms:Mandatory micronutrient enrichment in processed staples creates premium positioning for compliant brands.
- Aseptic filling and microwave-compatible retort convergence:Hybrid processing technologies enable ambient-stable meals with fresh-cooked sensory profiles.
Industry Challenges
- Reformulation talent scarcity:Food scientists capable of reducing ingredient counts while preserving shelf life command premium compensation.
- Legacy ERP integration with traceability platforms:Batch-level tracking for EU deforestation compliance requires retrofitting decades-old manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Packed Food Market |
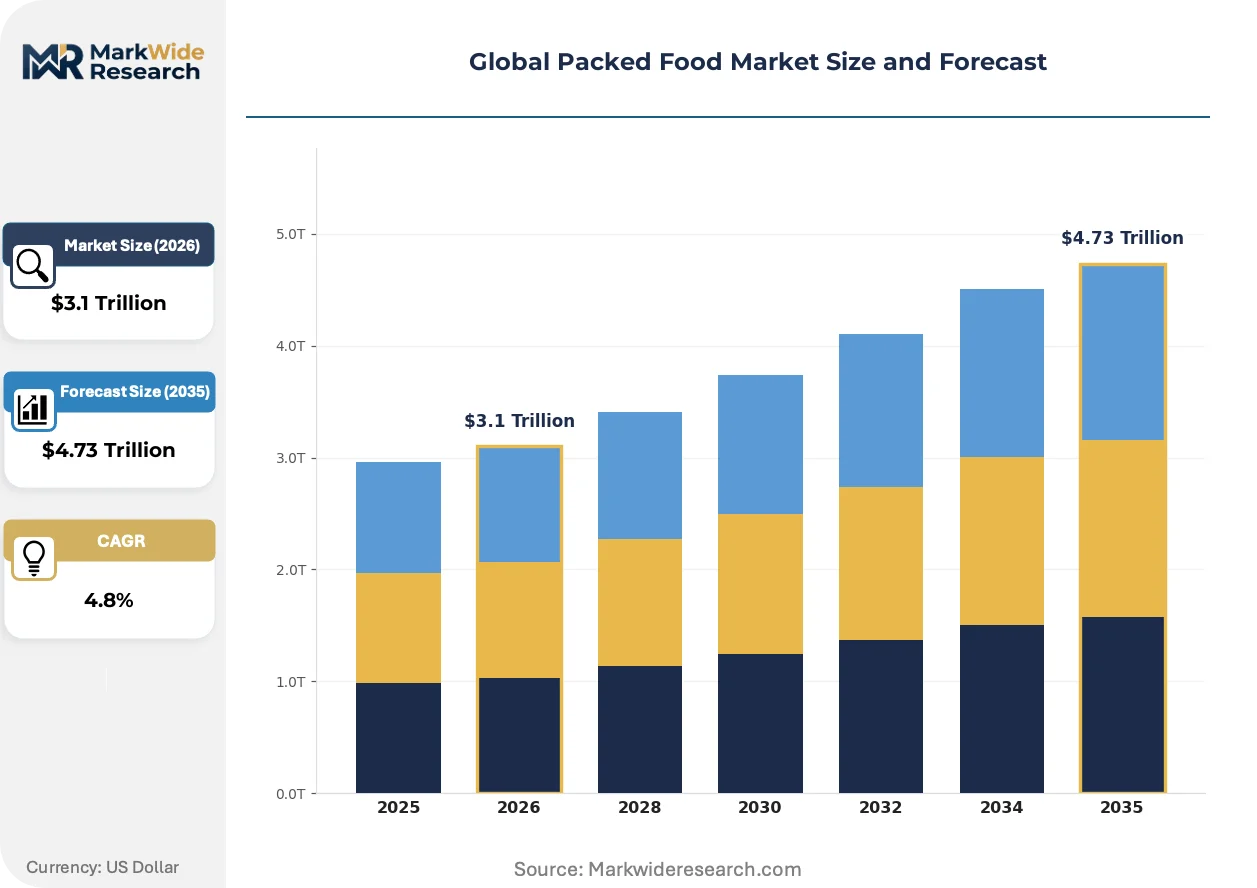
| Market Size in 2026 | $3.1 Trillion |
| Market Size in 2035 | $4.73 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canned Goods, Frozen Meals, Snack Bars, Ready-to-Eat Meals Packaging Type: Retort Pouches, Glass Jars, Plastic Containers, Vacuum-Sealed Bags Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service Outlets Customer Type: Households, Institutional Buyers, Food Manufacturers, Restaurants |
| Companies Covered | Nestlé, PepsiCo, Unilever, Mondelez International, General Mills, Kraft Heinz, Danone, Conagra Brands, Mars, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Packed Food Market Emerging Trajectories
Active and intelligent packaging systems, regulatory disclosure expansions, and channel fragmentation are simultaneously reshaping how products are preserved, labeled, and discovered by buyers.
High-barrier mono-material films are rendering obsolete multi-layer laminates that complicated mechanical recycling streams. European retailers and quick-service chains are accelerating adoption to preempt extended producer responsibility fees. The structural consequence is rendering obsolete legacy converter investments in incompatible extrusion and lamination equipment.
REACH and F-Gas Regulation restrictions on fluorinated compounds are forcing reformulation of grease-resistant coatings for paper-based food packaging. Industrial consequence includes accelerated R&D spending on bio-based barrier treatments. Bakery and fried-snack segments in Germany, France, and the Netherlands are most affected, with suppliers pivoting to polysaccharide and protein-derived alternatives.
Direct-to-pantry subscription models are compressing traditional retail slotting dynamics as urban consumers prioritize convenience over aisle browsing. Meal-kit and auto-replenishment platforms capture working households in London, Singapore, and Toronto. This shift is most visible in the ready-to-eat segment, where brand discovery now originates in algorithmic recommendation engines rather than end-cap displays.
Global Packed Food Market Segmentation
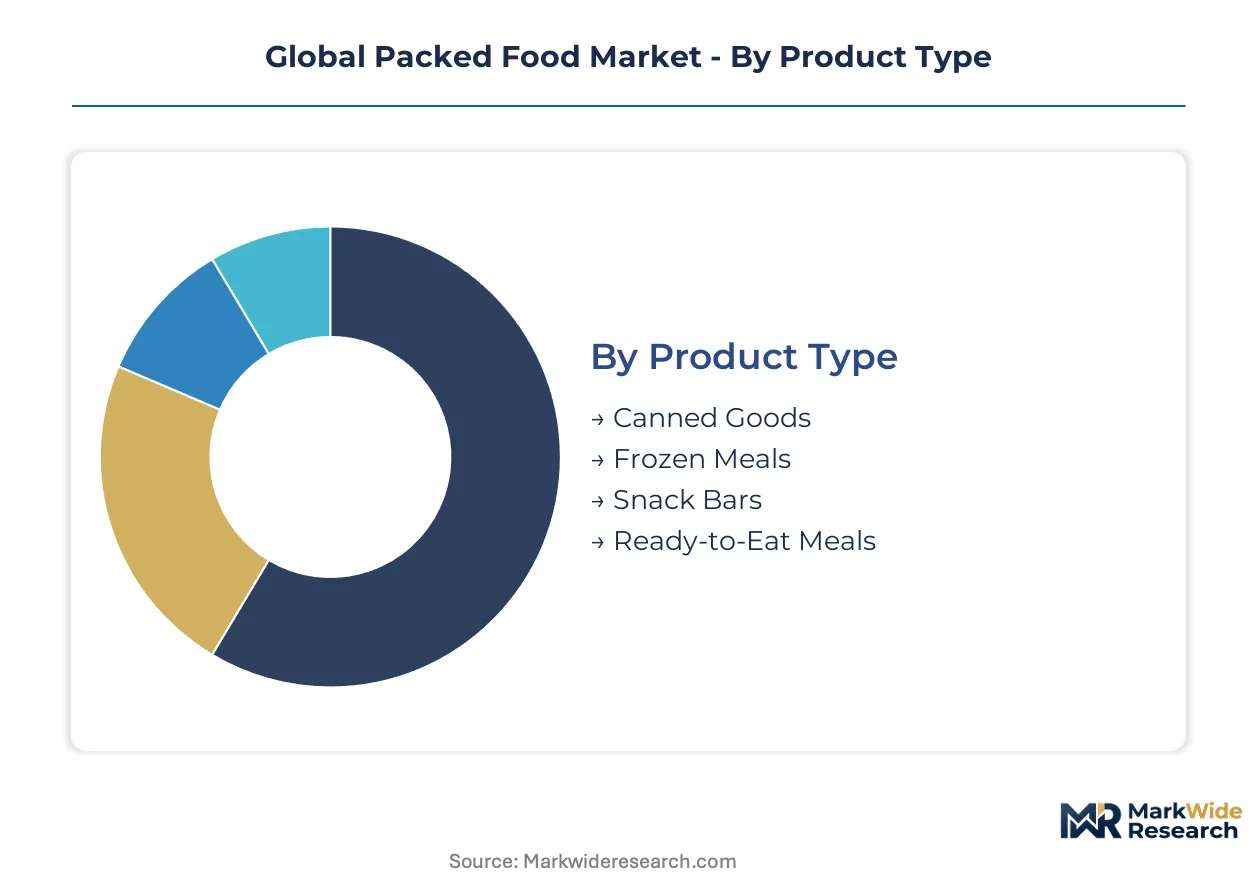
Segmentation in packed food reveals divergent margin structures and inventory velocities across product formats. Manufacturers calibrate production scheduling and cold-chain investments differently for ambient-stable versus temperature-dependent categories.
Product Type:
Cycle times vary dramatically: shelf-stable formats turn inventory monthly while frozen and fresh-prepared segments demand weekly replenishment to maintain sensory quality.
- Ready-to-Eat Meals:Thermally processed or refrigerated dishes requiring zero consumer preparation beyond heating. Urban working households in São Paulo, Mumbai, and Jakarta drive volume as dual-income families trade cooking time for convenience, though cold-chain gaps in tier-2 Indian and Indonesian cities constrain chilled format penetration.
- Snack Bars:Protein-fortified and functional-positioned formats in pharmacy and fitness channels. These items command premium shelf positioning in drugstore chains and gym retail, bypassing traditional grocery slotting fees while expanding fastest among all product types.
- Canned Goods:Metal or retort-pouch preserved vegetables, proteins, and complete meals with ambient stability.
- Frozen Meals:Blast-frozen complete dishes requiring continuous cold-chain maintenance from production through consumption.
Ready-to-Eat Meals anchors the volume base while Snack Bars gains share at the steepest rate.
Packaging Type:
Cost tiers separate legacy formats from next-generation solutions, with material choices directly determining logistics economics and regulatory compliance burdens.
- Retort Pouches:Multi-layer or mono-material flexible films enabling microwave compatibility and lighter shipping profiles. EU Green Deal recyclability mandates accelerate mono-polymer adoption as manufacturers abandon incompatible laminates, with European retailers driving specification changes.
- Plastic Containers:Injection-molded or thermoformed rigid formats for refrigerated and frozen applications. Cold-chain infrastructure investments in Brazil and Indonesia unlock demand for these temperature-dependent formats.
- Glass Jars:Inert barrier packaging for acidic preserves and premium positioned sauces.
- Vacuum-Sealed Bags:Barrier films for modified-atmosphere packaging of proteins and prepared ingredients.
Retort Pouches command the highest margin tier while Plastic Containers expand most quickly in emerging market cold-chain buildouts.
Distribution Channel:
Channel fragmentation is reshaping how buyers discover and replenish packed food, with digital platforms compressing traditional retail slotting dynamics.
- Online Retail:Direct-to-pantry subscription and auto-replenishment platforms. Meal-kit services capture working households in London, Singapore, and Toronto through algorithmic recommendation engines rather than end-cap displays.
- Supermarkets:Traditional multi-format retail with dedicated packaged food aisles and promotional end-cap positioning.
- Convenience Stores:Small-format urban retail emphasizing immediate consumption and single-serve portions.
- Food Service Outlets:Restaurants, cafeterias, and catering operations sourcing packed ingredients for menu assembly.
Supermarkets retain the volume foundation while Online Retail climbs the fastest as subscription models penetrate urban households.
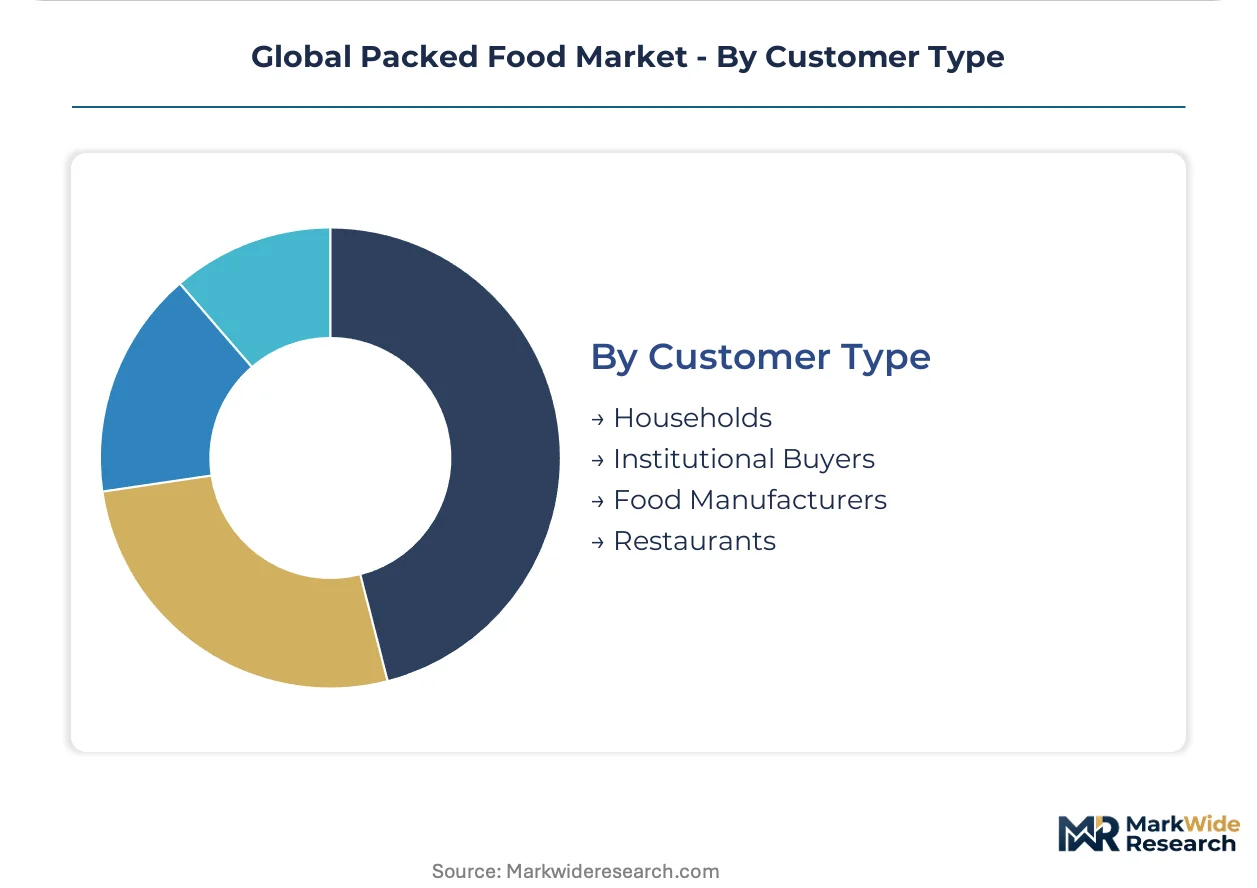
Customer Type:
Procurement patterns diverge sharply between price-sensitive institutional volume buyers and convenience-prioritizing residential consumers.
- Households:Individual and family consumers purchasing through retail channels for home consumption.
- Restaurants:Independent and chain operators sourcing packed ingredients for menu preparation.
- Institutional Buyers:Schools, hospitals, and corporate cafeterias procuring through contracted food service distributors.
- Food Manufacturers:Industrial purchasers integrating packed ingredients into downstream processed products.
Households dominate absolute demand while Restaurants expand most rapidly as labor costs drive kitchen simplification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports processed meat and soy-based ingredients to European and Asian buyers, while cold-chain investments in São Paulo and Minas Gerais unlock domestic demand for chilled ready-to-eat formats.
United States
Urban working households in New York and Los Angeles drive demand for subscription meal kits and protein-fortified snack bars. FDA modernization initiatives tighten bioengineered disclosure standards and nutrition labeling requirements. Chicago anchors Midwest production clusters where manufacturers retrofit legacy ERP systems for batch-level traceability compliance.
Germany
REACH and F-Gas Regulation restrictions force reformulation of grease-resistant coatings for bakery and fried-snack packaging. EU Green Deal packaging recyclability mandates accelerate mono-material retort pouch adoption across Bavaria and North Rhine-Westphalia. Berlin-based retailers preempt extended producer responsibility fees by specifying high-barrier mono-polymer films.
India
Cold-chain infrastructure expansion in Maharashtra and Gujarat enables penetration of refrigerated dairy and prepared meals into tier-2 cities. FSSAI enforces progressively stricter additive limits and mandatory micronutrient fortification in processed staples. Mumbai and Delhi-NCR concentrate demand from dual-income households trading cooking time for convenience.
Indonesia
Last-mile refrigeration buildouts in Java and Sumatra unlock demand for temperature-sensitive formats previously limited to ambient-stable categories. National food safety regulators align additive standards with ASEAN harmonization frameworks. Jakarta and Surabaya concentrate urban working household demand for ready-to-eat meals distributed through convenience store networks.
Japan
Aging demographics and single-person households in Tokyo and Osaka sustain premium positioning for portion-controlled, shelf-stable formats. METI standards on packaging material efficiency drive lightweighting investments in retort pouch specifications. Nagoya industrial clusters specialize in aseptic filling equipment serving export markets across Southeast Asia.
Global Packed Food Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented shelf-space dynamics. The vendor base organizes around three strategic archetypes: diversified multinationals with R&D networks, regional specialists with cold-chain logistics integration, and private-label converters serving retail chains. Dominant competitive moves include portfolio diversification into plant-based preservation systems and geographic expansion through distributor partnerships in emerging cold-chain markets.
Within the diversified multinational tier, Nestlé and PepsiCo exemplify channel-anchored positioning across retail and foodservice vectors. Nestlé occupies a reformulation-focused archetype leveraging precision fermentation capabilities in European and Asian production lines. PepsiCo represents the portfolio-breadth model spanning snack and beverage divisions with reduced-sodium and no-artificial-color commitments. Unilever sits within the sustainability-differentiation cluster through plant-based preservation systems and clean-label formulation technology.
| Leading Market Players |
|---|
| Nestlé |
| PepsiCo |
| Unilever |
| Mondelez International |
| General Mills |
| Kraft Heinz |
| Danone |
| Conagra Brands |
| Mars |
| Others |
Supply Flow & Price Mechanics
Aluminum sheet and polymer resin suppliers in the Gulf Coast and Rotterdam corridors anchor margin capture for flexible packaging converters, with their pricing power cascading downstream to determine profitability tiers across ambient-stable and temperature-sensitive product categories.
Pricing Analysis
Mono-material retort pouch specifications command 15-25% premiums over legacy multi-layer laminates, while standard-grade metal cans trade at commodity spot dynamics and next-generation aseptic carton formats price on functionality. Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-compliant clean-label formulations from conventional recipes and private-label economy tiers. Pricing pressure stems from aluminum and polymer input cost volatility squeezing converter margins. Institutional buyers in hospital and school cafeteria channels exhibit highest price sensitivity, while pharmacy-channel protein-fortified snack bar purchasers show lowest elasticity.
Supply Chain Analysis
Co-packing and contract manufacturing capacity concentrates with Hearthside Food Solutions, TreeHouse Foods, and regional specialists across Wisconsin, Illinois, and the Netherlands. Raw material sourcing draws from Saudi Arabian polymer resin suppliers, Australian aluminum smelters, and Brazilian soy protein processors. Single-source vulnerability in high-barrier mono-material film substrates poses structural risk given limited qualified converter base. Distribution runs through retail grocery slotting systems, direct-to-pantry subscription platforms, and foodservice distributor networks in tiered priority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
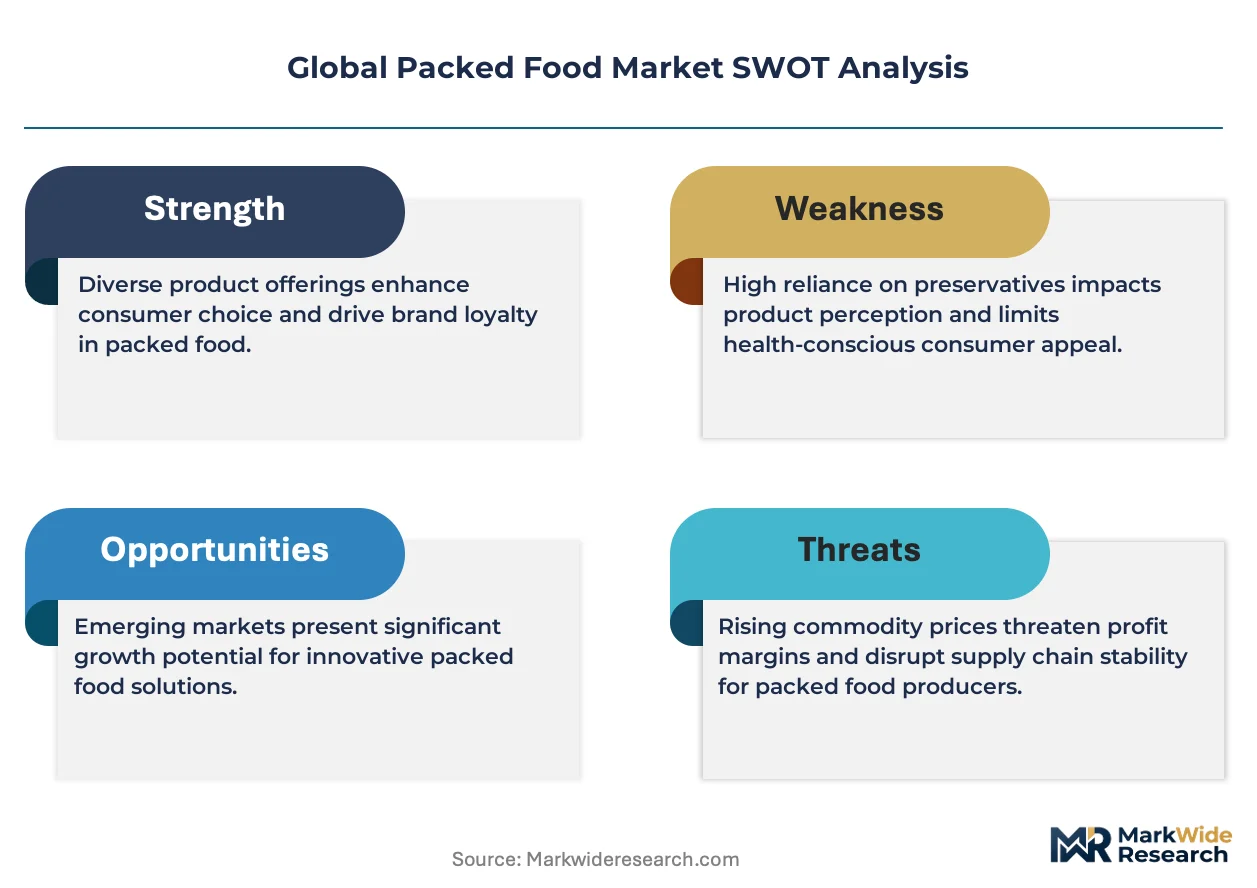
The Global Packed Food Market operates as a regulatory-moat business where EU Green Deal traceability infrastructure and FDA modernization compliance create switching costs that informal competitors cannot replicate.
For Market Incumbents: Entrench defensibility by acquiring precision fermentation capabilities for plant-based preservation systems and retrofitting legacy ERP systems for batch-level EU deforestation compliance. Cold-chain logistics integration in tier-2 Indian and Indonesian cities represents the priority capacity addition. Reformulation talent scarcity demands preemptive compensation structures to retain food scientists capable of clean-label shelf-life extension. For New Entrants and Emerging Players: Northern Indian states and tier-2 Indonesian cities present the most penetrable white-space geography where last-mile refrigeration buildouts lag metropolitan penetration. India's FSSAI-mandated micronutrient fortification creates premium positioning entry for compliant brands. Pharmacy and fitness channel distribution bypasses traditional grocery slotting fee barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed co-packing specialists holding regional cold-chain integration but lacking clean-label R&D capabilities. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Watch for EU extended producer responsibility fee implementation as margin compression signal triggering consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | EU Green Deal compliance locks out informal competitors lacking traceability infrastructure. |
| Mono-Material Retort Pouch Conversion | REACH and F-Gas Regulation restrictions accelerate R&D spending on bio-based barrier treatments. |
| Cold-Chain Infrastructure Expansion | Temperature-sensitive format penetration in Maharashtra and Gujarat unlocks tier-2 demand pools. |
| Precision Fermentation Capability Acquisition | Plant-based preservation systems replace synthetic additives while maintaining shelf stability. |
| Direct-to-Pantry Subscription Launch | Algorithmic recommendation engines in London and Singapore compress traditional retail slotting dynamics. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with R&D directors at diversified multinationals, category buyers at European retailers, co-packing operations managers, and cold-chain logistics specialists. Secondary validation drew from FDA nutrition labeling guidance documents, EU Green Deal regulatory texts, FSSAI fortification notifications, customs records for aluminum and polymer trade flows, and Nielsen retail audit data. Bottom-up SKU-level volume builds were triangulated against top-down macroeconomic consumption models.
Calibration against historical price elasticities and channel shift patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format stability requirements, packaging material recyclability tiers, distribution channel digital penetration, and regional cold-chain maturity. CAGRs were derived from trend extrapolation adjusted for regulatory implementation timelines. Industry-specific inputs incorporated EU extended producer responsibility fee schedules and India's FSSAI additive limit phase-ins.
Practitioners should monitor aluminum and polymer commodity price volatility, EU deforestation audit enforcement intensity, and tier-2 city cold-chain completion rates for early signals of forecast revision. Quarterly review of these named indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Pastry Fillings Market
Packaged Foods
China Packaged Food Products Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Morning Goods Market
Packaged Foods
Packaged Food Market
Packaged Foods
Packaged Sprouts Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Global Gluten-Free Breakfast Cereals Market
Packaged Foods
Canned Pasta Market
Packaged Foods
Packaged Currants Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Mexico Packaged Food Products Market