
 Burritos Market | 2026-2036
Burritos Market Size, Share, and Industry Trends Forecast 2026-2036
Burritos Market Analysis
Foodservice operators is pivoting toward customized assembly-line formats that let diners select proteins, salsas, and dietary accommodations. Chipotle Mexican Grill leverages its digital kitchen infrastructure to sustain throughput during peak hours. Taco Bell anchors its value proposition through craveable limited-time offerings that rotate seasonally. Qdoba Mexican Eats differentiates through free guacamole and queso policies that reduce perceived add-on friction.
A burrito consists of a flour tortilla wrapped around a filling of proteins, rice, beans, cheese, and sauces, with specifications ranging from eight-inch snack sizes to fourteen-inch meal formats engineered for handheld consumption. The product serves as a portable, customizable meal solution across quick-service restaurants, convenience retail, and frozen grocery channels. Beef and chicken variants occupy the largest volume pools within product type segmentation, while vegetarian formulations are capturing the fastest growth trajectory among health-conscious end users. Supermarkets and restaurants dominate distribution channel throughput, though online stores represent the most rapidly expanding access point for frozen and ready-to-heat formats.
FDA nutrition labeling requirements and USDA organic certification standards shape ingredient sourcing and clean-label formulation priorities across domestic manufacturers. State-level health department grading systems in California, Texas, and New York enforce food safety protocols that influence kitchen design and supply chain documentation. Stakeholders must monitor evolving allergen disclosure mandates and plant-based protein labeling guidelines that will determine competitive eligibility in retail and foodservice procurement cycles.
Market Dynamics
Meal occasion fragmentation is compressing traditional daypart boundaries across foodservice, forcing operators to engineer portable formats that satisfy breakfast, snacking, and late-night demand within single production lines.
Growth Catalysts
- USDA Organic Certification:Clean-label positioning unlocks premium shelf placement in retail freezer aisles and drives reformulation toward shorter ingredient decks.
- Digital kitchen infrastructure:Assembly-line restaurants deploy predictive prep algorithms that synchronize protein thawing with demand curves, reducing waste and throughput bottlenecks.
- Plant-based protein innovation:Textured pea and mycelium alternatives expand addressable vegetarian and flexitarian cohorts without requiring dedicated cooking equipment.
Market Restraints
- Flour tortilla input volatility:Wheat futures and freight energy costs transmit directly to margin compression for frozen retail manufacturers.
- California supply concentration:Central Valley produce sourcing creates climate-exposure vulnerability for salsa and vegetable filling supply chains.
- FDA allergen disclosure mandates:Label redesign cycles and cross-contamination protocols extend new product launch timelines by four to six months.
Strategic Opportunities
- Convenience retail channel expansion:C-store chains seek hot-hold burrito programs to capture commuter breakfast occasions.
- Dual carbon goals alignment:China SAMR green manufacturing incentives reward facilities that deploy renewable thermal energy in tortilla production.
- Direct-to-consumer frozen subscription:Regional brands bypass distributor markups through controlled cold-chain delivery to household freezers.
Industry Challenges
- Line cook labor scarcity:High-turnover kitchen roles complicate consistency execution in made-to-order assembly formats.
- Multi-jurisdiction labeling compliance:State-level sodium disclosure laws in New York and California force SKU proliferation or lowest-common-denominator formulation.
- Cold-chain integrity maintenance:Frozen retail distribution requires uninterrupted temperature logging that smaller operators struggle to document.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Burritos Market |
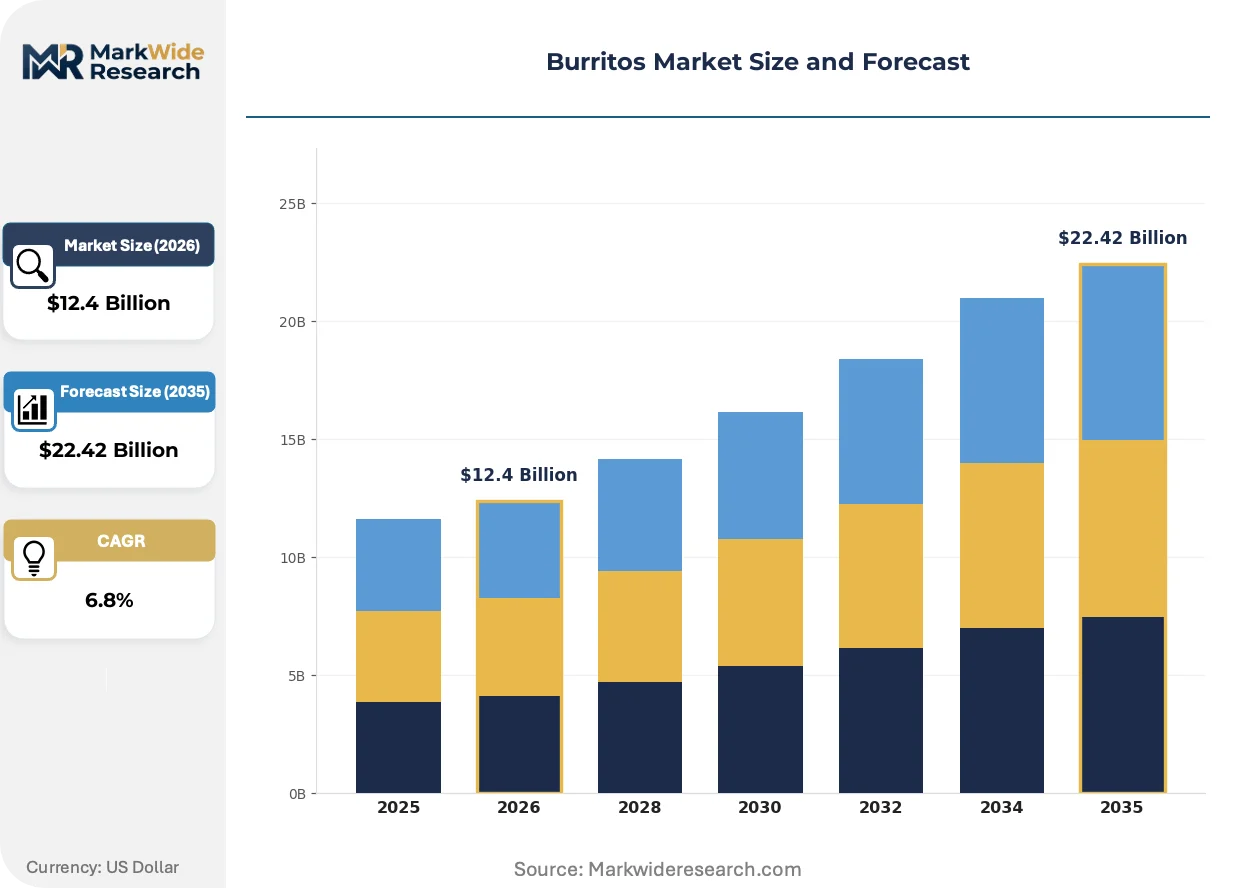
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetarian, Chicken, Beef, Pork Distribution Channel: Supermarkets, Food Trucks, Restaurants, Online Stores Price Tier: Premium, Mid-range, Budget, Discount End User: Students, Families, Professionals, Health Conscious |
| Companies Covered | Chipotle Mexican Grill, Taco Bell, Qdoba Mexican Eats, Moe's Southwest Grill, Del Taco, Amy's Kitchen, Freebirds World Burrito, Pancheros Mexican Grill, Ruiz Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Burritos Market Emerging Trajectories
Automation and dietary specification are converging to redefine how burritos are assembled, distributed, and consumed across every channel from quick-service counters to home freezers.
Robotic tortilla pressing and filling deposition systems are overtaking manual assembly in high-volume quick-service environments. Chipotle and regional chains deploy these systems during peak hours to maintain throughput without expanding headcount. Labor cost compression and portion consistency gains are accelerating capital deployment across the sector.
REACH chemical safety standards in Europe are tightening scrutiny on food-contact packaging materials used for frozen retail wraps. Manufacturers face reformulation pressure to eliminate per- and polyfluoroalkyl substances from microwaveable sleeve coatings. German and French retail buyers now require third-party certification as a procurement gate.
Breakfast protein preferences are rotating toward handheld formats that merge morning convenience with afternoon satiety. Quick-service operators capture commuter traffic through drive-thru and mobile order-ahead channels that bypass traditional dining room bottlenecks. Texas and Florida metropolitan corridors exhibit the strongest volume migration toward morning burrito occasions.
Burritos Market Segmentation
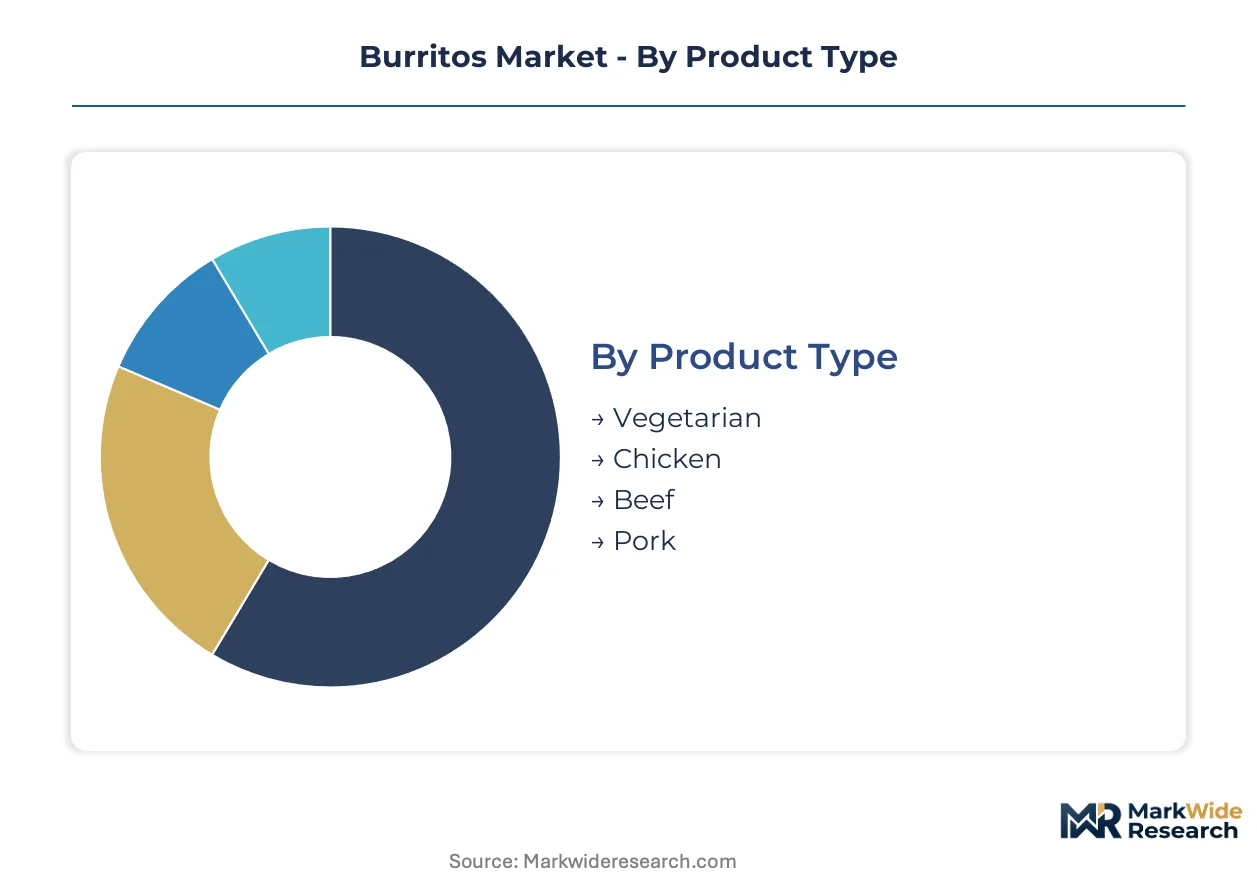
Segmentation in the burritos market reveals how protein preferences, purchase occasions, and price sensitivity split demand across divergent production and distribution strategies. Understanding these fault lines allows operators to align kitchen capacity, ingredient procurement, and channel investments with actual buyer behavior rather than assumed homogeneity.
Product Type:
Protein choice drives kitchen equipment configuration, supplier relationships, and margin structure more than any other product decision.
- Beef:Ground chuck and seasoned steak fillings dominate volume in quick-service and frozen retail channels. USDA grading standards for beef quality create tiered sourcing tiers that ripple through price positioning. Demand concentrates in Texas, Arizona, and California where regional seasoning traditions anchor brand loyalty.
- Chicken:White-meat strips and shredded dark meat offer the most flexible cost structure across commodity cycles. Quick-service chains deploy chicken as the default protein in breakfast burrito programs to minimize cross-contamination protocols with red meat. Volume clusters in southeastern states with integrated poultry processing infrastructure.
- Vegetarian:Black bean, pinto, and roasted vegetable formulations reduce exposure to protein commodity volatility. Plant-based analogs from textured pea and mycelium sources are gaining refrigerated case placement in urban supermarkets.
- Pork:Carnitas and al pastor styles carry higher labor intensity for slow-cooking preparation. Regional chains in the Southwest and Florida maintain dedicated pork programs that differentiate from national competitors.
Volume sits with beef and chicken; growth tilts toward vegetarian formulations as flexitarian dietary patterns expand.
Distribution Channel:
Channel selection determines temperature control requirements, packaging formats, and the balance between impulse and planned purchase behavior.
- Restaurants:Full-service and quick-service operators capture the highest per-transaction values through customization and beverage attachment. Assembly-line formats in Chipotle and Qdoba generate throughput that frozen retail cannot replicate. Labor scarcity in kitchen roles constrains expansion velocity in secondary markets.
- Supermarkets:Frozen and refrigerated cases offer the broadest geographic reach for regional brands without proprietary store networks. Retail buyers demand four-to-six month lead times for shelf resets that align with seasonal promotional calendars.
- Online Stores:Direct-to-consumer frozen subscription models bypass distributor markups through controlled cold-chain logistics. Customer acquisition costs remain elevated compared to impulse channels.
- Food Trucks:Mobile operations capture lunch and late-night occasions with lower fixed overhead than brick-and-mortar locations. Permit density restrictions in municipal jurisdictions limit fleet scaling.
Throughput concentrates in restaurants; channel expansion tilts most steeply toward online stores as cold-chain logistics mature.
Price Tier:
Price positioning signals ingredient provenance, portion architecture, and the trade-off between convenience and experiential value.
- Premium:Grass-fed beef, organic certification, and heritage grain tortillas command shelf-space allowances in Whole Foods and regional natural grocers. Price elasticity remains lowest among health-conscious and environmentally motivated cohorts.
- Mid-range:Conventional quick-service pricing anchors the competitive set for most chains. Value engineering focuses on protein portion consistency rather than ingredient provenance upgrades.
- Budget:Frozen multi-packs and value-menu items at national chains capture price-sensitive households and student segments. Margin compression requires volume throughput or vertical integration into tortilla production.
- Discount:Close-dated frozen inventory and promotional bundles move excess production without damaging core brand positioning. Channel conflict risks emerge when discount tiers appear in overlapping geography with mid-range offerings.
Revenue concentrates in mid-range; premium positioning climbs fastest as clean-label certification expands retail placement.
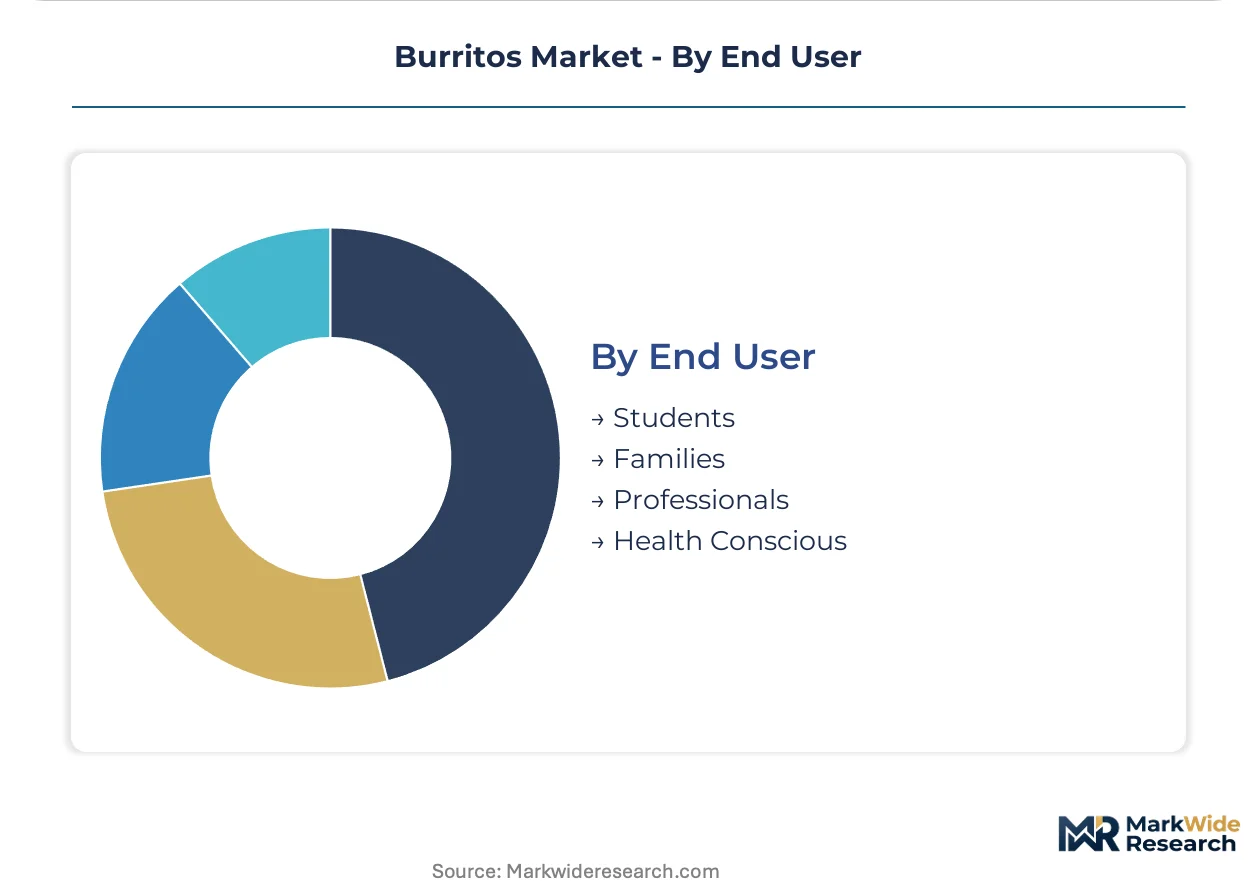
End User:
User archetypes dictate daypart targeting, nutritional messaging, and the relative priority of speed versus customization.
- Families:Multi-person combo meals and shareable formats drive weekend volume in suburban locations. Kids' menu integration determines repeat visit frequency.
- Professionals:Mobile order-ahead and grab-and-go breakfast burritos capture commuter occasions in business districts. Speed of service outweighs customization depth for this cohort.
- Students:Late-night hours and value pricing align with campus-adjacent locations. Digital-native ordering expectations require robust app infrastructure.
- Health Conscious:Macro-friendly bowls and low-carb tortilla alternatives command premium pricing with lower absolute volume. Nutrition transparency requirements exceed standard FDA labeling.
Transaction frequency sits with families; per-visit spending expands most quickly among health-conscious users seeking functional nutrition claims.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maquiladora zones along the US-Mexico border concentrate tortilla production capacity for cross-border supply chains. Tax incentives in these special economic zones attract frozen food manufacturers seeking duty-efficient export routes into US retail channels.
United States
Breakfast burrito demand surges in Texas and Florida metropolitan corridors where commuter traffic patterns favor drive-thru formats. FDA nutrition labeling requirements and USDA organic certification programs shape ingredient sourcing decisions for national retail brands. The Central Valley in California anchors salsa and vegetable filling supply chains, though climate exposure creates vulnerability for fresh produce inputs.
Mexico
Traditional corn and flour tortilla production clusters in Guadalajara and Monterrey supply both domestic consumption and US export markets. Mexico's Secretariat of Economy oversees maquiladora program incentives that reduce tariff exposure for frozen burrito manufacturers. Baja California assembly plants specialize in value-added frozen formats for California retail distribution.
Canada
Health Canada and the Canadian Food Inspection Agency enforce bilingual labeling requirements that extend product launch timelines for US exporters. Toronto and Vancouver metropolitan areas concentrate quick-service burrito expansion as chains test cold-climate operational protocols. Prairie province wheat production supplies tortilla flour inputs with lower freight exposure than US Midwest alternatives.
United Kingdom
London and Manchester drive quick-service adoption of Mexican formats among urban professional cohorts seeking portable lunch solutions. EFSA allergen disclosure standards and REACH chemical safety regulations for food-contact packaging shape frozen retail entry requirements. British Retail Consortium certification gates supermarket freezer placement for imported frozen burrito brands.
Germany
Berlin and Munich anchor the strongest Central European demand for plant-based burrito formulations aligned with flexitarian dietary trends. ECHA enforcement of REACH standards on microwaveable sleeve coatings forces reformulation of frozen retail packaging. Bavarian food processing clusters experiment with mycelium protein alternatives for vegetarian filling production.
Burritos Market Vendor Landscape
Top-tier vendors anchor national quick-service scale, while regional specialists and frozen retail manufacturers occupy differentiated tiers beneath. The competitive structure splits between assembly-line restaurant chains, legacy frozen food conglomerates, and emerging direct-to-consumer brands. Three archetypes dominate: vertically integrated tortilla producers, digital-native subscription services, and co-manufacturing-dependent regional labels. Consolidation pressure manifests through strategic acquisitions of regional chains and backward integration into captive tortilla production.
Within the quick-service tier, Chipotle Mexican Grill and Taco Bell exemplify divergent scale strategies, while Qdoba Mexican Eats occupies a position between premium positioning and value accessibility. Amy's Kitchen and Ruiz Foods anchor the frozen retail segment as representatives of clean-label and conventional mass-market archetypes respectively. These five entities collectively illustrate how protein sourcing flexibility, digital kitchen infrastructure, and channel-specific packaging requirements separate competitive positions across foodservice and retail environments.
| Leading Market Players |
|---|
| Chipotle Mexican Grill |
| Taco Bell |
| Qdoba Mexican Eats |
| Moe's Southwest Grill |
| Del Taco |
| Amy's Kitchen |
| Freebirds World Burrito |
| Pancheros Mexican Grill |
| Ruiz Foods |
| Others |
Supply Flow & Price Mechanics
Wheat futures volatility cascades through tortilla production costs into three-tier pricing structure across premium, standard, and economy levels for frozen retail burritos. Cost compression in budget tiers intensifies because flour input exposure transmits directly to margin structure without hedging mechanisms available to smaller operators.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement relationships, with premium positioning attached to four-to-six month shelf reset cycles and spot inventory clearing through discount channels. Pricing stratifies across premium, standard, and economy tiers based on USDA organic certification status and protein provenance grade. Price erosion runs through budget frozen multi-packs as private-label alternatives expand shelf presence. Students and price-sensitive households exhibit highest elasticity, while health-conscious buyers accept premium positioning for clean-label claims.
Supply Chain Analysis
Single-source vulnerability sits with Central Valley produce concentration for salsa and vegetable fillings, creating climate-exposure risk that ripples through national retail distribution networks. Tortilla flour draws from Kansas and Oklahoma wheat belts, with mycelium and textured pea proteins sourcing from Bavarian processing clusters and Midwest fermentation facilities. Tariff exposure through maquiladora zones complicates cross-border frozen format economics. Distribution runs through refrigerated third-party logistics networks serving supermarket freezer aisles and direct-to-consumer cold-chain subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The burritos market reads as a consolidation play where FDA allergen disclosure mandates and four-to-six month label redesign cycles force subscale frozen manufacturers toward exit or acquisition.
For Market Incumbents: Extend digital kitchen infrastructure investments to sustain throughput without headcount expansion in peak hour conditions. Secure backward integration into captive tortilla production to buffer wheat futures volatility and defend margin structure against private-label encroachment in frozen retail channels. For New Entrants and Emerging Players: Convenience retail channel partners represent the most penetrable entry vector for hot-hold breakfast burrito programs targeting commuter traffic in Texas and Florida metropolitan corridors. White-space concentration sits with direct-to-consumer frozen subscriptions that bypass distributor markups through controlled cold-chain logistics to household freezers. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional frozen brands with USDA organic certification and established supermarket shelf placement in secondary US markets. Long-term viability hinges on five-to-ten year positioning for plant-based protein transition. Monitor mycelium protein cost curves as inflection indicator for vegetarian formulation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tortilla Production | In-house flour milling buffers wheat futures exposure and compresses unit costs for frozen retail manufacturers. |
| Digital Kitchen Infrastructure Deployment | Predictive prep algorithms at Chipotle synchronize protein thawing with demand curves to reduce waste. |
| Plant-Based Protein Formulation Investment | Mycelium alternatives from Bavarian clusters expand addressable vegetarian cohorts without dedicated cooking equipment. |
| Direct-to-Consumer Subscription Launch | Controlled cold-chain delivery bypasses distributor markups and captures household freezer placement. |
| Convenience Retail Channel Expansion | C-store hot-hold programs capture commuter breakfast occasions in Texas and Florida drive-thru corridors. |
Methodological Framework
Multi-period observation of wheat futures, protein commodity indices, and frozen retail velocity data anchored the trend analysis, supplemented by interviews with quick-service operations directors, frozen food category buyers at supermarket chains, tortilla plant managers, and USDA certification specialists. Secondary validation drew from FDA labeling guidance documents, USDA organic program statistics, refrigerated logistics trade data, and SEC filings of publicly traded restaurant chains. Bottom-up channel volume estimates triangulated against top-down consumer expenditure patterns.
Segment-weighting approaches distributed value and volume across protein type, distribution channel, price tier, and end-user archetype dimensions throughout the forecast period. CAGRs were derived from trend extrapolation moderated by elasticity assumptions for price-tier migration and channel shift dynamics. Industry-specific inputs included breakfast occasion penetration rates in metropolitan corridors and cold-chain logistics maturity indices for direct-to-consumer fulfillment.
Caveats apply where FDA allergen disclosure mandate enforcement timelines or California Central Valley climate events could materially shift the outlook for fresh produce input availability and new product launch cadence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
North America Ready Meals Market
Packaged Foods
Injectable Cocoa Fillings Market
Packaged Foods
Canned Food Market
Packaged Foods
Asia-Pacific Ready Meals Market
Packaged Foods
Packaged Vegan Foods Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Ready-To-Eat Food Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Wet Pet Food Market
Packaged Foods
Alginate Casings Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
North America Chewing Gum Market
Packaged Foods
Instant Soup Market
Packaged Foods
Reduced Salt Packaged Foods Market