
 Convenience Food Market | 2026-2036
Convenience Food Market Size, Share, and Industry Trends Forecast 2026-2036
Convenience Food Market Analysis
A capital-intensity divergence between multinational processors and regional co-packers is bifurcating the competitive landscape. Nestlé S.A. leverages its freeze-drying infrastructure across European and Asian plants to control input costs on frozen meals. General Mills Inc. anchors its position through proprietary microwave-steam technology in single-serve bowls. Hormel Foods Corporation specializes in shelf-stable protein formats that bypass cold-chain dependencies in rural distribution.
Convenience food comprises industrially prepared, partially or fully cooked products requiring minimal consumer preparation beyond heating or direct consumption, typically formulated with preservatives, emulsifiers, and modified starches to achieve shelf stability or frozen durability. These products serve commercial and residential buyers seeking time reduction in meal preparation without fully outsourcing food service. Frozen meals occupy the largest margin pool due to premium pricing on health-positioned lines, while instant noodles compete primarily on volume throughput in emerging markets. Packaged snacks sustain the fastest structural expansion as portable formats penetrate office and transit consumption occasions.
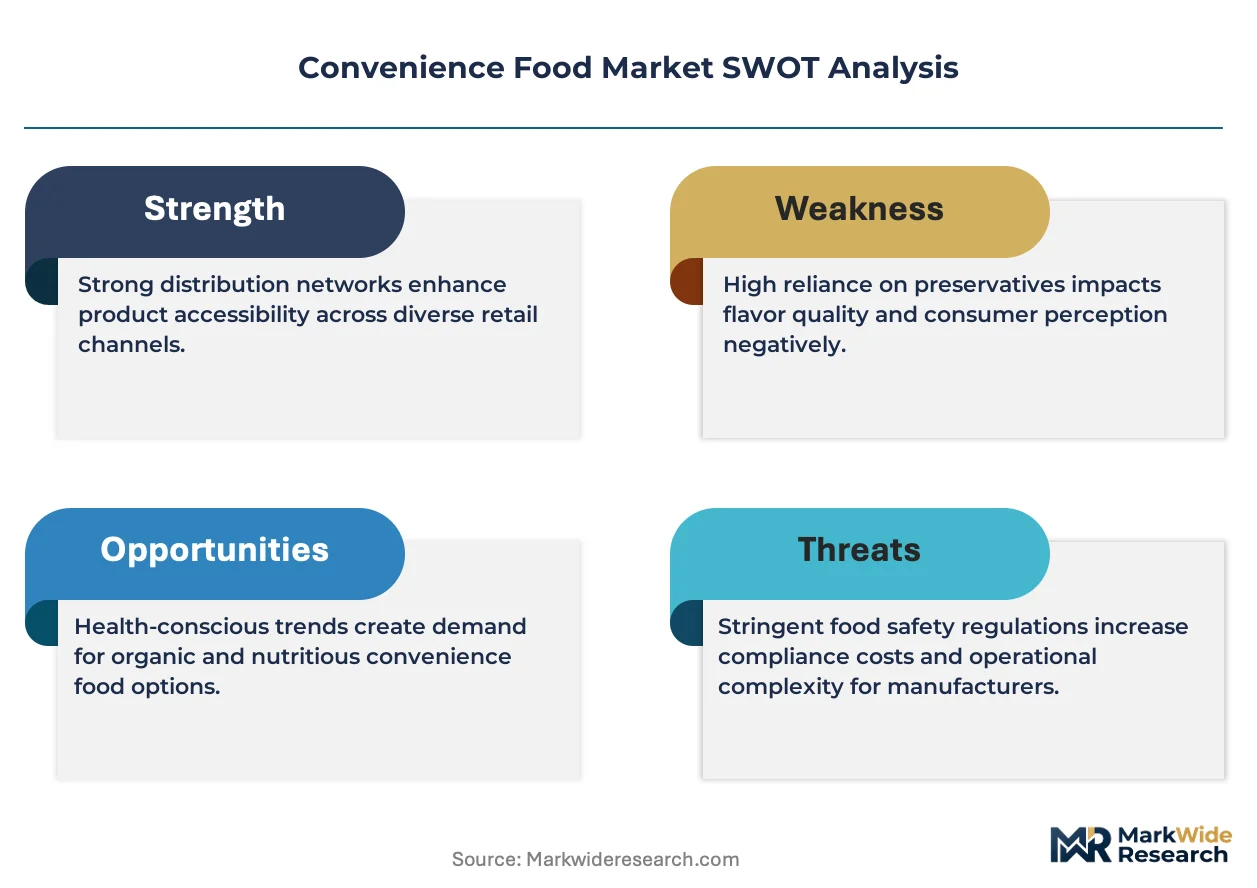
The FDA governs nutritional labeling and GRAS substance approvals for US-manufactured convenience foods, while the EU Green Deal and REACH framework restrict certain food-contact chemicals and mandate recyclability targets. EFSA evaluations on ultra-processed food classifications are reshaping formulation strategies across exporters serving European retail banners. Stakeholders must monitor evolving front-of-pack warning label regimes and calibrate portfolio exposure between premium health-positioned lines and value-tier staples.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing formulation timelines as manufacturers scramble to replace multi-layer laminates with mono-material alternatives before recyclability mandates take full effect.
Growth Catalysts
- Dual-income household expansion:Urban wage earners in India and Brazil are displacing scratch cooking with ready-to-eat formats as modern retail penetrates tier-two cities.
- Freeze-drying infrastructure:Capital deployment into European and Asian processing plants is reducing input cost volatility on frozen meal lines.
- FSSAI fortification mandates:India's micronutrient enrichment requirements for packaged foods are pulling reformulation investment toward health-positioned SKUs.
Market Restraints
- Palm oil price volatility:Input cost swings for emulsifier and fat sources are squeezing margin pools on instant noodle and snack formats.
- Cold-chain gaps:Rural distribution in sub-Saharan Africa and South Asia limits frozen meal penetration to urban corridors.
- EFSA ultra-processed classifications:Front-of-pack warning regimes under evaluation threaten volume throughput on preservative-dependent categories.
Strategic Opportunities
- Microwave-steam convergence:Single-serve bowl formats combining pressure-cooking physics with shelf-stable packaging are opening transit and office consumption occasions.
- PLI scheme tailwinds:India's production-linked incentives for food processing equipment are lowering capex barriers for regional co-packers.
- Direct-to-institutional channels:Healthcare and corporate cafeteria procurement bypassing traditional wholesale layers is concentrating volume with contract manufacturers.
Industry Challenges
- Reformulation talent scarcity:Food chemists capable of replacing modified starches with clean-label alternatives command premium compensation in European markets.
- Legacy asset stranding:Multi-layer packaging lines face accelerated depreciation as REACH-compliant mono-material investments absorb available capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Convenience Food Market |
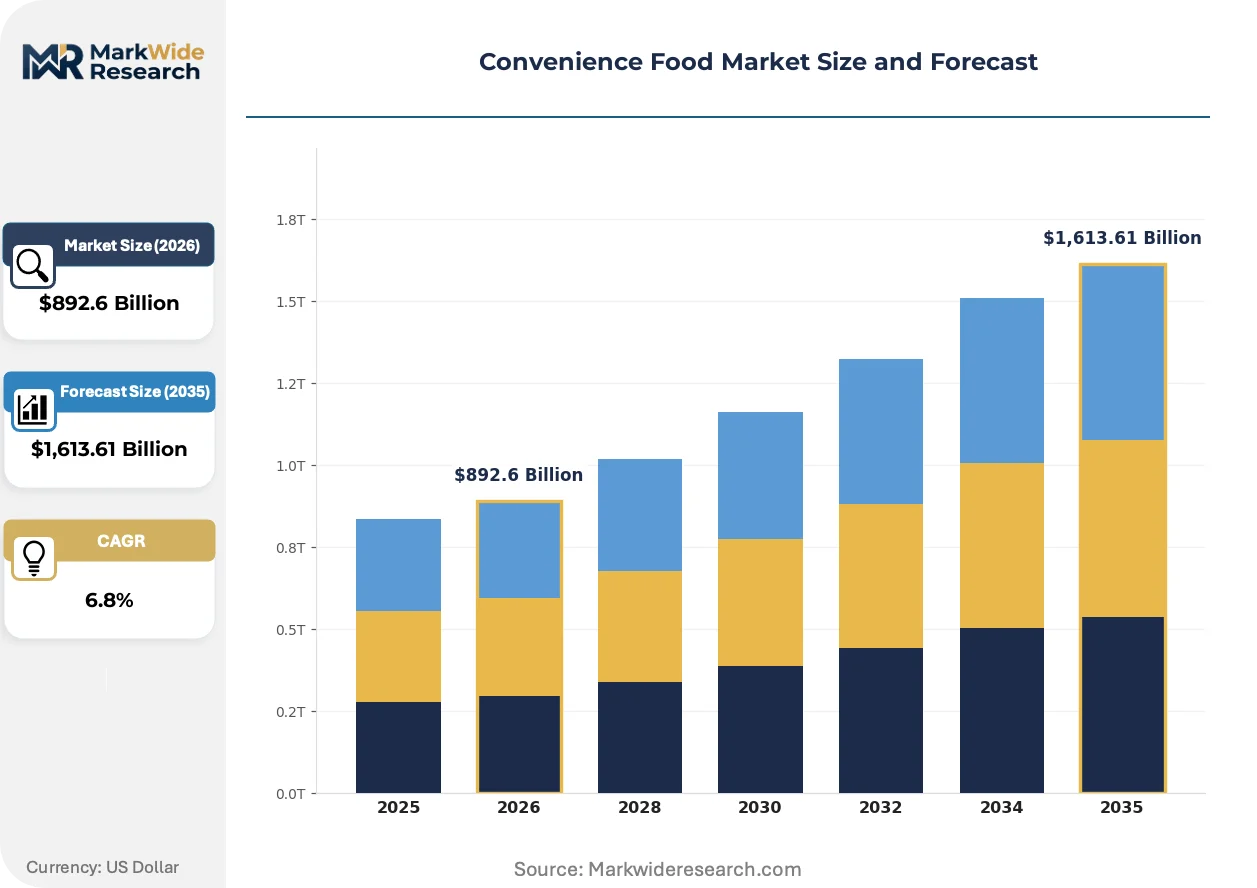
| Market Size in 2026 | $892.6 Billion |
| Market Size in 2035 | $1,613.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Meals, Ready-to-Eat Soups, Packaged Snacks, Instant Noodles Packaging Type: Single-Serve Packs, Family Packs, Recyclable Containers, Microwavable Trays End User: Busy Professionals, Students, Families, Seniors Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Wholesale Distributors |
| Companies Covered | The Kraft Heinz Company, Unilever, Nestlé S.A., 7-Eleven, Inc., B&G Foods, Inc., General Mills Inc., Hormel Foods Corporation, Alimentation Couche-Tard Inc., Conagra Brands, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Convenience Food Market Emerging Trajectories
Active and intelligent packaging systems are compressing spoilage windows while generating consumption data, reshaping how manufacturers align production with actual demand signals rather than forecast-driven batch sizes.
Modified atmosphere packaging with embedded oxygen scavengers is miniaturizing shelf-life extension from bulk industrial formats into individual retail units. Convenience food brands serving Japanese convenience store channels are adopting these systems fastest, with seven-eleven Japan and Lawson compressing replenishment cycles to sub-24-hour turns. The technology is miniaturizing cold-chain requirements for protein-heavy formats, enabling ambient distribution in Southeast Asian markets previously blocked by spoilage risk.
REACH restrictions on per- and polyfluoroalkyl substances in food-contact materials are forcing laminate suppliers to validate fluorine-free barrier coatings by 2025. European exporters serving German and French retail banners are accelerating qualification timelines to maintain shelf placement. Frozen meal categories with high fat content face the steepest reformulation curves as grease resistance without PFAS becomes the binding constraint.
Subscription-based meal kit procurement is fragmenting volume away from traditional retail grocery, with South Korean and Australian urban consumers leading the shift. Direct-to-consumer platforms are displacing supermarket center-store placement as the primary discovery mechanism for new convenience food brands. This pattern is most visible in Seoul and Sydney, where delivery app penetration has compressed brand loyalty cycles to single-purchase trial windows.
Convenience Food Market Segmentation
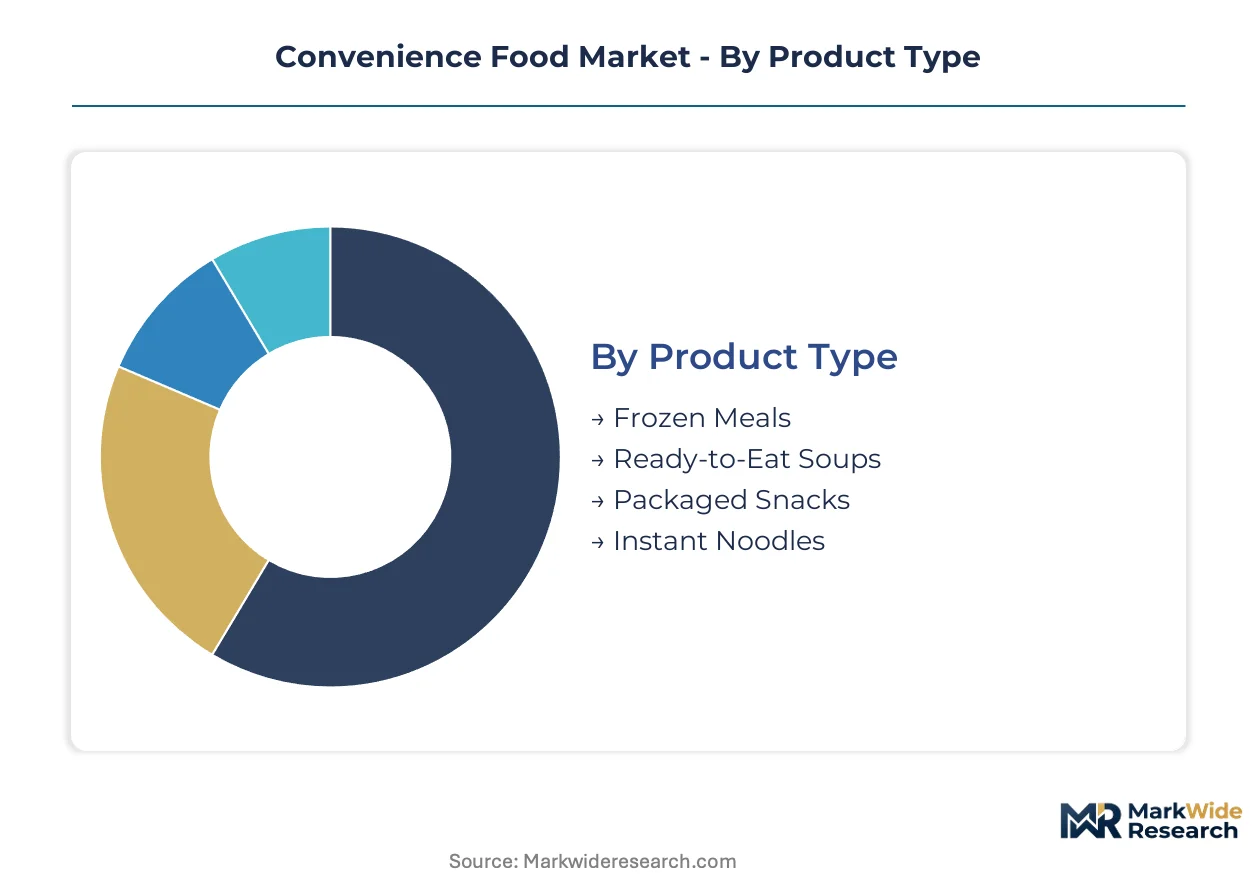
Convenience food manufacturers calibrate portfolio allocation across four intersecting dimensions. Product type determines capital intensity and cold-chain requirements. Packaging format governs regulatory compliance timelines under EU Green Deal mandates. End-user targeting shapes flavor positioning and price architecture. Distribution channel selection dictates margin capture and replenishment velocity.
Product Type:
Ready-to-eat soups face the most acute substitution pressure from foodservice delivery aggregators, while instant noodles compete against street-vendor pricing in emerging markets.
- Frozen Meals:Protein-centric formulations with modified atmosphere packaging dominate premium positioning in Japanese convenience store channels. Demand concentrates among dual-income households in Seoul and Mumbai where freezer penetration supports weekly stock-up behavior. EFSA ultra-processed classifications threaten margin pools on preservative-dependent lines.
- Ready-to-Eat Soups:Retort-pouched and aseptic-carton formats bypass cold-chain infrastructure in Southeast Asian distribution. Volume clusters in Thai and Vietnamese urban corridors where ambient storage tolerances expand retail placement. Swiggy and GrabFood delivery subsidies compress price premiums versus foodservice alternatives.
- Packaged Snacks:Extruded and baked formats with clean-label positioning penetrate office and transit consumption in São Paulo and Mexico City.
- Instant Noodles:Palm oil emulsifier dependence exposes margin volatility; fortification mandates from FSSAI pull reformulation toward micronutrient-enriched SKUs in Indian distribution.
Frozen meals retain volume leadership; packaged snacks hold the steepest expansion curve.
Packaging Type:
Cost tier differentiation separates premium mono-material investments from legacy multi-layer laminate depreciation.
- Single-Serve Packs:Portion-controlled formats with embedded oxygen scavengers enable sub-24-hour replenishment cycles in Lawson and 7-Eleven Japan channels. Demand concentrates among solo-dwelling professionals in Tokyo and Osaka where refrigerator capacity constraints favor just-in-time purchasing.
- Family Packs:Multi-portion configurations with resealable closures target weekly meal planning in suburban Australian and Canadian households. Volume clusters in Costco and Woolworths hypermarket formats where price-per-gram metrics dominate selection.
- Recyclable Containers:Mono-material polypropylene and paperboard alternatives absorb capital reallocation as REACH deadlines eliminate fluorinated barrier coatings.
- Microwavable Trays:Susceptor-equipped designs concentrate in North American frozen breakfast and entree categories where preparation speed overrides packaging cost.
Single-serve packs dominate urban throughput; recyclable containers face the steepest compliance-driven investment curve.
End User:
Application occasion determines formulation architecture and channel placement strategy.
- Busy Professionals:Shelf-stable protein bowls and microwave-steam formats penetrate office pantry procurement in Singapore and Sydney corporate towers. Demand concentrates among 25-40 age cohorts where lunch duration constraints favor sub-90-second preparation.
- Students:Value-tier instant noodles and snack formats dominate university-adjacent convenience store placement in Manila and Jakarta where discretionary income constraints prioritize calorie-per-dollar metrics.
- Families:Multi-portion frozen entrees and breakfast formats target weekly stock-up behavior in Walmart and Tesco hypermarket channels.
- Seniors:Texture-modified and sodium-controlled formulations concentrate in Japanese and German pharmacy-retail crossover channels where health claims undergo stricter substantiation.
Busy professionals drive premium pricing acceptance; students anchor volume throughput in emerging market distribution.
Distribution Channel:
Supply concentration in modern retail formats is displacing traditional wholesale layers across Asian markets.
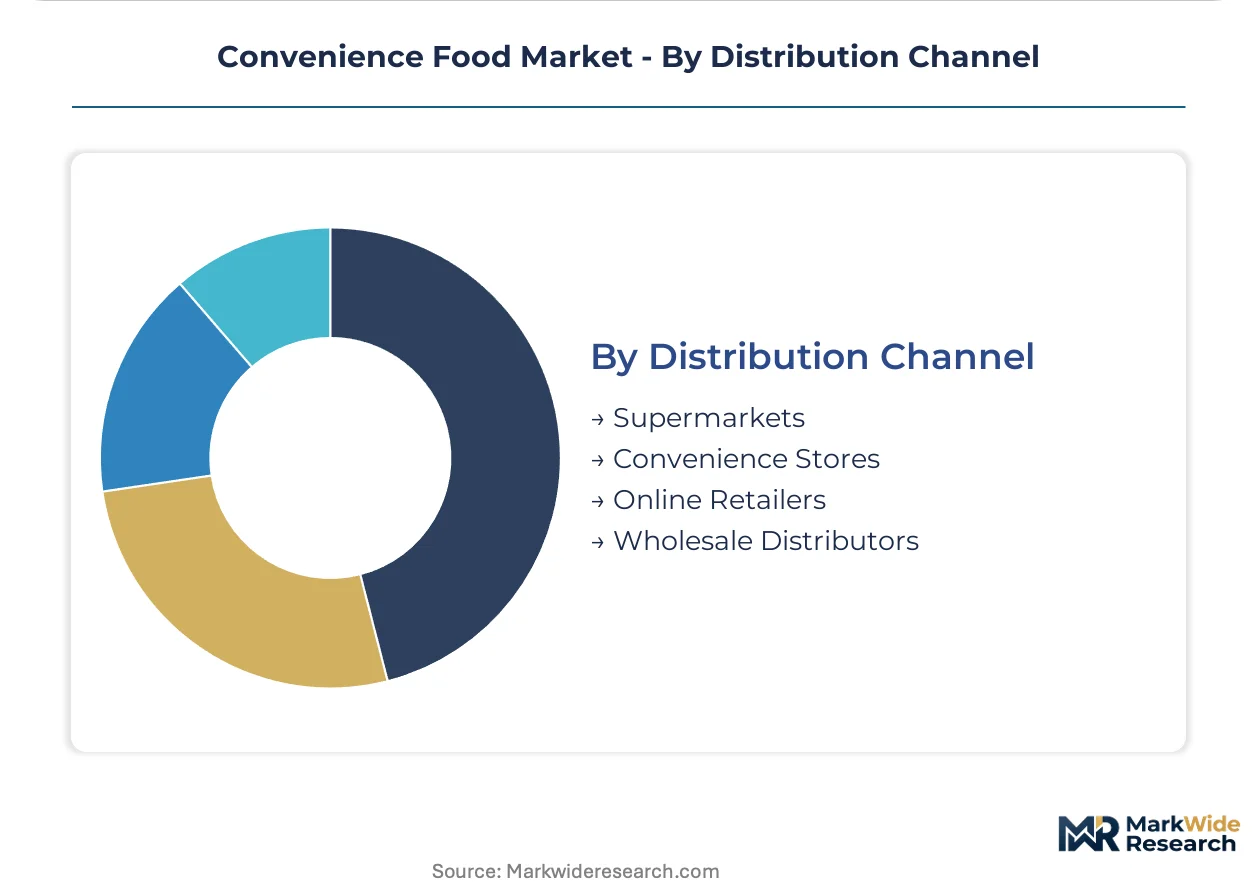
- Supermarkets:Center-store placement and end-cap promotions sustain discovery for new brand entrants in Carrefour and Ahold Delhaize banners. Volume concentrates in weekly stock-up occasions where basket-building incentives cross-sell convenience items with fresh perimeter goods.
- Convenience Stores:7-Eleven, Lawson, and FamilyMart networks in Japan and Thailand compress replenishment cycles through vendor-managed inventory systems. Demand clusters in impulse and distress-purchase occasions where location density overrides price comparison.
- Online Retailers:Direct-to-consumer platforms and quick-commerce apps fragment volume away from brick-and-mortar discovery in Seoul and Sydney metropolitan zones.
- Wholesale Distributors:Institutional and foodservice procurement concentrates volume with contract manufacturers serving healthcare and corporate cafeteria accounts.
Supermarkets retain volume leadership; online retailers capture the steepest share-gain trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Japanese buyers prioritize single-serve freshness with sub-24-hour replenishment cycles, while Indian households favor ambient-stable formats that tolerate irregular cold-chain access. Brazilian shoppers balance calorie-per-dollar metrics against emerging health-positioned premiums.
United States
Microwave-steam single-serve bowls dominate office pantry procurement in Chicago and Manhattan corporate towers. The FDA governs nutritional labeling and GRAS substance approvals, compressing reformulation timelines for preservative-dependent categories. Frozen meal production clusters in the Midwest corridor where soybean and corn inputs feed emulsifier supply chains.
Japan
Convenience store networks in Tokyo and Osaka compress replenishment through vendor-managed inventory systems. METI standards on active packaging systems accelerate oxygen-scavenger adoption in 7-Eleven and Lawson channels. Kanto region manufacturing concentrates modified-atmosphere packaging capacity for protein-heavy formats.
Germany
REACH restrictions on PFAS in food-contact materials force laminate suppliers to validate fluorine-free barrier coatings by 2025. The EU Green Deal mandates recyclability targets that accelerate mono-material polypropylene investments. Industrial clusters in Bavaria and North Rhine-Westphalia host reformulation labs replacing multi-layer legacy assets.
India
FSSAI fortification mandates pull investment toward micronutrient-enriched instant noodles as modern retail penetrates tier-two cities. PLI scheme incentives lower capex barriers for regional co-packers in Maharashtra and Gujarat. Hyderabad and Bangalore emerge as contract manufacturing hubs for shelf-stable protein formats.
Brazil
Value-tier snack formats anchor volume in São Paulo and Rio de Janeiro university-adjacent retail. ANVISA regulates front-of-pack labeling as health-positioned lines gain traction among urban professionals. Extruded and baked production concentrates in the Southeast region where corn and wheat inputs stabilize input costs.
Convenience Food Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational processors commanding freeze-drying and microwave-steam infrastructure while regional co-packers compete on localized flavor adaptation and regulatory agility. The competitive landscape bifurcates between capital-intensive format innovators and agile private-label suppliers. Three archetypes dominate: diversified food conglomerates with cross-category R&D platforms, convenience store operators with captive distribution networks, and protein-specialized processors with shelf-stable formulation expertise. Consolidation pressure manifests through backward integration into ingredient supply and strategic partnerships with quick-commerce delivery platforms.
Within the diversified conglomerate tier, Nestlé S.A. and Unilever exemplify scale-driven format innovation spanning frozen, ambient, and chilled categories. General Mills Inc. occupies a position among North American processors with heritage brand portfolios. Hormel Foods Corporation anchors the protein-specialized segment with shelf-stable expertise. The Kraft Heinz Company and Conagra Brands, Inc. sit within the mid-tier packaged food group, while 7-Eleven, Inc. and Alimentation Couche-Tard Inc. represent convenience store operators with vertical control over distribution endpoints. B&G Foods, Inc. exemplifies the regional brand aggregator archetype.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Unilever |
| Nestlé S.A. |
| 7-Eleven, Inc. |
| B&G Foods, Inc. |
| General Mills Inc. |
| Hormel Foods Corporation |
| Alimentation Couche-Tard Inc. |
| Conagra Brands, Inc. |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory cycles at European laminate suppliers compress pricing power for mono-material converters facing EU Green Deal deadlines. This lead-time compression concentrates margin pressure on regional co-packers while rewarding multinational processors with captive freeze-drying capacity.
Pricing Analysis
Contract-based long-term offtake agreements dominate frozen meal procurement between Nestlé and European retail banners, insulating input costs from palm oil volatility. Spot-market exposure concentrates in instant noodle emulsifier sourcing where Malaysian and Indonesian feedstock swings transmit directly to factory-gate pricing. Three-tier pricing structure across premium health-positioned, standard fortified, and economy bulk formats separates clean-label SKUs commanding shelf-space premiums from preservative-dependent value lines facing EFSA classification pressure. Students in Manila and Jakarta anchor price sensitivity through calorie-per-dollar optimization, while busy professionals in Singapore absorb premium positioning for sub-90-second preparation formats.
Supply Chain Analysis
Strait of Malacca transit underwrites palm oil delivery schedules to Southeast Asian noodle manufacturers, exposing margin pools to maritime congestion. Manufacturing concentration in Thailand, Vietnam, and Indonesia feeds extruded snack and retort-pouched soup capacity serving ambient distribution corridors. Modified starch and palm oil emulsifier dependencies draw from Malaysian plantations and Indian processing hubs. Single-source vulnerability concentrates in fluorinated barrier coating supply as REACH deadlines force qualification of fluorine-free alternatives. Distribution runs through vendor-managed inventory systems at 7-Eleven Japan and Lawson compressing replenishment cycles, with wholesale layers persisting only in sub-Saharan African markets lacking cold-chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based meal kit platforms and direct-to-institutional healthcare procurement are expanding recurring-revenue attachment faster than core packaged food manufacturing, reframing this market as a service-layer opportunity.
For Market Incumbents: Compound defensive positioning through backward integration into modified starch and clean-label emulsifier supply chains, securing formulation autonomy as REACH restrictions eliminate PFAS-dependent barriers. Add freeze-drying capacity in Maharashtra and Gujarat to capture PLI scheme incentives while regional co-packers face capital constraints. Channel control through vendor-managed inventory at Japanese convenience store networks limits quick-commerce platform encroachment. For New Entrants and Emerging Players: Lead with texture-modified and sodium-controlled formulations targeting Japanese pharmacy-retail crossover channels where health claim substantiation barriers filter out multinational competition. White-space concentrates in senior nutrition segments across German and Japanese distribution where incumbent portfolios underweight age-specific formulation. Direct-to-institutional procurement bypassing traditional wholesale layers offers volume concentration with healthcare and corporate cafeteria accounts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates divesting non-core ambient categories to refocus on frozen premium health-positioned lines. Five-to-ten-year viability favors protein-specialized processors with shelf-stable expertise and microwave-steam technology platforms over legacy retort-pouched soup manufacturers facing delivery-aggregator substitution. The signal to watch is FSSAI fortification mandate expansion beyond instant noodles into adjacent ambient categories, which would accelerate reformulation capex requirements and strain regional co-packer balance sheets.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Packaging Transition | EU Green Deal recyclability mandates force laminate supplier requalification by REACH deadlines. |
| Freeze-Drying Capacity Expansion | PLI scheme incentives in Maharashtra lower capex barriers for regional protein format processors. |
| Microwave-Steam Technology Licensing | Single-serve bowl formats penetrate office pantry procurement in Singapore corporate towers. |
| Direct-to-Institutional Channel Development | Healthcare and corporate cafeteria procurement concentrates volume with contract manufacturers. |
| Clean-Label Reformulation Investment | EFSA ultra-processed classifications threaten preservative-dependent category margin pools. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with convenience food brand managers, category buyers at Carrefour and Ahold Delhaize banners, plant engineers at European freeze-drying facilities, and channel sales heads at Japanese convenience store networks. Secondary validation drew from FSSAI fortification mandate filings, EFSA ultra-processed food evaluation documents, EU Green Deal packaging waste directive texts, and Nielsen retail audit data across Seoul, Sydney, and São Paulo metropolitan zones. Bottom-up volume modeling triangulated against top-down macroeconomic consumption indicators.
Across the analysis window, the forecasting framework segmented convenience food demand by product type, packaging format, end-user occasion, and distribution channel, with regional regulatory clusters overlaying geographic variation. CAGRs were derived from trend-line extrapolation of historical consumption patterns adjusted for penetration rates of modern retail infrastructure in tier-two Indian cities and cold-chain development corridors. Industry-specific inputs included vendor-managed inventory cycle compression at 7-Eleven Japan and Lawson, and palm oil price volatility transmission coefficients from Malaysian feedstock markets.
Forecasts assume regulatory continuity in EU REACH enforcement and FSSAI fortification mandates; material policy shifts would require re-modeling of reformulation investment timelines and capital allocation patterns. Practitioners should keep alternative scenarios live as EFSA front-of-pack warning label regimes and EU Green Deal recyclability deadline enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Eco Bowls Market
Packaged Foods
Packaged Rice Noodles Market
Packaged Foods
North America Ready Meals Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Global Fruit Spreads Market
Packaged Foods
Packaged Salad Market
Packaged Foods
US Packaged Food Market
Packaged Foods
Air-Dried Food Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
India Packaged Food Products Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Instant Cereals Market
Packaged Foods
US Packaged Salads Market
Packaged Foods
Coffee Pouch Market
Packaged Foods
Plant Focused Dips Market
Packaged Foods
Canned Beans Market