
 Norway Rechargeable Battery Market | 2026-2036
Norway Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Rechargeable Battery Market Insights
Lithium iron phosphate cathode chemistry is decoupling Norwegian cell production from cobalt supply risk. Morrow Batteries AS leverages vertical integration into active material synthesis to control cost structures. FREYR Battery anchors its competitive position through licensing of American 24M semi-solid electrode technology. Corvus Energy AS dominates marine energy storage with systems engineered for North Sea operating conditions.
A rechargeable battery stores electrochemical energy through reversible reduction-oxidation reactions, with lithium-ion variants achieving energy densities of 250-300 Wh/kg using nickel-manganese-cobalt or lithium iron phosphate cathode formulations paired with graphite or silicon composite anodes. These systems enable repeated charge-discharge cycling for grid stabilization, propulsion, and portable power applications. Solid-state product types attract the steepest R&D allocation as Norwegian developers target elimination of flammable liquid electrolytes. Electric vehicle application demand outpaces consumer electronics growth, driven by Norway's ICE sales ban and Nordic EV penetration leadership. Utility companies as end users are restructuring procurement to require verified low-carbon cell production.
Norwegian Water Resources and Energy Directorate permitting frameworks govern grid-connected storage installations exceeding 1 MW capacity. EU Battery Regulation delegated acts mandate carbon footprint declarations and recycled content minimums for cells placed on the European Economic Area market. BIS certification requirements affect import flows for non-EU sourced nickel and cobalt refining equipment. Stakeholders must monitor how EU critical raw materials act implementation alters Norwegian access to African and Indonesian processed metal streams.
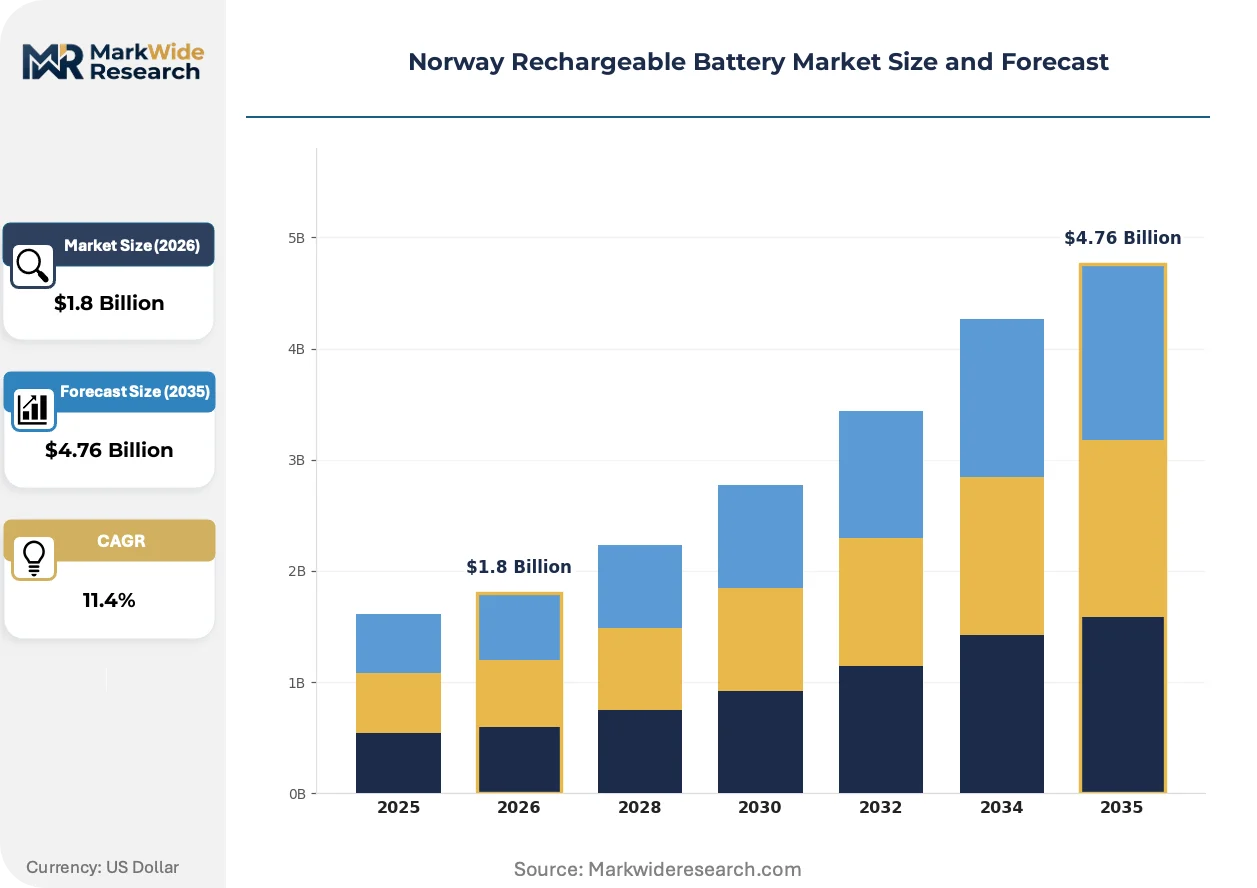
Market Dynamics
EU Battery Regulation carbon footprint declarations are forcing Norwegian cell manufacturers to restructure supply chains around verified low-carbon precursor sourcing, compressing procurement timelines and elevating traceability infrastructure to core competitive capability.
Growth Catalysts
- Zero-emission fjord ferry mandate:Norwegian maritime regulators require all fjord vessels to convert to electric propulsion by 2026, generating sustained demand for marine-optimized lithium-ion systems with enhanced thermal management.
- Oslo-Grenland industrial corridor concentration:Cell manufacturing and precursor refining investments cluster along this corridor, creating localized supplier networks that reduce logistics costs and accelerate R&D collaboration between adjacent facilities.
- ICE sales ban enforcement:Norway's prohibition on internal combustion engine vehicle sales from 2025 eliminates competing propulsion technologies, directing all automotive demand toward rechargeable battery electric platforms.
Market Restraints
- African cobalt supply concentration:Norwegian cathode production remains exposed to processing bottlenecks in the Democratic Republic of Congo and Zambia, where geopolitical instability and artisanal mining scrutiny disrupt material flows.
- Silicon anode swelling limitations:Silicon composite anodes promise higher energy density but suffer from volumetric expansion during cycling, degrading cell longevity and complicating warranty structures for automotive OEMs.
- Grid connection permitting delays:Norwegian Water Resources and Energy Directorate frameworks for utility-scale storage exceeding 1 MW capacity impose extended environmental review timelines that stall project commercialization.
Strategic Opportunities
- North Sea offshore wind integration:Floating offshore wind installations off Norway's coast require massive stationary storage for grid stabilization, creating demand for containerized battery systems engineered for saline environments.
- EU critical raw materials act alignment:Norwegian developers can secure preferential access to European processed metal streams by certifying domestic refining capacity under the act's strategic project designation.
- Solid-state electrolyte convergence:Combination of sulfide-based solid electrolytes with lithium metal anodes enables elimination of flammable liquid components, opening aviation and subsea applications previously closed to conventional lithium-ion.
Industry Challenges
- Electrochemical engineering talent scarcity:Norwegian universities produce insufficient specialists in solid-state cell architecture and dry electrode processing, forcing manufacturers to recruit from German and South Korean competitor pools.
- Semi-solid electrode certification complexity:Licensing American 24M technology requires extensive adaptation to EU Battery Regulation conformity assessment procedures, extending time-to-market for novel form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Rechargeable Battery Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Metal Hydride, Lead-Acid, Solid-State Application: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Industrial Equipment End User: Manufacturers, Retailers, Utility Companies, Residential Users Distribution Channel: Online Retailers, Direct Sales, Wholesale Distributors, Specialty Stores |
| Companies Covered | Morrow Batteries AS, FREYR Battery, Corvus Energy AS, Beyonder AS, Hydrovolt, Vianode, Pixii AS, Elinor Batteries, Kongsberg Maritime AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Rechargeable Battery Market Trends and Innovations
Dry electrode coating processes are eliminating solvent-based manufacturing steps, cutting energy consumption and facility footprint while enabling thicker active material layers that boost energy density.
Semi-solid electrode technology is automating the elimination of traditional calendering and drying stages, allowing FREYR Battery and similar developers to halve production line capital requirements. Maritime operators in Bergen and Stavanger are piloting these cells for ferry applications where reduced fire risk justifies premium pricing. The structural consequence is automating the compression of incumbent wet-coating equipment suppliers out of Nordic procurement portfolios.
EU Battery Regulation delegated acts mandating recycled content minimums are compelling Norwegian manufacturers to integrate hydrometallurgical black mass processing into domestic facilities. Industrial consequence includes binding offtake agreements with European recycling operators to secure qualified scrap streams. Automotive OEMs sourcing cells for the Nordic market are responding by inserting recycled content clauses into supplier contracts with penalty structures for non-compliance.
Fleet operators are consolidating procurement through long-term service agreements that bundle cell supply with predictive maintenance and residual value guarantees. Direct OEM relationships are displacing traditional distributor networks for volumes exceeding 100 MWh annually. This concentration is most visible among Oslo-based logistics companies electrifying last-mile delivery van fleets under municipal zero-emission zone requirements.
Norway Rechargeable Battery Market Segmentation
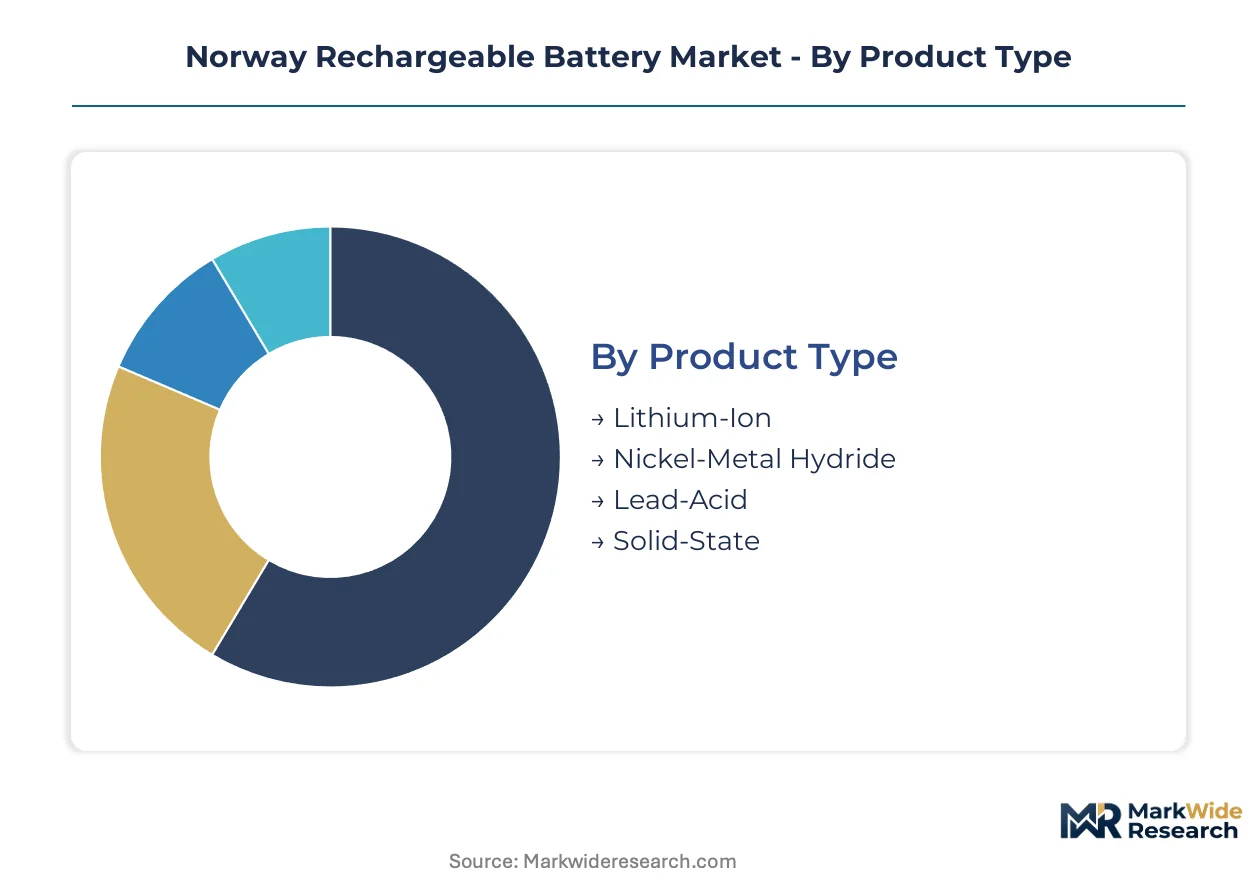
Segmentation reveals how capital deployment and regulatory pressure concentrate across Norway's rechargeable battery value chain. Each dimension exposes distinct margin structures and compliance burdens that determine competitive positioning.
Product Type:
Capital intensity varies dramatically across electrochemical systems, with solid-state manufacturing requiring 3-4x the upfront investment of conventional liquid-electrolyte lines due to dry room specifications and sulfide handling infrastructure.
- Lithium-Ion:Nickel-manganese-cobalt and lithium iron phosphate formulations dominate Norwegian production, with LFP chemistry decoupling supply chains from African cobalt processing bottlenecks. Morrow Batteries and FREYR Battery concentrate gigafactory investments in the Oslo-Grenland corridor to serve Nordic EV OEMs and maritime operators under the zero-emission fjord ferry mandate.
- Solid-State:Sulfide-based electrolytes paired with lithium metal anodes eliminate flammable liquid components, opening aviation and subsea applications previously closed to conventional systems. Norwegian developers allocate the steepest R&D budgets to this category despite unresolved manufacturing scale challenges.
- Nickel-Metal Hydride:Mature chemistry retains niche demand in hybrid vehicle auxiliary systems and industrial backup power where temperature tolerance outweighs energy density requirements.
- Lead-Acid:Flooded and valve-regulated designs persist in off-grid residential storage and marine starting applications where cost sensitivity dominates procurement criteria.
Most installed capacity flows through lithium-ion systems. Expansion is steepest in solid-state as developers target premium applications with enhanced safety requirements.
Application:
Application segmentation tracks how Norway's ICE sales ban and maritime decarbonization mandates redirect demand across end-use categories with diverging performance specifications.
- Electric Vehicles:Passenger cars, vans, and heavy trucks absorb the majority of Norwegian cell output, with fleet operators consolidating procurement through direct OEM relationships exceeding 100 MWh annually. The 2025 prohibition on internal combustion engine sales eliminates competing propulsion technologies entirely.
- Renewable Energy Storage:Grid-connected installations exceeding 1 MW capacity face Norwegian Water Resources and Energy Directorate permitting frameworks, while floating offshore wind integration off Norway's coast creates demand for containerized systems engineered for saline environments.
- Consumer Electronics:Portable power demand for smartphones, laptops, and power tools grows modestly relative to mobility applications, with procurement shifting toward verified low-carbon production under EU Battery Regulation alignment.
- Industrial Equipment:Forklifts, mining machinery, and agricultural vehicles require ruggedized thermal management systems optimized for Nordic operating conditions.
Revenue concentration sits with electric vehicles. Renewable energy storage is climbing the fastest as utility procurement restructures around carbon footprint declarations.
End User:
Customer type segmentation exposes diverging procurement sophistication, with utility companies and large manufacturers driving standardization while residential users remain price-sensitive and fragmented.
- Utility Companies:Transmission and distribution operators restructure procurement to require verified low-carbon cell production, inserting recycled content clauses with penalty structures for non-compliance under EU Battery Regulation delegated acts.
- Manufacturers:Automotive OEMs and marine system integrators dominate volume offtake, with Oslo-based logistics companies electrifying last-mile delivery van fleets under municipal zero-emission zone requirements.
- Retailers:Consumer-facing channels face margin compression as direct manufacturer relationships displace traditional distribution networks for volumes above threshold scales.
- Residential Users:Homeowners and small businesses purchase backup power and solar-coupled storage through online retailers and specialty stores, with demand concentrated in suburban Oslo and Bergen metropolitan areas.
Procurement volume concentrates with manufacturers. Contract sophistication is advancing most quickly among utility companies.
Distribution Channel:
Channel segmentation tracks the displacement of intermediaries as large-volume buyers consolidate direct relationships with cell producers, compressing distributor margins and restructuring logistics networks.
- Direct Sales:Long-term service agreements bundling cell supply with predictive maintenance and residual value guarantees dominate volumes exceeding 100 MWh annually, displacing traditional distributor networks among fleet operators and utility procurement teams.
- Wholesale Distributors:Regional inventory holders retain relevance for mid-scale industrial customers and smaller maritime operators requiring technical support and rapid spare parts availability.
- Online Retailers:E-commerce platforms capture residential and small commercial demand for standardized battery packs, with logistics optimization around Oslo and Trondheim distribution hubs.
- Specialty Stores:Technical retailers serving marine, automotive aftermarket, and off-grid segments provide installation services and warranty handling that pure digital channels cannot replicate.
Transaction volume flows predominantly through direct sales. Channel development is most active among online retailers expanding technical content and installation partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oslo-Grenland industrial corridor anchors Norwegian cell manufacturing, with precursor refining and active material synthesis clustering along this axis to serve Nordic EV OEMs and maritime electrification mandates.
Oslo Metropolitan Area
Capital region demand surges from municipal zero-emission zone requirements for last-mile delivery fleets. Norwegian Water Resources and Energy Directorate permitting governs grid-connected storage installations exceeding 1 MW. Fornebu and Lillestrøm host R&D facilities targeting solid-state electrolyte development for aviation applications.
Grenland Industrial Hub
Porsgrunn and Herøya concentrate gigafactory investments serving electric ferry operators under the 2026 zero-emission fjord mandate. EU Battery Regulation alignment tightens carbon footprint declarations for cells placed on the European Economic Area market. Local supplier networks reduce logistics costs for cathode precursor delivery.
Bergen Maritime Cluster
Western Norway's ferry electrification pilots drive marine-optimized lithium-ion procurement with enhanced thermal management. Norwegian Maritime Authority enforcement of zero-emission vessel requirements accelerates system integration contracts. Hanøytangen and Ågotnes facilities engineer containerized battery systems for North Sea offshore wind integration.
Stavanger Energy Corridor
North Sea offshore wind developers require massive stationary storage for grid stabilization at floating installations. Norwegian Petroleum Directorate frameworks for energy transition projects facilitate hybrid renewable-storage licensing. Risavika harbor hosts pilot programs for saline-environment battery containers.
Trondheim Technology Axis
Central Norway's research institutions supply electrochemical engineering talent for dry electrode processing development. Norwegian University of Science and Technology partnerships with manufacturers address solid-state cell architecture expertise gaps. Gløshaugen campus spinouts commercialize silicon composite anode formulations.
Norway Rechargeable Battery Market Competitive Landscape
Global majors compete with regional champions across technology licensing and vertical integration depth, producing a tiered structure where scale-driven producers face specialized marine system integrators. Market concentration is moderate, with domestic developers holding defensible positions in maritime and Nordic EV supply chains. Three archetypes dominate: integrated cell-and-material producers, technology licensees leveraging foreign IP, and marine application specialists. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with producers securing binding offtake agreements to lock in raw material streams.
Among Oslo-Grenland based developers, Morrow Batteries AS, FREYR Battery, and Corvus Energy AS occupy distinct strategic positions. Morrow Batteries exemplifies the integrated archetype through upstream control over active material synthesis. FREYR Battery anchors the technology-licensee tier, representing firms that import foreign electrode innovations for domestic adaptation. Corvus Energy sits within the marine specialization segment, exemplifying developers engineered for North Sea operating conditions. These three collectively demonstrate how Norwegian producers segment the market by electrochemical system and end-use application.
| Leading Market Players |
|---|
| Morrow Batteries AS |
| FREYR Battery |
| Corvus Energy AS |
| Beyonder AS |
| Hydrovolt |
| Vianode |
| Pixii AS |
| Elinor Batteries |
| Kongsberg Maritime AS |
| Others |
Pricing and Supply Chain Analysis
Cathode active material costs cascade through Norwegian cell manufacturing, with lithium iron phosphate precursors sourced from European refiners commanding premium pricing tiers against nickel-manganese-cobalt alternatives drawing from African and Indonesian processing hubs. This input-cost geography splits procurement strategies between EU Battery Regulation-compliant supply chains and cost-optimized Asian material streams.
Pricing Analysis
Input-cost pass-through from African cobalt and Indonesian nickel processing bottlenecks compresses margins on nickel-manganese-cobalt formulations, while lithium iron phosphate chemistry escapes this volatility through European precursor sourcing. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified low-carbon cells from transitional-grade and uncertified imports. Pricing pressure stems from utility procurement teams inserting recycled content clauses with penalty structures. Fleet operators above 100 MWh annual volumes exhibit lowest price sensitivity due to bundled service agreements, while residential buyers through online retailers remain most cost-responsive.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand above 100 MWh annually, displacing wholesale distributors for automotive and maritime procurement. Geographic supply concentration centers on China for processed cathode materials, South Korea for electrolyte formulations, and the Democratic Republic of Congo for cobalt hydroxide. Raw material dependencies include spodumene concentrate from Australia, nickel matte from Indonesia, and synthetic graphite from China. Single-source vulnerability in sulfide solid electrolyte precursors threatens solid-state scaling timelines. Distribution runs through long-term offtake agreements binding Norwegian gigafactories to European precursor refiners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norwegian cell manufacturing functions as a geographic-arbitrage play between EU Battery Regulation carbon footprint compliance and Nordic EV penetration premiums, exploiting the regulatory gap that penalizes Asian imports while rewarding domestic low-carbon production.
For Market Incumbents: Acquire hydrometallurgical black mass processing capabilities to secure recycled content streams under EU Battery Regulation delegated acts. Lock in binding offtake agreements with European lithium refiners before Critical Raw Materials Act strategic project designations close. Electrochemical engineering talent scarcity from German and South Korean competitor pools threatens production scaling timelines. For New Entrants and Emerging Players: Regional ferry operators outside the Oslo-Grenland corridor represent an underserved buyer archetype requiring marine-optimized systems with enhanced thermal management. Target Stavanger Energy Corridor floating offshore wind developers needing saline-environment containerized storage. White-space penetration runs through predictive maintenance bundling absent from incumbent direct sales models. For Investors and Strategic Acquirers: Consolidation pressure builds where solid-state electrolyte developers face manufacturing scale challenges exceeding capital access. Five-to-ten-year viability favors integrated cell-and-material producers with captive precursor refining. Acquisition target archetype: dry electrode processing specialists addressing talent scarcity at Norwegian universities. Signal to watch: EU Critical Raw Materials Act implementation altering Norwegian access to African and Indonesian metal streams.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursor Refining | Morrow Batteries' active material synthesis control reduces exposure to African cobalt processing bottlenecks. |
| Semi-Solid Electrode Technology Licensing | FREYR Battery's 24M adaptation halves production line capital requirements for maritime applications. |
| Marine System Integration Specialization | Corvus Energy dominates North Sea ferry electrification under the 2026 zero-emission mandate. |
| Hydrometallurgical Black Mass Processing | Hydrovolt secures qualified scrap streams for EU Battery Regulation recycled content compliance. |
| Solid-State Electrolyte R&D Convergence | Beyonder AS targets aviation and subsea applications closed to conventional lithium-ion systems. |
Research Methodology
Multiple input streams — cell manufacturer procurement directors, Norwegian Water Resources and Energy Directorate permitting officers, maritime system integrators, and EU regulatory affairs specialists — were reconciled against secondary validation from EEA customs databases, EU Battery Regulation delegated act drafts, and Nordic EV registration statistics. Bottom-up project pipeline aggregation across Oslo-Grenland gigafactory investments combined with top-down macroeconomic drivers to produce volume and value estimates. Primary fieldwork captured operational constraints at Porsgrunn and Herøya facilities.
Cross-referencing historical capacity deployment patterns against expert panel input on solid-state manufacturing timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled include electrochemical system, end-use application, buyer procurement scale, and regional regulatory cluster. CAGRs derived from weighted average of technology diffusion curves and policy mandate enforcement schedules. Industry-specific forecast inputs incorporated floating offshore wind project development databases and ferry electrification retrofit pipelines.
Underlying measurement precision varies by segment; electric vehicle application volumes carry tighter precision than emerging aviation solid-state demand. Forecasts reflect assumptions on EU Critical Raw Materials Act implementation pace and sulfide electrolyte manufacturing yield improvements. Periodic stress-testing of base assumptions is recommended against Norwegian Water Resources and Energy Directorate permitting timeline volatility and African cobalt supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Submarine Batteries Market
Batteries
Australia Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Vietnam Battery Market
Batteries
Europe Battery Cell Market
Batteries
Atomic Battery Market
Batteries
Coin Cell Lithium Batteries Market
Batteries
Global Primary Cells Market
Batteries
India Lead-Acid Battery Market
Batteries
North America Industrial Battery Market
Batteries
China Rechargeable Battery Market
Batteries
Rechargeable Coin Cell Market
Batteries
Behind-The-Meter (BTM) Battery Market
Batteries
Malaysia Battery Market
Batteries
Europe Rechargeable Battery Market
Batteries
Stationary Lead-Acid Battery Market