
 Sodium-Ion Battery Electrolyte Market | 2026-2036
Sodium-Ion Battery Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium-Ion Battery Electrolyte Market Insights
UN 38.3 lithium-ion transport certification is rotating toward sodium-ion analogs, creating a qualification bottleneck that filters supplier eligibility. Contemporary Amperex Technology Co. Limited leverages its scale to pre-certify electrolyte formulations across multiple cell formats. HiNa Battery Technology Co. Ltd. anchors its position through captive R&D in hard-carbon anode-electrolyte interfaces. Faradion Limited differentiates by specializing in high-voltage organic electrolyte salts for next-generation cathode chemistries.
Sodium-ion battery electrolyte comprises conductive salts dissolved in solvent systems, typically sodium hexafluorophosphate in carbonate blends with viscosity below 5 mPa·s and ionic conductivity exceeding 5 mS/cm at room temperature, enabling sodium-ion transport between hard-carbon anodes and layered-oxide cathodes during charge-discharge cycling. Organic electrolyte formulations currently lead product-type revenue due to compatibility with existing lithium-ion manufacturing infrastructure, while solid-state polymer electrolytes represent the fastest-growing form factor as manufacturers seek flame-retardant alternatives for grid storage installations. Energy storage systems dominate application demand because utilities prioritize cycle-life stability over energy density, whereas electric vehicle adoption of sodium-ion electrolytes remains nascent pending cold-start performance validation.
FDA oversight of battery materials in medical device power supplies intersects with EPA hazard classification rules for fluorinated electrolyte salts, creating dual compliance burdens for suppliers targeting US healthcare and industrial segments. China's SAMR enforces GB/T 36276 technical standards for electrochemical energy storage systems, directly specifying electrolyte purity thresholds and thermal runaway propagation tests. REACH registration requirements in Europe constrain importers of novel sodium salts, favoring electrolyte producers with established EU chemical dossiers. Stakeholders must monitor which certification regimes achieve cross-border mutual recognition first, as this will determine manufacturing location decisions and customer access priorities.
Market Dynamics
Electrolyte formulation standardization is compressing supplier margins while amplifying first-mover advantages for producers with pre-qualified salt-solvent portfolios across multiple cell architectures.
Growth Catalysts
- China's GB/T 36276 standard:Mandatory thermal runaway propagation testing for grid storage systems is forcing electrolyte purity upgrades that favor qualified suppliers with captive sodium hexafluorophosphate synthesis.
- Hard-carbon anode interface engineering:Solid-electrolyte interphase optimization breakthroughs are extending cycle life beyond 4,000 cycles for stationary storage operators prioritizing longevity over energy density.
- Lithium carbonate price volatility:Sustained supply constraints in South American brine extraction are accelerating sodium-ion pilot deployments by battery integrators seeking input cost stability.
Market Restraints
- Fluorinated salt supply concentration:Sodium hexafluorophosphate precursor manufacturing clusters in Hubei and Shandong provinces create single-source vulnerability for non-Chinese cell producers.
- Ionic conductivity floor:Organic liquid electrolytes remain capped near 8 mS/cm at sub-zero temperatures, blocking cold-climate EV adoption pending solid-state polymer maturation.
- REACH registration timelines:ECHA novel substance dossier requirements impose 18-24 month lag on European market entry for experimental sodium salts beyond NaPF6.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Production-linked incentives for advanced chemistry cells include sodium-ion eligibility, opening electrolyte supply contracts for domestic giga-factory projects.
- Marine electrification:Port authorities in Rotterdam and Singapore are specifying non-flammable battery chemistries for shore power and vessel propulsion, favoring solid-state polymer electrolyte development.
- Dual-carbon policy alignment:China's MEE carbon intensity benchmarks for industrial processes reward electrolyte producers with closed-loop solvent recovery systems and renewable-powered salt synthesis.
Industry Challenges
- UN 38.3 analog certification:Absence of harmonized sodium-ion transport testing protocols forces redundant qualification campaigns across FAA, IATA, and maritime Dangerous Goods frameworks.
- Electrochemist talent scarcity:Limited academic programs specializing in sodium-ion interfacial chemistry constrain R&D velocity for mid-tier suppliers without university partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium-Ion Battery Electrolyte Market |
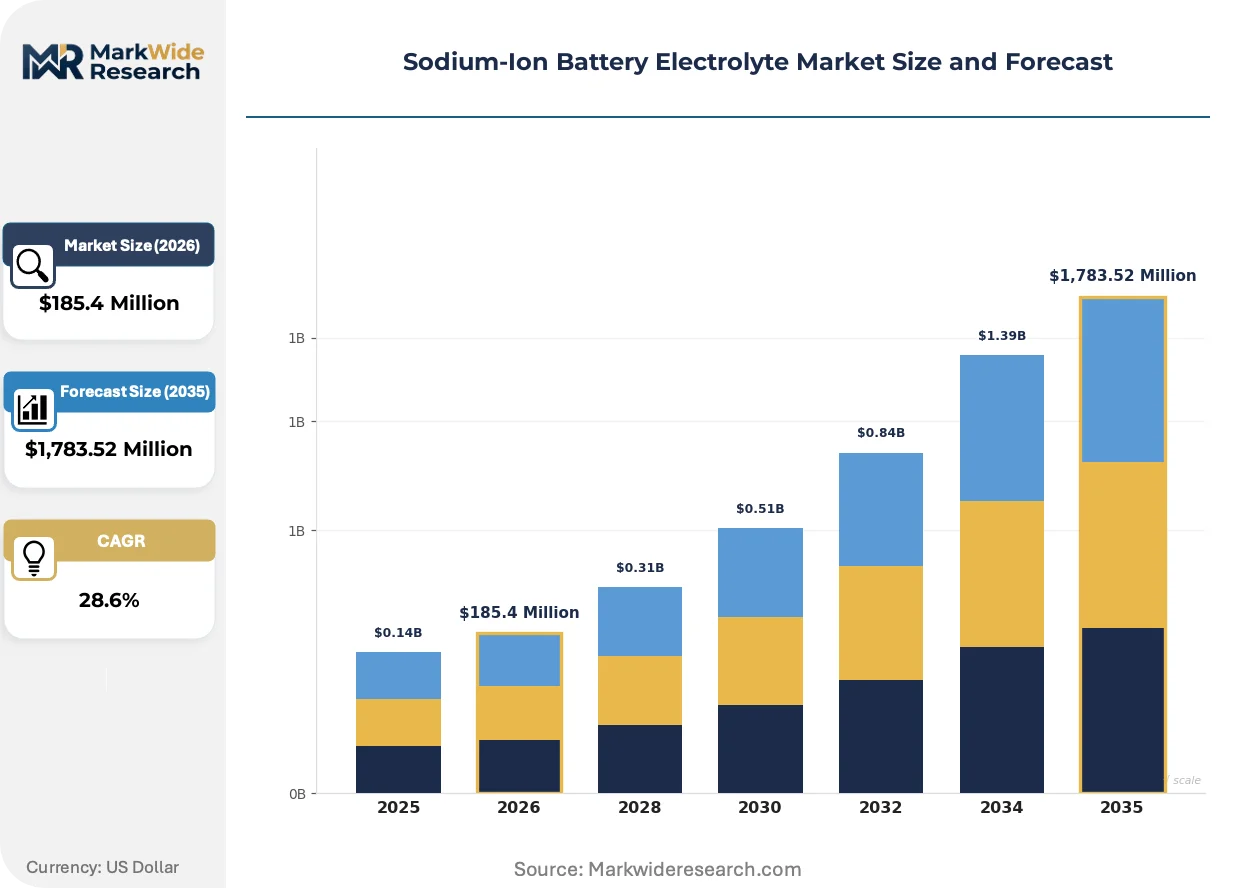
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $1,783.52 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Electrolyte, Aqueous Electrolyte, Polymer Electrolyte, Ionic Liquid Electrolyte Application: Energy Storage Systems, Electric Vehicles, Consumer Electronics, Industrial Applications End User: Manufacturers, Research Institutions, Automotive Companies, Energy Providers Form Factor: Liquid, Gel, Solid, Semi-solid |
| Companies Covered | Contemporary Amperex Technology Co. Limited, HiNa Battery Technology Co. Ltd., Faradion Limited, Altris AB, Natron Energy, TIAMAT SAS, Zhejiang Starry Pharmaceutical Co. Ltd., Sichuan Xingneng New Materials Co. Ltd., Shenzhen Highstar Electrical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium-Ion Battery Electrolyte Market Trends and Innovations
Electrolyte chemistry is fragmenting along performance-versus-safety trade-offs as grid storage procurement specifications diverge from mobility requirements. Formulation houses must now maintain parallel development tracks.
Solid-state polymer electrolytes incorporating ceramic fillers are decomposing the traditional liquid-electrolyte dominance in stationary storage tenders. Utility procurement teams in Germany and Australia are mandating flame-retardant form factors for containerized battery installations. This shift is compressing addressable market share for conventional carbonate-based formulations in the grid segment.
REACH authorization requirements for fluorinated compounds are tightening disclosure obligations for electrolyte salt importers into the European Economic Area. ECHA's 2023 update to Annex XIV candidate listing triggered reformulation efforts toward partially-fluorinated alternatives. Cell producers serving EU medical device and industrial markets are accelerating supply chain audits to preempt registration gaps.
Long-term offtake contracting is displacing spot purchasing for sodium hexafluorophosphate as cathode material producers secure volume commitments. Tier-one battery integrators in China and South Korea are negotiating five-year supply agreements with electrolyte houses, locking in capacity before commercial scale-up. This pattern concentrates procurement leverage among vertically integrated cell manufacturers with balance sheet capacity for prepayment structures.
Sodium-Ion Battery Electrolyte Market Segmentation
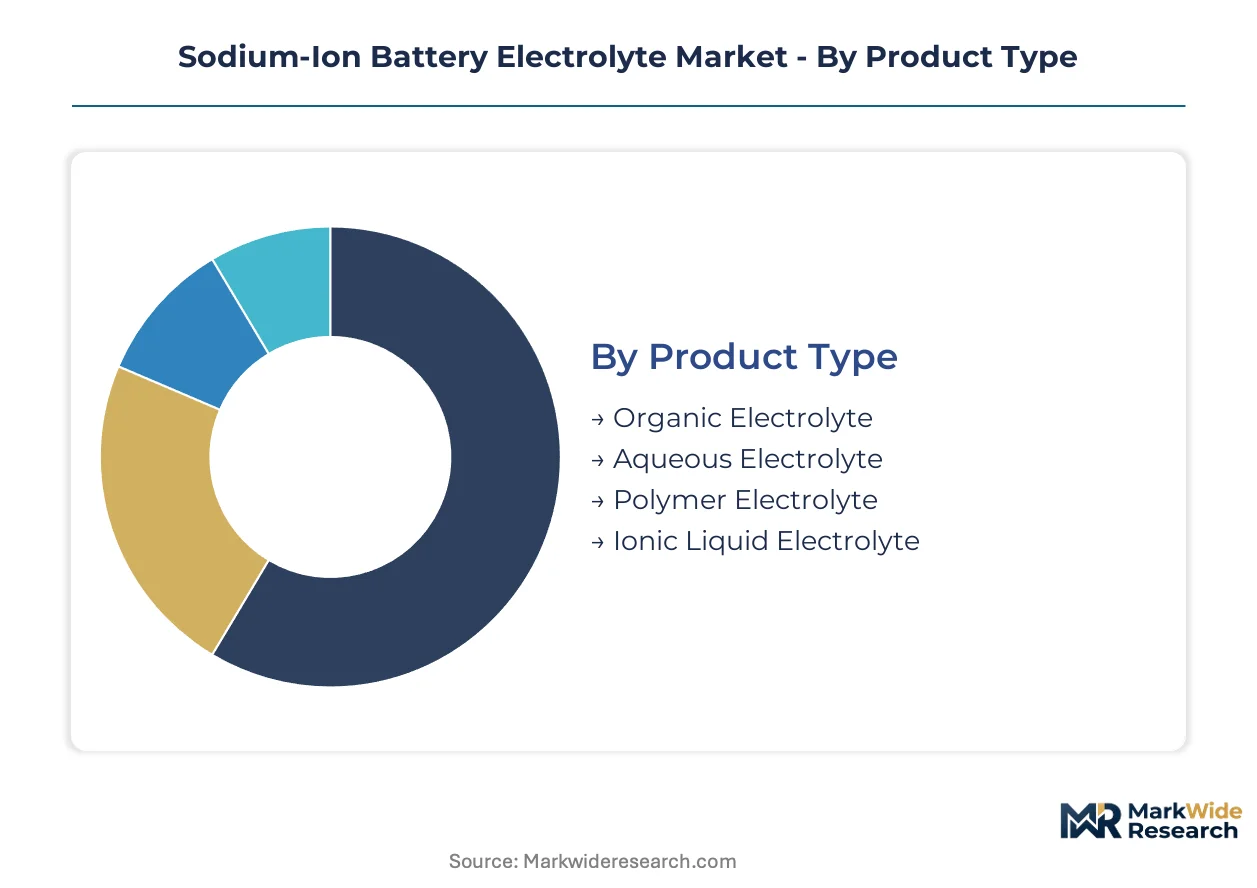
Electrolyte suppliers must navigate divergent performance requirements across cell architectures and end-use environments. Segmentation reveals where formulation complexity translates to pricing power versus commoditization pressure.
Product Type:
Margin pools concentrate in formulations compatible with existing lithium-ion manufacturing infrastructure, where qualification costs create switching barriers.
- Organic Electrolyte:Sodium hexafluorophosphate dissolved in carbonate solvent blends dominates current production, leveraging established purification and filling equipment from lithium-ion lines. China's cathode material clusters in Hunan and Hubei provinces drive procurement concentration, with state-backed stationary storage tenders specifying cycle-life thresholds that favor mature organic formulations.
- Polymer Electrolyte:Solid-state architectures incorporating ceramic fillers are expanding most quickly as German and Australian utilities mandate flame-retardant chemistries for containerized grid installations. Rotterdam and Singapore port authorities are specifying non-flammable electrolytes for marine electrification, accelerating pilot production scale-up.
- Aqueous Electrolyte:Water-based systems eliminate flammability risks but sacrifice voltage window, finding niche deployment in indoor stationary storage where safety regulations are most stringent.
- Ionic Liquid Electrolyte:Room-temperature molten salt formulations offer thermal stability for extreme climate operation, though cost structures currently restrict adoption to defense and aerospace qualification programs.
Organic electrolyte holds installed capacity. Polymer electrolyte is rotating up the share rankings.
Application:
Volume concentration tracks procurement cycles for utility-scale storage versus mobility platforms with divergent performance validation timelines.
- Energy Storage Systems:Grid operators prioritize cycle-life stability exceeding 4,000 cycles over energy density, enabling sodium-ion penetration where lithium supply constraints disrupt project financing. China's GB/T 36276 thermal runaway propagation standards are forcing electrolyte purity upgrades that filter supplier eligibility.
- Electric Vehicles:Cold-start performance validation below minus 20 degrees Celsius remains incomplete, blocking OEM adoption pending solid-state polymer maturation with sub-zero ionic conductivity above 5 mS/cm.
- Consumer Electronics:Cost-sensitive portable power applications favor aqueous systems where energy density requirements are modest and safety certifications are accelerated.
- Industrial Applications:Forklift and material handling equipment in European warehouses are piloting sodium-ion replacements under REACH-constrained supply chains.
Energy storage systems command procurement volume. Electric vehicles are climbing the priority ladder as validation milestones advance.
End User:
Customer type determines contract structure, with captive R&D programs offering volume commitments versus spot purchasing from research institutions.
- Manufacturers:Cell producers negotiate five-year offtake agreements for sodium hexafluorophosphate, locking in capacity before commercial scale-up concentrates leverage among vertically integrated suppliers.
- Automotive Companies:OEM qualification programs impose 18-24 month validation cycles, creating entry barriers that favor electrolyte houses with pre-certified salt-solvent portfolios.
- Research Institutions:Academic and national laboratory procurement drives experimental salt development, though volumes remain below commercial thresholds.
- Energy Providers:Utility procurement teams are mandating flame-retardant form factors in containerized tenders, shifting specification authority from cell manufacturers to system integrators.
Manufacturers anchor contract volume. Energy providers are ascending the influence hierarchy through tender specification control.
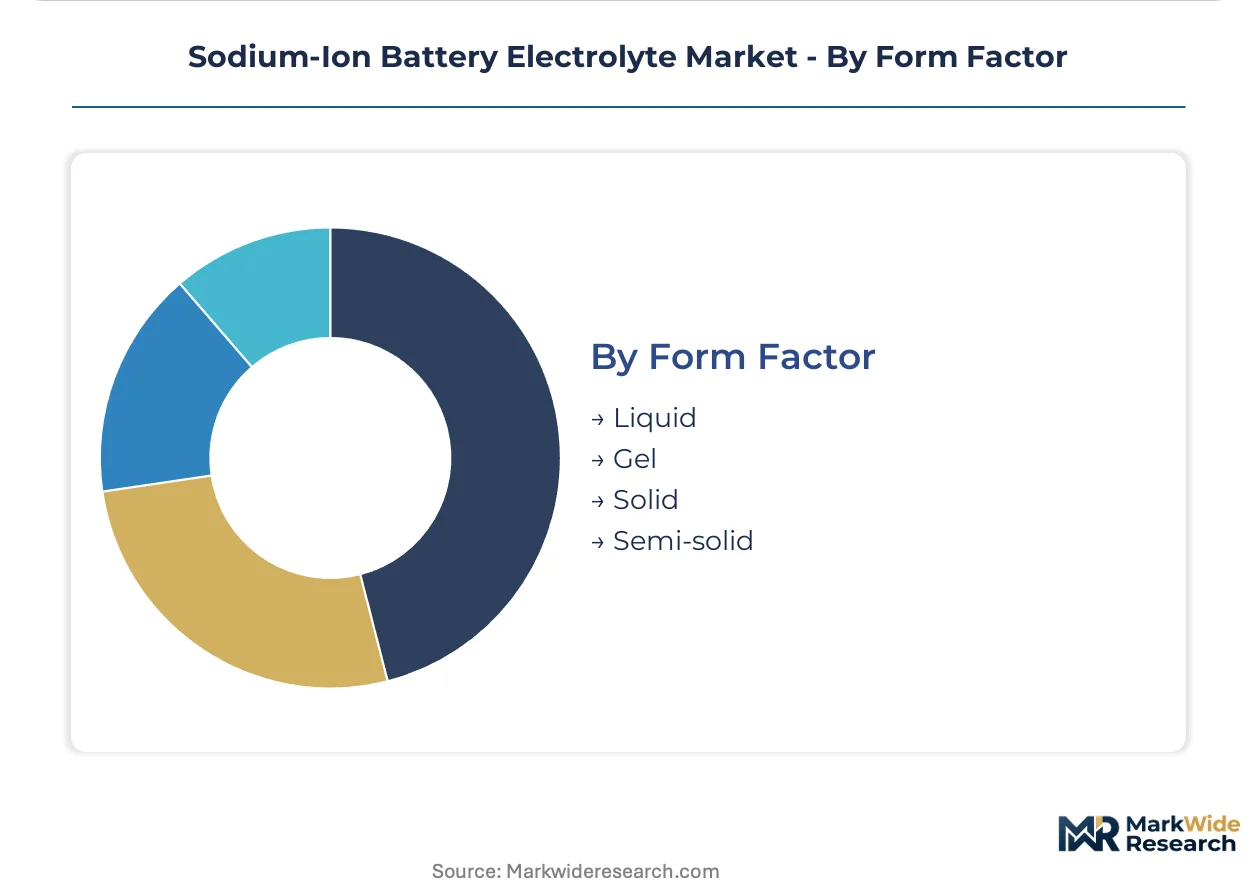
Form Factor:
Physical state determines manufacturing equipment compatibility and safety classification for transport and installation.
- Liquid:Conventional carbonate-based formulations dominate current production, filling existing lithium-ion lines with viscosity below 5 mPa·s for high-speed assembly.
- Solid:Ceramic-filled polymer matrices eliminate leakage risks and thermal runaway propagation, gaining specification in German grid storage tenders.
- Gel:Semi-rigid architectures balance ionic conductivity with mechanical stability for flexible battery geometries in consumer applications.
- Semi-solid:Hybrid formulations are emerging for marine electrification where vibration tolerance and non-flammability converge in port authority specifications.
Liquid form factor retains production dominance. Solid electrolyte is advancing fastest through utility safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's state-backed deployment targets for stationary storage are compressing qualification timelines for electrolyte suppliers across multiple jurisdictions. India's PLI scheme for advanced chemistry cells is opening electrolyte supply contracts for domestic giga-factory projects. European REACH requirements are constraining market entry for experimental sodium salts beyond standard formulations.
China
Hunan and Hubei province cathode material clusters are driving concentrated procurement of sodium hexafluorophosphate. SAMR enforces GB/T 36276 technical standards specifying electrolyte purity thresholds and thermal runaway propagation tests. Zhejiang and Sichuan electrolyte producers are scaling captive salt synthesis to meet state-backed grid storage deployment targets.
India
Domestic giga-factory projects under the PLI scheme for ACC batteries are creating electrolyte supply contract opportunities. CEA technical standards for electrochemical energy storage systems are mandating safety testing protocols for imported formulations. Gujarat and Tamil Nadu manufacturing corridors are attracting electrolyte qualification programs from cell producers seeking localized supply chains.
Germany
Utility procurement teams are mandating flame-retardant electrolyte form factors for containerized grid installations. ECHA REACH registration requirements are favoring producers with established chemical dossiers for sodium salts. Bavaria and North Rhine-Westphalia industrial clusters are piloting solid-state polymer electrolyte integration for stationary storage tenders.
United States
Grid-scale energy storage operators are expanding sodium-ion pilot deployments as lithium supply constraints disrupt project financing. FDA oversight of battery materials in medical devices intersects with EPA hazard classification rules for fluorinated electrolyte salts. California and Texas utility markets are driving specification authority toward system integrators for non-flammable battery chemistries.
Australia
Utility procurement specifications are prioritizing cycle-life stability exceeding 4,000 cycles for sodium-ion grid installations. The country's national energy regulator is developing safety standards for containerized battery systems that reference electrolyte thermal stability. New South Wales and Victoria grid storage tenders are specifying flame-retardant form factors that favor solid-state polymer development.
Sodium-Ion Battery Electrolyte Market Competitive Landscape
Listed leaders compete with private specialists across electrolyte formulation and qualification capabilities. The supplier base segments into vertically integrated cell manufacturers with captive electrolyte production, independent formulation houses with pre-certified salt-solvent portfolios, and regional specialists serving localized giga-factory projects. Strategic moves concentrate on long-term offtake contracting and cross-border qualification campaigns to secure procurement leverage.
Within the integrated cell manufacturer tier, Contemporary Amperex Technology Co. Limited exemplifies scale-driven pre-certification across multiple cell formats. HiNa Battery Technology Co. Ltd. and Faradion Limited occupy positions as technology specialists with differentiated approaches to anode-electrolyte interfaces and high-voltage organic salt formulations respectively. These three companies represent the dominant competitive archetypes shaping procurement dynamics and qualification timelines.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| HiNa Battery Technology Co. Ltd. |
| Faradion Limited |
| Altris AB |
| Natron Energy |
| TIAMAT SAS |
| Zhejiang Starry Pharmaceutical Co. Ltd. |
| Sichuan Xingneng New Materials Co. Ltd. |
| Shenzhen Highstar Electrical Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
China's GB/T 36276 thermal runaway propagation standards gate both supplier qualification timelines and price differentiation across sodium-ion electrolyte tiers, compressing margins for uncertified producers while amplifying premiums for pre-qualified formulation houses with captive sodium hexafluorophosphate synthesis.
Pricing Analysis
Certification level (GB/T 36276-qualified versus non-qualified) creates the primary spread between electrolyte suppliers, with qualified producers commanding contract premiums through five-year offtake agreements with tier-one battery integrators. Three-tier pricing structure across qualified-premium, standard-industrial, and spot-economy levels reflects purity thresholds and thermal stability test completion. Cost compression in the spot-economy tier is intensifying because cathode material producers in Hunan and Hubei provinces are consolidating procurement leverage. Grid-scale energy storage operators show lowest price sensitivity due to project financing requirements for qualified suppliers, while research institutions remain most price-sensitive with sub-commercial volumes.
Supply Chain Analysis
Strategic stockpiling of sodium hexafluorophosphate precursors dominates inventory strategy among non-Chinese cell producers seeking buffer against Hubei and Shandong province supply disruptions. Manufacturing concentration in China, South Korea, and Japan feeds global electrolyte formulation, with sodium hexafluorophosphate salt, carbonate solvent blends, and hard-carbon anode materials anchoring input dependencies. Single-source vulnerability in Chinese precursor manufacturing clusters exposes non-domestic producers to tariff escalation and export license uncertainty. Distribution runs through vertically integrated cell manufacturers with captive electrolyte production, independent formulation houses with pre-certified portfolios, and regional specialists serving localized giga-factory projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium-ion battery electrolyte sits in early-cycle expansion as grid storage procurement specifications diverge from lithium-ion requirements, with state-backed stationary storage deployment targets in China accelerating qualification timelines for pre-certified suppliers.
For Market Incumbents: Consolidate procurement leverage through long-term offtake contracting for sodium hexafluorophosphate before commercial scale-up concentrates buyer power among vertically integrated cell manufacturers. Deepen backward integration into captive salt synthesis in Zhejiang and Sichuan production clusters to defend margin position against REACH-constrained European entrants. Pre-certify electrolyte formulations across cylindrical, prismatic, and pouch cell formats to lock in switching costs before solid-state polymer alternatives mature. For New Entrants and Emerging Players: Lead with solid-state polymer electrolyte development for German and Australian utility tenders mandating flame-retardant form factors, where incumbents remain anchored to carbonate-based liquid formulations. Target marine electrification specifications from Rotterdam and Singapore port authorities as the most penetrable application segment, with non-flammability requirements filtering established suppliers lacking polymer expertise. Pursue joint development agreements with hard-carbon anode producers to optimize solid-electrolyte interphase engineering and accelerate cycle-life validation beyond 4,000 cycles. For Investors and Strategic Acquirers: EU Battery Regulation and REACH authorization timelines for fluorinated compounds reshape the acquisition landscape, favoring electrolyte houses with established chemical dossiers over experimental salt developers facing 18-24 month registration lags. Target formulation specialists with pre-qualified salt-solvent portfolios across multiple cell architectures, as qualification bottlenecks create durable competitive moats. Watch for cross-border mutual recognition agreements between China's SAMR and European regulators as the inflection signal determining manufacturing location decisions and customer access priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Sodium Hexafluorophosphate Synthesis | Backward integration into salt production insulates margin from Hubei and Shandong supply concentration. |
| Multi-Format Pre-Certification Campaign | UN 38.3 analog qualification across cylindrical, prismatic, and pouch cells locks in OEM switching costs. |
| Solid-State Polymer Scale-Up | Flame-retardant electrolyte production captures German and Australian utility tender specifications. |
| Hard-Carbon Anode Interface R&D Partnership | Solid-electrolyte interphase optimization extends cycle life beyond grid storage operator thresholds. |
| REACH Dossier Completion | Established chemical registration accelerates European market entry before novel substance timelines constrain competitors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and project development databases, combining interviews with electrolyte formulation executives, cathode material procurement leads, grid storage system integrators, and electrochemistry R&D directors with validation through SAMR GB standard documentation, ECHA REACH registration records, and utility tender specifications. Bottom-up volume estimates from cell manufacturer capacity announcements triangulate against top-down market sizing from stationary storage deployment pipelines and electric vehicle platform adoption timelines.
Segmentation dimensions modeled span electrolyte product type (organic liquid, solid-state polymer, aqueous, ionic liquid), application (energy storage systems, electric vehicles, consumer electronics, industrial equipment), end user (cell manufacturers, automotive OEMs, energy providers, research institutions), and form factor (liquid, solid, gel, semi-solid) across the projection horizon. CAGRs derive from electrolyte demand per gigawatt-hour of sodium-ion cell production, adjusted for cathode chemistry transitions and solid-state polymer penetration rates in grid storage tenders.
The analysis sits within stated boundaries; outcomes outside sustained lithium carbonate price volatility, accelerated solid-state polymer maturation, or harmonized sodium-ion transport certification protocols would require recalibration. Forecasts reflect assumptions regarding GB/T 36276 enforcement timelines, REACH authorization scope for fluorinated salts, and state-backed storage deployment targets in China. Revision becomes warranted when cross-border regulatory mutual recognition crosses implementation thresholds or solid-state polymer ionic conductivity exceeds 5 mS/cm at sub-zero temperatures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Asia Pacific Electric Vehicle VRLA Batteries Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Italy Rechargeable Battery Market
Batteries
Dry Cell Battery Market
Batteries
Military Battery Packs Market
Batteries
Deep Cycle Battery Market
Batteries
Australia Battery Market
Batteries
North America Industrial Battery Market
Batteries
Battery Maintainer Market
Batteries
VRLA Batteries Market
Batteries
India SLI Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
France Rechargeable Battery Market
Batteries
Leisure Battery Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market