
 Aluminum Based Battery Market | 2026-2036
Aluminum Based Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Based Battery Market Analysis
Market Context
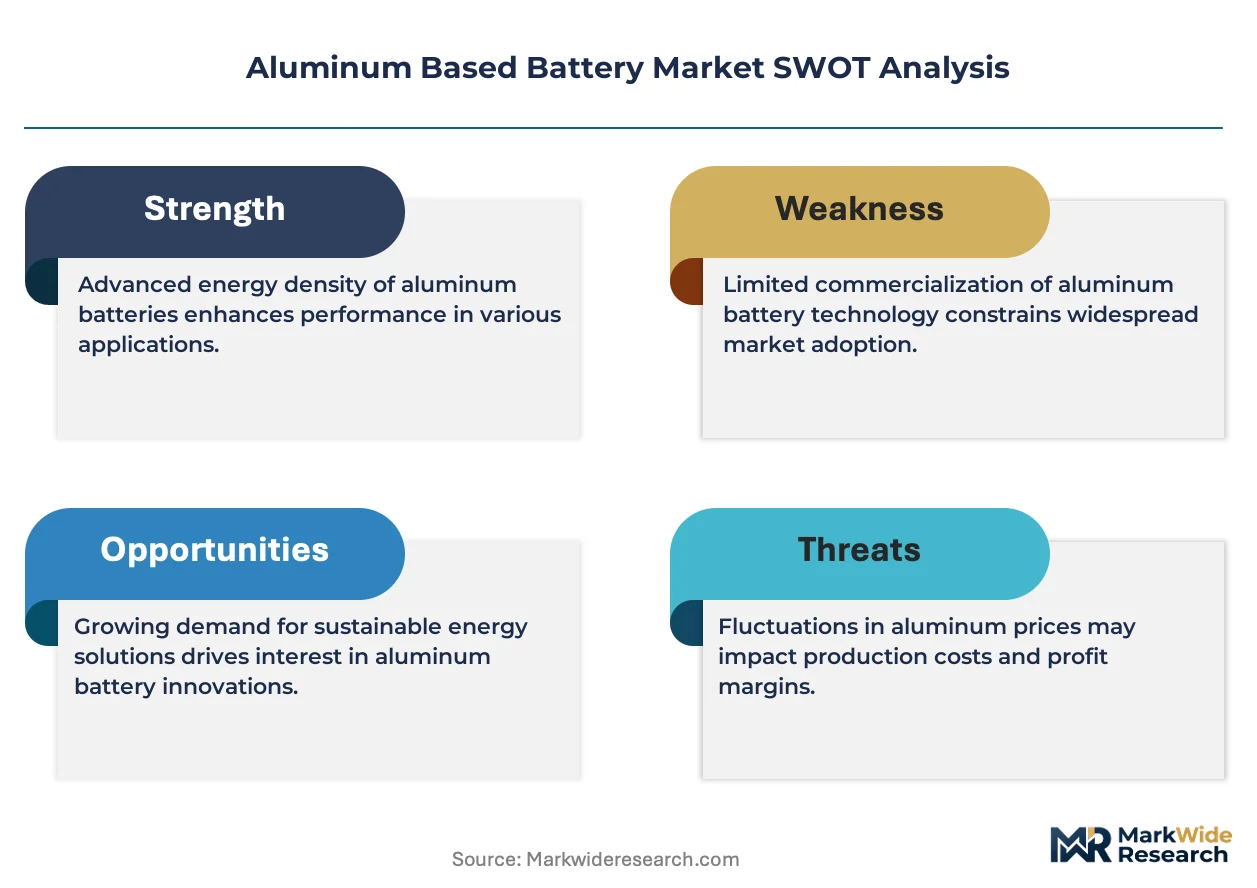
The aluminum based battery market is pivoting between premium aluminum-graphene formulations for aerospace and defense buyers and commodity aluminum-air cells for stationary grid storage. Phinergy anchors the premium tier through its aluminum-air technology leadership in military and backup power applications. Graphene Manufacturing Group competes with specialized graphene-enhanced cathode materials that extend cycle life for electric vehicle prototypes.
Technical Definition and Segment Structure
Aluminum based batteries utilize metallic aluminum anodes paired with diverse cathode chemistries—air, sulfur, ion-insertion oxides, or graphene composites—operating in aqueous or non-aqueous electrolytes with theoretical energy densities exceeding 1,000 Wh/kg for aluminum-air variants. Their primary purpose centers on decoupling energy storage from lithium supply chain constraints while leveraging aluminum's abundance and recyclability. Aluminum-ion product types occupy the fastest-growing structural position as automakers seek cobalt-free alternatives, while renewable energy storage applications concentrate margin pools through long-duration grid contracts requiring ultra-high capacity configurations.
Regulatory Framework
The EU Battery Regulation and REACH compliance frameworks mandate carbon footprint disclosure and recycled content thresholds that favor aluminum's established recycling infrastructure over lithium's nascent recovery networks. China's SAMR enforces GB standards for electrochemical safety testing that aluminum-based systems must satisfy for domestic grid deployment. Stakeholders must monitor how FERC interconnection rules in the United States treat novel battery chemistries for utility-scale storage procurement.
Market Dynamics
The aluminum based battery market is being fundamentally restructured by automakers' urgent search for cobalt-free chemistries that bypass lithium supply bottlenecks, forcing rapid cathode material innovation and electrolyte system redesign.
Growth Catalysts
- EU Battery Regulation:Carbon footprint disclosure mandates and recycled content thresholds favor aluminum's mature recycling infrastructure, accelerating OEM qualification timelines for aluminum-ion prototypes.
- Defense procurement:Military backup power requirements for forward operating bases are absorbing aluminum-air systems for their ultra-high energy density and silent operation profiles.
- Electrolyte chemistry advances:Ionic liquid formulations are suppressing aluminum dendrite formation, extending cycle life sufficiently for electric vehicle duty cycles.
Market Restraints
- Graphite supply concentration:High-purity graphite for graphene-enhanced cathodes sources primarily from China's Heilongjiang province, creating single-point vulnerability.
- Technical limitation:Aluminum-air systems suffer from electrolyte evaporation rates that degrade shelf life below commercial viability for consumer electronics.
- Substitution threat:Sodium-ion batteries from CATL and BYD are capturing the same cobalt-free, abundant-metal positioning at lower manufacturing complexity.
Strategic Opportunities
- India's stationary storage:CEA grid interconnection standards for long-duration batteries are creating first-mover windows for aluminum-air deployments at renewable hybrid parks.
- Maritime propulsion:Aluminum-water reaction systems for coastal ferries are emerging as a zero-emission alternative to hydrogen fuel cells in Nordic shipping corridors.
- US IRA manufacturing credits:Advanced energy project tax incentives are offsetting capital costs for domestic aluminum battery cell production facilities.
Industry Challenges
- Electrochemical engineering talent:The specialized workforce for aqueous aluminum battery R&D concentrates at a handful of national laboratories and spinouts, constraining scale-up velocity.
- UN 38.3 certification timelines:Transport safety testing for novel metal-air chemistries extends commercialization schedules by 18-24 months versus lithium-ion baselines.
- Legacy BMS incompatibility:Existing battery management system architectures designed for lithium voltage curves require complete redesign for aluminum-ion electrochemistry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Based Battery Market |
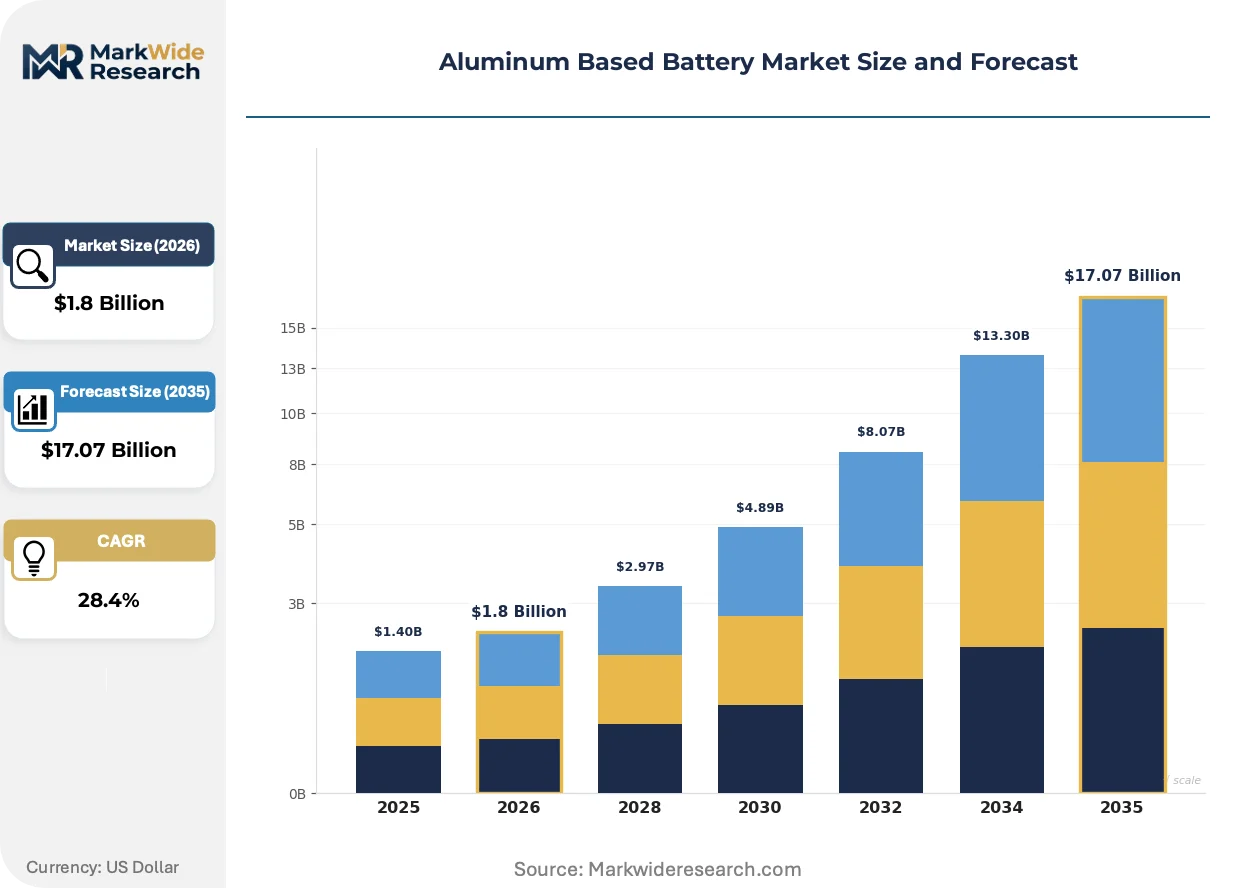
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum-Air, Aluminum-Ion, Aluminum-Sulfur, Aluminum-Graphene Application: Electric Vehicles, Portable Electronics, Renewable Energy Storage, Grid Management End User: Automakers, Electronics Manufacturers, Energy Providers, Military Applications Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra-High Capacity |
| Companies Covered | Graphene Manufacturing Group, Phinergy, Alcoa Corporation, Aluminum Corporation of China Limited, Ion Storage Systems, Fuji Pigment Co., Ltd., UACJ Corporation, Constellium SE, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Based Battery Market Emerging Trajectories
Aluminum battery technology is converging with solid-state electrolyte research and graphene manufacturing scale-up, compressing the gap between laboratory performance and automotive qualification standards.
Solid-state ceramic electrolytes are replacing aqueous systems in aluminum-sulfur configurations, eliminating hydrogen evolution side reactions that plagued earlier generations. BMW's battery research consortium in Munich is testing these cells for 2028 platform integration. This architecture is unifying the safety profile of solid-state lithium designs with aluminum's cost and abundance advantages.
China's GB/T standards for electrochemical energy storage safety are mandating nail penetration and thermal runaway propagation tests that aluminum-based systems must satisfy for domestic grid deployment. SAMR enforcement is tightening documentation requirements for electrolyte composition disclosure. Grid-scale integrators in Jiangsu and Guangdong provinces are prioritizing chemistries with pre-certified compliance pathways.
Automotive procurement departments are consolidating supplier relationships from multi-chemistry portfolios toward single-platform aluminum-ion partnerships, compressing vendor qualification from twelve suppliers to three per OEM. Tier 1 battery makers are responding with dedicated aluminum R&D centers. Germany's automotive corridor exhibits this concentration most acutely, with Volkswagen and Mercedes-Benz both reducing qualified cell sources.
Aluminum Based Battery Market Segmentation
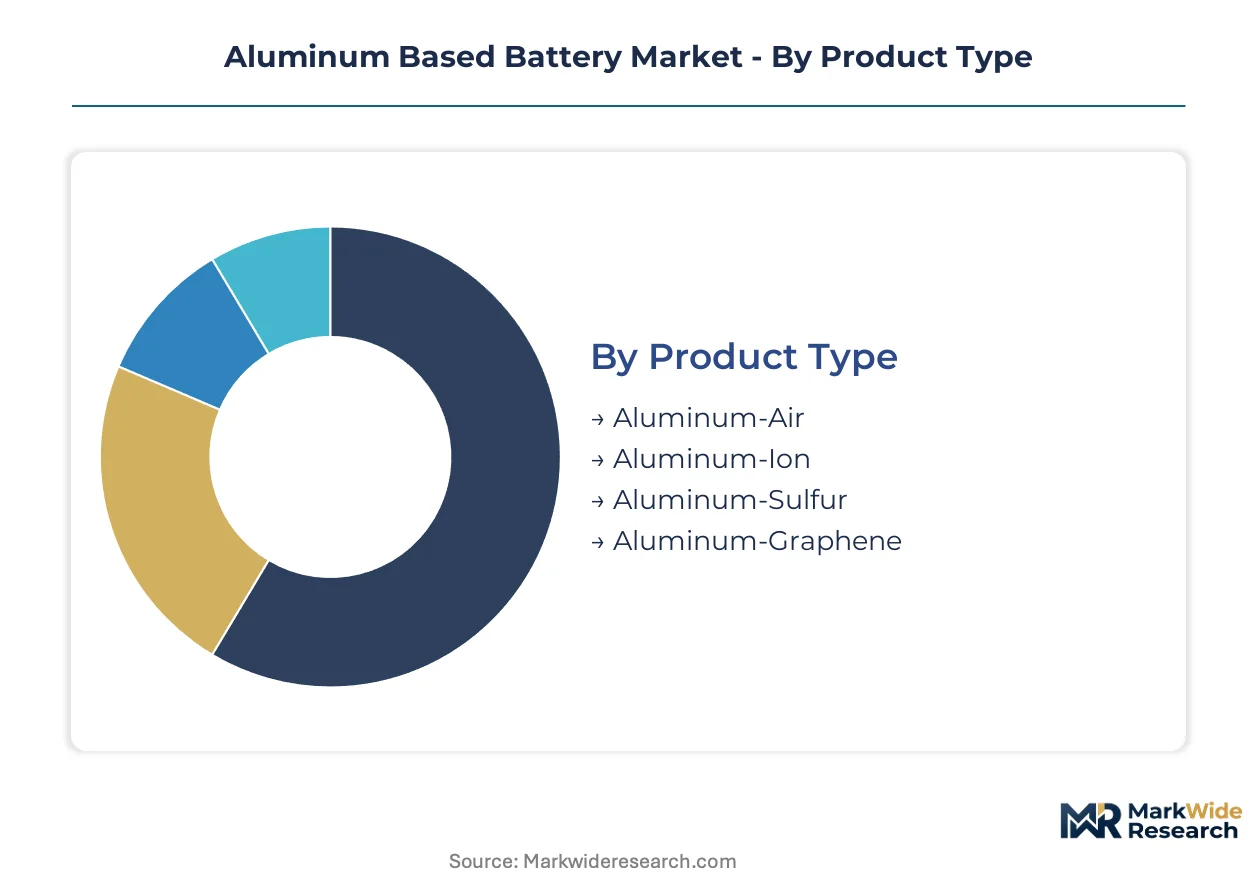
Aluminum based battery segmentation reveals divergent commercialization timelines across chemistries and applications. Product type and capacity configurations determine whether systems target automotive qualification or stationary grid contracts.
Product Type:
Automotive procurement departments weigh energy density against cycle life when selecting aluminum battery chemistries for platform integration.
- Aluminum-Ion:Reversible electrochemistry using aluminum intercalation into graphite or graphene cathodes enables thousands of cycles. BMW and Volkswagen prototype evaluations in Germany concentrate demand as automakers seek cobalt-free alternatives with lithium-ion-comparable rechargeability.
- Aluminum-Air:Primary cell architecture extracts energy from aluminum oxidation with ambient oxygen, delivering theoretical densities exceeding 1,000 Wh/kg. Military backup power applications absorb production from Phinergy and Israel-based developers for forward operating base silent power.
- Aluminum-Sulfur:Solid-state ceramic electrolyte variants eliminate hydrogen evolution side reactions. BMW's Munich research consortium tests these for automotive duty cycles.
- Aluminum-Graphene:Graphene-enhanced cathodes from Graphene Manufacturing Group extend cycle life through reduced aluminum dendrite formation. Aerospace and defense buyers pay premium pricing for ultra-light configurations.
Aluminum-Ion leads on scale through automotive partnerships; Aluminum-Air leads on momentum through defense procurement acceleration.
Application:
Application selection determines whether aluminum batteries compete on installed cost per kWh or gravimetric energy density.
- Electric Vehicles:OEM qualification timelines favor aluminum-ion systems with demonstrated 800+ cycle life. Germany's automotive corridor concentrates development resources as EU Battery Regulation carbon footprint mandates favor aluminum's recycling infrastructure.
- Renewable Energy Storage:Long-duration grid contracts at Indian hybrid renewable parks prioritize aluminum-air ultra-high capacity configurations. CEA interconnection standards create first-mover windows for 8+ hour discharge applications.
- Portable Electronics:Aluminum-air electrolyte evaporation rates degrade shelf life below commercial viability for consumer devices. Cycle life limitations constrain adoption.
- Grid Management:Utility-scale procurement in Jiangsu and Guangdong provinces prioritizes pre-certified GB/T compliant chemistries. SAMR enforcement tightens documentation requirements.
Electric Vehicles dominates current revenue; Renewable Energy Storage is climbing the fastest as grid operators contract for multi-day storage.
End User:
End user procurement sophistication varies from automotive BMS redesign requirements to military silent operation specifications.
- Automakers:BMW, Volkswagen, and Mercedes-Benz consolidate supplier relationships toward single-platform aluminum-ion partnerships. Tier 1 battery makers respond with dedicated aluminum R&D centers.
- Energy Providers:Grid-scale integrators in China and India prioritize chemistries with pre-certified compliance pathways for domestic deployment.
- Electronics Manufacturers:Consumer device OEMs await aluminum-air shelf life improvements before qualification.
- Military Applications:Forward operating base power requirements absorb aluminum-air production for silent, high-density backup. Defense procurement bypasses commercial cycle life constraints.
Automakers lead on scale through platform integration commitments; Military Applications leads on momentum through urgent operational requirements.
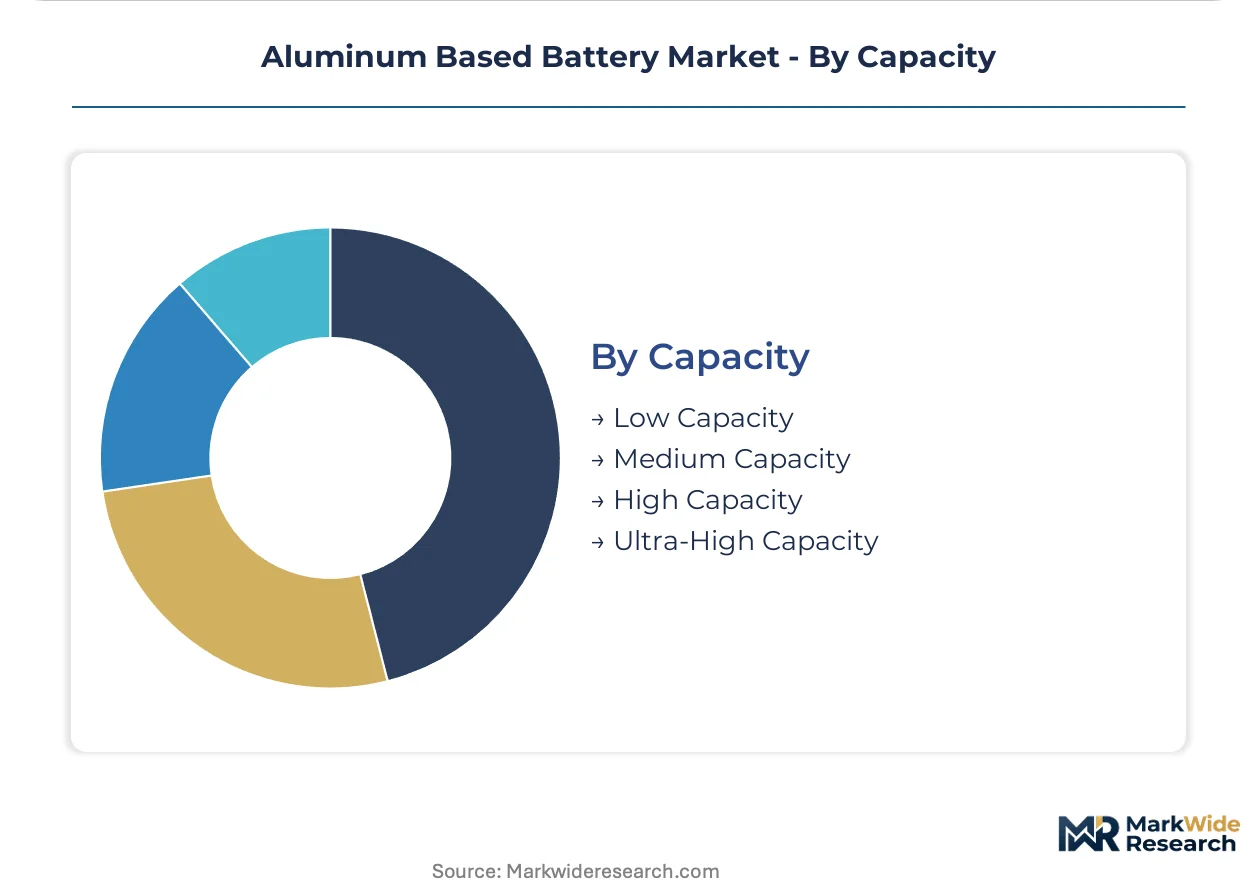
Capacity:
Capacity tiering separates automotive duty cycles from stationary grid contracts and portable power applications.
- High Capacity:50-200 kWh configurations target electric vehicle platforms with aluminum-ion electrochemistry. Automotive BMS architectures require complete redesign for aluminum voltage curves.
- Ultra-High Capacity:Grid-scale and maritime propulsion applications exceed 500 kWh with aluminum-air or aluminum-water reaction systems. Nordic shipping corridors evaluate coastal ferry zero-emission alternatives.
- Medium Capacity:Industrial backup and commercial microgrids utilize 10-50 kWh aluminum-sulfur solid-state configurations.
- Low Capacity:Sub-10 kWh portable and emergency power applications remain constrained by aluminum-air shelf life degradation.
High Capacity leads on scale through automotive volume commitments; Ultra-High Capacity leads on momentum through grid and maritime contract acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized electrochemical engineering talent concentrates at national laboratories in Germany, China, and the United States, anchoring regional R&D clusters that feed prototype development pipelines for automotive and defense applications.
China
Grid-scale integrators in Jiangsu and Guangdong provinces prioritize aluminum-based chemistries with pre-certified compliance pathways. SAMR enforces GB/T standards for electrochemical energy storage safety, mandating nail penetration and thermal runaway propagation tests. Yangtze River Delta battery manufacturers are scaling aluminum-ion cell production for domestic EV qualification timelines.
Germany
BMW, Volkswagen, and Mercedes-Benz consolidate supplier relationships toward single-platform aluminum-ion partnerships in Bavaria and Baden-Württemberg. The EU Battery Regulation carbon footprint disclosure mandates favor aluminum's mature recycling infrastructure over lithium recovery networks. Munich anchors BMW's battery research consortium testing solid-state aluminum-sulfur configurations for 2028 platform integration.
United States
Defense procurement for forward operating base silent power absorbs aluminum-air production from developers with military contracts. FERC interconnection rules for utility-scale storage procurement are treating novel battery chemistries under evolving frameworks. National laboratory spinouts in the Mountain West and Pacific Northwest concentrate aqueous aluminum battery R&D talent.
India
CEA grid interconnection standards for long-duration batteries are creating first-mover windows for aluminum-air deployments at renewable hybrid parks. The PLI scheme for advanced chemistry cell manufacturing is offsetting capital costs for domestic production facilities. Tamil Nadu and Gujarat industrial corridors are evaluating ultra-high capacity configurations for 8+ hour discharge applications.
Israel
Military backup power requirements for silent, high-density energy storage are absorbing aluminum-air system production from technology developers. The national defense procurement framework bypasses commercial cycle life constraints that limit civilian applications. Tel Aviv-area R&D clusters are advancing electrolyte chemistry formulations for aluminum-water reaction systems.
Aluminum Based Battery Market Vendor Landscape
Top-tier vendors anchor defense and aerospace procurement channels, while mid-tier specialists compete for automotive qualification slots and grid-scale integration contracts. The vendor base stratifies across premium aluminum-graphene formulations for aerospace buyers and commodity aluminum-air cells for stationary storage. Three archetypes dominate: vertically integrated aluminum producers with captive materials supply, graphene-enhanced cathode specialists, and primary aluminum-air developers for military applications. Competitive moves center on dedicated aluminum R&D center establishment and strategic partnerships with Tier 1 battery makers for OEM qualification.
Within the primary aluminum-air tier, Phinergy exemplifies defense-focused technology development for military backup power applications. Graphene Manufacturing Group occupies a position among graphene-enhanced cathode specialists extending cycle life for electric vehicle prototypes. Aluminum Corporation of China Limited represents the vertically integrated archetype, leveraging captive aluminum supply chains for cost positioning in grid-scale deployments.
| Leading Market Players |
|---|
| Graphene Manufacturing Group |
| Phinergy |
| Alcoa Corporation |
| Aluminum Corporation of China Limited |
| Ion Storage Systems |
| Fuji Pigment Co., Ltd. |
| UACJ Corporation |
| Constellium SE |
| Panasonic Corporation |
| Others |
Supply Flow & Price Mechanics
Captive aluminum supply chains anchored by state-backed smelters in China and integrated mining-conversion operations in Australia lock in raw material cost advantages for cell manufacturers, compressing input volatility and anchoring pricing power with producers who control upstream metal flows.
Pricing Analysis
Cell-plus-electrolyte bundling versus unbundled component sales splits the market between turnkey system integrators and specialized materials suppliers. Three-tier pricing structure across premium graphene-enhanced, standard aluminum-ion, and commodity aluminum-air tiers reflects cathode complexity and cycle life performance. Cost compression in the standard tier is intensifying because sodium-ion alternatives from CATL and BYD are forcing competitive repositioning. Grid-scale energy providers exhibit the highest price sensitivity due to capital-intensive procurement cycles, while defense buyers absorb premium pricing for silent-operation specifications.
Supply Chain Analysis
Electrochemical engineering talent shortages in Bavaria, Ontario, and Jiangsu provinces constrain production scale-up velocity for aqueous aluminum battery manufacturing. High-purity graphite for graphene-enhanced cathodes draws from China's Heilongjiang province and Mozambique's Balama operations, while aluminum feedstock rests on Australian bauxite and Chinese smelter capacity. Single-source vulnerability concentrates in spherical graphite processing for battery-grade anode materials. Distribution runs through Tier 1 battery maker partnerships for automotive qualification and direct military procurement channels for defense applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aluminum based battery market functions as a stable compounder underpinned by automakers' irreversible pivot toward cobalt-free chemistries that bypass lithium supply constraints.
For Market Incumbents: Deploy dedicated aluminum R&D center establishment as the primary lever to consolidate supplier relationships with BMW, Volkswagen, and Mercedes-Benz before sodium-ion alternatives capture automotive qualification slots. Secure captive graphite supply agreements with Heilongjiang processors to defend against cathode material shortages. Accelerate GB/T and UN 38.3 certification investment to compress commercialization timelines versus lithium-ion baselines. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer the lowest-friction route for aluminum-air system penetration at Indian renewable hybrid parks where CEA interconnection standards create first-mover windows. Target maritime propulsion applications in Nordic shipping corridors as the most penetrable segment given hydrogen fuel cell cost barriers. Pursue joint development agreements with national laboratory spinouts to access aqueous aluminum battery R&D talent pools. For Investors and Strategic Acquirers: Roll-up economics work for vertically integrated aluminum producers with captive smelter capacity because cathode material cost positioning determines cell manufacturing competitiveness. Five-to-ten year viability hinges on automotive platform integration commitments from German OEMs. Watch for sodium-ion battery pricing announcements from CATL and BYD as the critical inflection signal for aluminum-ion market share trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| GB/T Certification Pre-Qualification | Accelerates grid deployment in Jiangsu and Guangdong provinces under SAMR enforcement. |
| Graphene Cathode Supply Agreement | Locks in cycle life performance for BMW and Volkswagen prototype evaluations. |
| Solid-State Electrolyte Joint Venture | Enables aluminum-sulfur configurations that eliminate hydrogen evolution side reactions. |
| Defense Procurement Contract | Bypasses commercial cycle life constraints through military silent operation specifications. |
| Recycling Infrastructure Partnership | Leverages aluminum's mature recovery networks to satisfy EU Battery Regulation thresholds. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with battery research consortium directors, Tier 1 supplier procurement managers, grid integration specialists at CEA and FERC, and defense procurement officers with secondary validation against SEC filings from aluminum producers, EIA energy storage deployment data, SAMR GB/T standard documentation, and EU Battery Regulation impact assessments. Bottom-up cell production estimates and top-down automotive platform integration timelines were triangulated for consistency.
Historical reference periods spanning installed capacity growth, cathode material pricing volatility, and certification timeline benchmarks anchored the projection horizon. Segmentation modeling incorporated product type chemistry splits, application duty cycle requirements, end user procurement sophistication tiers, and regional regulatory cluster variations. CAGRs were derived from S-curve technology adoption patterns and automotive platform lifecycle commitments. Forecast inputs included ionic liquid electrolyte performance trajectories and solid-state ceramic electrolyte manufacturing yield assumptions.
The model assumes a particular technology adoption path; alternative pathways for sodium-ion battery commercialization would alter the outlook for aluminum-ion automotive market share. Forecasts reflect assumptions regarding EU Battery Regulation enforcement timing, FERC interconnection rule evolution, and defense procurement budget allocation. Material deviation in German OEM platform integration commitments or Chinese graphite export restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Industrial Backup Battery Market
Batteries
Japan Battery Market
Batteries
Power Battery Sealant Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Europe Battery Cell Market
Batteries
Drone Power Sources Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
Battery Terminal Brushes Market
Batteries
Global Primary Cells Market
Batteries
China Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Battery Anode Materials Market
Batteries
North America NMC Battery Pack Market
Batteries
SLI Battery Market