
 Battery Wash System Market | 2026-2036
Battery Wash System Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Wash System Market Insights
Aftermarket service revenue is reshaping profit pools in the Battery Wash System Market as fleet operators shift from capital purchases to subscription-based maintenance contracts. Carney Battery Handling Ltd. anchors its position through specialized engineering for heavy-duty forklift battery fleets. BHS, Inc. leverages integrated water recycling modules to differentiate its fixed-installation product line. Solus Group competes on geographic reach across North American material-handling corridors.
A battery wash system is industrial equipment engineered to clean electrolyte residue, corrosion deposits, and conductive contaminants from lead-acid and lithium-ion battery casings using controlled high-pressure water jets, chemical neutralization, or ultrasonic cavitation at specified flow rates and temperature thresholds. Its primary purpose is to prevent ground fault incidents, terminal degradation, and thermal runaway risks in high-cycle battery applications. Automated cleaning technology commands the dominant share of new installations as labor costs and throughput requirements intensify. Ultrasonic cleaning represents the fastest-expanding segment for precision battery refurbishment where cavitation reaches internal cell interconnects without mechanical abrasion. Fixed installation systems retain the deepest margin pools through long-term service agreements and consumables lock-in.
OSHA workplace exposure limits and EPA wastewater discharge standards in the United States compel closed-loop system architecture with neutralization tanks and filtration stages. Germany's REACH framework and the EU's RoHS directive restrict hazardous chemical formulations in battery cleaning agents, driving formulation substitution toward biodegradable surfactants. China's GB standards for industrial effluent enforce pH monitoring and heavy-metal capture in manufacturing-scale wash operations. Stakeholders must evaluate regulatory divergence across jurisdictions when configuring platform architectures and chemical supply chains for multi-region deployment.
Market Dynamics
Fleet electrification timelines and OSHA-mandated containment protocols are compressing capital deployment cycles for automated battery maintenance infrastructure across material-handling operations.
Growth Catalysts
- REACH chemical substitution mandates:Germany's ECHA framework is phasing out hazardous surfactants in battery cleaning formulations, forcing formulation innovation toward biodegradable alternatives that extend equipment service intervals.
- Warehouse automation intensity:Third-party logistics operators in the United States are deploying closed-loop wash systems to minimize forklift battery downtime in 24/7 fulfillment networks.
- Lithium-ion cell manufacturing corridors:Industrial battery producers around Shenzhen and Dongguan are scaling precision wash capacity to meet export certification requirements for European and North American automotive OEMs.
Market Restraints
- Stainless steel input volatility:Wash cabinet fabrication depends on austenitic steel grades subject to nickel price swings from Indonesian and Philippine concentrate supply.
- Neutralization chemistry concentration:Specialty chemical supply for pH balancing and heavy-metal capture concentrates among German and Japanese formulators, creating procurement bottlenecks.
- Ultrasonic generator technical limits:Cavitation frequency tuning for lithium-polymer cell architectures remains unresolved at production scale, constraining refurbishment throughput.
Strategic Opportunities
- Indian material-handling electrification:PLI scheme subsidies for forklift fleet modernization are creating first-mover openings for wash system integrators in Pune and Chennai industrial zones.
- Water recycling module convergence:Integration of membrane filtration and reverse osmosis into compact skid designs is enabling mobile wash deployment for distributed battery swap networks.
- EPA effluent rule tightening:Proposed revisions to Clean Water Act discharge limits for battery manufacturing facilities will mandate tertiary treatment upgrades, expanding aftermarket retrofit demand.
Industry Challenges
- Electrochemical process engineering talent scarcity:Wash system OEMs face recruitment gaps for specialists capable of optimizing neutralization kinetics across varying cell chemistries.
- UL 508A certification timelines:Control panel assembly approval for hazardous location installations extends lead times by four to six months, compressing project delivery windows.
- Legacy lead-acid infrastructure retrofit complexity:Existing wash pits and manual stations require structural modification to accommodate automated conveyor and robotics integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Wash System Market |
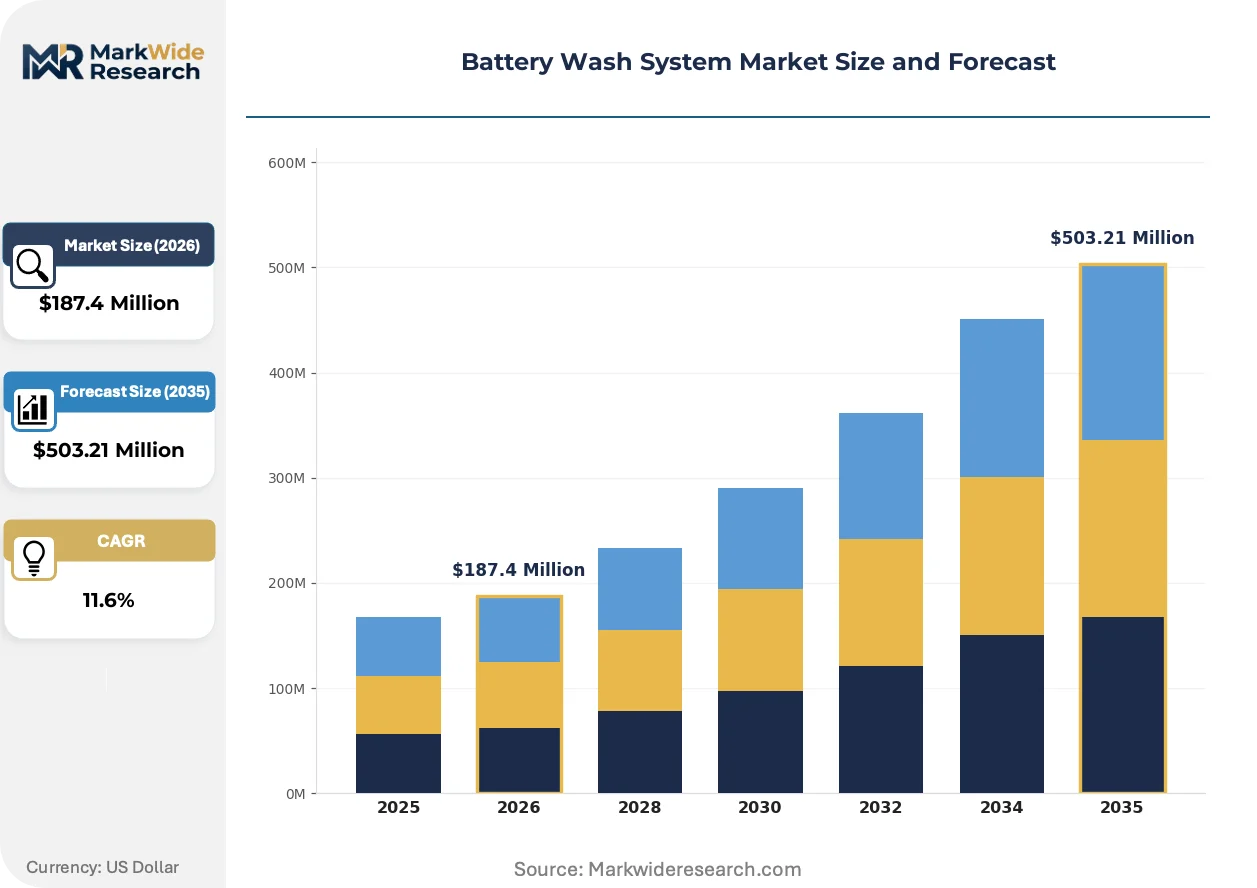
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable System, Fixed Installation, Automated Cleaning, Manual Wash Technology: High-Pressure Water Jet, Chemical Cleaning, Ultrasonic Cleaning, Thermal Wash End User: Automotive Industry, Aerospace Sector, Battery Manufacturers, Recycling Facilities Installation: Indoor Setup, Outdoor Setup, Mobile Units, Integrated Systems |
| Companies Covered | Carney Battery Handling Ltd., BHS, Inc., Solus Group, Sackett Systems, Inc., HPI Processes, Inc., Materials Transportation Company, NTB GROUP, Battery Spa, EcoClean Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Wash System Market Trends and Innovations
Equipment architecture is pivoting from standalone wash cabinets to integrated maintenance cells that combine cleaning, charging, and diagnostic functions in unified footprints.
Ultrasonic cavitation technology is hybridizing with conventional high-pressure spray systems to address contamination in battery terminal crevices and cell interconnects without mechanical abrasion. Tier-one automotive battery refurbishers in South Korea and Germany are piloting dual-mode configurations that switch between spray and cavitation based on residue conductivity readings. This convergence is compressing cycle times for precision cleaning applications while expanding addressable volumes in second-life battery processing.
EPA wastewater discharge standards under the Clean Water Act are tightening permissible limits for dissolved lead and sulfuric acid residuals from battery wash operations. Facilities in Michigan and Ohio industrial corridors face capital requirements for closed-loop neutralization and filtration stage additions. The regulatory pressure is accelerating equipment replacement cycles among independent battery service providers who previously operated open-loop discharge systems.
Subscription-based maintenance contracts are displacing outright equipment purchases among multi-site fleet operators seeking to convert battery wash capacity from capital expenditure to operating expense. Third-party logistics providers with national distribution networks are consolidating vendor relationships under single-source service agreements that bundle chemicals, consumables, and remote monitoring. This preference shift is most visible in the United States, where warehouse labor cost inflation is driving automation procurement through operating budgets rather than capital committees.
Battery Wash System Market Segmentation
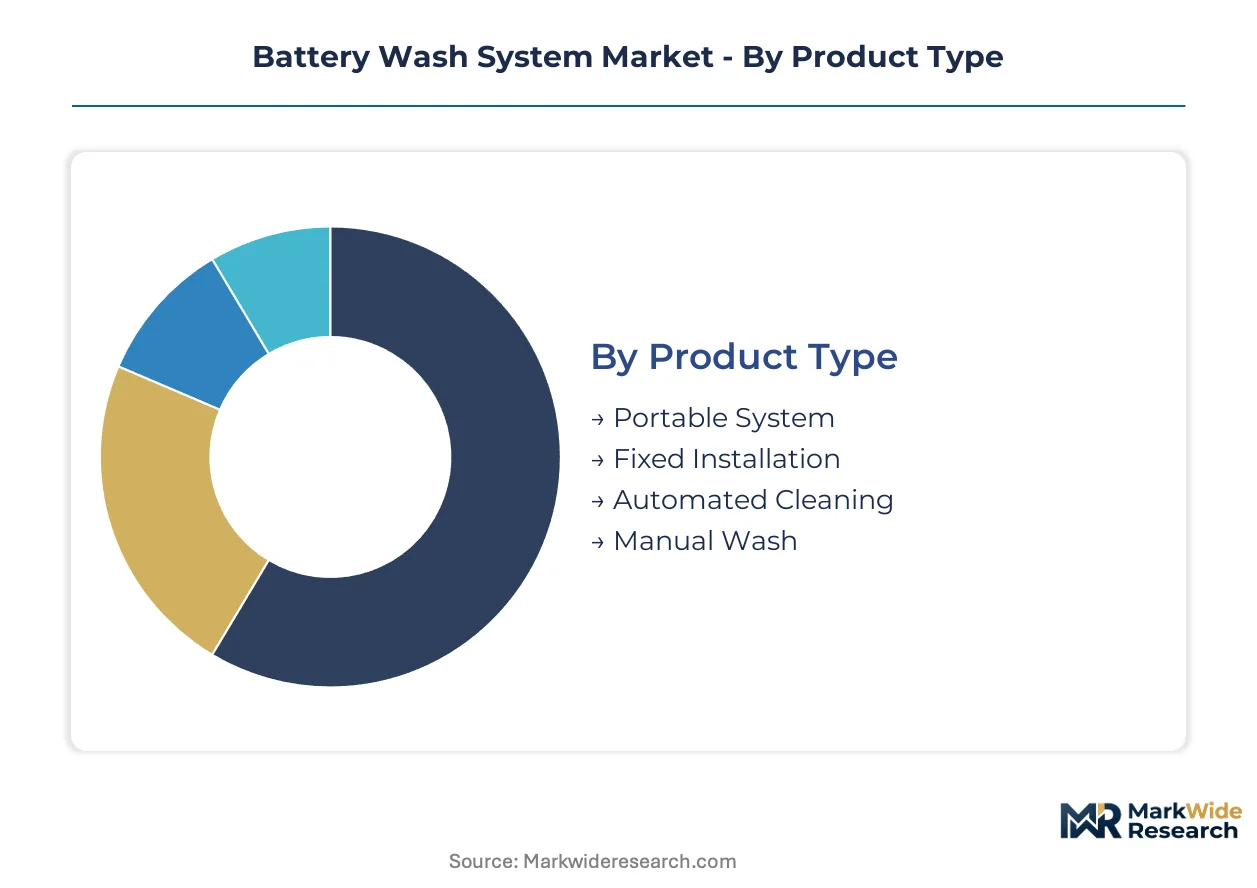
Battery wash system architecture fragments across four critical dimensions that determine procurement priorities and margin structure. Product type and technology choices lock in operational workflows, while end-user verticals and installation configurations dictate capital deployment patterns and service contract terms.
Product Type:
Use-case spectrum spans from distributed field maintenance to centralized high-throughput operations, with automation intensity and mobility requirements driving specification divergence.
- Automated Cleaning:Conveyor-fed systems integrate robotic handling, programmable wash cycles, and closed-loop water recovery for 24/7 material-handling fleets. Third-party logistics operators in the United States are consolidating procurement under single-source service agreements that bundle remote monitoring with chemical replenishment. The dominant share belongs to Automated Cleaning, while Portable System is closing the gap fastest.
- Fixed Installation:Permanent cabinet configurations anchor battery maintenance cells with stainless steel construction, neutralization tanks, and multi-stage filtration. German industrial corridors specify these systems to satisfy ECHA chemical containment mandates and REACH substitution requirements for biodegradable surfactants.
- Portable System:Skid-mounted or caster-based units enable distributed deployment across warehouse networks and remote mining operations. Indian material-handling electrification under PLI scheme subsidies is creating first-mover demand in Pune and Chennai industrial zones.
- Manual Wash:Operator-dependent stations with basic spray wands and gravity-fed drainage persist in legacy lead-acid service operations. OSHA-mandated containment retrofits are accelerating replacement cycles among independent battery service providers in Michigan and Ohio.
Fixed Installation retains the deepest margin pools through long-term consumables lock-in, though Automated Cleaning commands the dominant share of new capital deployment.
Technology:
Cleaning modality selection hinges on contamination chemistry, substrate sensitivity, and throughput requirements, with hybrid architectures gaining traction in precision applications.
- Ultrasonic Cleaning:Cavitation-based systems generate microscopic bubble collapse to penetrate terminal crevices and cell interconnects without mechanical abrasion. Tier-one automotive battery refurbishers in South Korea and Germany pilot dual-mode configurations switching between spray and cavitation based on residue conductivity readings. Ultrasonic Cleaning holds the technology leadership position, while Thermal Wash is gaining adoption slowest due to energy intensity constraints.
- High-Pressure Water Jet:Controlled spray systems deliver specified flow rates and temperature thresholds to remove electrolyte residue and corrosion deposits from lead-acid casings. Warehouse automation intensity across United States fulfillment networks is standardizing procurement around closed-loop variants with integrated water recycling.
- Chemical Cleaning:Formulation-based neutralization targets conductive contaminants and heavy-metal deposits through pH-balanced surfactant application. REACH framework restrictions on hazardous chemicals are forcing substitution toward biodegradable alternatives that extend equipment service intervals.
- Thermal Wash:Heated aqueous systems accelerate reaction kinetics for stubborn organic contamination in industrial battery refurbishment. Energy cost volatility and carbon intensity concerns constrain deployment outside subsidized manufacturing zones.
High-Pressure Water Jet anchors volume shipments, though Ultrasonic Cleaning exhibits the steepest expansion trajectory in second-life battery processing.
End User:
Vertical-specific contamination profiles and regulatory exposure create divergent specification requirements across the demand base.
- Battery Manufacturers:Original cell producers in Shenzhen and Dongguan industrial corridors scale precision wash capacity to meet export certification requirements for European and North American automotive OEMs. These facilities mandate tertiary treatment stages to satisfy China's GB standards for industrial effluent and heavy-metal capture.
- Automotive Industry:Vehicle OEMs and tier suppliers deploy wash systems for traction battery refurbishment and warranty remediation. EPA wastewater discharge standards under the Clean Water Act are tightening permissible limits for dissolved lead residuals from Michigan and Ohio operations.
- Recycling Facilities:End-of-life battery processors require aggressive contamination removal to enable safe dismantling and material recovery. Electrochemical process engineering talent scarcity constrains optimization of neutralization kinetics across varying cell chemistries.
- Aerospace Sector:Aviation battery maintenance operations prioritize precision cleaning for nickel-cadmium and lithium-ion aircraft cells with strict weight and dimensional tolerances. UL 508A certification timelines for hazardous location installations extend project delivery windows by four to six months.
Battery Manufacturers concentrate the highest throughput requirements, while Automotive Industry presents the most fragmented procurement landscape.
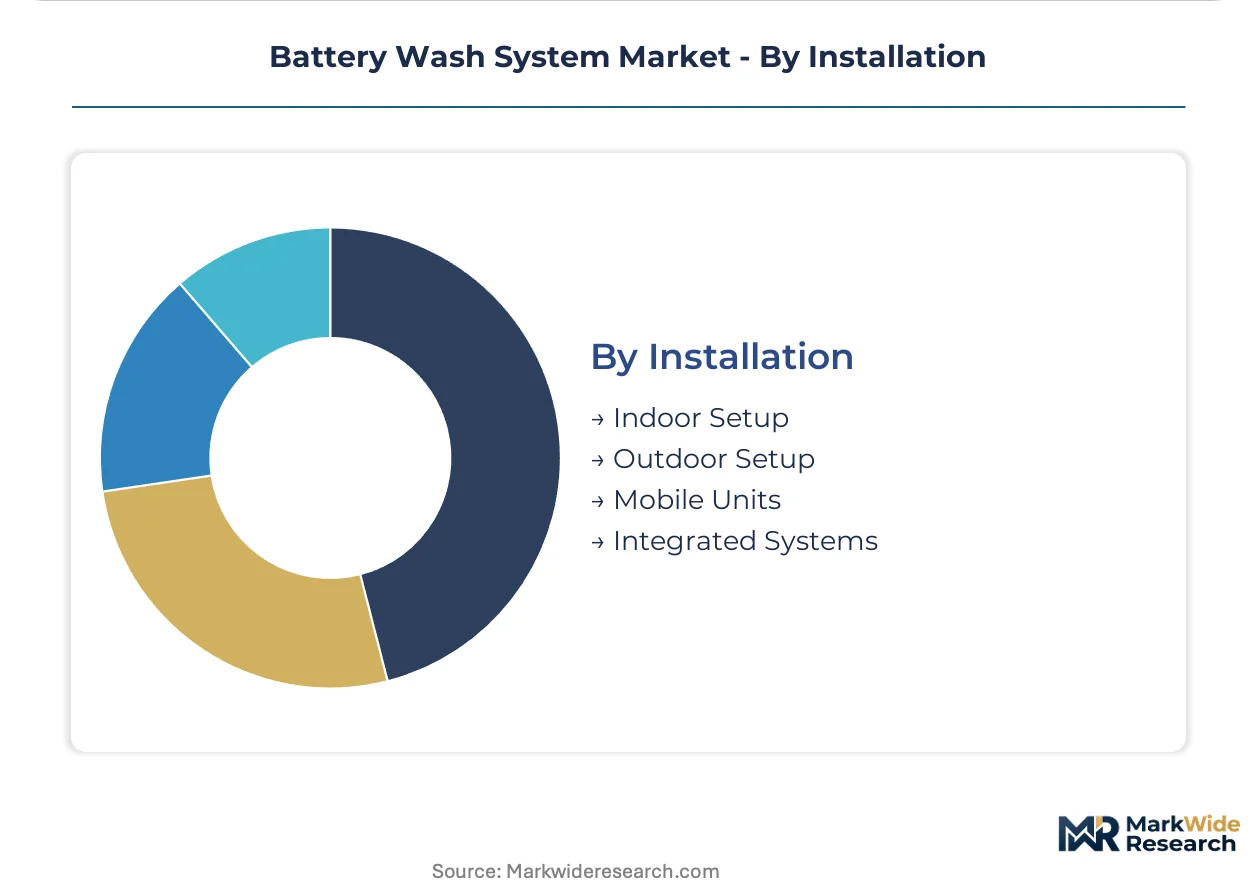
Installation:
Physical deployment configuration determines capital intensity, regulatory exposure, and service model economics.
- Integrated Systems:Unified maintenance cells combine cleaning, charging, and diagnostic functions within single footprints. Equipment architecture is pivoting from standalone wash cabinets toward these configurations as fleet operators seek to minimize battery downtime in 24/7 networks.
- Indoor Setup:Climate-controlled installations with dedicated ventilation and containment infrastructure dominate established industrial facilities. OSHA workplace exposure limits compel closed-loop architecture with neutralization tanks and filtration stages.
- Mobile Units:Trailer-mounted or containerized systems enable rapid deployment across distributed battery swap networks. Water recycling module convergence through membrane filtration and reverse osmosis is enabling compact skid designs for this segment.
- Outdoor Setup:Weather-hardened configurations serve mining, construction, and remote logistics operations with minimal infrastructure. Stainless steel input volatility from Indonesian and Philippine nickel concentrate supply creates fabrication cost uncertainty.
Indoor Setup retains the installed base majority, though Integrated Systems are displacing standalone configurations fastest among multi-site fleet operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate low price elasticity as regulatory mandates compel closed-loop system procurement, while Indian and Chinese operators remain highly sensitive to capital outlay and prioritize subsidized entry-level configurations.
United States
Third-party logistics operators with 24/7 fulfillment networks drive automated wash system deployment to minimize forklift battery downtime. OSHA workplace exposure limits and EPA wastewater discharge standards under the Clean Water Act mandate neutralization tanks and filtration stages. Michigan and Ohio industrial corridors face capital requirements for tertiary treatment upgrades as independent battery service providers accelerate replacement cycles.
Germany
Industrial corridors specify fixed-installation systems to satisfy ECHA chemical containment mandates and REACH substitution requirements for biodegradable surfactants. The ECHA framework phases out hazardous surfactants in battery cleaning formulations, forcing innovation toward biodegradable alternatives. Stuttgart and Munich manufacturing clusters anchor demand for precision wash capacity serving automotive OEM supply chains.
China
Industrial battery producers around Shenzhen and Dongguan scale precision wash capacity to meet export certification requirements for European and North American automotive OEMs. GB standards for industrial effluent enforce pH monitoring and heavy-metal capture in manufacturing-scale wash operations. The Pearl River Delta manufacturing corridor concentrates the highest throughput requirements for tertiary treatment stages.
India
PLI scheme subsidies for forklift fleet modernization create first-mover openings for wash system integrators in price-sensitive procurement environments. The country's national industrial policy provides capital expenditure support for material-handling electrification. Pune and Chennai industrial zones emerge as primary demand centers for skid-mounted portable units enabling distributed deployment.
South Korea
Tier-one automotive battery refurbishers pilot dual-mode ultrasonic-spray configurations for second-life battery processing. The national industrial regulator enforces stringent effluent standards for battery manufacturing facilities. Seoul and Gyeonggi-do industrial clusters concentrate precision cleaning applications for lithium-ion cell export certification.
Battery Wash System Market Competitive Landscape
Specialist engineering houses and diversified material-handling equipment suppliers split the market between premium fixed-installation systems and mobile service platforms. The vendor base organizes around three strategic archetypes: heavy-duty fleet specialists leveraging long-term service agreements, integrated water recycling technology providers capturing margin through consumables lock-in, and geographic coverage players consolidating distributed maintenance contracts. Dominant competitive moves include backward integration into stainless steel fabrication to offset nickel price volatility, and strategic partnerships with third-party logistics operators for national service contract consolidation.
Among North American service-focused operators, Carney Battery Handling Ltd., BHS, Inc., and Solus Group exemplify distinct strategic positioning within the competitive structure. Carney Battery Handling Ltd. anchors the heavy-duty specialist archetype through engineering depth for industrial forklift battery fleets. BHS, Inc. occupies a position within the integrated technology tier, with its corporate structure suggesting capacity for water recycling module development. Solus Group represents the geographic coverage archetype, with its naming convention indicating a service-network orientation across material-handling corridors. These three entities collectively illustrate how competitive differentiation fragments across engineering specialization, technology integration, and geographic reach rather than concentrating in any single capability domain.
| Leading Market Players |
|---|
| Carney Battery Handling Ltd. |
| BHS, Inc. |
| Solus Group |
| Sackett Systems, Inc. |
| HPI Processes, Inc. |
| Materials Transportation Company |
| NTB GROUP |
| Battery Spa |
| EcoClean Systems |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's stainless steel fabrication corridors is compressing margin pools for wash cabinet OEMs while simultaneously extending supplier payment horizons. This utilization imbalance grants procurement leverage to system integrators in Germany and the United States, who now demand 90-day terms and bundled chemical replenishment contracts.
Pricing Analysis
After-sales service revenue through multi-year maintenance contracts now drives lifetime value for fixed-installation system vendors. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified hazardous-location configurations from basic indoor setups and entry-level portable skids. Cost compression in the economy tier is intensifying because Indian PLI-subsidized operators prioritize capital-light procurement. Battery manufacturers in Shenzhen and Dongguan exhibit the lowest price sensitivity due to export certification requirements, while independent service providers in Michigan and Ohio face acute budget constraints.
Supply Chain Analysis
Extended payment terms from 60 to 120 days are becoming standard for stainless steel fabricators serving wash cabinet OEMs. Supply concentrates in China for austenitic steel grades, Germany for precision ultrasonic generator components, and Japan for specialty neutralization chemistry. Fabrication draws from nickel concentrate originating in Indonesia and the Philippines, with pH-balancing agents sourced from German and Japanese formulators. Single-source vulnerability in cavitation frequency control modules creates procurement risk. Distribution runs through direct OEM sales for large fleet operators and regional distributor networks for independent service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is approaching a platform-economics inflection as integrated maintenance cells converge cleaning, charging, and diagnostic functions into unified footprints. Interoperability standards for remote monitoring APIs are fragmenting vendor lock-in strategies.
For Market Incumbents: Pre-empt portable system encroachment by embedding water recycling modules into compact skid designs for distributed deployment. Defend margin position through captive supply of biodegradable surfactant formulations that extend equipment service intervals. Consolidate national service contracts with third-party logistics operators before subscription-based procurement becomes universal.
For New Entrants and Emerging Players: Pursue first-mover positioning in India's PLI-subsidized material-handling electrification corridor around Pune and Chennai. Target battery swap network operators seeking mobile wash deployment with membrane filtration-enabled compact units. Establish go-to-market partnerships with regional stainless steel fabricators to bypass established OEM distribution channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable and mobile system segments as water recycling module convergence reduces filtration stage costs. Long-term viability favors vendors with integrated technology stacks spanning hardware, consumables, and remote diagnostics. Acquisition targets should demonstrate installed base density in 24/7 fulfillment networks. Watch for EPA Clean Water Act tertiary treatment rule finalization as inflection signal for aftermarket retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive supply of austenitic grades insulates margin from Indonesian nickel price volatility. |
| Water Recycling Module Convergence | Membrane filtration and reverse osmosis integration enables mobile deployment for distributed swap networks. |
| Biodegradable Surfactant Formulation Lock-in | REACH-compliant chemistry substitution creates recurring consumables revenue with extended service intervals. |
| Remote Monitoring API Standardization | Interoperability platforms fragment vendor lock-in and accelerate subscription-based contract adoption. |
| Mobile Skid Design Miniaturization | Compact filtration architectures penetrate Indian PLI-subsidized electrification corridors in Pune and Chennai. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with maintenance directors at third-party logistics operators, plant engineers at battery manufacturing facilities, aftermarket service heads at forklift fleet operators, and procurement leads at industrial battery distributors; alongside secondary validation through EPA effluent discharge filings, OSHA workplace exposure limit updates, ECHA REACH substance restriction announcements, and customs trade data for stainless steel wash cabinet imports. Bottom-up triangulation across equipment shipment records and top-down reconciliation against capital expenditure disclosures from listed material-handling operators anchored volume estimates.
Forecast inputs span product type automation intensity, technology modality adoption curves, end-user vertical throughput requirements, and installation configuration mobility preferences across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macroeconomic industrial production indices and regulatory compliance timeline acceleration. Industry-specific inputs include lithium-ion cell manufacturing capacity expansion in the Pearl River Delta and PLI scheme implementation pace for Indian forklift electrification.
Sensitivities concentrate around nickel price volatility, EPA effluent rule finalization timing, and ultrasonic cavitation frequency breakthroughs for lithium-polymer architectures. Forecasts reflect assumptions regarding regulatory enforcement continuity and stainless steel supply chain stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Power Battery Cells Market
Batteries
East Europe Battery Market
Batteries
Romania Rechargeable Battery Market
Batteries
Medical Batteries Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Sodium Nickel Chloride Battery Market
Batteries
GCC Rechargeable Battery Market
Batteries
Iron Salt Battery Market
Batteries
Forklift Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
Global Industrial Lead Acid Battery Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
Battery Anode Materials Market
Batteries
Automotive Start-Stop Battery Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Australia Battery Market