
 Sodium-Air Battery Market | 2026-2036
Sodium-Air Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium-Air Battery Market Analytics
Utility-scale buyers and defense contractors are bifurcating demand from consumer electronics purchasers as the dominant procurement archetype in sodium-air battery development. Faradion anchors its position through captive sodium sourcing relationships and British materials science heritage. Solid Power differentiates via solid-state electrolyte architectures that reduce dendrite formation risks. IBM Corporation leverages its quantum computing and AI simulation capabilities to compress electrochemical discovery cycles for cathode materials.
A sodium-air battery electrochemically reduces oxygen at a porous carbon cathode while oxidizing metallic sodium at the anode, achieving theoretical energy densities exceeding 1,600 Wh/kg through the formation of sodium superoxide or peroxide discharge products. The technology primarily serves long-duration stationary storage and heavy electric mobility applications where gravimetric efficiency outweighs cycle-life requirements. Secondary battery configurations now attract the majority of pilot funding as engineers solve reversibility challenges in the sodium-oxygen reaction pathway. Solid-state technology segments command attention from automotive OEMs seeking thermal runaway immunity, while liquid electrolyte variants sustain near-term cost advantages for grid storage integrators targeting 8-12 hour discharge durations.
The US Department of Energy and Germany's KBA shape product standards through battery safety certification protocols and vehicle-type approval requirements that increasingly reference alternative chemistries. Japan's METI funds domestic solid-state sodium battery consortia under its green transformation industrial policy, tightening supply chain localization rules for subsidy eligibility. Stakeholders must monitor which regulatory jurisdictions first mandate sodium-based content thresholds in public procurement tenders, as these decisions will lock in manufacturing location advantages before production scale crystallizes.
Market Dynamics
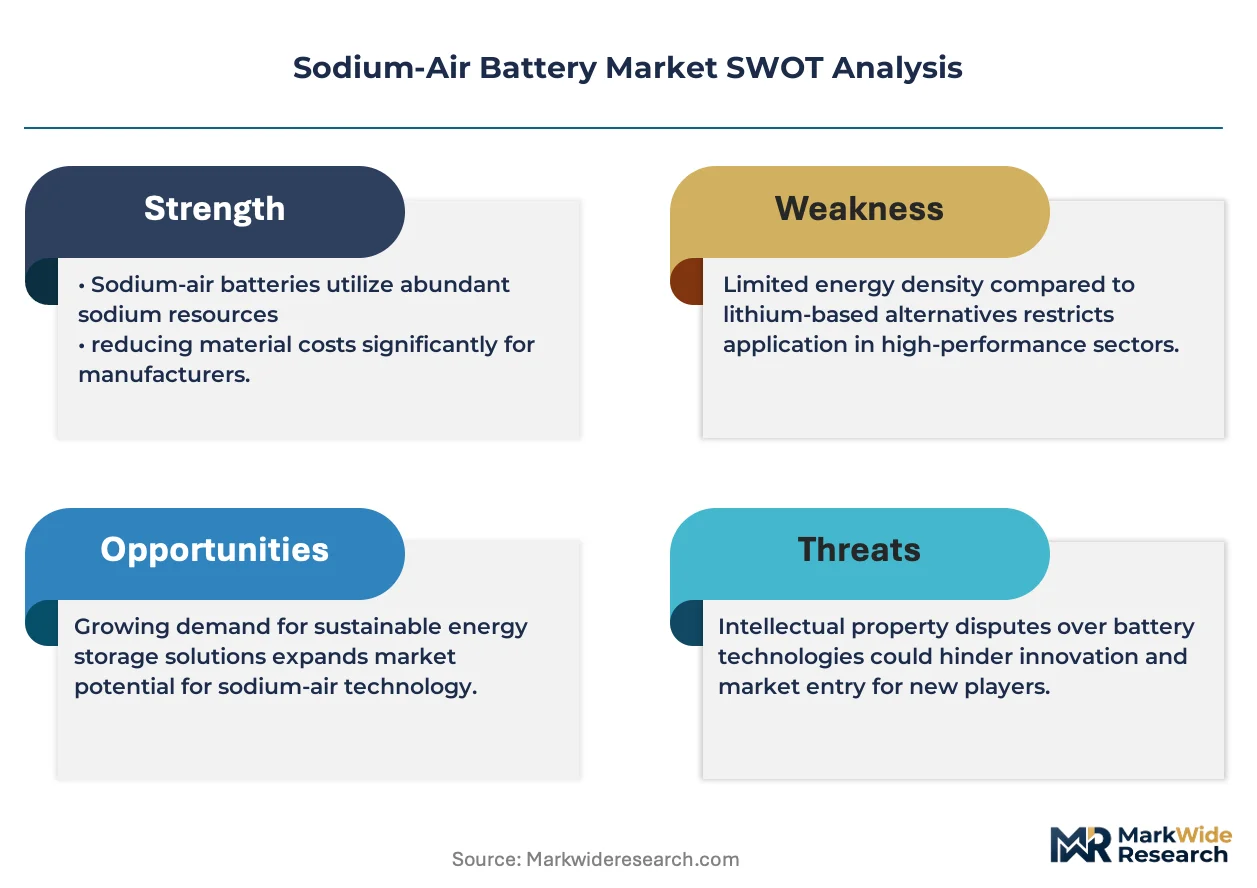
Solid-state electrolyte maturation is compressing development timelines for sodium-air systems, while Germany's KBA safety certification protocols and Japan's METI-funded consortia actively reshape where production capacity crystallizes.
Growth Catalysts
- Automotive OEM Substitution Pressure:Electric vehicle manufacturers in Germany are diversifying beyond lithium-ion dependencies as KBA vehicle-type approval frameworks expand alternative chemistry pathways.
- Stationary Storage Duration Requirements:Grid integrators targeting 8-12 hour discharge durations favor sodium-air theoretical energy density advantages over lithium-ion cost curves.
- Japan's Green Transformation Industrial Policy:METI-funded domestic solid-state sodium battery consortia tighten supply chain localization rules, accelerating captive sodium sourcing investments.
Market Restraints
- Reversibility Engineering Costs:Secondary battery configurations require substantial capital to solve sodium-oxygen reaction pathway degradation, compressing near-term commercialization margins.
- Metallic Sodium Supply Concentration:Captive sodium sourcing relationships concentrate among limited chemical processors, exposing value chains to input volatility.
- Thermal Runaway Certification Barriers:Solid-state variants face extended validation timelines against evolving battery safety certification protocols across multiple jurisdictions.
Strategic Opportunities
- Defense Contractor Procurement Channels:Long-duration energy density requirements for military mobility applications create dedicated demand streams separate from civilian automotive qualification cycles.
- US Inflation Reduction Act Content Thresholds:Domestic battery value chain buildout incentives reward manufacturing location decisions before production scale crystallizes.
- Quantum-Accelerated Materials Discovery:AI simulation convergence with electrochemical modeling compresses cathode material development cycles beyond traditional experimental timelines.
Industry Challenges
- Solid-State Manufacturing Scale-Up:Thin-film electrolyte deposition equipment requires specialized cleanroom infrastructure absent from conventional lithium-ion production facilities.
- Cross-Chemistry Talent Scarcity:Electrochemists with sodium-specific expertise remain concentrated in academic research institutes rather than commercial engineering functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium-Air Battery Market |
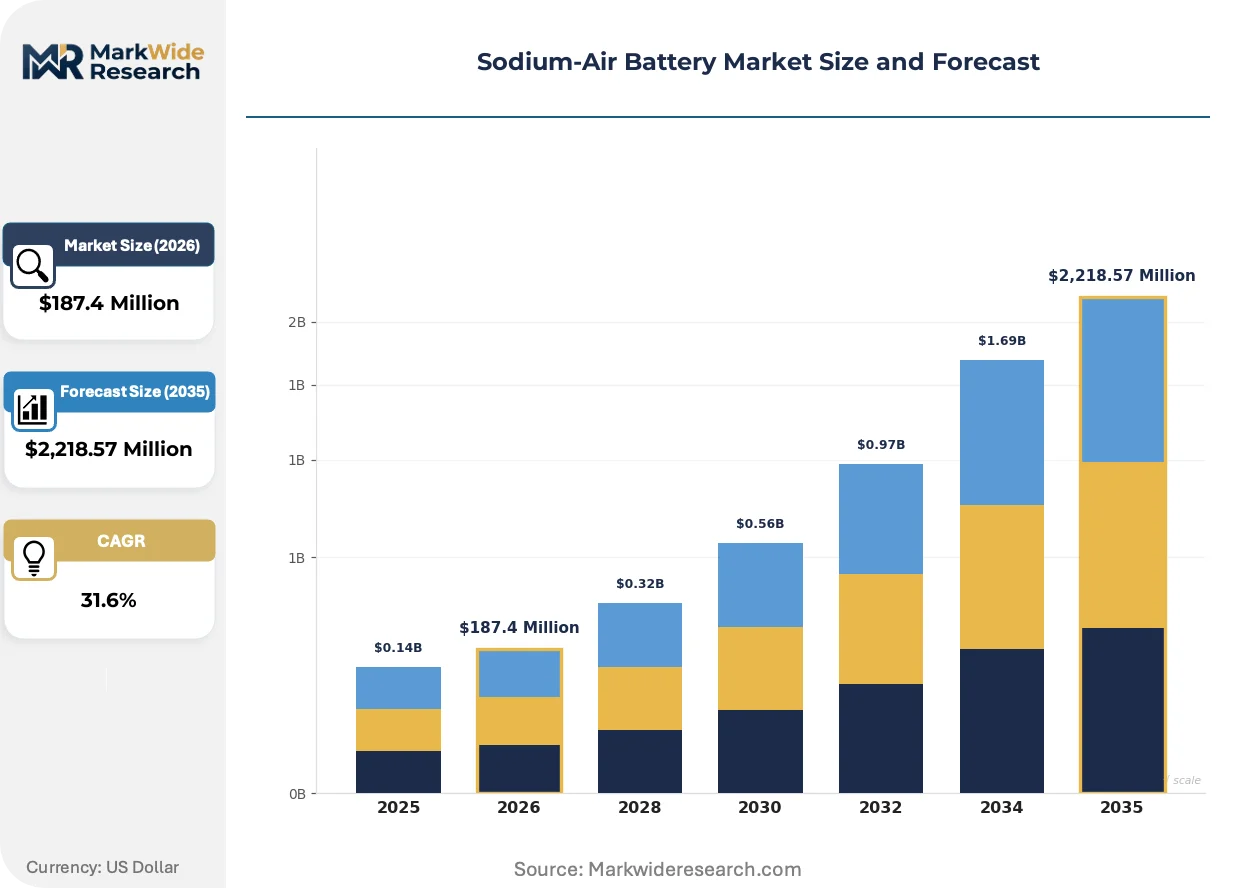
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Battery, Secondary Battery, Rechargeable Battery, Non-Rechargeable Battery Technology: Liquid Electrolyte, Solid State, Hybrid System, Nano-Structured End User: Consumer Electronics, Electric Vehicles, Renewable Energy Storage, Grid Storage Installation: Portable Systems, Stationary Systems, Integrated Units, Standalone Units |
| Companies Covered | IBM Corporation, Solid Power, Sion Power Corporation, Faradion, Johnson Matthey, PolyPlus Battery Company, NOHMs Technologies, Echogen Power Systems, WattJoule Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium-Air Battery Market Evolving Landscape
Three distinct vectors are reshaping sodium-air battery development: electrolyte architecture divergence, regulatory jurisdiction competition for manufacturing location, and procurement archetype specialization between utility-scale and defense applications.
Solid-state electrolyte technology is bifurcating development pathways across the sodium-air landscape. Ceramic and glass-ceramic architectures reduce dendrite formation risks while enabling thermal runaway immunity. Automotive OEMs in Germany and Japan are prioritizing solid-state configurations for electric mobility platforms despite higher unit costs. This technology divergence is compressing qualification timelines for liquid electrolyte variants in grid storage applications where 8-12 hour duration economics dominate safety premiums.
Germany's KBA battery safety certification protocols are expanding reference standards to include alternative chemistries beyond lithium-ion baselines. The industrial consequence accelerates vehicle-type approval pathways for sodium-air systems in European automotive supply chains. Heavy electric mobility segments are responding fastest, with German OEMs integrating sodium-air pilot lines into domestic battery value chain buildout strategies.
Utility-scale buyers and defense contractors are consolidating as the dominant procurement archetype, displacing consumer electronics purchasers from sodium-air development roadmaps. Long-duration stationary storage integrators and military mobility program offices now command dedicated engineering resources previously allocated to portable device applications. This concentration is most visible in Germany and Japan, where national industrial policies explicitly exclude consumer-grade applications from green transformation subsidy eligibility.
Sodium-Air Battery Market Segmentation
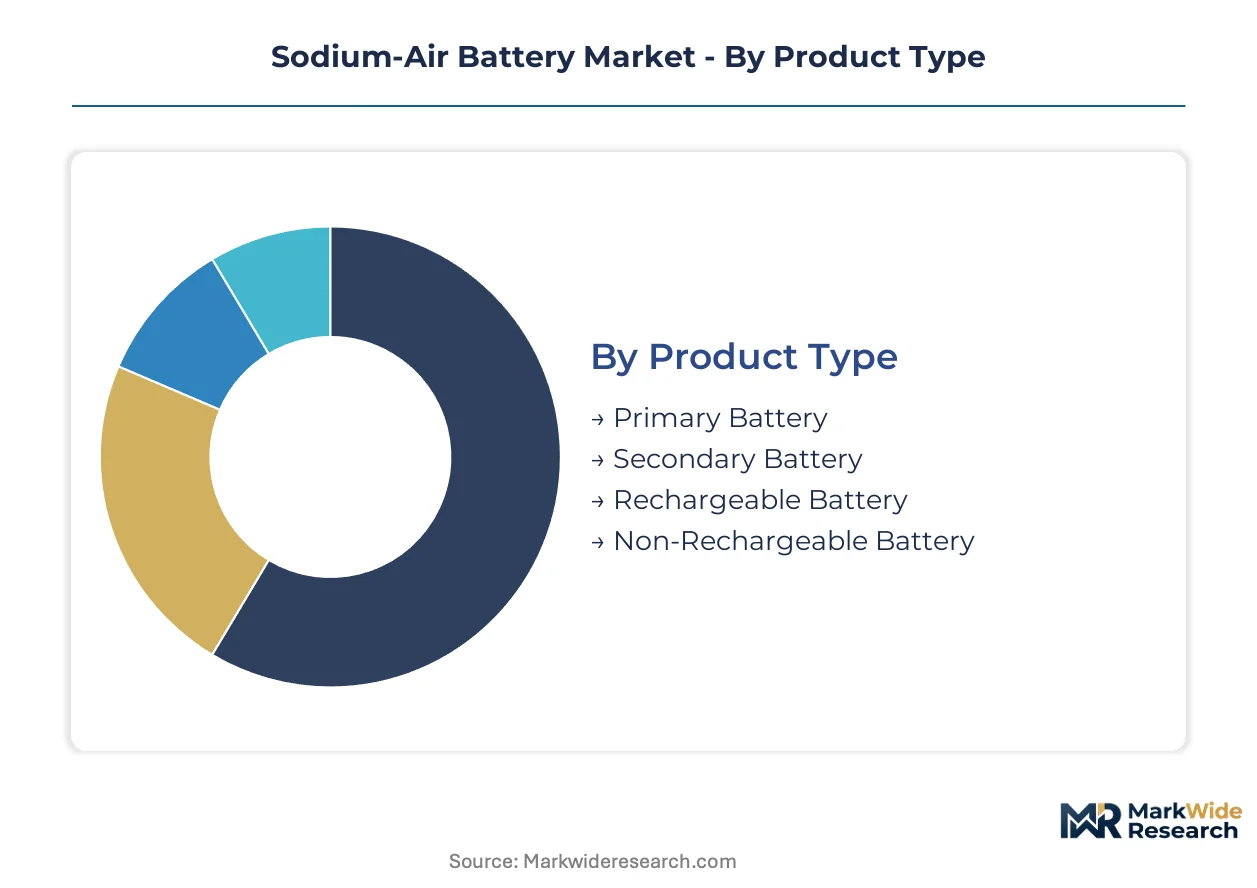
Sodium-air battery segmentation reveals how electrochemical architecture, deployment scale, and customer procurement patterns fragment commercial opportunity. Manufacturers align R&D budgets against segments where theoretical energy density advantages translate into defendable margin pools.
Product Type:
Secondary configurations concentrate the highest margin pools as automotive OEMs and grid integrators fund reversibility engineering solutions.
- Primary Battery:Single-discharge electrochemical systems deliver sodium-oxygen reactions without recharge infrastructure. Defense contractors in Germany source these for expeditionary power where resupply logistics outweigh cycle-life economics.
- Secondary Battery:Reversible sodium-oxygen chemistry enables repeated charge-discharge cycles through controlled superoxide-peroxide phase management. Pilot funding from Japan's METI consortia targets this segment for electric mobility qualification timelines.
- Rechargeable Battery:Engineered for deep-cycle durability with modified cathode porosity to accommodate discharge product volume expansion. Grid storage developers in Germany favor these for 8-12 hour duration applications.
- Non-Rechargeable Battery:Optimized for maximum gravimetric energy density without electrode regeneration complexity. Remote sensing and underwater vehicle applications drive procurement in defense channels.
The dominant share belongs to Secondary Battery, while Rechargeable Battery is closing the gap fastest.
Technology:
Cost tier stratification separates premium solid-state architectures from liquid electrolyte systems competing on near-term manufacturing scale.
- Liquid Electrolyte:Conventional ionic conductivity through organic solvent-based sodium salt solutions. German grid integrators deploy these for stationary systems where thermal management infrastructure offsets safety certification premiums.
- Solid State:Ceramic or glass-ceramic sodium-ion conductors eliminate dendrite formation and thermal runaway pathways. Japanese automotive OEMs prioritize this technology for vehicle-type approval under METI-funded development programs.
- Hybrid System:Combines liquid electrolyte ionic conductivity with solid-state interfacial stabilization layers. Research institutes in Korea advance this architecture to bridge performance-cost gaps.
- Nano-Structured:Engineered cathode porosity and anode surface architecture at sub-micron scales to enhance reaction kinetics. IBM's quantum-accelerated materials discovery targets this segment for cathode optimization.
Solid State commands premium positioning, yet Liquid Electrolyte retains volume leadership through faster manufacturing scale-up.
End User:
Application-driven demand concentration shifts procurement archetypes away from consumer electronics toward heavy infrastructure and mobility platforms.
- Electric Vehicles:Heavy electric mobility platforms exploit sodium-air gravimetric efficiency for extended range applications. Germany's KBA vehicle-type approval frameworks actively expand alternative chemistry pathways for domestic OEMs.
- Grid Storage:Long-duration stationary systems leverage theoretical energy density for 8-12 hour discharge economics. Utility-scale buyers in Germany consolidate procurement specifications around liquid electrolyte configurations.
- Renewable Energy Storage:Coupled with wind and solar generation assets to buffer intermittency through electrochemical discharge. Japan's green transformation industrial policy excludes this segment from consumer-grade subsidy restrictions.
- Consumer Electronics:Portable device applications have lost engineering priority as sodium-air development concentrates on larger-format systems. National industrial policies in Germany and Japan explicitly omit this end user from funded consortia.
Grid Storage anchors current deployment, though Electric Vehicles is expanding most quickly through automotive OEM diversification strategies.
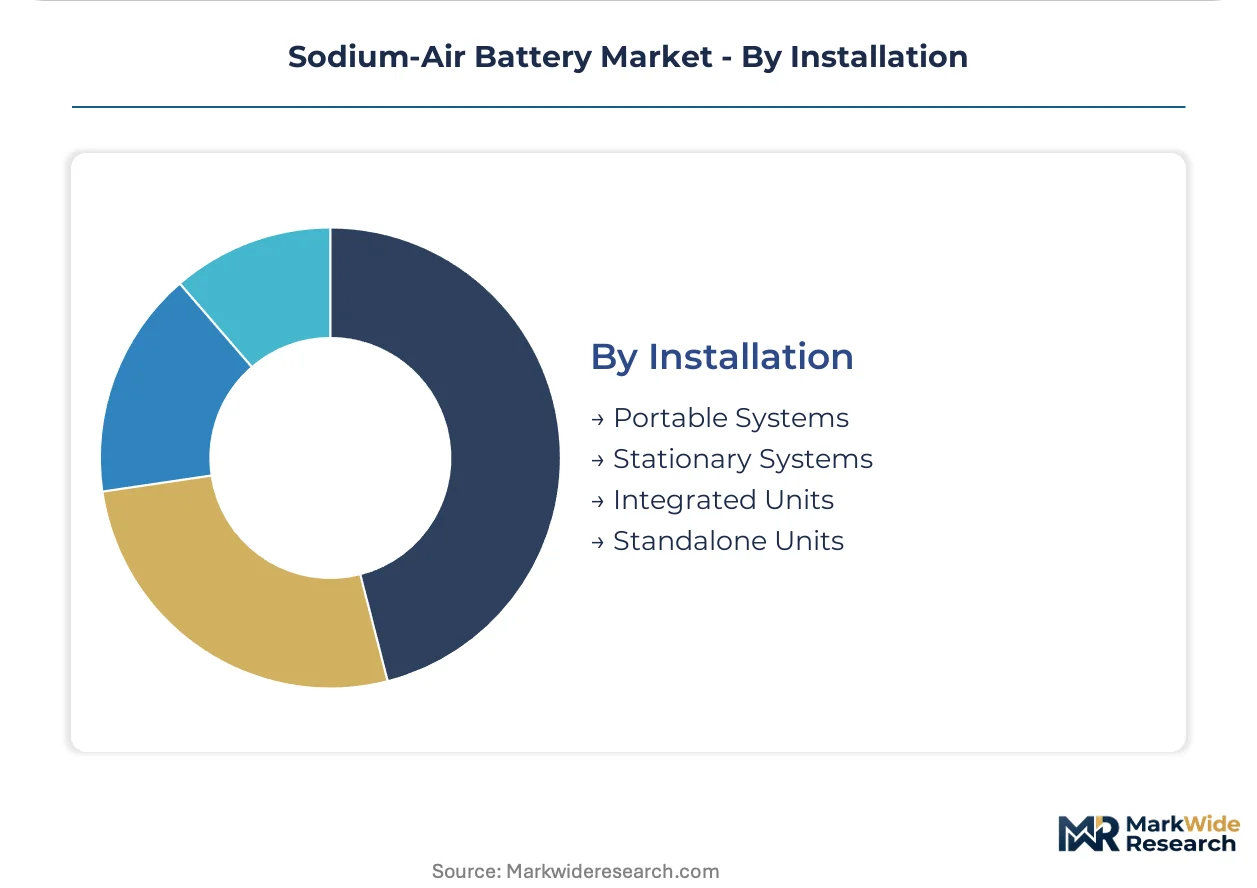
Installation:
Customer type fragmentation separates mobile defense applications from fixed utility infrastructure with distinct certification and logistics requirements.
- Stationary Systems:Fixed-site installations with integrated thermal management and electrolyte containment infrastructure. German renewable energy developers deploy these for grid-connected storage with KBA safety protocol compliance.
- Portable Systems:Modular configurations for expeditionary or field-deployed power without permanent infrastructure. Defense contractors specify these for military mobility programs requiring rapid redeployment capability.
- Integrated Units:Factory-assembled battery systems with pre-configured power electronics and management systems. Japanese solid-state consortia favor this approach to accelerate vehicle integration timelines.
- Standalone Units:Self-contained systems with independent thermal and electrical isolation for remote operation. Remote industrial sites in Germany adopt these where grid connection is economically prohibitive.
Stationary Systems holds the largest installed base, while Portable Systems is gaining share fastest through defense procurement channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale buyers and defense contractors concentrate procurement power across four distinct national jurisdictions, each shaping sodium-air battery deployment through divergent regulatory frameworks and industrial policy instruments.
Germany
KBA vehicle-type approval protocols actively expand alternative chemistry pathways for domestic automotive OEMs diversifying beyond lithium dependencies. The national automotive regulator coordinates with federal industrial policy frameworks favoring domestic battery value chain buildout. Stuttgart and Munich clusters host pilot line integration for heavy electric mobility platforms seeking gravimetric efficiency advantages.
Japan
METI-funded domestic solid-state sodium battery consortia accelerate captive sodium sourcing investments under green transformation industrial policy. Subsidy eligibility rules tighten supply chain localization requirements for electrochemical component manufacturing. Nagoya and Osaka industrial corridors concentrate thin-film electrolyte deposition equipment development for thermal runaway immunity applications.
United States
Defense contractors drive dedicated demand streams for long-duration energy density in military mobility applications separate from civilian automotive qualification cycles. Department of Energy battery safety certification protocols shape product standards through alternative chemistry reference expansions. Michigan and California clusters attract manufacturing location decisions ahead of production scale crystallization.
South Korea
Research institutes advance hybrid electrolyte architectures bridging solid-state performance with liquid electrolyte cost structures. National industrial policy instruments coordinate automotive OEM participation in sodium-air pilot programs. Seoul metropolitan area and Gwangju-Honam region concentrate electrochemical expertise from adjacent lithium-ion supply chain migration.
United Kingdom
Materials science heritage institutions anchor sodium sourcing relationships through captive chemical processor partnerships. National battery strategy frameworks prioritize alternative chemistry pathways for grid storage integration. Oxford and Cambridge clusters host quantum-accelerated materials discovery programs targeting cathode optimization cycles.
Sodium-Air Battery Market Competitive Landscape
Player mix skews toward technology developers with captive materials relationships and solid-state electrolyte specialization. The competitive field organizes around three strategic archetypes: research-institute spinouts with quantum simulation capabilities, chemical processors with backward integration into sodium supply, and automotive-facing solid-state specialists. Consolidation pressure operates through strategic partnerships for electrolyte architecture licensing and geographic co-location with OEM qualification facilities.
Among research-intensive developers, IBM Corporation exemplifies the quantum-accelerated materials discovery archetype, while Solid Power occupies a position within solid-state electrolyte specialization. Faradion represents the captive sodium sourcing tier with British materials science heritage. These three anchors illustrate how competitive positioning fragments across technology vectors rather than consolidating around integrated manufacturing scale.
| Leading Market Players |
|---|
| IBM Corporation |
| Solid Power |
| Sion Power Corporation |
| Faradion |
| Johnson Matthey |
| PolyPlus Battery Company |
| NOHMs Technologies |
| Echogen Power Systems |
| WattJoule Corporation |
| Others |
Value Network & Pricing Analysis
Pilot line capacity utilization across German and Japanese manufacturing clusters compresses unit economics for solid-state sodium-air configurations while sustaining premium pricing tiers for liquid electrolyte systems serving grid storage integrators. This scale asymmetry concentrates pricing power among chemical processors with captive sodium sourcing relationships and thin-film deposition equipment operators, forcing downstream battery assemblers into long-term offtake contracts indexed to metallic sodium commodity benchmarks.
Pricing Analysis
Cost-plus contracts with sodium metal indexation dominate procurement between chemical processors and battery manufacturers, with price adjustments tied to London Metal Exchange sodium benchmarks and energy input costs. Three-tier pricing structure across premium solid-state automotive grades, standard liquid electrolyte grid configurations, and economy-tier primary battery defense applications reflects certification complexity differentials. Pricing pressure stems from reversibility engineering capital requirements compressing margins in secondary battery configurations. Defense contractors exhibit lowest price sensitivity due to expeditionary power mission requirements, while German utility-scale buyers negotiate aggressively on liquid electrolyte volume commitments.
Supply Chain Analysis
Extended lead times for specialized thin-film electrolyte deposition equipment constrain manufacturing scale-up timelines, with ceramic sodium-ion conductor substrates drawing from Japanese and Korean materials science suppliers. Metallic sodium feedstock concentrates among German chemical processors and British materials heritage institutions, while porous carbon cathode architectures source from established lithium-ion supply chain migrations in China and South Korea. Single-source vulnerability permeates solid-state electrolyte precursor markets, particularly ceramic sintering furnaces and ultra-high purity sodium refining capacity. Distribution runs through direct OEM qualification partnerships rather than merchant market channels, with automotive and defense procurement offices commanding dedicated engineering liaison teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium-air battery development exhibits cyclical recovery characteristics as automotive OEM substitution pressure and defense procurement channel expansion converge after a prolonged reversibility engineering trough. Germany's KBA vehicle-type approval pathway expansion and Japan's METI-funded consortia reactivation provide named cyclical catalysts.
For Market Incumbents: Shield established positions through captive sodium sourcing relationship deepening and solid-state electrolyte architecture patent thickets against Korean research institute hybrid system advances. Prioritize KBA certification investment ahead of alternative chemistry threshold mandates in German public procurement tenders. Channel control over thin-film deposition equipment allocation represents the critical defensive lever against margin compression in premium automotive tiers. For New Entrants and Emerging Players: After-sales service and lifecycle management capabilities present the most exploitable service-layer gap, as incumbents concentrate engineering resources on pilot line qualification rather than field deployment support. Target German standalone unit installations for remote industrial sites where grid connection economics favor modular sodium-air configurations over lithium-ion alternatives. Pursue joint development agreements with defense contractors seeking expeditionary power logistics solutions outside civilian automotive qualification cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors research-institute spinouts with quantum simulation capabilities and chemical processors with backward integration into sodium supply, rather than automotive-facing solid-state specialists facing extended validation timelines. Long-term viability across the analysis window hinges on which regulatory jurisdictions first mandate sodium-based content thresholds in public procurement. Monitor KBA protocol expansion pace as the primary inflection indicator for manufacturing location advantage crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Sodium Sourcing Agreement | Secures metallic sodium feedstock against German chemical processor concentration risk. |
| Solid-State Electrolyte Patent Licensing | Accelerates KBA vehicle-type approval timelines for Japanese automotive OEM partners. |
| Defense Contractor Joint Development | Opens dedicated procurement channels outside civilian automotive qualification cycles. |
| Thin-Film Deposition Equipment Partnership | Resolves cleanroom infrastructure scarcity constraining manufacturing scale-up. |
| Quantum-Accelerated Cathode Discovery | Compresses electrochemical development cycles through IBM-class simulation capabilities. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with solid-state battery engineering directors, utility-scale procurement officers, defense program managers, and chemical processing executives; and secondary validation through METI consortium disclosure documents, KBA vehicle-type approval registers, Department of Energy battery safety certification protocols, and patent filing analytics. Bottom-up triangulation across electrolyte architecture development timelines and top-down reconciliation against national industrial policy expenditure commitments anchored market sizing.
Across the projection horizon, the analytical framework modeled sodium-air battery deployment across product type, technology architecture, end-use application, and installation configuration dimensions. CAGRs derived from electrolyte maturation curve analysis and automotive OEM platform integration timelines, with cross-reference to metallic sodium supply elasticity and thin-film deposition equipment capacity expansion schedules.
Underlying assumptions cover solid-state electrolyte yield rate improvements and KBA protocol expansion pace, with deviation risk concentrated in reversibility engineering breakthrough timing and defense procurement cycle volatility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Portable Battery Powered Products Market
Batteries
Silicon Battery Market
Batteries
Home Inverter Battery Market
Batteries
Japan Rechargeable Battery Market
Batteries
Non-Rechargeable Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
18650 And 21700 Battery Market
Batteries
Micro Battery Market
Batteries
High Temperature NiMH Battery Market
Batteries
Middle East and Africa Battery Market
Batteries
Aluminum Based Battery Market
Batteries
India Alkaline Battery Market
Batteries
48 Volt Battery System Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Aluminum Wire Battery Market
Batteries
Europe Industrial Battery Market