
 Aluminium-Sulfur Battery Market | 2026-2036
Aluminium-Sulfur Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminium-Sulfur Battery Market Insights
EU Battery Regulation is shifting the cost-of-entry calculus for aluminium-sulfur cell producers seeking European market access. Furukawa Battery Co. Ltd. leverages its electrochemical R&D heritage to anchor development of high-temperature molten salt formulations. GS Yuasa Corporation sustains manufacturing scale across its Japanese facilities while competing on solid-state electrolyte integration. Panasonic Corp. differentiates through prismatic cell architectures optimized for grid-scale thermal management.
Aluminium-sulfur batteries employ molten aluminium anodes and sulfur cathodes separated by a molten salt electrolyte, operating at temperatures between 90°C and 200°C to maintain ionic conductivity and electrochemical reversibility. The technology stores energy through the redox reaction between aluminium and sulfur, delivering theoretical energy densities exceeding conventional lithium-ion systems for stationary applications. Prismatic cells dominate current manufacturing throughput due to superior thermal uniformity in containerized installations, while solid-state technology attracts the fastest development investment as researchers replace molten electrolytes with ceramic conductors. Grid energy storage applications command the deepest margin pools because utility procurement cycles prioritize twenty-year operational lifespans over upfront capital costs.
The EU Battery Regulation and REACH framework impose strict carbon-footprint disclosure and recycling-content mandates on battery producers selling into Europe. China's GB standards and MIIT circulars set parallel technical benchmarks for domestic aluminium-sulfur deployment in renewable energy zones. Japan's METI directs subsidy flows toward molten-metal battery demonstrations integrated with solar farms. Stakeholders must monitor which regulatory jurisdiction certifies first-party lifecycle data as the definitive passport for cross-border trade.
Market Dynamics
The EU Battery Regulation's carbon-footprint disclosure mandates are forcing aluminium-sulfur cell producers to restructure supply chains around certified low-carbon aluminium smelters and regional sulfur processing hubs before European market entry becomes viable.
Growth Catalysts
- Grid Storage Procurement:California utilities are scaling pilot deployments of containerized aluminium-sulfur systems for renewable firming, with procurement cycles prioritizing twenty-year operational lifespans over upfront capital expenditure.
- Molten Salt Formulation Advances:Electrochemical R&D programs in Japan are yielding high-temperature electrolyte compositions that maintain ionic conductivity below 150°C, reducing thermal management overhead for stationary installations.
- EU Green Deal Alignment:The bloc's domestic content thresholds and recycling-content mandates under REACH are creating preferential market access for aluminium-sulfur technologies with closed-loop material recovery systems.
Market Restraints
- Primary Aluminium Cost Volatility:Energy-intensive smelting operations tie cell economics to regional electricity price swings, particularly in markets dependent on natural gas peaking plants.
- Sulfur Supply Concentration:Refinery byproduct sulfur availability clusters around petrochemical corridors in Texas, Louisiana, and the Middle East, exposing producers to feedstock transport costs and geopolitical disruption.
- Thermal Cycling Degradation:Repeated heating and cooling of molten salt electrolytes induces seal fatigue and container corrosion, compressing effective service intervals below theoretical cell lifespans.
Strategic Opportunities
- Industrial Microgrids:Germany's manufacturing belt around Düsseldorf and Munich presents concentrated demand for on-site aluminium-sulfur storage displacing diesel backup generators.
- Prismatic-Solid State Convergence:Ceramic electrolyte research programs are converging with established prismatic cell architectures to enable ambient-temperature operation without sacrificing manufacturing throughput.
- Direct Procurement Channels:Utility-scale developers are bypassing traditional battery integrators to contract directly with cell manufacturers, capturing margin previously allocated to system packaging.
Industry Challenges
- High-Temperature Materials Science Talent:The intersection of molten metal electrochemistry and ceramic engineering commands specialized expertise scarce outside national laboratory and smelting industry pipelines.
- First-Party Lifecycle Certification:EU Battery Regulation compliance requires producers to establish auditable carbon-accounting systems from bauxite extraction through cell retirement, a capability absent from most development-stage manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminium-Sulfur Battery Market |
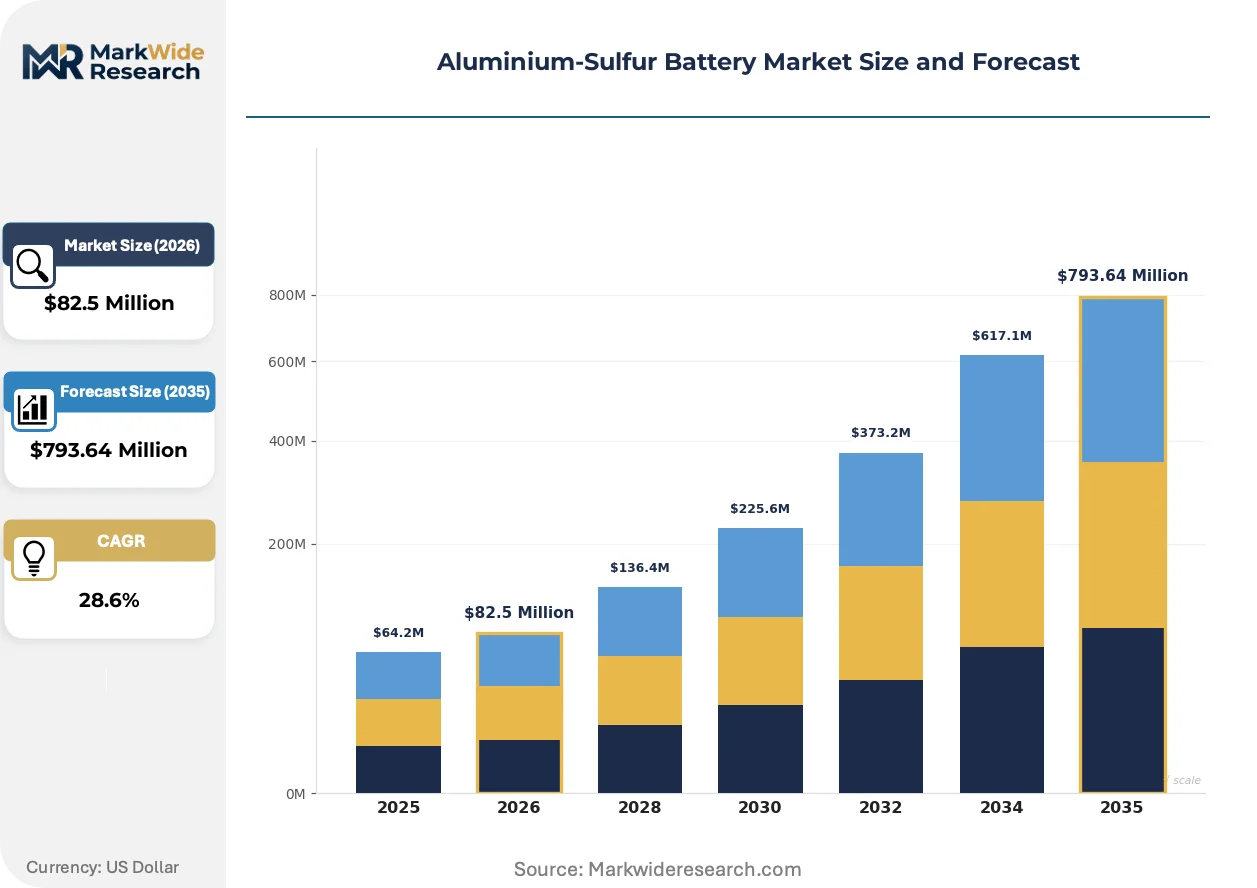
| Market Size in 2026 | $82.5 Million |
| Market Size in 2035 | $793.64 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Cylindrical Cells, Flexible Cells, Stackable Cells End User: Automotive, Grid Energy Storage, Portable Electronics, Aerospace Technology: Electrochemical, Solid-State, Hybrid, Flow Battery Application: Renewable Energy Storage, Electric Vehicles, Backup Power, Consumer Electronics |
| Companies Covered | Furukawa Battery Co. Ltd., GS Yuasa Corporation, East Penn Manufacturing Company, Inc., Exide Industries Limited, Panasonic Corp., Exide Technologies, Green Science Alliance, Lion Batteries Pty Ltd, Johnson Controls, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminium-Sulfur Battery Market Trends and Innovations
Solid-state electrolyte research is compressing the temperature operating window for aluminium-sulfur systems while prismatic cell standardization is enabling modular grid-scale deployment at accelerating velocity across utility procurement programs.
Ceramic conductor formulations are replacing molten salt electrolytes in pilot production lines, maintaining electrochemical reversibility at sub-100°C temperatures. Grid operators in California and Texas are qualifying these lower-temperature cells for indoor installation alongside power electronics. This thermal regime reduction is decentralizing deployment options beyond containerized outdoor arrays into building-integrated and underground vault configurations.
The EU Battery Regulation's carbon-footprint class thresholds are mandating supply chain documentation from raw material extraction through manufacturing. European producers are responding by securing low-carbon aluminium from hydropower-fed smelters in Norway and Iceland. Cell architectures optimized for European certification are capturing premium positioning in utility tenders that weight lifecycle emissions above upfront capital cost.
Utility procurement departments are consolidating vendor relationships around integrated cell-system providers capable of twenty-year service contracts. Traditional battery integrators face margin compression as developers contract directly with manufacturers for containerized installations. This disintermediation is most visible in Germany, where industrial offtakers are negotiating power purchase agreements bundled with on-site aluminium-sulfur storage without intermediary engineering-procurement-construction firms.
Aluminium-Sulfur Battery Market Segmentation
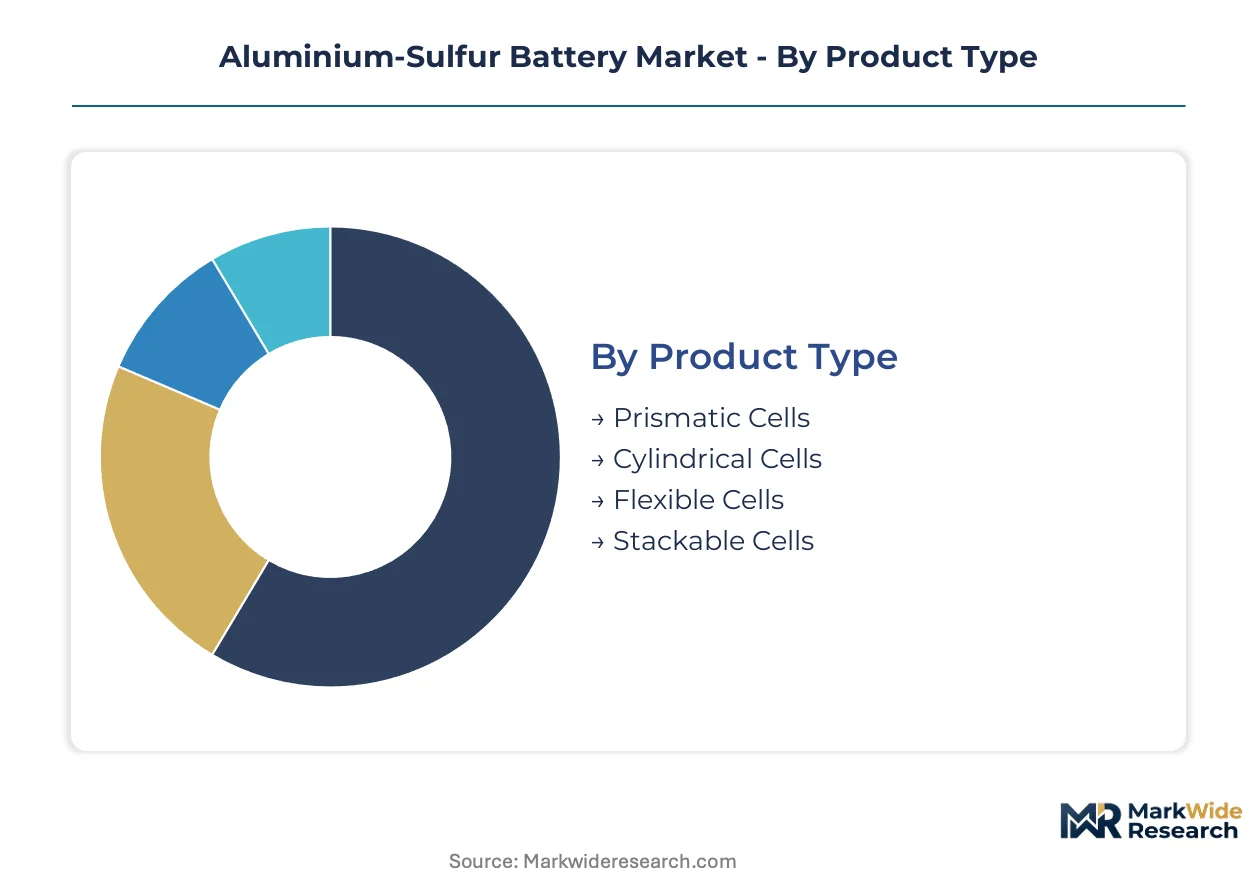
Aluminium-sulfur battery architectures diverge sharply across thermal management requirements, installation constraints, and procurement scale. Each segment carries distinct material specifications and certification pathways that determine addressable market access.
Product Type:
Thermal uniformity and manufacturing throughput separate the dominant cell geometries from emerging formats.
- Prismatic Cells:Rectangular aluminum housings optimize heat dissipation in containerized grid installations. California utilities specify prismatic formats for renewable firming projects requiring twenty-year service intervals.
- Cylindrical Cells:Rolled electrode assemblies suit automated production lines with established winding equipment. Japanese manufacturers leverage cylindrical heritage from lithium-ion operations to reduce tooling transition costs.
- Flexible Cells:Polymer-encapsulated designs conform to irregular mounting surfaces in aerospace applications. Thin-film substrates trade energy density for packaging versatility in weight-constrained deployments.
- Stackable Cells:Modular interlocking units enable field-expansible capacity without container replacement. Industrial microgrids in Germany's manufacturing belt favor stackable architectures for phased capital deployment.
Mature deployment sits with prismatic configurations. Newer deployment is concentrated in stackable formats.
End User:
Procurement scale and technical specifications fragment demand across mobility, stationary, and portable applications.
- Grid Energy Storage:Utility-scale installations prioritize cycle stability over gravimetric density. Twenty-year operational lifespans dominate procurement criteria in California and Texas renewable zones.
- Automotive:Power density requirements and crash safety standards constrain aluminium-sulfur adoption. High-temperature operation complicates vehicle integration against NHTSA thermal propagation rules.
- Portable Electronics:Consumer devices demand ambient-temperature operation incompatible with molten electrolyte systems. Solid-state research programs target this gap with ceramic conductor formulations.
- Aerospace:Satellite and unmanned platforms tolerate thermal management mass penalties for energy density gains. Furukawa Battery and GS Yuasa anchor development partnerships with Japanese space agencies.
Established procurement sits with grid operators. Emerging qualification concentrates in aerospace programs.
Technology:
Electrolyte chemistry defines the temperature-operating window and manufacturing capital intensity.
- Electrochemical:Molten salt electrolytes between 90°C and 200°C deliver proven reversibility with established materials. Furukawa Battery's high-temperature formulations dominate current production volume.
- Solid-State:Ceramic conductors enable sub-100°C operation, expanding indoor installation options. California and Texas utilities are qualifying solid-state pilots for building-integrated storage.
- Hybrid:Combined liquid-solid electrolyte architectures balance ionic conductivity with seal durability. Research programs at Panasonic target hybrid formats for prismatic cell integration.
- Flow Battery:External electrolyte reservoirs decouple power and energy scaling for long-duration applications. Flow configurations remain pre-commercial for aluminium-sulfur chemistry.
Commercial maturity sits with electrochemical systems. Steepest expansion trajectory belongs to solid-state development.
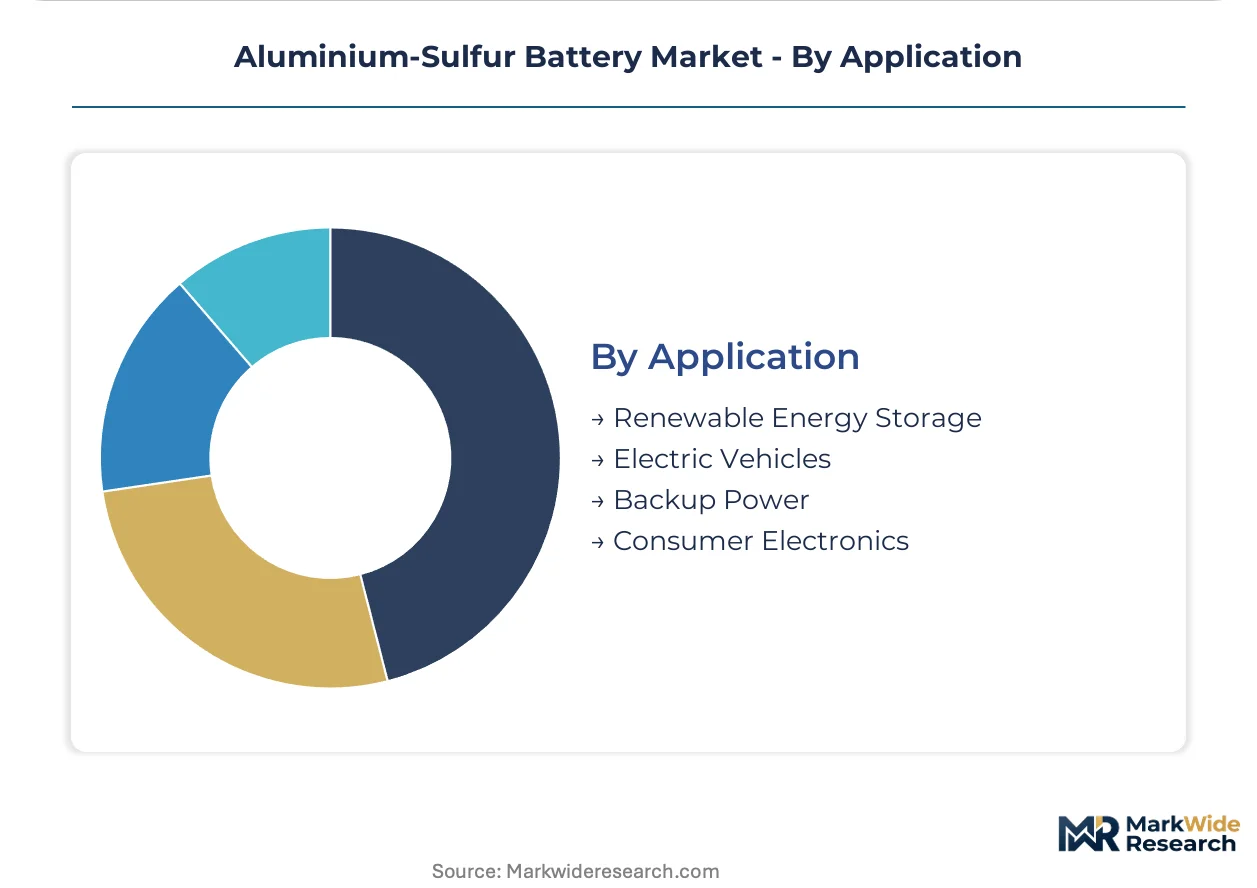
Application:
Duration requirements and duty cycles determine cell specification and warranty structures.
- Renewable Energy Storage:Solar and wind firming demands 4-8 hour discharge capability with daily cycling. EU Green Deal alignment favors aluminium-sulfur systems with closed-loop material recovery.
- Electric Vehicles:Fast-charge compatibility and cold-start performance lag lithium-ion benchmarks. Solid-state electrolyte advances are prerequisite for automotive qualification.
- Backup Power:Infrequent cycling tolerates thermal ramp delays in mission-critical installations. German industrial offtakers deploy backup systems alongside solar generation under METI-inspired subsidy models.
- Consumer Electronics:Form factor constraints and safety certifications exclude molten-electrolyte designs. Solid-state ceramic conductors represent the sole viable pathway for this segment.
Deployed capacity sits with renewable firming. Fastest qualification activity concentrates in backup power applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's renewable energy corridors concentrate pilot manufacturing capacity for molten-metal battery systems. Tax incentives in California's clean technology zones accelerate utility-scale deployment timelines. Industrial clusters in Germany's manufacturing belt anchor European qualification programs for grid-integrated storage.
United States
California utilities drive procurement of containerized aluminium-sulfur systems for renewable firming applications. The Inflation Reduction Act's clean energy manufacturing credits reduce capital costs for domestic cell production facilities. Industrial microgrid developers in Texas petrochemical corridors leverage localized sulfur feedstock access for backup power installations.
Germany
Industrial battery demand concentrates around Düsseldorf and Munich manufacturing belts seeking on-site storage solutions. EU Battery Regulation carbon-footprint thresholds mandate supply chain restructuring toward certified low-carbon aluminium sources. The country's national industrial strategy directs subsidy flows toward molten-metal battery demonstrations integrated with solar generation assets.
China
GB standards and MIIT circulars establish technical benchmarks for aluminium-sulfur deployment in western renewable energy zones. Dual carbon goals accelerate qualification of high-temperature storage systems for grid stabilization. Yangtze River Delta industrial parks host pilot production lines targeting utility procurement cycles.
Japan
METI subsidy programs channel funding toward molten-metal battery demonstrations paired with solar farm installations. Electrochemical R&D heritage in Kansai and Chubu regions sustains high-temperature electrolyte formulation advances. Domestic manufacturers leverage cylindrical cell production expertise from lithium-ion operations to reduce tooling transition costs.
Aluminium-Sulfur Battery Market Competitive Landscape
Japanese producers anchor one tier; Chinese and European specialists hold adjacent positions in emerging qualification programs. The vendor base separates into three structural tiers: established electrochemical developers with molten salt heritage, solid-state research programs targeting thermal regime reduction, and industrial battery incumbents diversifying into grid-scale formats. Dominant competitive moves include strategic partnerships with utility developers for twenty-year service contracts and backward integration into low-carbon aluminium supply chains.
Within the established electrochemical tier, Furukawa Battery Co. Ltd. and GS Yuasa Corporation represent Japanese heritage in high-temperature molten salt formulations. Panasonic Corp. occupies a position bridging prismatic cell architectures with emerging solid-state research vectors. East Penn Manufacturing Company, Inc. exemplifies North American industrial battery incumbents adapting existing production infrastructure toward grid-scale thermal management systems.
| Leading Market Players |
|---|
| Furukawa Battery Co. Ltd. |
| GS Yuasa Corporation |
| East Penn Manufacturing Company, Inc. |
| Exide Industries Limited |
| Panasonic Corp. |
| Exide Technologies |
| Green Science Alliance |
| Lion Batteries Pty Ltd |
| Johnson Controls, Inc. |
| Others |
Pricing and Supply Chain Analysis
London Metal Exchange aluminium cash prices cascade through aluminium-sulfur battery supply chains into three distinct procurement tiers. Premium tier contracts command twenty-year service guarantees with certified low-carbon smelter provenance, while spot market cells trade at substantial discounts without EU Battery Regulation carbon-footprint documentation.
Pricing Analysis
Lead-time compression premiums dominate pricing differentiation across utility procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates cells with full lifecycle certification from those with partial documentation or none. Pricing pressure stems from primary aluminium cost volatility tied to natural gas peaking plant economics in European smelting corridors. Grid operators exhibit lowest price sensitivity, prioritizing twenty-year operational lifespans over upfront capital expenditure, while industrial microgrid developers demonstrate highest elasticity to spot market fluctuations.
Supply Chain Analysis
Reverse-logistics networks for molten salt electrolyte recovery and aluminium anode remelting remain underdeveloped across all production geographies. Supply concentrates in China, Japan, and Germany for electrochemical cell manufacturing, with Norway and Iceland anchoring low-carbon aluminium feedstock. Critical dependencies include refinery byproduct sulfur from Texas and Louisiana petrochemical corridors, ceramic conductor precursors from Japanese specialty chemical producers, and prismatic cell housings from Yangtze River Delta metal fabrication clusters. Single-source vulnerability in high-temperature seal materials exposes producers to aerospace alloy supply disruptions. Distribution runs through direct procurement channels as utility-scale developers bypass traditional battery integrators for manufacturer-direct containerized installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over low-carbon aluminium smelting capacity determines European market access viability. Players securing hydropower-fed feedstock contracts in Norway and Iceland establish defensible cost positions against carbon-footprint class thresholds.
For Market Incumbents: Extend twenty-year service contract coverage to capture utility procurement cycles before solid-state electrolyte research displaces molten salt formulations. Secure backward integration into certified low-carbon aluminium supply chains to defend margin position against EU Battery Regulation compliance costs. Counter emerging Chinese producers by accelerating prismatic cell standardization through joint qualification programs with California and Texas grid operators.
For New Entrants and Emerging Players: Solid-state ceramic conductor research programs offer the most penetrable wedge for ambient-temperature operation segments excluded from molten-electrolyte competition. Target German industrial microgrid demand around Düsseldorf and Munich manufacturing belts where diesel backup displacement creates immediate procurement appetite. Pursue technology licensing arrangements with established Japanese electrochemical developers to bypass high-temperature materials science talent scarcity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with incomplete EU Battery Regulation certification pathways in European jurisdictions. Long-term viability over a five-to-ten-year horizon hinges on first-party lifecycle data infrastructure capable of auditable carbon-accounting from bauxite extraction through cell retirement. Monitor solid-state pilot qualification timelines at California and Texas utilities as the critical inflection signal for thermal regime reduction investment returns. Material deviation in named triggers warrants pause and re-evaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Aluminium | Captive supply from Norway and Iceland smelters secures EU Battery Regulation premium tier access. |
| Solid-State Electrolyte Pilot Qualification | Texas and California utility indoor installation approvals expand addressable market beyond containerized arrays. |
| Twenty-Year Service Contract Standardization | Direct manufacturer-utility relationships disintermediate traditional battery integrators and capture system packaging margin. |
| Prismatic Cell Architecture Convergence | Thermal uniformity optimization aligns with containerized grid-scale deployment requirements in renewable firming applications. |
| High-Temperature Materials Science Talent Acquisition | National laboratory and smelting industry pipeline access addresses scarce ceramic engineering expertise for seal durability advancement. |
Research Methodology
Document review covered regulatory filings from the EU Battery Regulation implementing acts, METI subsidy program disclosures, and California Public Utilities Commission procurement records, complemented by interviews with utility planning officers, electrochemical R&D directors at Japanese manufacturers, industrial battery procurement leads in Germany, and molten salt materials scientists at national laboratory programs. Secondary validation drew from EIA grid storage deployment databases, IEA stationary battery outlooks, and customs trade data for aluminium and sulfur feedstock flows. Bottom-up cell production capacity estimates triangulated against top-down utility procurement pipeline valuations.
Market sizing outputs reflect segment-level modeling across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs derive from regression analysis of historical procurement cycle timing, electrolyte formulation advancement trajectories, and regulatory threshold implementation schedules. Forecast inputs incorporate molten salt thermal cycling degradation curves, solid-state ceramic conductor conductivity improvement rates, and EU carbon-footprint class threshold enforcement timelines.
Several conditions sit outside the modeled scope, including unannounced breakthroughs in ambient-temperature ionic liquid electrolytes, geopolitical disruption of Middle Eastern sulfur supply corridors, and retroactive tightening of REACH recycling-content mandates. Forecasts reflect assumptions regarding continued IRA manufacturing credit stability and METI demonstration program funding continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Asia-Pacific Industrial Battery Market
Batteries
Battery Separators Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Sweden Rechargeable Battery Market
Batteries
Europe SLI Battery Market
Batteries
Portable Battery Pack Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
Advanced Batteries Market
Batteries
North America NMC Battery Pack Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
Battery-Powered Riveter Market
Batteries
UAV Battery Pack Market
Batteries
India Lead-Acid Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Military Battery Packs Market
Batteries
India Rechargeable Battery Market