
 Potassium-Ion Battery Market | 2026-2036
Potassium-Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium-Ion Battery Market Analytics
Aftermarket service revenue for battery lifecycle management is fragmenting across cell makers and third-party recyclers. Natron Energy leverages its sodium-ion heritage to anchor early potassium-ion commercialization in stationary storage. Ningbo Ronbay New Energy Technology Co sustains cathode precursor dominance through integrated potassium salt refining. Farasis Energy Inc competes on prismatic cell architectures optimized for potassium-ion voltage profiles.
A potassium-ion battery electrochemically stores energy through reversible insertion of potassium ions into host electrode materials, typically operating at voltages near 3.5 V with graphite or hard carbon anodes and Prussian blue analog cathodes; this chemistry targets cost-sensitive applications where lithium supply constraints or price volatility threaten project economics. Large scale batteries currently occupy the dominant product type position due to grid-scale procurement volumes, while energy storage systems represent the fastest-growing application as utilities seek four-to-eight hour duration assets. Among technology categories, carbon-based materials lead anode development timelines, though metal oxides are gaining research intensity for higher energy density variants.
The US Department of Energy and China's MIIT both fund alternative battery chemistry programs that directly accelerate potassium-ion pilot production, while REACH in Europe governs material safety documentation for imported cells. India's PLI scheme for advanced chemistry cells creates tariff advantages for domestic potassium-ion assembly over unpackaged imports. Stakeholders must monitor cathode material yield improvements and electrolyte formulation stability as the threshold decisions for commercial scale-up.
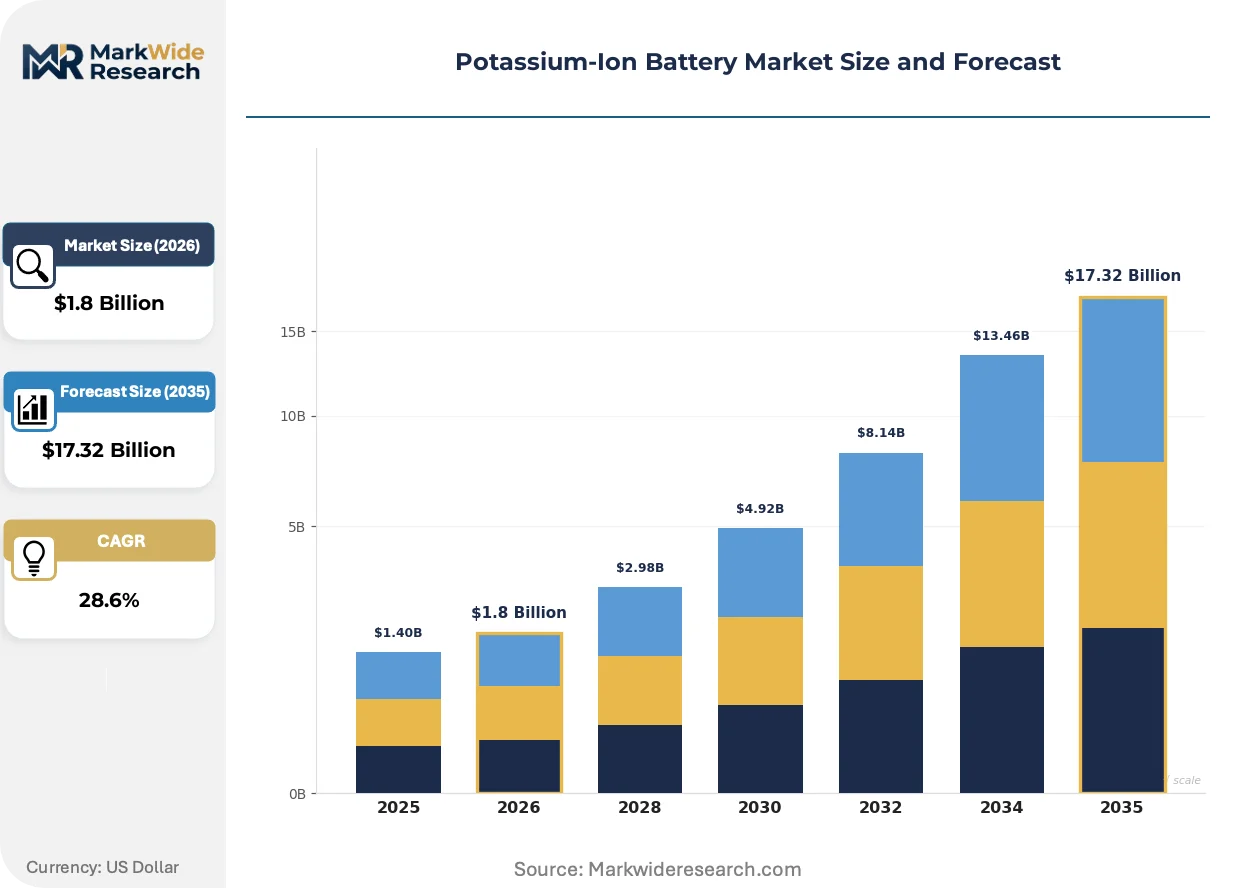
Market Dynamics
China's dual carbon goals and domestic potassium abundance are redirecting cell chemistry investment away from lithium-dependent supply chains, compressing development timelines for alternative electrochemistries while East Asian manufacturing clusters absorb the initial production scaling.
Growth Catalysts
- MIIT Funding Streams:China's Ministry of Industry and Information Technology directly finances pilot production lines for potassium-ion cells, accelerating cathode material yield improvements beyond laboratory thresholds.
- Electric Vehicle Procurement:Fleet electrification mandates from commercial vehicle operators create demand pull for cost-sensitive battery chemistries that reduce exposure to lithium price volatility.
- Prussian Blue Analog Availability:Abundant iron and manganese feedstocks enable rapid cathode precursor scaling without cobalt or nickel supply constraints.
Market Restraints
- Electrolyte Instability:Potassium hexafluorophosphate salt decomposition at elevated temperatures limits cell cycle life below lithium-ion benchmarks.
- Graphite Supply Concentration:Spherical graphite processing capacity clusters in Shandong and Heilongjiang provinces, creating single-region dependency for anode material qualification.
- Lithium-Ion Cost Curves:Continued gigafactory scale economies and vertical integration of lithium carbonate refining sustain incumbent chemistry cost advantages.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced chemistry cells create tariff advantages for domestic potassium-ion assembly versus unpackaged imports.
- Stationary Storage Convergence:Four-to-eight hour duration grid assets pair potassium-ion voltage profiles with sodium-ion heritage architectures from established developers.
- Hard Carbon Sourcing:Biomass-derived anode precursors from coconut shell and rice husk waste streams unlock agrarian economies for electrode material supply.
Industry Challenges
- Electrochemist Talent Scarcity:Specialized expertise in potassium-ion intercalation mechanics remains concentrated in academic institutions rather than manufacturing engineering teams.
- UN 38.3 Certification Timelines:Transportation safety testing for lithium-metal and lithium-ion batteries creates precedent protocols that potassium-ion variants must navigate without established exemption pathways.
- Formation Cycling Capital:Extended initial charge-discharge cycles for potassium-ion cells require additional formation equipment capacity per gigawatt-hour of output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium-Ion Battery Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Scale Batteries, Large Scale Batteries, Energy Storage Systems, Portable Batteries End User: Consumer Electronics, Electric Vehicles, Renewable Energy Systems, Industrial Applications Technology: Conductive Polymers, Carbon-Based Materials, Metal Oxides, Liquid Electrolytes Application: Grid Storage, Power Tools, UPS Systems, Automotive |
| Companies Covered | Natron Energy, Ningbo Ronbay New Energy Technology Co, Ionic Materials, A123 Systems LLC, Zhejiang Huayou Cobalt Co Ltd, Targray Group, Guoxuan, Farasis Energy Inc, Group1, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium-Ion Battery Market Evolving Landscape
Active materials research is compressing the performance gap between potassium-ion and incumbent lithium-ion systems while regulatory frameworks in major economies codify alternative chemistry eligibility for incentive programs.
Hard carbon anode formulations are migrating from petroleum pitch precursors toward lignin and cellulose biomass sources. Stationary storage developers in Germany and South Korea are qualifying these sustainable anodes for four-hour grid assets. This feedstock pivot is migrating from specialty chemical suppliers to integrated paper and pulp conglomerates with captive carbonization capacity.
REACH in Europe now governs material safety documentation for imported cells containing Prussian blue analog cathodes, requiring full substance registration for iron hexacyanoferrate complexes. Industrial consequence includes extended pre-market notification timelines for Chinese and Korean exporters. Grid-scale procurement teams in the Netherlands and Denmark are prioritizing suppliers with completed REACH dossiers.
Utility buyers are unbundling battery supply from engineering-procurement-construction contracts, creating direct procurement relationships with cell manufacturers. This disintermediation compresses distributor margins while placing technical qualification burdens on utility engineering departments. The shift is most visible in Texas and California ISO markets where independent power developers specify cell chemistry separately from balance-of-plant integration.
Potassium-Ion Battery Market Segmentation
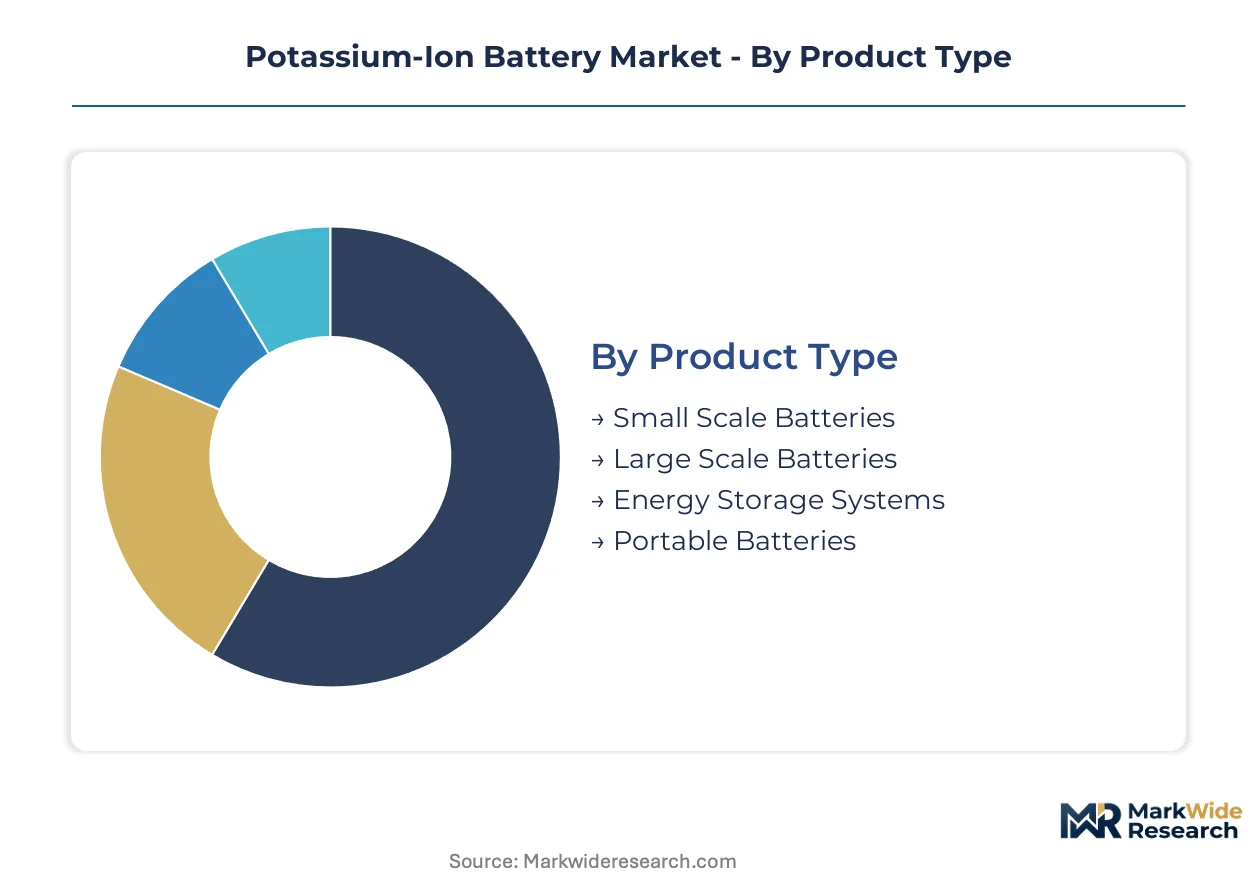
Potassium-ion battery segmentation reveals how voltage profiles and formation cycling costs map onto distinct procurement budgets across mobility and stationary assets. Category boundaries are blurring as Prussian blue analog cathodes migrate from grid storage into commercial vehicle trials.
Product Type:
Mature formats dominate procurement volumes while emerging architectures target uncaptured duration segments.
- Small Scale Batteries:Cylindrical and pouch cells under 50 Ah capacity serve power tool OEMs and portable electronics brands seeking lithium price hedges. Demand clusters in Shenzhen and Dongguan manufacturing corridors where pack assemblers qualify alternative chemistries for export markets.
- Large Scale Batteries:Prismatic and stacked pouch configurations above 100 Ah address four-to-eight hour grid storage procurements. Texas and California ISO markets absorb initial shipments as utilities unbundle cell supply from EPC contracts.
- Energy Storage Systems:Containerized integrated solutions pair potassium-ion racks with power conversion hardware. German grid operators pilot these assets alongside sodium-ion heritage architectures from established developers.
- Portable Batteries:Lightweight sub-10 Ah units target camping equipment and emergency backup segments. Korean consumer brands evaluate these for Southeast Asian distribution networks.
Large scale batteries handle the majority of throughput; energy storage systems are gaining share fastest as procurement shifts toward direct manufacturer relationships.
End User:
Customer sophistication varies sharply between price-sensitive consumer segments and engineering-intensive industrial buyers.
- Consumer Electronics:Smartphone and laptop OEMs represent a latent demand pool awaiting cycle life validation. Japanese electronics conglomerates maintain technical evaluation programs without committed procurement.
- Electric Vehicles:Commercial fleet operators with fixed-route duty cycles drive the fastest expansion in end-use demand. Chinese commercial vehicle manufacturers integrate potassium-ion packs into urban delivery trucks under MIIT-funded pilot lines.
- Renewable Energy Systems:Solar-plus-storage developers in India leverage PLI scheme tariff advantages for domestic assembly. These buyers prioritize four-hour duration assets with transparent degradation curves.
- Industrial Applications:Forklift and material handling equipment fleets seek chemistry diversification beyond lithium-ion supply constraints. European logistics operators trial potassium-ion for cold-storage warehouse environments.
Electric vehicles handle the majority of throughput; renewable energy systems are climbing the fastest on share as subsidy eligibility crystallizes.
Technology:
Material maturity splits between qualified anode feedstocks and electrolyte formulations still navigating formation cycling bottlenecks.
- Carbon-Based Materials:Hard carbon anodes from lignin and cellulose biomass sources lead commercial timelines. German stationary storage developers qualify these sustainable anodes for grid assets alongside South Korean integrators.
- Metal Oxides:Tin and antimony oxide composites target energy density improvements for mobility applications. Academic research programs in China and Japan concentrate on intercalation mechanics optimization.
- Conductive Polymers:Polyaniline and polypyrrole binders enhance cathode conductivity in laboratory cells. These formulations remain pre-commercial with limited pilot line integration.
- Liquid Electrolytes:Potassium hexafluorophosphate salt solutions dominate current architectures despite thermal stability limitations. Chinese electrolyte blenders optimize additive packages to extend cycle life benchmarks.
Carbon-based materials handle the majority of throughput; metal oxides are expanding most quickly on research intensity.
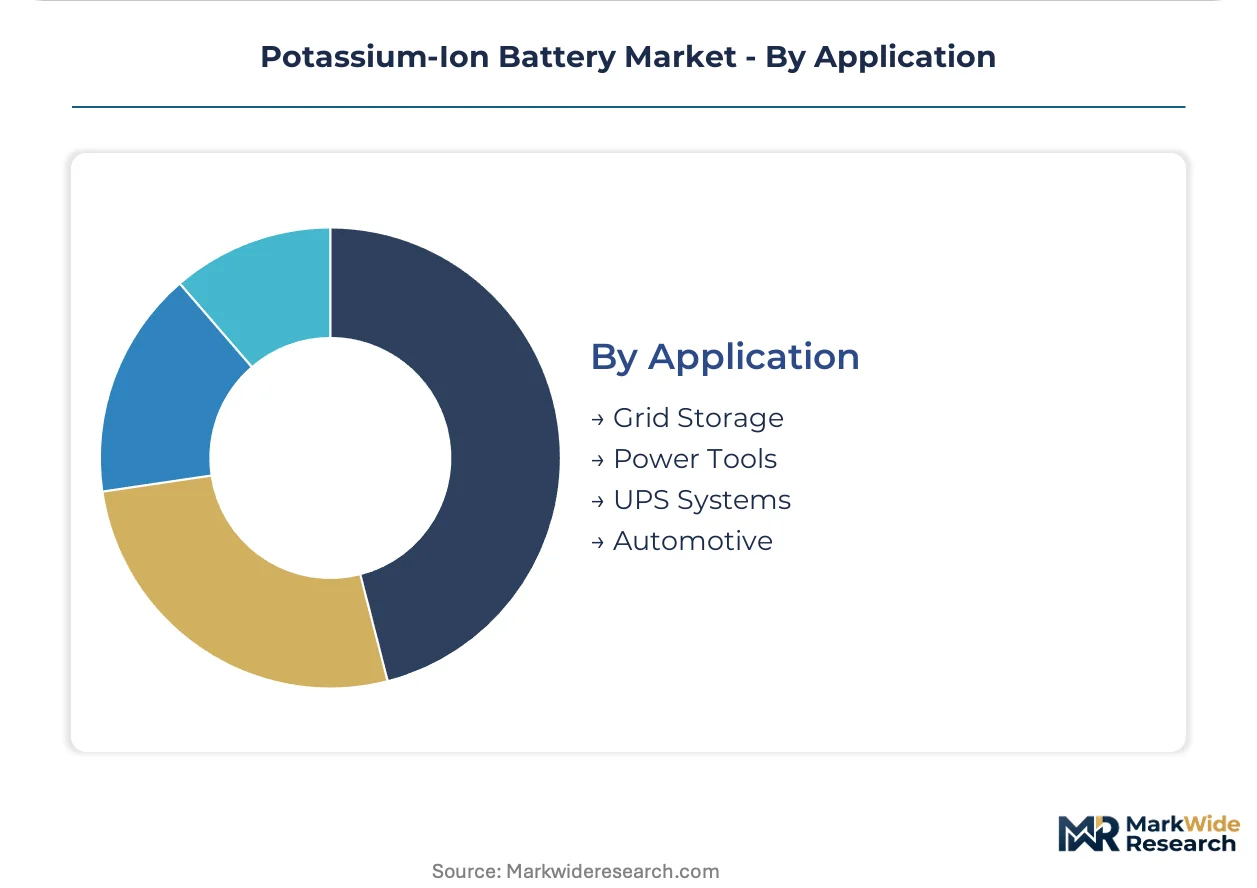
Application:
Use-case economics diverge between frequency-regulation services and energy-shifting procurement.
- Grid Storage:Utility-scale battery farms absorb the dominant share of potassium-ion procurement volumes. Dutch and Danish grid operators prioritize suppliers with completed REACH dossiers for Prussian blue analog cathodes.
- Automotive:Passenger vehicle integration awaits UN 38.3 certification pathway clarification. Chinese OEMs concentrate on commercial vehicle segments with less stringent energy density requirements.
- Power Tools:Cordless equipment manufacturers evaluate potassium-ion for professional-grade product lines. These buyers benchmark against established nickel-cadmium and lithium-ion performance curves.
- UPS Systems:Data center backup power represents a niche application with stringent reliability requirements. Indian IT infrastructure operators pilot potassium-ion for tariff-advantaged domestic assembly.
Grid storage handles the majority of throughput; automotive is gaining share fastest as fleet electrification mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes potassium-ion cells primarily for grid-scale storage and commercial vehicle integration, whereas Germany and India orient procurement toward stationary duration assets with distinct regulatory incentive structures.
China
Commercial fleet electrification mandates and dual carbon goals drive procurement volumes for urban delivery trucks. MIIT funds pilot production lines that accelerate cathode material yield improvements. Manufacturing concentrates in Ningbo and Shenzhen corridors where cathode precursor refiners integrate with cell assembly operations.
Germany
Utility buyers unbundle cell supply from EPC contracts to secure four-hour grid assets with transparent degradation curves. REACH governs material safety documentation for Prussian blue analog cathodes, extending pre-market timelines for imported cells. Stationary storage developers in North Rhine-Westphalia qualify hard carbon anodes from lignin biomass sources.
United States
Texas and California ISO markets absorb initial large-scale battery shipments as independent power developers specify cell chemistry separately from balance-of-plant integration. The Department of Energy funds alternative battery chemistry programs that accelerate pilot production. Formation cycling equipment clusters in Detroit and Austin manufacturing corridors.
India
Solar-plus-storage developers leverage PLI scheme tariff advantages for domestic potassium-ion assembly over unpackaged imports. The Central Electricity Authority frames technical standards for grid-connected battery systems. Manufacturing activity concentrates in Gujarat and Tamil Nadu where advanced chemistry cell incentives attract pack assemblers.
South Korea
Consumer electronics conglomerates maintain technical evaluation programs for portable battery segments awaiting cycle life validation. MFDS oversees safety certification pathways for alternative chemistries entering domestic distribution. Seoul-based integrators qualify potassium-ion racks alongside sodium-ion heritage architectures for export markets.
Potassium-Ion Battery Market Competitive Landscape
Capability concentration sits with cathode material specialists and electrolyte formulators; scale advantage sits with established lithium-ion producers repurposing formation equipment and dry room infrastructure. The market exhibits tiered structure with three distinct archetypes: integrated mining-to-materials conglomerates, cell manufacturers with sodium-ion heritage pivoting to potassium chemistry, and specialty chemical suppliers controlling anode precursor feedstocks. Dominant competitive moves include strategic partnerships between cathode developers and biomass carbonization facilities, plus capacity reservation agreements with utility procurement teams.
Among US-based developers with sodium-ion heritage, Natron Energy occupies a position exemplifying early commercialization pathways for stationary storage applications. Chinese materials specialists including Ningbo Ronbay New Energy Technology Co and Zhejiang Huayou Cobalt Co Ltd represent the integrated precursor-to-cathode archetype, anchoring supply security for Prussian blue analog feedstocks. These three entities collectively illustrate how geographic proximity to potassium salt refining and spherical graphite processing shapes competitive positioning in the emerging cell chemistry landscape.
| Leading Market Players |
|---|
| Natron Energy |
| Ningbo Ronbay New Energy Technology Co |
| Ionic Materials |
| A123 Systems LLC |
| Zhejiang Huayou Cobalt Co Ltd |
| Targray Group |
| Guoxuan |
| Farasis Energy Inc |
| Group1 |
| Others |
Value Network & Pricing Analysis
Tariff exposure under India's PLI scheme for advanced chemistry cells determines both pricing tier spreads and supply chain shape, compressing landed costs for domestic assembly while elevating unpackaged import prices.
Pricing Analysis
Long-term offtake contracts dominate utility-scale procurement, with project-based pricing for containerized energy storage systems and spot transactions for cathode precursor chemicals. Price differentiation hinges on certification grade—REACH dossier completion for Prussian blue analog cathodes commands premiums in Dutch and Danish markets—and volume scale, with gigawatt-hour commitments unlocking standard-tier economics. Cost compression in small-scale cylindrical cells is intensifying because Shenzhen pack assemblers qualify alternative chemistries for export price hedging. Commercial fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, while data center UPS buyers prioritize reliability over unit economics.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Ningbo and Shenzhen cell assembly corridors, where cathode precursor refiners integrate with formation cycling operations. Geographic supply concentration centers on China for spherical graphite processing and Prussian blue analog synthesis, India for PLI-advantaged pack assembly, and Germany for lignin-derived hard carbon qualification. Raw material dependencies rest on potassium salt feedstocks, iron and manganese cathode precursors, and biomass anode sources from coconut shell and rice husk waste streams. Single-source vulnerability in Shandong and Heilongjiang spherical graphite processing creates qualification bottlenecks for anode material. Distribution runs through direct procurement relationships between cell manufacturers and utility engineering departments, bypassing traditional EPC intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Potassium-ion chemistry is emerging from a lithium supply cycle trough, with fleet electrification mandates and dual carbon policy commitments providing cyclical uplift across the forecast horizon.
For Market Incumbents: Insulate formation cycling capacity through backward integration into hard carbon feedstock supply, securing lignin and cellulose biomass streams from paper and pulp conglomerates. Prioritize REACH dossier completion for Prussian blue analog cathodes to defend European utility procurement relationships against Korean and Japanese sodium-ion heritage competitors. For New Entrants and Emerging Players: Pursue stationary storage integration partnerships with German grid operators qualifying four-hour duration assets, where sodium-ion heritage architectures lower technical qualification barriers. Target Indian solar-plus-storage developers leveraging PLI scheme tariff advantages, offering transparent degradation curves that satisfy Central Electricity Authority technical standards. For Investors and Strategic Acquirers: Cathode material specialists with integrated potassium salt refining capabilities present acquisition targets with supply security moats. Frame long-term viability around electrolyte formulation stability thresholds as the inflection signal—monitoring Chinese additive package optimizations that extend cycle life benchmarks beyond laboratory thresholds indicates commercial readiness acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Ningbo refiners securing iron hexacyanoferrate feedstocks bypass cobalt and nickel supply constraints. |
| Formation Cycling Capacity Expansion | Detroit and Austin equipment clusters address extended initial charge-discharge cycle requirements. |
| REACH Dossier Completion | Completed substance registration unlocks Dutch and Danish utility procurement prioritization. |
| Biomass Hard Carbon Sourcing | Lignin and cellulose precursors from agrarian waste streams unlock sustainable anode supply. |
| PLI Scheme Domestic Assembly | Gujarat and Tamil Nadu pack assemblers gain tariff advantages over unpackaged imports. |
Research Methodology
Initial hypotheses were tested against primary input from cell manufacturing executives, utility procurement officers, cathode material R&D directors, and EPC contract managers, and refined through secondary validation against MIIT funding disclosures, FERC interconnection filings, ECHA REACH registration databases, and Indian Central Electricity Authority technical standards. Bottom-up cell shipment estimates triangulated with top-down grid storage procurement pipeline analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling capacity expansion timelines against fleet electrification procurement schedules. Segmentation dimensions included product format, end-use application, electrode material technology, and regional regulatory incentive structure. CAGRs were derived from electrolyte formulation stability trajectories and cathode material yield improvement curves specific to Prussian blue analog commercialization.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices or potassium salt export tariff regimes would shift the trajectory of alternative chemistry investment. Quarterly review of MIIT pilot line commissioning announcements and UN 38.3 certification pathway developments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Aluminium-Sulfur Battery Market
Batteries
Medical Batteries Market
Batteries
Wood-Based Batteries Market
Batteries
Primary Lithium Battery Market
Batteries
Industrial Battery Charger Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Military Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
Europe Lead-Acid Battery Market
Batteries
North Africa Battery Market
Batteries
Molten Salt Battery Market
Batteries
Nickel-Based Battery Charger Market
Batteries
SLI Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Battery Anode Materials Market