
 Asia Power Tool Batteries Market | 2026-2036
Asia Power Tool Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Power Tool Batteries Market Analysis
China's dual carbon goals is recalibrating procurement criteria across the Asia Power Tool Batteries landscape, pushing OEMs toward higher energy-density cell architectures and cleaner supply chains. Samsung SDI Co., Ltd leverages its cylindrical cell expertise to anchor premium cordless platforms for industrial users. Makita Corporation dominates professional-grade segments through integrated battery and tool ecosystems. Panasonic Corporation sustains its position via nickel-metal hydride legacy lines serving price-sensitive replacement markets.
Asia power tool batteries store and discharge electrical energy through electrochemical cells, typically lithium-ion packs rated between 18V and 40V with capacities from 2.0Ah to 12.0Ah, designed to deliver sustained current for brushless motors in cordless equipment. The lithium-ion product type leads value generation due to superior cycle life and reduced weight versus nickel-cadmium alternatives, though nickel-metal hydride retains niche traction in cold-climate applications. Professional contractors represent the most concentrated end-user margin pool, while the home improvement application segment shows structural expansion as cordless platforms penetrate residential maintenance workflows.
China's SAMR enforces GB standards for lithium-ion cell safety and transportation, while Japan's METI governs battery recycling obligations under its home appliance recycling law; India's BIS certification mandates cell-level testing for imported packs. These frameworks elevate compliance costs for non-integrated suppliers but protect incumbent manufacturers with established certification infrastructure. Stakeholders must monitor evolving chemistry-specific regulations and cell origin traceability requirements as regional supply chains decouple from sole-source dependencies.
Market Dynamics
China's dual carbon goals are compressing the competitive window for nickel-cadmium architectures while lithium-ion cell production concentrates in the Yangtze River Delta manufacturing belt. This structural pivot forces suppliers to recalibrate chemistry roadmaps and certification pipelines simultaneously.
Growth Catalysts
- GB Standards Compliance:China's SAMR enforcement of GB/T 18287 safety protocols for lithium-ion cells is accelerating factory upgrades across Guangdong and Jiangsu provinces, eliminating subscale nickel-cadmium producers.
- Brushless Motor Adoption:Professional contractors in Vietnam and Indonesia are standardizing 18V-40V cordless platforms for concrete drilling and metal cutting applications, pulling high-discharge battery demand.
- Recycling Mandates:Japan's METI home appliance recycling law is creating closed-loop material recovery infrastructure that reduces virgin cobalt dependency for domestic cell manufacturers.
Market Restraints
- Cobalt Price Volatility:Cathode material cost swings tied to Democratic Republic of Congo concentrate supply are compressing gross margins for non-integrated pack assemblers.
- Cell Import Concentration:India's BIS certification backlog for imported cylindrical cells creates 90-120 day procurement delays for domestic power tool OEMs lacking captive cell lines.
- Thermal Runaway Limitations:High-discharge applications above 100A continuous draw still favor nickel-metal hydride in sub-zero climates, constraining lithium-ion penetration in northern Japan construction sites.
Strategic Opportunities
- Indonesia Manufacturing Buildout:Battery pack assembly investments in Batam free trade zone offer tariff-advantaged export positioning into ASEAN markets with tightening Rules of Origin requirements.
- Solid-State Convergence:Sulfide-based electrolyte research is integrating with existing cylindrical form factors, promising 40% energy density gains for premium professional tool lines by late-decade.
- Digital Distribution Channels:Industrial e-procurement platforms are bypassing traditional electrical wholesale networks in South Korea, enabling direct battery pack sales to mid-sized contractor fleets.
Industry Challenges
- Electrochemical Engineering Talent Scarcity:Cell characterization and battery management system firmware development functions face acute shortages across Shenzhen and Suzhou tech corridors.
- Dual Certification Burden:Simultaneous GB standards compliance for China and PSE marking for Japan extends product launch timelines by 8-12 months for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Power Tool Batteries Market |
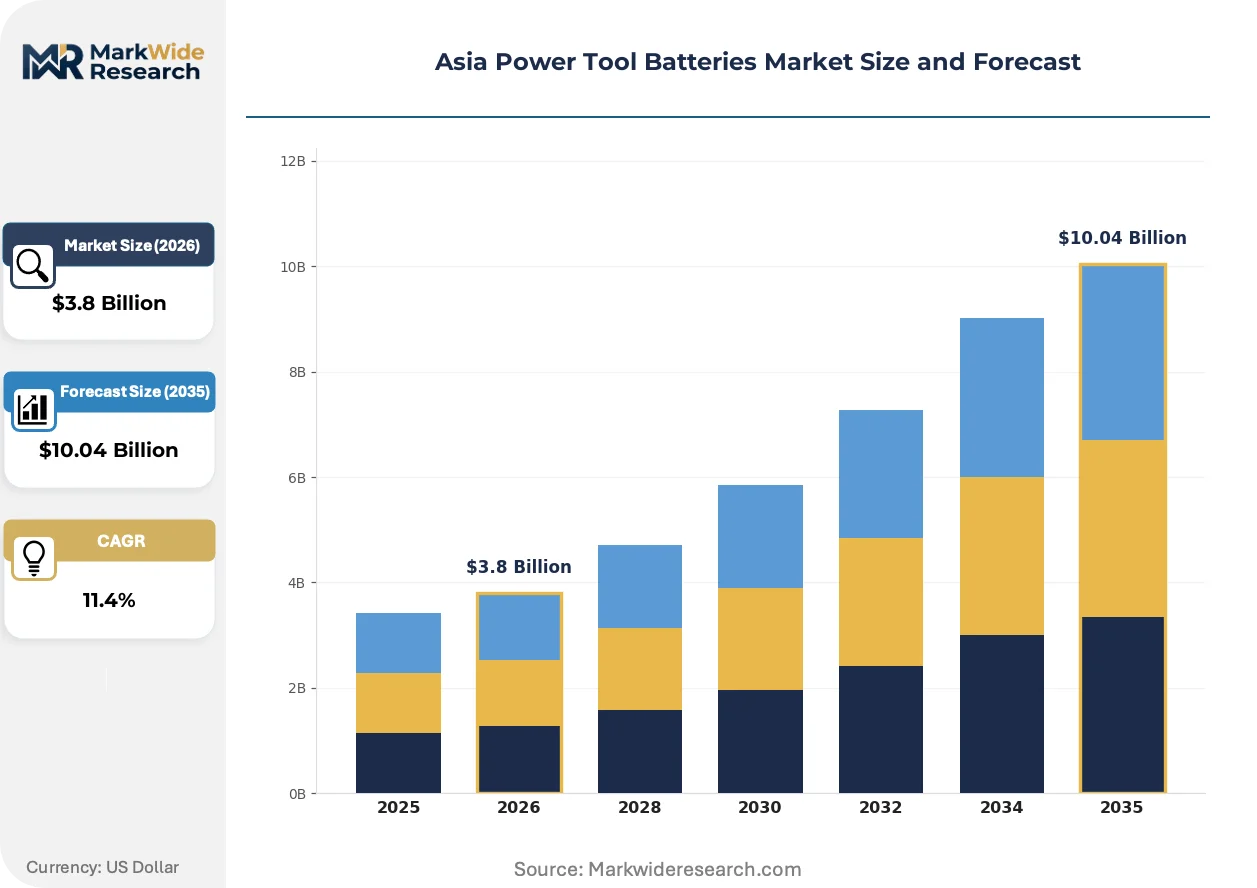
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Nickel-Cadmium, Nickel-Metal Hydride, Lead-Acid Application: Construction, Automotive, Manufacturing, Home Improvement End User: DIY Enthusiasts, Professional Contractors, Industrial Users, Retail Customers Size: Compact, Medium, Heavy-Duty, Portable |
| Companies Covered | Bosch Ltd, Makita Corporation, Panasonic Corporation, Hitachi Ltd, Samsung SDI Co., Ltd, Ryobi Limited, Stanley Black & Decker Inc., Hilti Corporation, Techtronic Industries Company Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Power Tool Batteries Market Emerging Trajectories
Solid-state electrolyte research and silicon-anode architectures are compressing the performance gap between consumer electronics cells and industrial power tool applications. These chemistry advances coincide with procurement digitization and regional regulatory divergence.
Silicon-composite anodes are integrating into high-nickel cathode configurations to push 21700 cylindrical cells beyond 5.0Ah capacity thresholds. Korean construction equipment fleets are piloting these packs for extended concrete grinding cycles without voltage sag. The technology is integrating charge-rate capabilities that reduce midday downtime for professional crews.
China's GB 31241-2022 cell safety standard is mandating nail penetration and overcharge abuse testing that exceeds IEC 62133 baseline requirements. Domestic OEMs with in-house testing laboratories are compressing third-party certification cycles. Export-oriented manufacturers in Ningbo and Dongguan are most affected, retooling thermal management architectures to satisfy dual compliance pipelines.
Industrial buyers are consolidating cordless platform commitments to single-voltage ecosystems, prioritizing battery interchangeability across drill, grinder, and saw tool categories. Traditional electrical wholesalers in Bangkok and Kuala Lumpur are losing share to manufacturer-direct fleet management contracts. This pattern is most visible in Vietnam's commercial construction vertical, where general contractors now specify platform-locked procurement in tender documents.
Asia Power Tool Batteries Market Segmentation
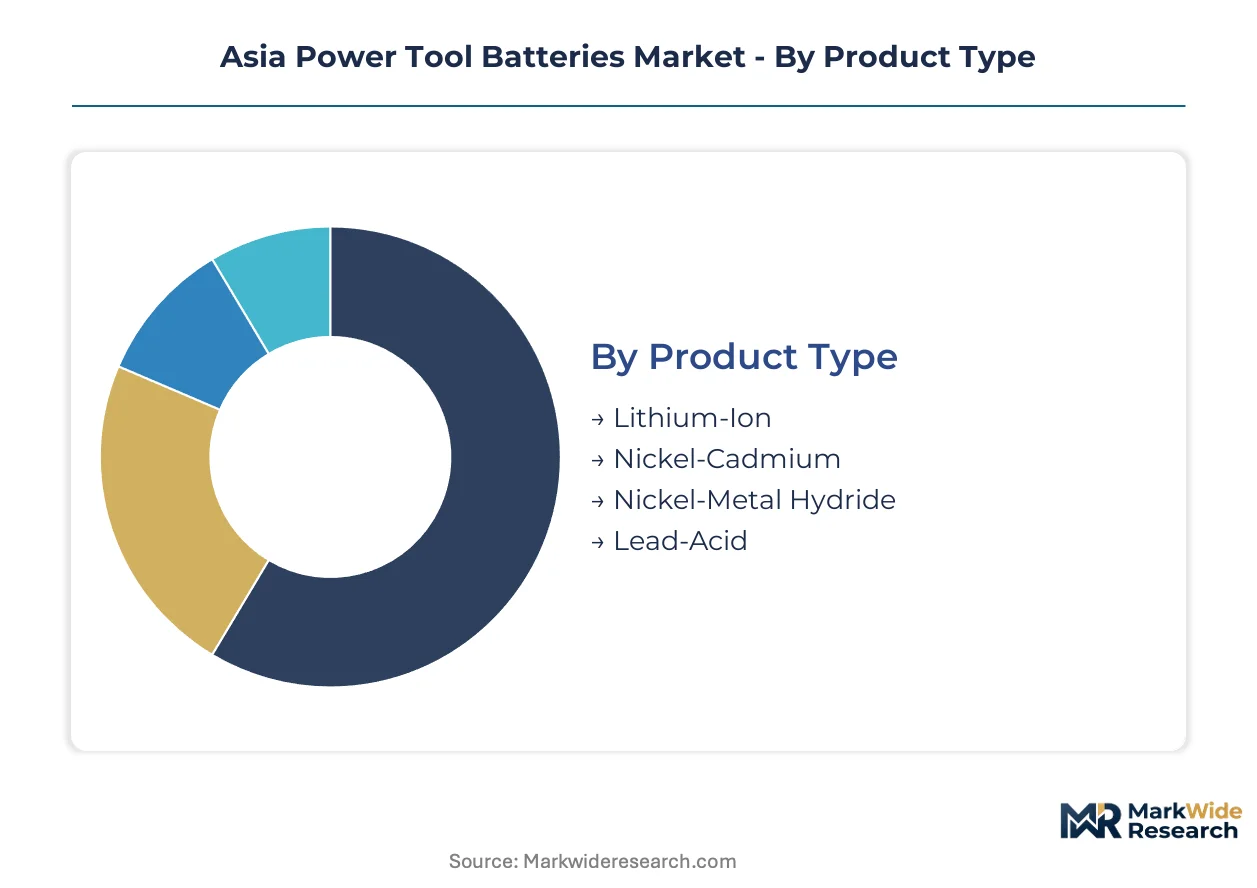
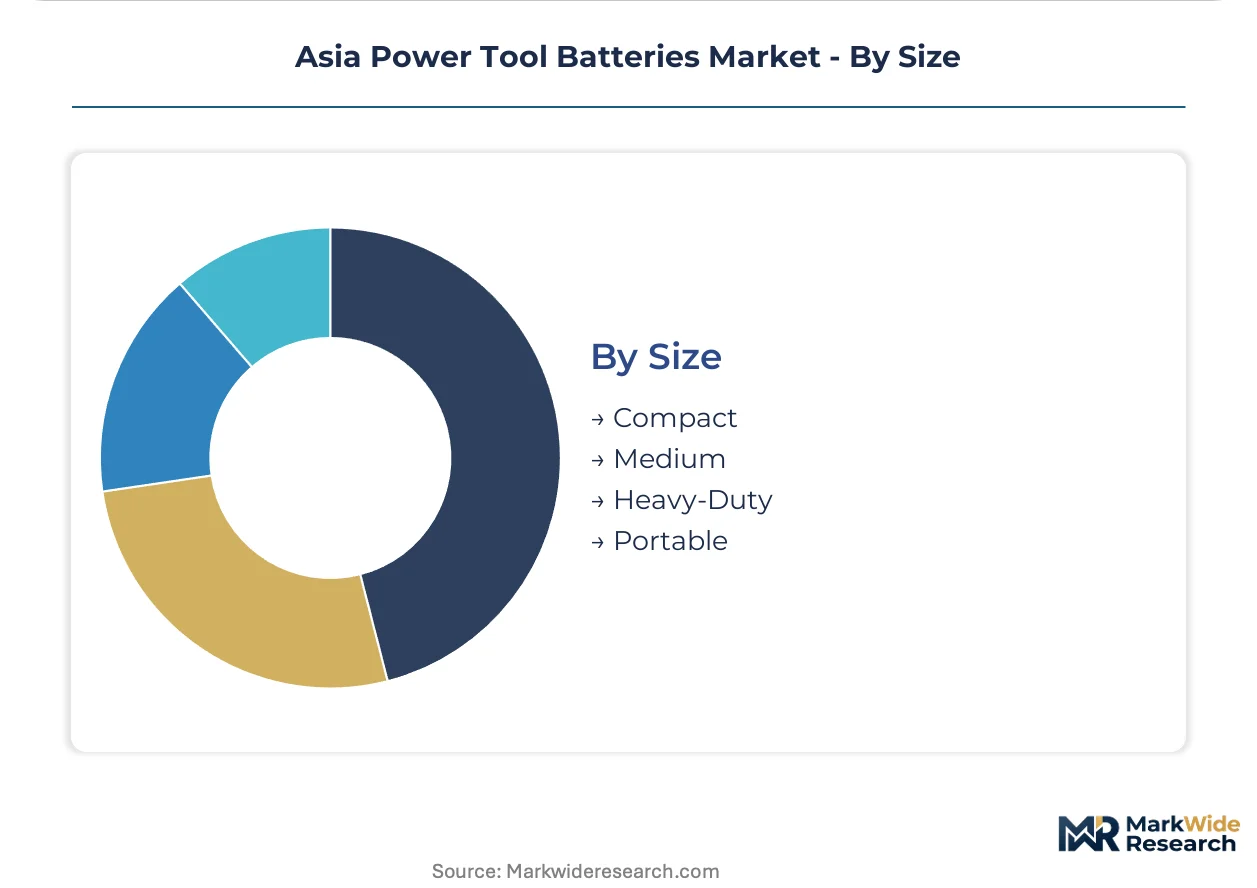
Segmentation reveals how chemistry choices, end-use intensity, and physical form factors split procurement budgets across Asia's power tool battery landscape. Suppliers calibrate cell architectures and pack geometries to match distinct voltage, cycle life, and thermal requirements.
Product Type:
Cell chemistry supply concentrates in China's Yangtze River Delta, where integrated producers leverage captive cathode material streams to serve both domestic OEMs and export pack assemblers.
- Lithium-Ion:High-nickel cathode configurations in 18650 and 21700 cylindrical formats deliver 18V-40V platforms with 2.0Ah-12.0Ah capacity ranges. Demand clusters in Guangdong province manufacturing belts where cordless tool OEMs source packs for brushless motor applications. SAMR's GB 31241-2022 safety mandates are compressing qualification cycles for imported cell alternatives.
- Nickel-Cadmium:Robust tolerance to deep discharge and sub-zero operation sustains niche deployment in northern Japan construction sites and legacy tool fleets. China's dual carbon goals are accelerating factory closures across Jiangsu province, eliminating subscale producers unable to fund environmental compliance upgrades.
- Nickel-Metal Hydride:Retains replacement market traction for cold-climate applications where thermal runaway risks constrain lithium-ion adoption.
- Lead-Acid:Survives in stationary backup and price-sensitive bulk storage roles, though energy density limitations exclude cordless tool integration.
Today's leader: Lithium-Ion. Tomorrow's challenger: Solid-state derivatives gaining pilot traction in Korean R&D pipelines.
Application:
End-use intensity determines pack specification tiers, with high-discharge continuous draw applications commanding premium cell selections and reinforced thermal management architectures.
- Construction:Concrete drilling and metal cutting operations in Vietnam and Indonesia pull 40V high-capacity configurations with sustained 100A+ discharge capability. General contractors in Ho Chi Minh City and Jakarta now specify voltage-locked procurement in tender documents, consolidating fleet interoperability around single-platform commitments.
- Manufacturing:Assembly line cordless tools in China's Pearl River Delta require rapid charge-rate compatibility to minimize shift-change downtime. Pack-as-a-service leasing models are emerging in Dongguan electronics assembly clusters.
- Automotive:Aftermarket repair shops in Thailand and Malaysia source mid-voltage packs for diagnostic equipment and portable lighting systems.
- Home Improvement:Residential maintenance workflows in South Korea's apartment renovation sector show structural expansion as cordless platforms displace corded alternatives for drilling and fastening tasks.
Construction commands current procurement volumes. Home Improvement climbs the fastest as residential electrification penetrates middle-income households.
End User:
Customer type stratification mirrors margin architecture, with fleet-scale professional accounts extracting volume discounts while DIY segments absorb retail markups through distributor networks.
- Professional Contractors:Concentrated margin pool across Southeast Asia commercial construction verticals. Fleet standardization on 18V-40V platforms in Bangkok and Kuala Lumpur is compressing electrical wholesaler margins as manufacturer-direct procurement expands.
- Industrial Users:Automotive and electronics manufacturing facilities in Shenzhen and Suzhou specify pack interchangeability across tool categories to minimize inventory carrying costs.
- DIY Enthusiasts:Price-sensitive segment served through retail channels in India's urban centers, with BIS certification requirements for imported cells creating procurement friction.
- Retail Customers:Replacement battery purchases through e-commerce platforms in South Korea, where industrial e-procurement channels are bypassing traditional distribution.
Professional Contractors anchor margin capture. Industrial Users represent the steepest expansion trajectory as manufacturing automation deepens cordless tool penetration.
Size:
Physical form factor selection trades energy density against ergonomic constraints, with compact geometries dominating residential applications and heavy-duty configurations serving extended-cycle industrial operations.
- Heavy-Duty:Extended-cycle packs for concrete grinding and demolition applications in Indonesia's infrastructure buildout. Korean construction equipment fleets pilot silicon-anode 21700 configurations exceeding 5.0Ah thresholds.
- Compact:Lightweight 2.0Ah-4.0Ah formats for overhead drilling and confined-space fastening in Japan's renovation sector.
- Medium:Versatile 5.0Ah-8.0Ah capacity range serving general-purpose drilling and sawing across China's residential construction belt.
- Portable:Modular pack designs enabling field-swappable configurations for remote site operations in Philippines archipelago construction.
Heavy-Duty commands premium pricing. Compact gains share fastest as residential tool penetration accelerates in aging housing stock markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia's power tool battery workforce clusters around electrochemical engineering talent pools in Shenzhen, Suzhou, and Nagoya, with factory technicians and BMS firmware developers commanding premium wages across the Yangtze River Delta manufacturing belt.
China
Construction contractors in Guangdong province are standardizing 40V cordless platforms for concrete drilling applications. SAMR's GB 31241-2022 cell safety mandates are forcing factory upgrades across Jiangsu province, eliminating subscale nickel-cadmium producers unable to fund compliance investments. Dongguan electronics assembly clusters now pilot pack-as-a-service leasing models to minimize shift-change downtime.
Japan
Professional contractors in Tokyo and Osaka demand compact 2.0Ah-4.0Ah formats for overhead drilling in aging housing stock renovations. METI's home appliance recycling law creates closed-loop material recovery infrastructure that reduces virgin cobalt dependency for domestic cell manufacturers. Nagoya's industrial corridor hosts integrated producers leveraging captive cathode material streams for brushless motor applications.
South Korea
Korean construction equipment fleets pilot silicon-anode 21700 configurations exceeding 5.0Ah thresholds for extended concrete grinding cycles. The country's national industrial regulator enforces cell-level testing protocols that exceed baseline IEC requirements. Seoul's industrial e-procurement platforms bypass traditional electrical wholesale networks, enabling direct battery pack sales to mid-sized contractor fleets.
Vietnam
Commercial construction verticals in Ho Chi Minh City specify voltage-locked procurement in tender documents, consolidating fleet interoperability around single-platform commitments. The country's national standards body mandates BIS-equivalent certification for imported cylindrical cells, creating procurement friction for non-integrated suppliers. Batam free trade zone pack assembly investments offer tariff-advantaged export positioning into ASEAN markets.
India
Aftermarket repair shops in Mumbai and Delhi source mid-voltage packs for diagnostic equipment and portable lighting systems. BIS certification backlog for imported cylindrical cells creates 90-120 day procurement delays for domestic power tool OEMs lacking captive cell lines. Gujarat's manufacturing belt attracts pack assemblers seeking to bypass import certification bottlenecks through local cell sourcing partnerships.
Asia Power Tool Batteries Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across Asia's power tool battery landscape, with integrated cell manufacturers facing off against pack assemblers sourcing from third-party cathode suppliers. The market structure tilts toward consolidation among cylindrical cell specialists with captive material streams, while non-integrated pack makers struggle against dual certification burdens. Three archetypes dominate: vertically integrated electronics conglomerates, pure-play power tool OEMs with captive battery ecosystems, and independent cell suppliers serving multiple tool brands. Capacity expansion and strategic partnerships represent the dominant competitive vectors as firms race to secure cathode material offtake agreements.
Within the integrated electronics tier, Samsung SDI Co., Ltd and Panasonic Corporation exemplify capital-heavy producers with cylindrical cell expertise anchoring premium cordless platforms. Makita Corporation occupies a position among pure-play tool OEMs that dominate professional-grade segments through integrated battery and tool ecosystems. These three companies represent contrasting strategic postures: the cell-first conglomerate model, the tool-first ecosystem approach, and the legacy chemistry incumbent defending replacement market positions.
| Leading Market Players |
|---|
| Bosch Ltd |
| Makita Corporation |
| Panasonic Corporation |
| Hitachi Ltd |
| Samsung SDI Co., Ltd |
| Ryobi Limited |
| Stanley Black & Decker Inc. |
| Hilti Corporation |
| Techtronic Industries Company Limited |
| Others |
Supply Flow & Price Mechanics
Cobalt metal price volatility on the London Metal Exchange cascades through cathode material costs into tiered pack pricing across Guangdong and Jiangsu manufacturing belts. Professional contractors absorb premium lithium-ion configurations while price-sensitive DIY segments retreat toward nickel-metal hydride alternatives in India's replacement markets.
Pricing Analysis
Bundled fleet-management contracts now separate from unbundled per-pack transactions across Southeast Asia procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under GB 31241-2022 and volume-scale commitments from general contractors. Pricing pressure stems from cathode material cost swings tied to Democratic Republic of Congo concentrate supply. DIY enthusiasts through India's urban retail channels exhibit highest price sensitivity; integrated OEMs with captive cell lines demonstrate lowest.
Supply Chain Analysis
Dual-sourcing requirements from Vietnam's commercial construction verticals now mandate multi-supplier qualification for cylindrical cell procurement. Manufacturing gravity draws from China's Yangtze River Delta, South Korea's industrial corridors, and Japan's Nagoya tech belt. Raw material dependencies rest on cobalt concentrate, high-purity nickel sulfate, and electrolyte solvents. Single-source vulnerability concentrates in cathode precursor supply. Distribution runs through manufacturer-direct fleet contracts compressing traditional Bangkok and Kuala Lumpur electrical wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Power Tool Batteries Market functions as a stable compounder anchored by cordless platform standardization across Southeast Asian construction verticals. Structural fleet commitments generate recurring replacement demand independent of cyclical new-tool purchases.
For Market Incumbents: Anticipate solid-state electrolyte convergence by securing sulfide-based research partnerships before chemistry roadmaps lock. Defend position by accelerating GB standards pre-certification in Dongguan testing laboratories to compress launch timelines against multi-market entrants. Priority lever: captive cathode material streams. For New Entrants and Emerging Players: Mid-sized contractor fleets in Indonesia's Batam free trade zone represent an underserved buyer archetype bypassed by integrated OEM direct-sales organizations. Target pack-assembly investments with tariff-advantaged ASEAN export positioning. White-space penetration runs through industrial e-procurement platforms in Seoul bypassing traditional distribution layers. For Investors and Strategic Acquirers: Asymmetric upside sits with cylindrical cell specialists possessing captive material streams and established SAMR certification infrastructure. Five-to-ten-year viability favors integrated producers over non-integrated pack assemblers facing dual certification burdens. Signal to watch: BIS certification backlog resolution in India indicating import dependency reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Secures cobalt and nickel sulfate supply chains against LME price volatility for Guangdong pack producers. |
| GB Standards Pre-Certification Investment | Compresses SAMR qualification cycles by 8-12 months versus third-party testing for multi-market suppliers. |
| Silicon-Anode R&D Partnership | Pushes 21700 cylindrical cells beyond 5.0Ah thresholds for Korean construction equipment fleet pilots. |
| Batam Free Trade Zone Assembly Buildout | Delivers tariff-advantaged export positioning into ASEAN markets with tightening Rules of Origin requirements. |
| Industrial E-Procurement Platform Integration | Bypasses traditional Bangkok electrical wholesaler networks for direct mid-sized contractor fleet access. |
Methodological Framework
Multiple input streams — primary interviews with power tool OEM procurement directors, battery pack engineering leads, and SAMR certification specialists; secondary validation through customs trade data, SEC 10-K filings, and GB standards documentation; plus bottom-up and top-down triangulation — were reconciled to construct segment-level demand estimates across the analysis window.
Cross-referencing historical shipment patterns with panel input from Dongguan and Suzhou manufacturing clusters anchored the analytical framework. Segmentation dimensions modeled include cell chemistry type, voltage platform tier, end-use intensity, and regional regulatory cluster. CAGRs were derived from slope analysis of normalized growth trajectories. Forecast inputs incorporated brushless motor adoption curves and GB 31241-2022 compliance investment schedules.
Underlying measurement precision varies by segment; lithium-ion product type and professional contractor end-use carry tighter precision than nickel-cadmium legacy lines and DIY enthusiast segments. Forecasts reflect assumptions around cobalt price stability and SAMR enforcement continuity. Deviation in China's dual carbon policy acceleration or BIS certification backlog resolution would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Battery Cases Market
Batteries
Japan Battery Market
Batteries
Zinc Carbon Battery Market
Batteries
N-Type Battery Market
Batteries
Global Solar Battery Charger Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Aluminum Wire Battery Market
Batteries
East Europe Battery Market
Batteries
Battery Binders Market
Batteries
Asia-Pacific Primary Battery Market
Batteries
Coin Cell Lithium Batteries Market
Batteries
Aluminum-Air Battery Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Printable Battery Market
Batteries
18650 And 21700 Battery Market