
 Rechargeable Battery Market | 2026-2036
Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Rechargeable Battery Market Intelligence
The EU Battery Regulation is expanding compliance obligations for cell producers across the European value chain, requiring carbon footprint declarations and recycled content minimums that reshape procurement criteria for automotive buyers. Panasonic Corporation leverages its cylindrical cell expertise to sustain long-term supply relationships with premium EV manufacturers. LG Energy Solution differentiates through high-nickel chemistry leadership and vertical integration into cathode precursor production. Contemporary Amperex Technology Co. Limited dominates global production capacity through aggressive scale expansion and cost-engineered lithium-iron-phosphate platforms.
Rechargeable batteries are electrochemical energy storage devices designed for multiple charge-discharge cycles, typically employing lithium-ion chemistry with graphite anodes and transition-metal-oxide cathodes delivering energy densities of 250-300 Wh/kg for mobility applications. Their primary commercial purpose is to decouple energy generation from consumption, enabling portable electronics, electrified transport, and grid-scale storage. Lithium-ion products anchor current revenue pools across consumer electronics and electric vehicle applications, while solid-state configurations represent the fastest-growing technology segment as manufacturers pursue higher energy density and reduced thermal runaway risk. Battery management systems constitute a critical margin concentration point where semiconductor integration and software-defined control create differentiation.
The EU Battery Regulation, EPA hazardous waste standards, and China's GB/T battery safety standards collectively define product compliance, recycling infrastructure requirements, and market access conditions across major production geographies. REACH chemical restrictions and RoHS substance limits further constrain material selection for electrode binders and electrolyte additives in European supply chains. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation threatens to segment cell designs and raise qualification costs for multi-region suppliers.
Market Dynamics
Lithium-iron-phosphate chemistry is displacing nickel-cobalt-manganese formulations across electric vehicle and energy storage procurement, compressing cathode material supply chains and rewiring tier-one supplier relationships as automotive OEMs prioritize thermal stability and cost engineering over energy density.
Growth Catalysts
- EU Battery Regulation recycled content mandates:Automotive OEMs in Germany, France, and Italy now require suppliers to certify minimum recycled lithium and cobalt thresholds, creating qualified supplier lists that favor integrated recyclers.
- China's state-backed energy storage procurement:Provincial grid operators under the National Energy Administration execute annual gigawatt-hour tenders that concentrate demand and validate lithium-iron-phosphate cell economics at scale.
- Silicon-anode material advances:Solid-electrolyte interphase engineering from materials startups enables 20% energy density gains in cylindrical cells without manufacturing line retooling.
Market Restraints
- Lithium carbonate price volatility:Spot market swings in Chilean and Australian spodumene concentrate feedstock transmit directly to cell cost structures, eroding margin visibility for tier-two producers.
- Cathode precursor supply concentration:Over 70% of high-nickel cathode active material refining capacity sits within Chinese state-owned enterprise control, creating single-source vulnerability for European and North American cell plants.
- Solid-state electrolyte manufacturing yield:Sulfide-based ceramic separator production remains below commercial viability thresholds, delaying automotive qualification timelines beyond 2028 for most Western suppliers.
Strategic Opportunities
- US Inflation Reduction Act domestic content credits:Battery cell and module production qualifying under the $35 per kilowatt-hour tax credit creates location incentives for cathode precursor plants in Texas and Tennessee.
- Second-life stationary storage applications:Retired electric vehicle battery packs with 70-80% remaining capacity are redeploying into grid-scale buffering systems, extending value capture across 15-20 year asset lifecycles.
- India PLI scheme for advanced chemistry cells:Production-linked incentive disbursements for gigafactory investments in Gujarat and Tamil Nadu open import-substitution positioning for lithium-iron-phosphate and sodium-ion platforms.
Industry Challenges
- Electrolyte formulation chemist scarcity:The specialized knowledge base for fluorinated additive synthesis and high-voltage stability engineering concentrates within a handful of Japanese and South Korean research institutions.
- UN 38.3 lithium battery certification timelines:Third-party testing laboratory backlogs for air transport safety documentation extend product launch schedules by 4-6 months for new cell geometries.
- Legacy lead-acid infrastructure retrofit:Existing automotive 12V battery distribution networks require cold-chain and state-of-charge monitoring upgrades incompatible with lithium-ion handling protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rechargeable Battery Market |
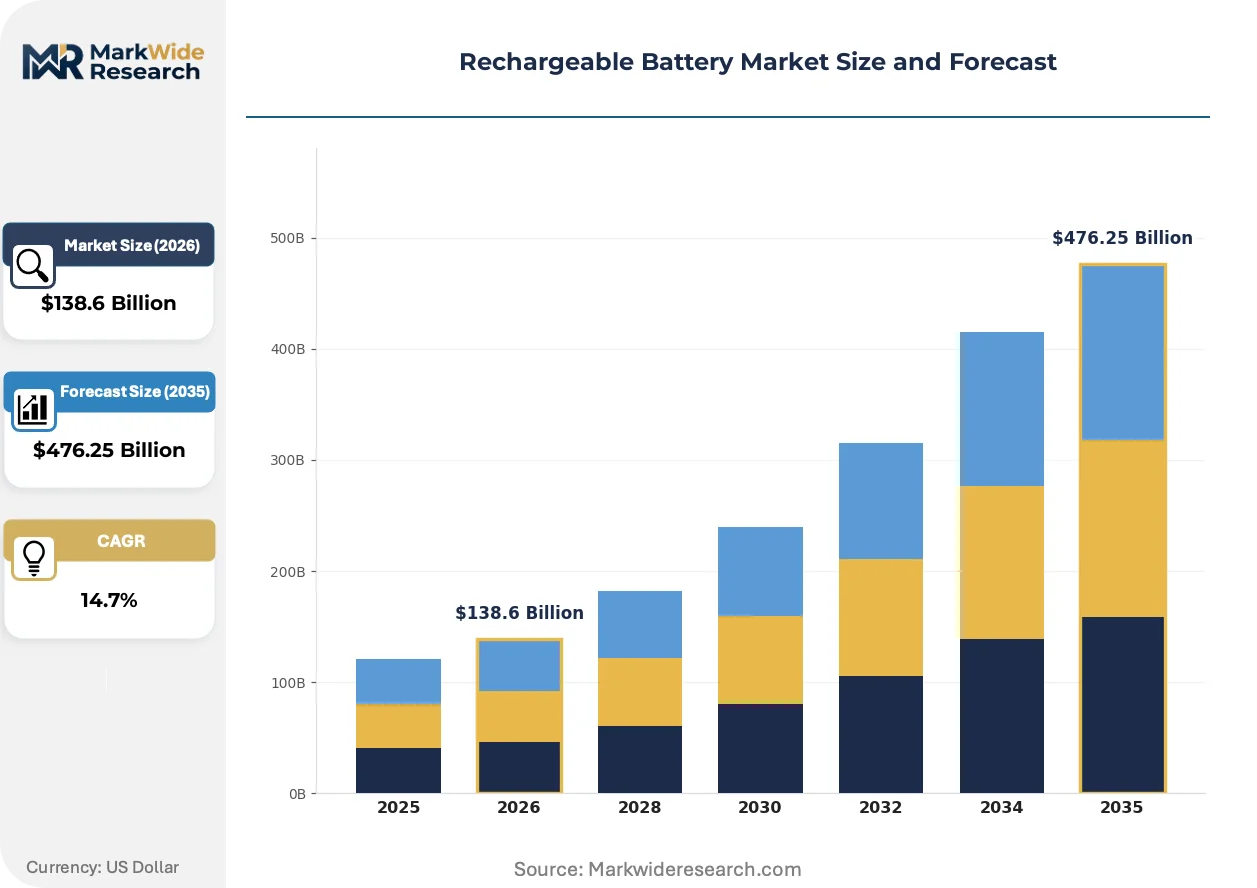
| Market Size in 2026 | $138.6 Billion |
| Market Size in 2035 | $476.25 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Metal Hydride, Lead Acid, Nickel-Cadmium, Solid State, Zinc-Air Application: Consumer Electronics, Electric Vehicles, Grid Energy Storage, Industrial Equipment, Aerospace Systems, Wearable Devices Technology: Fast Charging, Wireless Charging, Thermal Management, Battery Management Systems, Advanced Electrode Materials, Solid Electrolyte End User: Vehicle Manufacturers, Electronic Device Makers, Renewable Energy Providers, Heavy Machinery Operators, Defense Sector, Medical Equipment Suppliers |
| Companies Covered | Panasonic Corporation, Contemporary Amperex Technology Co. Limited, Samsung SDI, LG Energy Solution, BYD Company Ltd., Tesla Inc., EnerSys, A123 Systems, Duracell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rechargeable Battery Market Strategic Shifts & Innovations
Cell manufacturing is bifurcating between gigascale commodity production and precision-engineered premium platforms, with equipment suppliers and materials scientists racing to solve the thermal management and formation-cycle bottlenecks that constrain output velocity.
Dry electrode coating is electrifying conventional solvent-based manufacturing by eliminating N-methyl-2-pyrrolidone recovery systems and slashing drying energy intensity. Tesla and BMW have both qualified pilot lines using this technology for their next-generation cylindrical cells. The process compression is electrifying capital efficiency benchmarks and forcing incumbent coating equipment makers to accelerate R&D or lose automotive qualification windows.
REACH chemical authorization amendments are restricting per- and polyfluoroalkyl substances in electrode binders and electrolyte additives across European manufacturing. Cell producers must reformulate wetting agents and separator coatings by 2026 to maintain market access. High-performance automotive segments face the steepest substitution costs, with some suppliers shifting qualification work to US and Asian plants outside direct ECHA jurisdiction.
Fleet operators and renewable developers now specify battery management system data portability as a contractual requirement, rejecting vendor-locked software architectures that prevent third-party analytics integration. This unbundling of hardware from control software is disrupting traditional tier-one supplier relationships. The shift is most visible in California and Germany, where utility-scale storage procurement frameworks mandate open communication protocols for grid interconnection compliance.
Rechargeable Battery Market Segmentation
Segmentation in rechargeable batteries reveals how chemistry choices, application requirements, and buyer procurement criteria fragment the competitive landscape. Understanding these divisions exposes where margin concentrates and which technology transitions threaten incumbent positions.
Product Type:
Procurement decisions hinge on the trade-off between energy density requirements and total cost of ownership across cycle life.
- Lithium-ion:Dominant chemistry employing graphite anodes and layered oxide cathodes delivering 250-300 Wh/kg. Demand concentrates in electric vehicle powertrains from German and Chinese automotive OEMs prioritizing range performance and fast-charge capability.
- Solid State:Ceramic or polymer electrolyte configurations replacing flammable liquid separators. Commercial traction accelerates in South Korean and Japanese premium EV programs where thermal runaway elimination justifies manufacturing complexity premiums.
- Nickel-Metal Hydride:Mature chemistry with rare-earth hydrogen storage alloys. Hybrid electric vehicles in Toyota's Japanese production network sustain procurement volumes despite lithium-ion displacement pressure.
- Lead Acid:Flooded and valve-regulated designs with sulfuric acid electrolyte. Stationary backup power in Indian telecom infrastructure and US uninterruptible power supply installations preserves demand.
- Nickel-Cadmium:Sintered plate construction with potassium hydroxide electrolyte. Aviation starting systems and Russian Arctic railway signaling equipment maintain niche procurement.
- Zinc-Air:Atmospheric oxygen cathode with aqueous alkaline electrolyte. Hearing aid manufacturers in Denmark and Germany specify this chemistry for highest energy density in miniature formats.
Volume sits with Lithium-ion; growth tilts toward Solid State.
Application:
End-use specifications diverge sharply on cycle depth, calendar life, and operating temperature windows.
- Electric Vehicles:Battery electric and plug-in hybrid platforms requiring 150,000+ kilometer cycle durability. Chinese state-backed procurement programs and California ZEV mandates concentrate gigawatt-hour demand.
- Grid Energy Storage:Utility-scale buffering and frequency regulation installations. Texas ERCOT interconnection queues and German transmission system operator tenders validate lithium-iron-phosphate economics at multi-hour duration.
- Consumer Electronics:Smartphones, laptops, and tablets prioritizing volumetric energy density. Apple and Samsung supply chains in Vietnam and South Korea drive cylindrical and pouch cell procurement.
- Industrial Equipment:Forklifts, mining vehicles, and port handling machinery. European warehouse automation adopters in the Netherlands and Belgium shift from lead-acid to opportunity-charged lithium-ion.
- Aerospace Systems:Satellite power systems and electric propulsion prototypes. NASA Artemis program suppliers and French defense procurement specify radiation-hardened cell designs.
- Wearable Devices:Smartwatches, fitness bands, and medical patches. Swiss watch manufacturers and Boston health-tech startups demand sub-500 milliampere-hour formats with flexible form factors.
Revenue concentrates in Electric Vehicles; expansion accelerates fastest in Grid Energy Storage.
Technology:
Technology selection separates commodity cell producers from differentiated platform suppliers.
- Battery Management Systems:Integrated circuits and firmware controlling cell balancing, thermal limits, and state-of-charge estimation. Semiconductor integration from Texas Instruments and Analog Devices creates margin concentration in automotive qualification.
- Fast Charging:Electrolyte additives and anode architectures enabling 10-80% state-of-charge in under 20 minutes. Chinese EV charging network operators and Saudi electric bus fleets specify 4C-rate capable cells.
- Thermal Management:Liquid cooling plates, phase change materials, and active heating systems. Norwegian winter operation requirements and Arizona desert fleet deployments drive engineering investment.
- Advanced Electrode Materials:Silicon-graphite composite anodes and high-nickel cathode precursors. Korean materials suppliers and Finnish forestry-derived lignin binder startups compete for automotive qualification.
- Wireless Charging:Inductive and resonant power transfer eliminating connector wear. Medical implant manufacturers in Minnesota and German automotive tier-one suppliers pilot sealed enclosure designs.
- Solid Electrolyte:Sulfide, oxide, and polymer ionic conductors replacing liquid separators. Japanese automotive consortiums and US Department of Energy funding programs push manufacturing yield improvements.
Margin pools in Battery Management Systems; technology transition momentum gathers in Solid Electrolyte.
End User:
Buyer concentration and procurement sophistication vary dramatically across end-user categories.
- Vehicle Manufacturers:Vertically integrated OEMs and dedicated battery electric vehicle specialists. Tesla's Nevada operations and Volkswagen's Salzgitter facility exemplify captive cell production or long-term offtake contracting.
- Renewable Energy Providers:Solar and wind developers adding storage to power purchase agreements. NextEra Energy in Florida and Orsted in Denmark specify battery management system data portability for asset optimization.
- Electronic Device Makers:Consumer electronics brands with annual cell procurement in the billions of units. Foxconn's Indian iPhone assembly expansion and Samsung's Vietnamese production reshape regional supply allocation.
- Heavy Machinery Operators:Construction, mining, and agricultural equipment fleets. Caterpillar's electrification program and Komatsu's underground mining automation drive ruggedized cell specifications.
- Defense Sector:Military specifications requiring extreme temperature operation and supply chain security. US Department of Defense Trusted Capital program and UK Ministry of Defence battery standardization initiatives restrict qualified suppliers.
- Medical Equipment Suppliers:Implantable and portable diagnostic device manufacturers. Medtronic's Minnesota operations and Siemens Healthineers' German facilities demand ISO 13485 quality system certification.
Procurement volume aggregates at Vehicle Manufacturers; contract sophistication advances fastest among Renewable Energy Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global cell capacity while Europe and North America build domestic supply chains through subsidy-driven reshoring. This production-consumption divide creates trade flow dependencies and regulatory friction across jurisdictions.
China
State-backed procurement programs under the National Energy Administration concentrate gigawatt-hour demand for grid storage and electric buses. GB/T battery safety standards and MIIT production permits enforce domestic qualification requirements that foreign suppliers struggle to meet. The Yangtze River Delta hosts CATL's headquarters and BYD's manufacturing complexes, anchoring cathode precursor refining and cell assembly within a single logistics radius.
Germany
Volkswagen's Salzgitter facility and BMW's Leipzig operations drive automotive cell demand exceeding 100 GWh annually by 2028. The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape procurement criteria for tier-one suppliers. North Rhine-Westphalia clusters materials research at RWTH Aachen and pilot production lines for solid-state electrolyte development.
United States
The Inflation Reduction Act's $35 per kilowatt-hour production tax credit redirects investment toward Texas and Tennessee cathode plants. EPA hazardous waste standards and DOT transport regulations create compliance layers distinct from European frameworks. Nevada's Tesla Gigafactory and emerging Michigan operations represent the largest cell production footprint outside Asia.
South Korea
LG Energy Solution and Samsung SDI anchor high-nickel chemistry leadership for premium European automotive programs. MFDS industrial safety oversight and KATS standards certification govern cell export qualification. The Seoul Capital Area concentrates R&D investment in silicon-anode architectures and fast-charge electrolyte formulations.
Japan
Panasonic Corporation sustains long-term supply relationships with Tesla through cylindrical cell expertise refined at Osaka and Nevada facilities. METI technology roadmaps prioritize solid-state manufacturing yield improvements by 2027. The Kansai region hosts Toyota's hybrid battery production and materials suppliers serving aerospace qualification programs.
Rechargeable Battery Market Key Industry Players
The competitive structure tilts toward scale-driven commodity producers and chemistry-specialized premium platforms. Korean and Japanese incumbents dominate high-nickel automotive qualification while Chinese state-linked enterprises capture lithium-iron-phosphate volume through cost-engineered manufacturing. Three archetypes define positioning: integrated materials-to-cells producers, automotive-captive joint ventures, and independent contract manufacturers. Capacity expansion and backward integration into cathode precursor production constitute the dominant competitive moves reshaping tier-one supplier relationships.
Among Asian-based producers, Panasonic Corporation, LG Energy Solution, and Contemporary Amperex Technology Co. Limited occupy positions spanning the premium-to-commodity spectrum. Panasonic exemplifies the automotive-captive archetype through sustained cylindrical cell supply relationships. LG Energy Solution represents chemistry leadership in high-nickel platforms with upstream control over precursor refining. CATL anchors the scale-driven commodity tier through aggressive capacity expansion and state-backed procurement access. These three entities collectively illustrate how geographic origin, corporate structure, and integration depth segment competitive positioning across automotive and energy storage demand pools.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Contemporary Amperex Technology Co. Limited |
| Samsung SDI |
| LG Energy Solution |
| BYD Company Ltd. |
| Tesla Inc. |
| EnerSys |
| A123 Systems |
| Duracell |
| Others |
Cost & Logistics Intelligence
Lithium carbonate spot movements transmit from Chilean and Australian spodumene concentrate through to cell cost structures, with automotive OEM procurement teams in Germany and China negotiating contract terms that embed raw material pass-through clauses alongside fixed-volume commitments.
Pricing Analysis
Cycle-life guarantees anchor value-based pricing for grid storage operators, with Tesla Megapack and Fluence deployments commanding premiums against commodity cells based on throughput warranties. Price differentiation hinges on automotive qualification tier and cathode chemistry certification, with high-nickel platforms from Korean suppliers sustaining margin against lithium-iron-phosphate compression. Cost compression in cylindrical formats is intensifying because dry electrode coating adoption eliminates solvent recovery overhead. Fleet operators in California exhibit highest price sensitivity, while defense contractors in the US and UK demonstrate lowest sensitivity due to supply chain security mandates.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Long Beach aggregate cathode active material flows before final-mile delivery to cell plants in Nevada, Salzgitter, and the Yangtze River Delta. Manufacturing gravity centers on China, South Korea, and Japan, with cathode precursor refining drawing from Indonesian nickel, Chilean lithium, and DRC cobalt. Single-source vulnerability concentrates in Chinese state-owned enterprise control over high-nickel precursor capacity. Distribution runs through long-term offtake contracts with quarterly price adjustments rather than spot market procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refined lithium output from South American brine operations and Australian hard-rock mines trails gigafactory commissioning timelines, propping cell pricing through sustained feedstock tightness.
For Market Incumbents: Deepen backward integration into cathode precursor production through captive refining assets in Indonesia or Finland, insulating margin from Chinese supply concentration. Secure automotive qualification windows for silicon-anode platforms before solid-state disruption accelerates. Prioritize EU Battery Regulation compliance investment to maintain access to Volkswagen and BMW procurement lists. For New Entrants and Emerging Players: Begin with second-life stationary storage refurbishment, where retired electric vehicle packs with residual capacity offer lowest capital intensity entry. Target Indian state tenders under the PLI scheme for advanced chemistry cells, where import substitution policy creates protected demand. Pursue direct contracting with renewable developers specifying open battery management system protocols as differentiation. For Investors and Strategic Acquirers: Solid-state electrolyte manufacturing yield improvements crossing commercial viability thresholds is the leading indicator that chemistry transition timelines are compressing. Frame exposure across a five-to-ten year horizon around materials-to-cells integration depth rather than pure capacity scale. Monitor Japanese automotive consortium qualification announcements as inflection signal for premium platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Backward Integration | Indonesian nickel refining and Finnish cobalt processing reduce Chinese supply concentration risk for European automotive programs. |
| Solid-State Manufacturing Yield Improvement | Toyota and Samsung SDI pilot lines crossing commercial thresholds accelerates premium EV qualification timelines. |
| Second-Life Storage Platform Development | NextEra Energy and Orsted procurement frameworks validate 15-20 year asset lifecycle extension for retired automotive packs. |
| Dry Electrode Coating Adoption | Tesla and BMW qualification eliminates N-methyl-2-pyrrolidone recovery capital, compressing cylindrical cell cost curves. |
| Battery Management System Data Portability | California and German utility mandates unbundle hardware from software, disrupting traditional tier-one supplier lock-in. |
Research Approach
SEC 10-K filings, MIIT production permit disclosures, and EIA battery storage deployment databases formed the secondary backbone, supplemented by customs records tracking cathode active material trade flows. Primary interviews with cell plant engineering directors, automotive procurement leads at German and Chinese OEMs, and utility storage planners at ERCOT and German transmission system operators validated capacity and pricing assumptions. Bottom-up cell production counts by facility triangulated against top-down gigawatt-hour demand estimates from electric vehicle registration data and grid interconnection queues.
Bottom-up modeling aggregated individual gigafactory throughput estimates across chemistry platforms, while top-down analysis anchored total addressable market sizing against National Energy Administration procurement targets and Inflation Reduction Act credit eligibility. Segmentation across product type, application, and technology dimensions incorporated cathode chemistry evolution, solid-state manufacturing readiness, and battery management system software unbundling trends. CAGRs derived from facility commissioning timelines and raw material contract pricing trajectories rather than historical growth extrapolation.
Underlying measurement precision varies by segment; lithium-iron-phosphate production volumes carry tighter precision than solid-state qualification timelines due to commercial confidentiality around pilot yields. Forecasts reflect assumptions regarding subsidy continuity, raw material price convergence, and manufacturing yield improvement rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Modular Battery Pack Platforms for Skateboard EVs Market
Batteries
Global Industrial Battery Market
Batteries
East Africa Battery Market
Batteries
Micro Battery Market
Batteries
East Europe Battery Market
Batteries
Middle East and Africa Rechargeable Battery Market
Batteries
Automotive Start-Stop Battery Market
Batteries
United States SLI Battery Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Coin Cell Lithium Batteries Market
Batteries
India Lead-Acid Battery Market
Batteries
North America NMC Battery Pack Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Asia Power Tool Batteries Market
Batteries
West Africa Battery Market