
 Italy SLI Battery Market | 2026-2036
Italy SLI Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Italy SLI Battery Market Insights
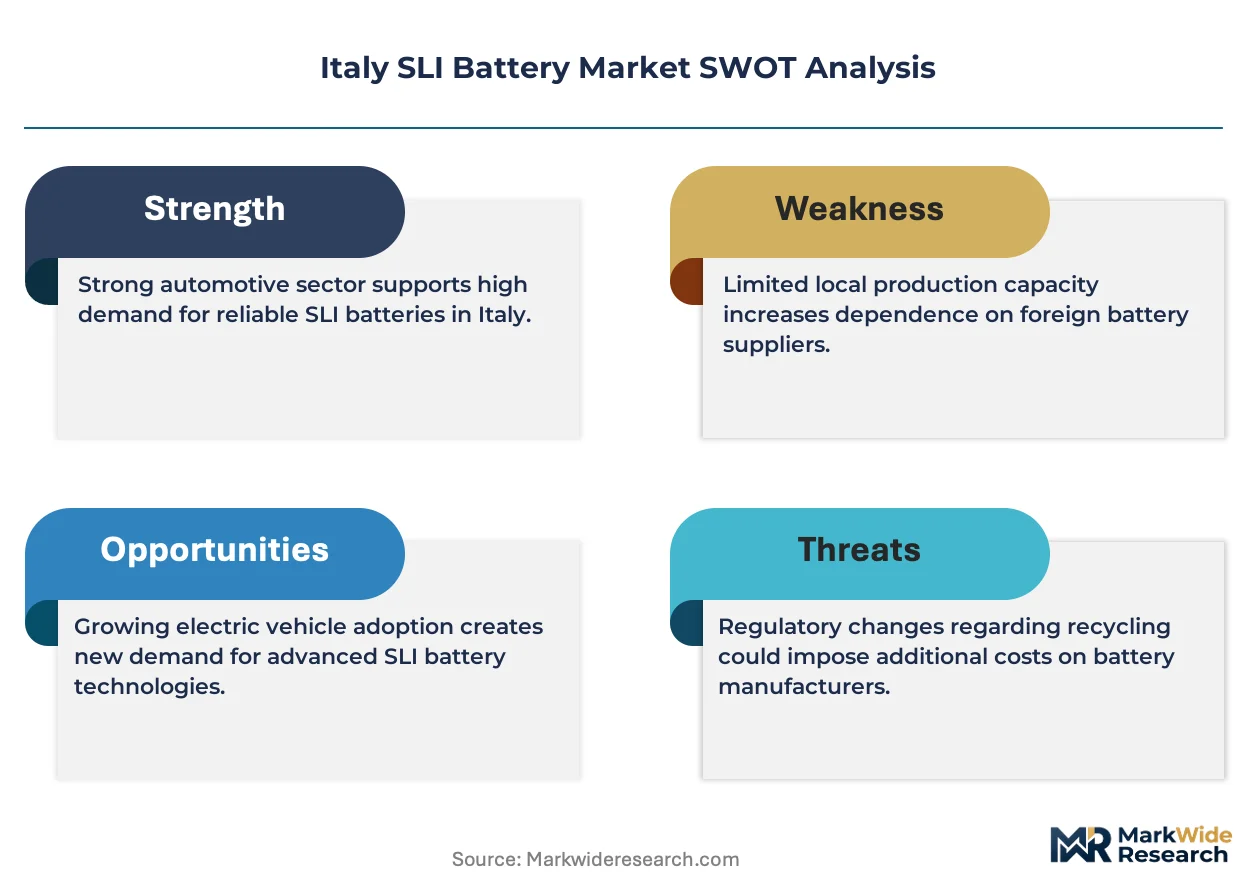
The EU Battery Regulation is decoupling compliance costs from legacy production models across the Italy SLI Battery Market. Midac SpA leverages its domestic manufacturing footprint to anchor supply contracts with Fiat and Iveco service networks. Fiamm Energy Technology S.p.A. sustains R&D intensity in enhanced flooded battery chemistry for start-stop applications. Exide Technologies competes through backward integration into lead recycling, reducing raw material exposure.
An SLI battery is a rechargeable lead-acid or advanced chemistry unit engineered to deliver high cold-cranking amperage for engine starting, sustain vehicle electrical loads during operation, and accept alternator recharge cycles at 12V or 24V nominal voltage. Lead-acid chemistry still dominates installed base economics, though AGM and EFB technologies capture margin pools from start-stop vehicle penetration across Italian OEM channels. Passenger vehicles anchor volume demand, while commercial vehicle fleets drive replacement cycle premiums in the aftermarket installation segment.
Italy's Ministry of Enterprise and Made in Italy coordinates with ECHA and the EU Battery Regulation framework to enforce due diligence, carbon footprint labeling, and recycling efficiency thresholds on domestic producers. BIS and CE marking requirements shape product standards for export-oriented Italian manufacturers serving adjacent European markets. Stakeholders must monitor how delegated acts under the EU Battery Regulation recalibrate recycled lead content mandates and whether domestic recyclers can scale capacity ahead of compliance deadlines.
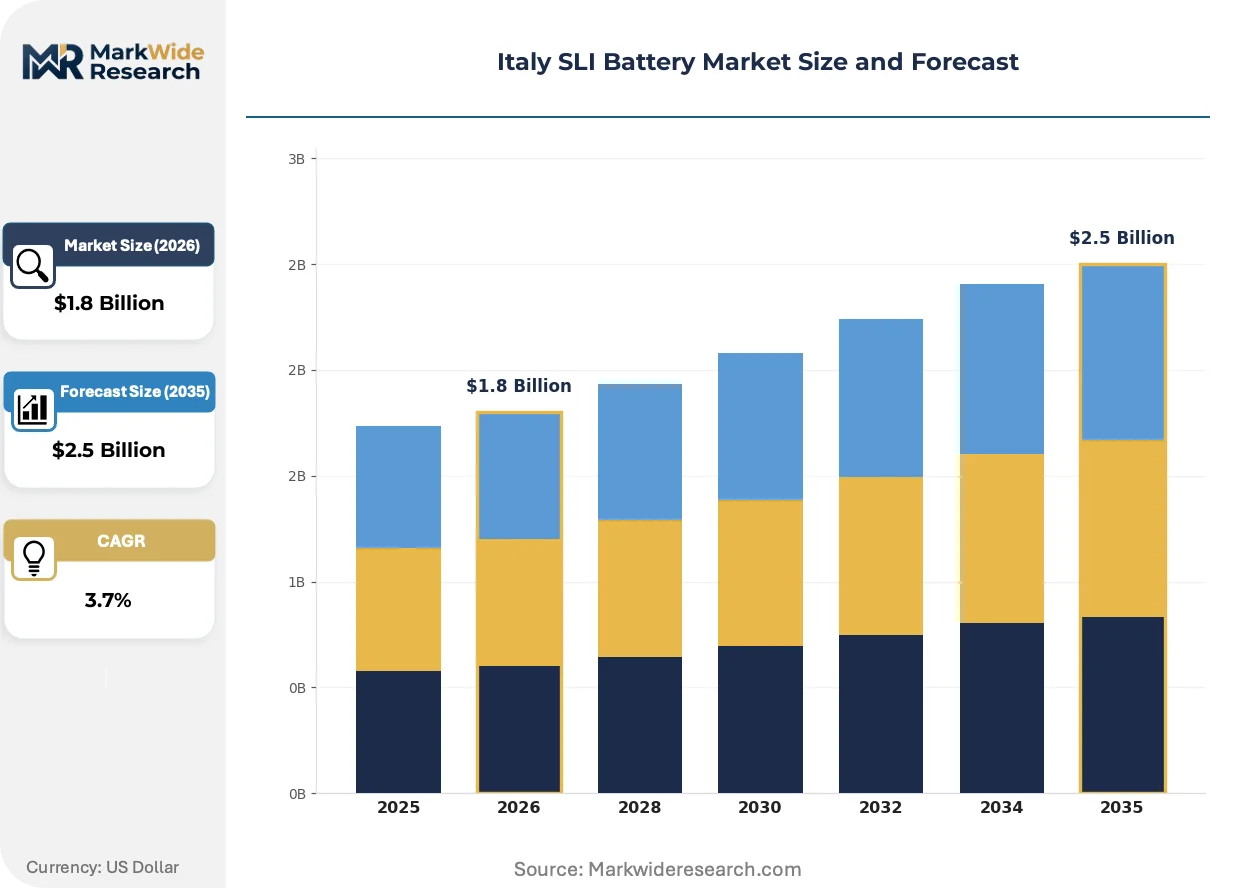
Market Dynamics
The EU Battery Regulation's carbon footprint declarations and recycled content mandates are restructuring production economics across Italian SLI battery manufacturing, forcing domestic producers to reconfigure supply chains and certify material provenance ahead of binding compliance deadlines.
Growth Catalysts
- Start-stop vehicle penetration:Enhanced flooded battery and AGM chemistry demand accelerates as Italian OEMs integrate micro-hybrid systems across passenger vehicle platforms to meet fleet emission targets.
- EU Green Deal industrial policy:Battery recycling infrastructure investments receive public co-financing, expanding domestic lead recovery capacity and reducing raw material import dependency for northern Italian production clusters.
- Commercial vehicle electrification lag:Heavy-duty truck and bus segments retain 12V/24V SLI architectures longer than passenger cars, sustaining replacement cycle premiums in aftermarket channels serving Iveco and DAF service networks.
Market Restraints
- Lead price volatility:London Metal Exchange lead contract fluctuations compress margin predictability for producers lacking captive smelter capacity or long-term concentrate offtake agreements.
- Single-source supply concentration:Premium separator membrane and advanced electrolyte additive production concentrates among German and Belgian specialty chemical suppliers, creating input bottlenecks for Italian battery assemblers.
- Lithium-ion substitution trajectory:48V mild-hybrid and full-electric vehicle architectures displace conventional SLI functions in premium passenger segments, narrowing the addressable market for lead-acid chemistry.
Strategic Opportunities
- Southern Italy aftermarket underpenetration:Sicily and Calabria exhibit lower battery replacement frequency and weaker distributor coverage, creating whitespace for regional logistics investments and service network expansion.
- CE marking export facilitation:Italian manufacturers with certified carbon footprint documentation can leverage domestic compliance to access adjacent Balkan and North African markets where EU regulatory alignment is emerging.
- Battery management system integration:Convergence of SLI units with telematics-enabled state-of-charge monitoring creates value-added service revenue streams for fleet management providers and OEM captive finance arms.
Industry Challenges
- Recycling certification timeline compression:ECHA delegated acts under the EU Battery Regulation mandate third-party audited recycling efficiency declarations, requiring Italian producers to requalify supplier networks within abbreviated compliance windows.
- Electrochemical engineering talent scarcity:Domestic universities produce insufficient graduates specializing in lead-acid and advanced battery chemistry, forcing manufacturers to recruit from German and French technical institutes or invest in internal apprenticeship programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy SLI Battery Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, AGM, Gel, Lithium-Ion End User: Passenger Vehicles, Commercial Vehicles, Motorcycles, Boats Installation Type: OEM, Aftermarket, Replacement, Custom Technology: Start-Stop, Enhanced Flooded, EFB, Conventional |
| Companies Covered | Exide Technologies, Johnson Controls, EnerSys, Sunlight Group, FAAM, Midac SpA, Accumulatori Ariete S.r.l., Fiamm Energy Technology S.p.A., Leoch International Technology Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy SLI Battery Market Trends and Innovations
Digital process control and automated manufacturing systems are penetrating Italian battery plants, while regulatory disclosure requirements and aftermarket channel restructuring simultaneously reshape competitive positioning across the value chain.
Smart formation and testing equipment is automating end-of-line quality verification in Turin and Milan manufacturing facilities. Mid-tier Italian producers are retrofitting legacy assembly lines with machine vision and robotic handling systems to reduce manual inspection labor and improve cold-cranking amperage consistency. This automation is compressing defect rates and enabling just-in-sequence delivery contracts with Fiat Stellantis assembly plants.
ECHA enforcement of the EU Battery Regulation's due diligence and carbon footprint labeling provisions intensifies documentation burdens on Italian exporters. Domestic manufacturers must now trace lead concentrate origin through smelter certificates and quantify Scope 3 emissions across supplier tiers. Northern Italian industrial clusters are responding by consolidating procurement through vertically integrated European lead recyclers with audited chain-of-custody protocols.
Fleet operators are unbundling battery replacement from full-service maintenance contracts, shifting toward direct procurement from authorized distributors with transparent core exchange pricing. This disintermediation pressures traditional garage channels that historically captured margin on both labor and parts. The pattern is most pronounced in Lombardy and Veneto, where large logistics fleets operate centralized procurement functions and negotiate volume rebates independent of service networks.
Italy SLI Battery Market Segmentation
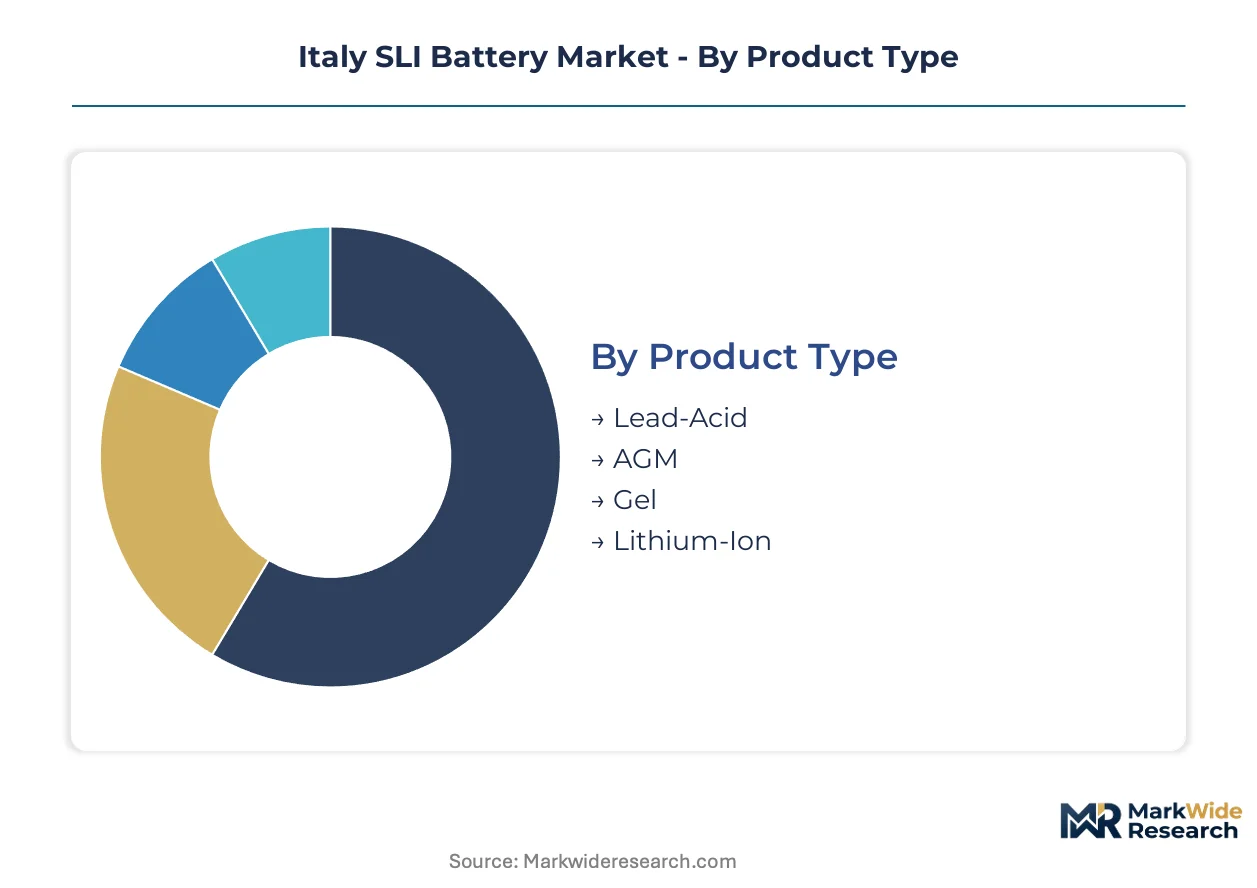
SLI battery procurement patterns in Italy diverge sharply across chemistry types and installation channels. Turin and Milan production clusters source differently than southern aftermarket distributors. Segment boundaries are hardening as EU Battery Regulation compliance costs reshape supplier economics.
Product Type:
Lead-acid chemistry commands concentrated smelter capacity across northern Italian industrial zones, with captive recycling infrastructure anchoring cost structures for domestic assemblers.
- Lead-Acid:Flooded-cell construction with lead dioxide positive plates and sponge lead negative electrodes delivers cold-cranking amperage for conventional 12V architectures. Fiat Stellantis and Iveco production lines in Turin and Brescia absorb volume from domestic formators. ECHA carbon footprint declarations now mandate smelter origin documentation, compressing margins for producers lacking backward integration.
- AGM:Absorbent glass mat separators immobilize electrolyte, enabling deep-cycle tolerance and vibration resistance for start-stop applications. Premium passenger platforms from Alfa Romeo and Maserati specify AGM for micro-hybrid systems. Lombardy fleet operators pay replacement premiums for AGM durability in urban delivery cycles.
- Gel:Silica-thickened electrolyte eliminates stratification, suited for marine and recreational vehicle standby power where tilt tolerance matters. Italian yacht builders in Viareggio and La Spezia specify gel for auxiliary battery banks.
- Lithium-Ion:Lithium iron phosphate chemistry delivers energy density for 48V mild-hybrid architectures displacing SLI functions in premium segments. Limited Italian assembly capacity concentrates import dependency on German and Chinese cell suppliers.
Today's leader: Lead-Acid. Tomorrow's challenger: AGM.
End User:
Vehicle electrification timelines split end-user demand trajectories, with commercial fleets retaining 12V/24V architectures longer than passenger segments.
- Passenger Vehicles:OEM demand concentrates at Fiat Stellantis Mirafiori and Cassino plants for ICE and mild-hybrid platforms. Start-stop penetration drives EFB and AGM specification in B-segment and above. Aftermarket replacement cycles compress in urban Lombardy and Veneto corridors.
- Commercial Vehicles:Iveco production at Suzzara and Brescia anchors 24V SLI demand for heavy-duty trucks and buses. Fleet operators in Emilia-Romagna negotiate direct procurement contracts, bypassing traditional garage channels. Extended replacement intervals sustain margin pools despite lower unit volumes.
- Motorcycles:Compact lead-acid and lithium-ion units serve Piaggio and Ducati production in Tuscany and Emilia-Romagna. Premium displacement segments shift toward lithium weight reduction.
- Boats:Dual-battery configurations for cranking and house loads dominate Adriatic and Tyrrhenian marina service networks. Gel and AGM chemistries capture margin from vibration and tilt requirements.
Commercial vehicles sustain replacement premiums; passenger platforms face chemistry displacement fastest.
Installation Type:
OEM and aftermarket channels operate on divergent margin structures, with just-in-sequence delivery compressing working capital for plant-direct suppliers.
- OEM:Direct supply contracts to Fiat Stellantis and Iveco assembly plants require certified carbon footprint documentation and recycled content verification under EU Battery Regulation delegated acts. Northern Italian formators invest in automated testing equipment to meet cold-cranking amperage consistency thresholds.
- Aftermarket:Authorized distributor networks serve independent garages across Italy's 20 regions, with core exchange pricing transparency eroding traditional labor-plus-parts margin capture. Sicily and Calabria exhibit distributor coverage gaps.
- Replacement:Fleet-managed direct procurement concentrates in Lombardy logistics corridors, unbundling battery supply from full-service maintenance contracts. Volume rebate structures favor national distributors over regional players.
- Custom:Specialty vehicle and industrial equipment applications require form factor and terminal modifications, served by niche assemblers in Veneto and Piedmont with flexible production lines.
Fleet direct procurement is gaining share fastest in northern industrial clusters.
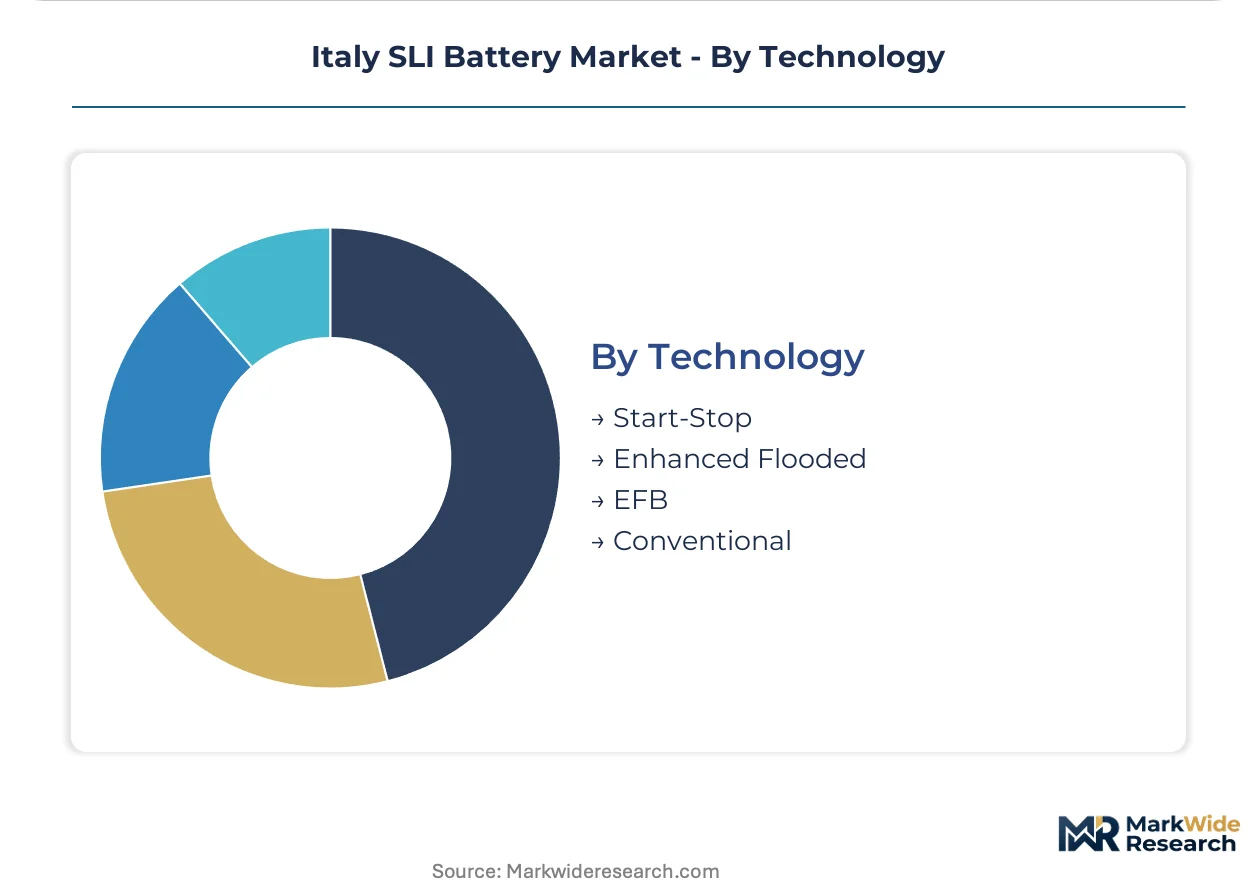
Technology:
Start-stop system penetration splits technology demand, with enhanced flooded batteries capturing mid-market volume and AGM defending premium positioning.
- Start-Stop:Micro-hybrid systems require deep-cycle tolerance and rapid recharge acceptance, driving EFB and AGM specification across Fiat Stellantis and Volkswagen Group platforms assembled in Italy. BIS and CE marking requirements shape export qualification protocols.
- Enhanced Flooded:Modified plate chemistry and separator design improve cycle life for entry-level start-stop applications. Midac SpA and Fiamm Energy Technology sustain R&D intensity in this segment for cost-sensitive B- and C-segment vehicles.
- EFB:Advanced flooded construction with carbon additives reduces sulfation in partial state-of-charge operation. Italian OEM channels specify EFB for price-competitive micro-hybrid variants.
- Conventional:Standard flooded lead-acid retains installed base economics in non-start-stop vehicles and commercial truck auxiliary applications. Replacement demand concentrates in aging vehicle parc across southern regions.
Enhanced Flooded commands volume today; Start-Stop integration requirements reshape tomorrow's specification mix.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrochemical engineering talent concentrates in northern Italian industrial clusters, with Turin and Milan universities supplying specialized workforce pools to battery formators serving Fiat Stellantis and Iveco production networks.
Piedmont
Turin anchors OEM supply contracts to Fiat Stellantis Mirafiori assembly operations, with Midac SpA and Fiamm Energy Technology maintaining production facilities in the metropolitan corridor. ECHA enforcement of carbon footprint documentation under the EU Battery Regulation pressures local formators to consolidate lead procurement through certified European recyclers. The industrial zone sustains just-in-sequence delivery contracts requiring automated cold-cranking amperage testing equipment.
Lombardy
Milan and Brescia concentrate commercial vehicle battery demand from Iveco Suzzara operations and logistics fleet procurement functions. Fleet operators in the Po Valley corridor negotiate direct distributor contracts, bypassing traditional garage channels for 24V SLI replacement cycles. The region exhibits the highest aftermarket price transparency on core exchange pricing, compressing margins for regional service networks.
Veneto
Specialty battery assemblers in the Veneto industrial belt serve custom form factor requirements for industrial equipment and marine applications. CE marking documentation from domestic producers facilitates export qualification to Balkan markets where regulatory alignment with EU Battery Regulation standards is emerging. The cluster maintains flexible production lines for low-volume terminal modifications.
Emilia-Romagna
Ducati and Piaggio motorcycle production in Bologna and Pontedera drives compact battery specification for premium displacement segments shifting toward lithium weight reduction. The region's engineering heritage supports R&D intensity in advanced flooded battery chemistry for start-stop applications. Local distributors face margin pressure from fleet-managed direct procurement concentrated in adjacent Lombardy corridors.
Sicily
Palermo and Catania exhibit underpenetrated aftermarket distributor coverage relative to northern industrial clusters, with lower battery replacement frequency in aging vehicle parc. The regional logistics infrastructure creates whitespace for service network expansion targeting southern replacement demand. Domestic producers with certified carbon footprint documentation can leverage compliance investments to access North African export markets from Sicilian port facilities.
Italy SLI Battery Market Competitive Landscape
The competitive structure tilts toward vertically integrated domestic specialists with captive recycling infrastructure and multinational battery systems providers with pan-European distribution networks. Italian producers cluster in northern industrial zones around Turin and Milan, while foreign-headquartered competitors access the market through import channels and authorized distributor relationships. Two strategic archetypes dominate: domestic formators with backward integration into lead recovery, and multinational industrial battery specialists with diversified chemistry portfolios. Consolidation pressure intensifies through ECHA-mandated recycling certification requirements, while capacity investments concentrate in automated formation and testing equipment.
Among Italy-based producers, Midac SpA, Fiamm Energy Technology S.p.A., and Accumulatori Ariete S.r.l. occupy positions within the domestic specialist tier, representing vertically integrated manufacturing footprints anchored in northern industrial clusters. Exide Technologies and Johnson Controls exemplify multinational systems providers with diversified energy storage portfolios spanning automotive and industrial applications. EnerSys and Sunlight Group represent industrial battery specialists with European distribution networks serving commercial vehicle aftermarket channels. The competitive dynamic pits domestic compliance-advantaged producers against scale-driven international competitors with broader chemistry diversification.
| Leading Market Players |
|---|
| Exide Technologies |
| Johnson Controls |
| EnerSys |
| Sunlight Group |
| FAAM |
| Midac SpA |
| Accumulatori Ariete S.r.l. |
| Fiamm Energy Technology S.p.A. |
| Leoch International Technology Limited |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between ECHA-compliant carbon footprint documentation and legacy unverified supply separates premium AGM and EFB pricing from commodity flooded-cell tiers, with northern Italian OEM channels commanding documentation premiums while southern aftermarket distributors absorb cost compression from unbundled service models.
Pricing Analysis
Bundled garage service contracts are unbundling into direct battery procurement with transparent core exchange pricing, particularly across Lombardy fleet operators negotiating volume rebates independent of labor charges. Three-tier pricing structure across premium AGM, standard EFB, and economy flooded-cell levels reflects carbon footprint certification status and recycled content verification under EU Battery Regulation delegated acts. Pricing pressure stems from fleet procurement centralization compressing distributor margins in northern industrial corridors. Commercial vehicle operators exhibit lowest price sensitivity due to extended replacement intervals and downtime cost avoidance, while independent southern garage channels face acute sensitivity to core exchange transparency.
Supply Chain Analysis
Dual-sourcing mandates from Fiat Stellantis and Iveco procurement functions require Italian formators to qualify multiple lead concentrate suppliers across Germany, Belgium, and domestic recycling clusters. Raw material dependencies center on lead bullion from European smelters, separator membranes from German specialty chemical producers, and electrolyte additives concentrated among Belgian suppliers. Single-source vulnerability in premium separator production creates input bottlenecks for AGM and EFB assembly. Distribution runs through authorized distributor networks serving OEM assembly plants via just-in-sequence contracts and aftermarket channels covering Italy's 20 regions with core exchange logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as start-stop vehicle penetration shifts demand toward EFB and AGM specifications with superior margin profiles and regulatory compliance premiums.
For Market Incumbents: Deploy carbon footprint certification investments as a defensive moat against unverified imports from Balkan and North African channels. Consolidate procurement through vertically integrated European lead recyclers with audited chain-of-custody protocols ahead of ECHA delegated act deadlines. Reinforce automation in Turin and Milan formation facilities to defend cold-cranking amperage consistency thresholds for Fiat Stellantis just-in-sequence contracts. For New Entrants and Emerging Players: Fleet procurement functions in Lombardy and Emilia-Romagna represent the most penetrable channel for direct distributor relationships unbundled from traditional garage service networks. Southern Italy aftermarket underpenetration in Sicily and Calabria offers whitespace for regional logistics investments targeting aging vehicle parc replacement cycles. A CE marking export facilitation strategy leveraging domestic compliance documentation unlocks adjacent Balkan markets where EU regulatory alignment is emerging. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic formators possessing captive lead recycling infrastructure and ECHA-certified carbon footprint documentation. Long-term viability over a multi-year horizon favors vertically integrated specialists over pure assembly operations exposed to concentrate price volatility and regulatory compliance cost compression. Watch recycling efficiency threshold tightening under EU Battery Regulation delegated acts as the inflection indicator for supplier consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Recycling | Captive smelter capacity insulates Midac and Fiamm from LME price volatility and ECHA origin documentation mandates. |
| Automated Formation Equipment Deployment | Machine vision and robotic handling at Turin facilities compress defect rates for Fiat Stellantis just-in-sequence delivery contracts. |
| Southern Aftermarket Network Expansion | Sicily and Calabria distributor coverage gaps create first-mover advantage in replacement cycle capture for aging vehicle parc. |
| CE Marking Export Qualification | Domestic carbon footprint documentation enables Balkan and North African market access where EU regulatory alignment emerges. |
| Battery Management System Integration | Telematics-enabled state-of-charge monitoring creates recurring revenue streams for fleet management providers and OEM finance arms. |
Research Methodology
Bottom-up vehicle platform modeling reconciled against top-down lead concentrate import tracking forms the analytical core of this study. Primary interviews with Fiat Stellantis procurement officers, Iveco platform engineers, aftermarket distributor operations heads, and ECHA regulatory affairs specialists combined with secondary validation from EU trade statistics, Italian Ministry of Enterprise circular economy reports, and battery industry association filings. Triangulation across supply-side capacity assessments and demand-side vehicle production databases ensures segment-level accuracy.
Historical trendline analysis of SLI battery content per vehicle across passenger and commercial platforms established baseline penetration rates for start-stop technologies. Segmentation modeling spans chemistry type, end-use vehicle class, installation channel, and regional production cluster dimensions. CAGRs were derived from regression analysis against fleet emission target compliance timelines and replacement cycle dynamics. Forecast inputs incorporate EU Battery Regulation delegated act implementation schedules and recycling capacity buildout across northern Italian industrial zones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion substitution trajectories in 48V mild-hybrid architectures and ECHA recycling efficiency threshold calibration. Projections reflect assumptions regarding lead price stability, OEM platform electrification roadmaps, and southern aftermarket distributor network development. Deviation in EU Battery Regulation enforcement intensity or accelerated lithium-ion cost parity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
South America Rechargeable Battery Market
Batteries
Iron Salt Battery Market
Batteries
India Micro Batteries Market
Batteries
Military Battery Packs Market
Batteries
Europe Battery Cell Market
Batteries
AAA Battery Market
Batteries
East Europe Battery Market
Batteries
Japan Rechargeable Battery Market
Batteries
North America Consumer Battery Market
Batteries
FORTELION Battery Module Market
Batteries
Low Temperature Battery Market
Batteries
Forklift Battery Rental Market
Batteries
Indonesia Battery Market
Batteries
Automotive AGM Battery Market
Batteries
Battery Cell Market
Batteries
Proton Battery Market