
 GCC Rechargeable Battery Market | 2026-2036
GCC Rechargeable Battery Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Rechargeable Battery Market Intelligence
Utility-scale energy storage procurement is reorganizing demand patterns across Gulf utilities, pulling volume away from traditional automotive-first battery suppliers. Tesla leverages its integrated energy storage architecture to anchor large-scale solar-plus-storage deployments in Saudi Arabia. BYD Company Limited sustains manufacturing scale advantages through its blade-cell platform, while LG Chem competes on cathode material specialization for regional EV assembly lines.
GCC rechargeable batteries are electrochemical energy storage devices designed for multiple charge-discharge cycles, typically employing lithium-ion chemistries with nickel-manganese-cobalt or lithium-iron-phosphate cathodes and graphite or silicon-composite anodes to deliver energy densities between 150-300 Wh/kg for industrial and mobility applications. Lithium-ion dominates installed capacity due to superior cycle life and thermal stability under Gulf climate conditions. Automotive applications generate the deepest margin pools as OEM localization requirements intensify, while renewable energy storage represents the fastest-expanding segment driven by utility-scale solar integration mandates across the six member states.
Saudi Arabia's SFDA and UAE's MOHAP enforce product safety standards for battery imports, while Saudi Standards, Metrology and Quality Organization (SASO) technical regulations mandate UN 38.3 transportation testing and IEC 62619 industrial safety compliance for grid-connected installations. These frameworks elevate entry barriers for uncertified suppliers and redirect procurement toward established tier-one manufacturers. Stakeholders must monitor evolving local content requirements and carbon-border adjustment mechanisms that could reshape supplier qualification criteria.
Market Dynamics
Utility-scale energy storage procurement is reorganizing demand patterns across Gulf utilities, pulling procurement volume away from traditional automotive-first battery suppliers toward integrated energy storage architects capable of solar-plus-storage turnkey delivery.
Growth Catalysts
- SASO Technical Regulations:Saudi Standards, Metrology and Quality Organization mandates for UN 38.3 transportation testing and IEC 62619 industrial safety compliance elevate entry barriers for uncertified suppliers and redirect procurement toward established tier-one manufacturers with certification infrastructure.
- NEOM Industrial Corridor:Saudi Arabia's giga-project demands concentrated battery procurement for renewable microgrids and electric mobility infrastructure, creating anchor demand volumes that reshape regional supplier qualification criteria.
- Lithium-Iron-Phosphate Chemistry:Superior thermal stability under Gulf climate conditions with ambient temperatures exceeding 50°C enables longer cycle life in outdoor installations, accelerating displacement of nickel-manganese-cobalt formulations in stationary storage applications.
Market Restraints
- Cathode Active Material Concentration:Supply of refined lithium, nickel, and cobalt concentrates in Chinese and Indonesian processing facilities creates geographic single-point-of-failure risk for GCC assemblers dependent on seaborne chemical precursor imports.
- Cell Formation Energy Intensity:The electrochemical conditioning process for lithium-ion cells requires sustained grid electricity input at 0.3-0.5 kWh per Ah of finished capacity, elevating manufacturing costs in markets with high industrial electricity tariffs.
- Solid-State Substitution Timeline:Next-generation solid-state electrolyte architectures promise energy density improvements exceeding 400 Wh/kg, threatening to strand capital invested in incumbent liquid-electrolyte production lines before depreciation cycles complete.
Strategic Opportunities
- Kuwait Renewable Energy Targets:The emirate's 15% renewable electricity mandate by 2030 remains underpenetrated for utility-scale battery pairing, offering first-mover positioning for integrated solar-storage developers before competitive auction saturation.
- Second-Life Automotive Packs:Retired electric vehicle batteries retaining 70-80% state-of-health are converging with stationary storage demand, enabling circular economy business models that bypass virgin cell cost structures for frequency regulation applications.
- Jebel Ali Free Zone Logistics:Dubai's bonded warehousing and re-export infrastructure supports duty-efficient distribution into African and South Asian markets, transforming the UAE into a regional trading hub beyond domestic absorption capacity.
Industry Challenges
- Battery Management System Firmware Integration:Cell-level monitoring electronics must interface with diverse inverter and energy management platforms across Saudi, Emirati, and Omani grid codes, requiring multi-protocol software engineering capabilities scarce in regional talent pools.
- Thermal Runaway Containment Certification:SASO and MOHAP safety protocols mandate propagation testing and fire suppression validation that extends product qualification timelines by 8-14 months, compressing effective revenue windows for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Rechargeable Battery Market |
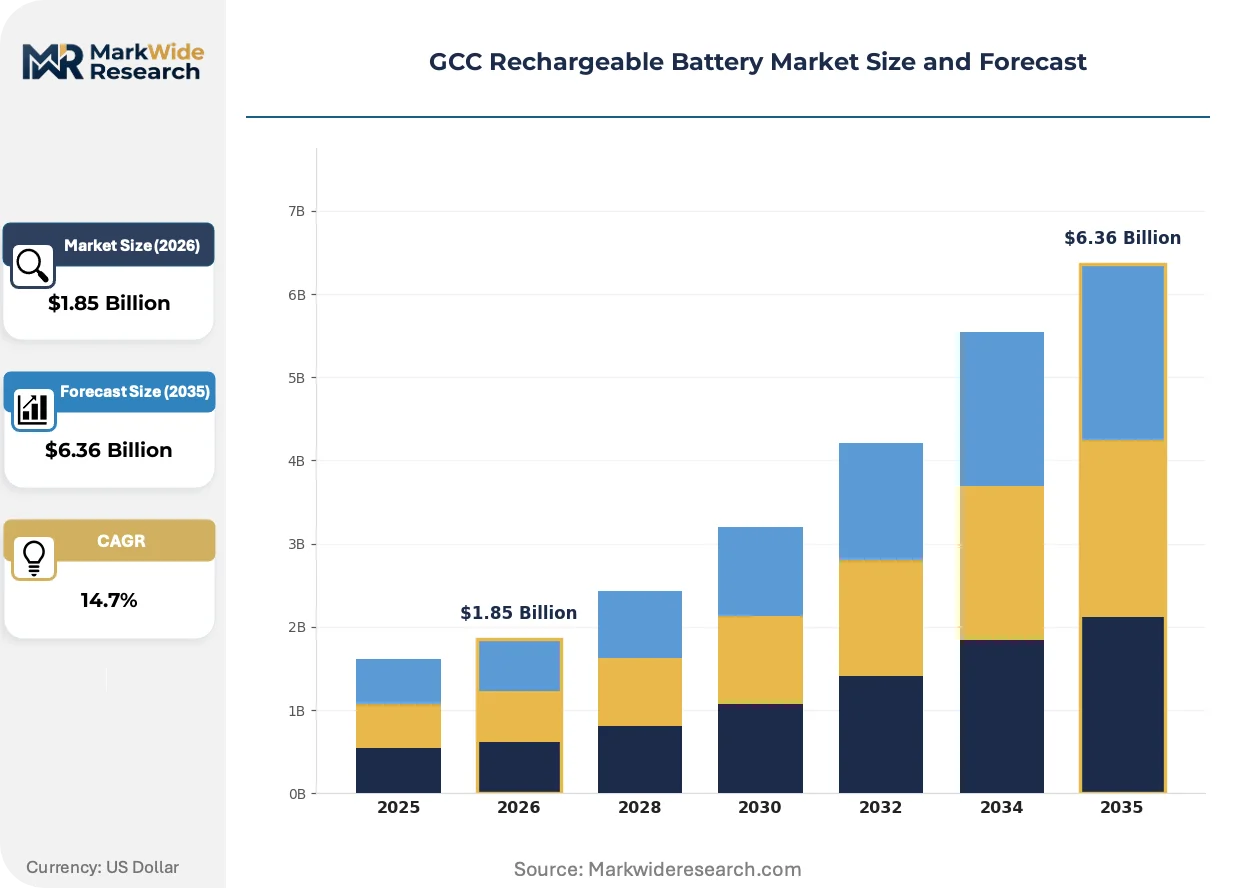
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.36 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel Cadmium, Nickel Metal Hydride, Lead Acid Application: Consumer Electronics, Automotive, Renewable Energy, Industrial Equipment End User: Manufacturers, Distributors, Retailers, Energy Providers Capacity: Below 1000 mAh, 1000-3000 mAh, 3000-5000 mAh, Above 5000 mAh |
| Companies Covered | Tesla, Exide Technologies, LG Chem, East Penn Manufacturing, Johnson Controls, Samsung SDI, BYD Company Limited, Shenzhen Honcell Energy Co. Ltd., Panasonic, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Rechargeable Battery Market Strategic Shifts & Innovations
Cell chemistry evolution, regulatory safety harmonization, and procurement model transformation are converging to restructure competitive positioning across GCC rechargeable battery value chains.
Lithium-iron-phosphate cathode formulations are displacing nickel-manganese-cobalt alternatives in Gulf utility-scale installations. Saudi Electric Company and Emirates Water and Electricity Company procurement teams specify LFP for 4-hour duration solar-plus-storage projects due to superior cycle stability under ambient temperatures exceeding 45°C. This chemistry transition is compressing margin premiums previously captured by high-nickel cathode suppliers and redirecting cathode active material procurement toward Chinese LFP precursor producers.
MOHAP battery safety mandates in the UAE are tightening parallel to Saudi SFDA import inspection protocols, creating regulatory convergence across the two largest GCC markets. Industrial consequence includes mandatory UN 38.3 test report authentication and factory audit requirements that disqualify trading-house intermediaries lacking direct manufacturing relationships. Grid-connected storage segments face the steepest compliance burden, with project developers now embedding 6-9 month certification lead times into construction schedules.
Direct procurement from cell manufacturers is displacing distributor-mediated purchasing for volumes exceeding 100 MWh annual offtake. Saudi industrial developers at NEOM and Riyadh logistics corridors negotiate frame contracts with CATL and BYD supply subsidiaries, bypassing regional trading houses that historically captured 12-18% margin layers. This channel compression is most visible in Saudi Arabia's renewable energy project pipeline, where engineering-procurement-construction contractors now source cells directly to meet local content scoring requirements.
GCC Rechargeable Battery Market Segmentation
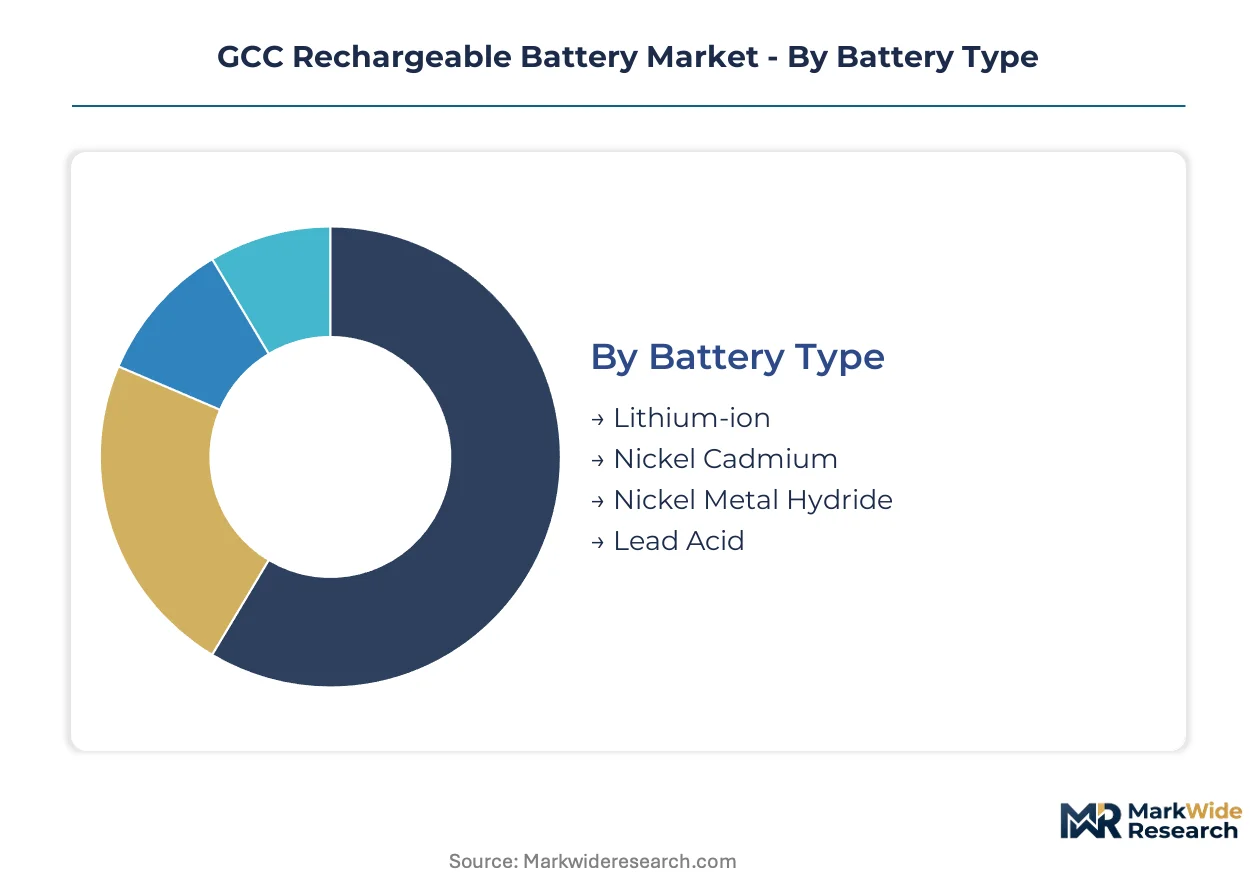
Segmentation in the GCC rechargeable battery market reveals how chemistry selection, application requirements, and procurement channels intersect with Saudi and Emirati regulatory frameworks. Understanding these divisions exposes where incumbent technologies face displacement pressure and where new capacity investments concentrate.
Battery Type:
Solid-state and sodium-ion architectures threaten to displace established chemistries before depreciation cycles complete, with substitution pressure varying sharply by thermal stability requirements and cycle life specifications.
- Lithium-ion:Dominant chemistry employing nickel-manganese-cobalt or lithium-iron-phosphate cathodes with graphite anodes, delivering 150-300 Wh/kg energy density. NEOM and Riyadh industrial corridors specify LFP variants for solar-plus-storage installations exceeding 45°C ambient operating conditions.
- Lead Acid:Mature flooded and valve-regulated designs using lead dioxide cathodes and sponge lead anodes in sulfuric acid electrolyte. Backup power for Saudi telecommunications infrastructure and UAE data centers sustains residual demand despite weight and cycle life limitations.
- Nickel Cadmium:Sintered plate construction with potassium hydroxide electrolyte tolerates deep discharge cycles. Aviation ground support equipment and oilfield drilling applications in Oman and Kuwait retain niche procurement volumes.
- Nickel Metal Hydride:Rare-earth alloy anodes paired with nickel oxyhydroxide cathodes deliver moderate energy density without cadmium toxicity. Hybrid electric vehicle battery packs for regional automotive assembly lines represent the primary offtake channel.
Lithium-ion anchors the volume base while lithium-iron-phosphate formulations within this category gain share at the steepest rate.
Application:
Margin structures diverge sharply between price-sensitive consumer electronics and capital-intensive utility procurement, with certification requirements creating tiered entry barriers.
- Renewable Energy:Grid-scale battery energy storage systems paired with solar photovoltaic installations require 4-hour duration capability and IEC 62619 safety compliance. Saudi Electric Company and Emirates Water and Electricity Company procurement specifications favor this segment for gigawatt-hour project pipelines.
- Automotive:Traction batteries for electric vehicles and hybrid platforms face OEM localization mandates and SASO technical regulation compliance. NEOM mobility infrastructure and Dubai's electric bus fleet conversion generate concentrated demand volumes.
- Consumer Electronics:Cylindrical and pouch cells for smartphones, laptops, and portable power banks compete on cost and form factor flexibility. Jebel Ali Free Zone re-export channels distribute into African and South Asian markets beyond domestic absorption.
- Industrial Equipment:Forklift motive power, uninterruptible power supplies, and material handling systems require robust cycle life under heavy-duty discharge profiles. Saudi logistics corridors and UAE port automation projects specify this segment.
Automotive applications command the deepest margin pools while renewable energy storage is expanding most quickly.
End User:
Procurement sophistication varies from direct manufacturer relationships to distributor-mediated purchasing, with channel structure determining qualification timelines and local content scoring.
- Energy Providers:Saudi Electric Company, Emirates Water and Electricity Company, and regional independent power producers negotiate frame contracts exceeding 100 MWh annual offtake. Direct cell manufacturer relationships bypass historical trading house margins.
- Manufacturers:Automotive OEMs, electronics assemblers, and industrial equipment builders integrate cells into finished products. SASO factory audit requirements and UN 38.3 test report authentication mandate direct manufacturing relationships.
- Distributors:Regional trading houses serving sub-100 MWh accounts face margin compression as procurement concentrates. Bonded warehousing in Jebel Ali Free Zone supports duty-efficient re-export positioning.
- Retailers:Consumer-facing channels for replacement batteries and portable power products. Price competition and brand recognition dominate purchasing criteria with minimal technical specification involvement.
Energy providers anchor the volume base while manufacturers are climbing the fastest as localization requirements intensify.
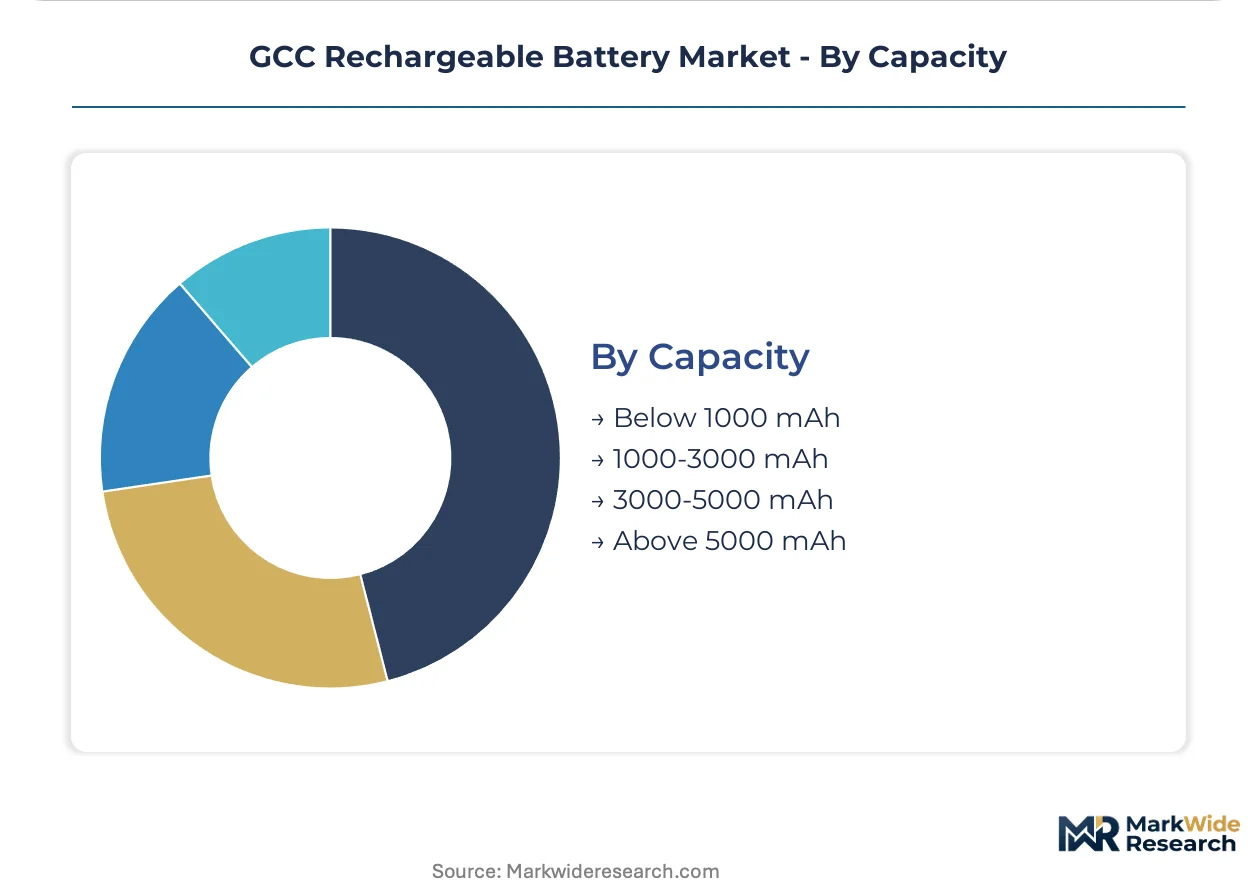
Capacity:
Scale economies and thermal management complexity create distinct competitive dynamics across capacity tiers, with larger formats demanding specialized integration capabilities.
- Above 5000 mAh:Prismatic and large-format pouch cells for electric vehicle traction and utility-scale storage. NEOM renewable microgrids and Saudi electric bus deployments specify this tier for energy density and pack-level optimization.
- 3000-5000 mAh:High-capacity cylindrical and pouch formats for premium consumer electronics and light electric vehicles. UAE electric scooter sharing operators and portable power station manufacturers concentrate procurement.
- 1000-3000 mAh:Standard cylindrical 18650 and 21700 cells for mainstream consumer electronics and power tools. Volume manufacturing scale in Chinese cell plants supports cost-competitive positioning.
- Below 1000 mAh:Small cylindrical and coin cells for wearables, hearing aids, and IoT sensors. Medical device requirements under SFDA and MOHAP protocols elevate quality certification barriers.
Above 5000 mAh formats anchor the volume base while 3000-5000 mAh applications are gaining share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's bonded warehousing and re-export infrastructure transforms Dubai into the GCC's battery distribution gateway, channeling cells into Saudi industrial corridors and onward to African and South Asian markets.
Saudi Arabia
NEOM's renewable microgrids and Riyadh's electric bus fleet conversion generate concentrated procurement volumes exceeding 100 MWh annually. SASO mandates UN 38.3 transportation testing and IEC 62619 industrial safety compliance for grid-connected installations. The Eastern Province's Jubail industrial cluster hosts assembly operations serving petrochemical sector backup power requirements.
United Arab Emirates
Dubai's solar-plus-storage procurement and Abu Dhabi's data center UPS modernization drive utility-scale and industrial demand. MOHAP enforces battery safety standards parallel to Saudi SFDA protocols, requiring factory audit authentication for import clearance. Jebel Ali Free Zone's duty-efficient logistics infrastructure supports regional distribution hub positioning.
Kuwait
The emirate's 15% renewable electricity mandate by 2030 remains underpenetrated for utility-scale battery pairing, offering first-mover positioning. The country's national energy regulator oversees grid interconnection standards for storage assets. Al-Zour's refinery complex and Shagaya renewable energy park concentrate industrial demand in the southern region.
Oman
Oilfield drilling applications and aviation ground support equipment sustain niche demand for nickel-cadmium and specialized chemistries. The sultanate's national standards body aligns technical regulations with GCC harmonization frameworks. Sohar Port and Freezone's industrial cluster attracts battery assembly investments serving regional mining and logistics sectors.
Qatar
World Cup legacy infrastructure and data center expansion sustain demand for uninterruptible power supply systems. The country's national quality infrastructure mandates product conformity assessment for electrical equipment imports. Ras Laffan's industrial city concentrates procurement for petrochemical and liquefied natural gas facility backup power.
GCC Rechargeable Battery Market Key Industry Players
Concentration sits with integrated energy storage architects and established cell manufacturers possessing certification infrastructure for SASO and MOHAP compliance. The vendor base stratifies across three tiers: multinational chemistry specialists with Gulf frame contracts, Chinese scale manufacturers leveraging blade-cell and prismatic platforms, and regional trading houses facing margin compression from direct procurement trends. Dominant competitive moves include backward integration into cathode active material supply and strategic partnerships with EPC contractors for solar-plus-storage turnkey delivery.
Within the integrated energy storage tier, Tesla and BYD Company Limited exemplify architectures capable of solar-plus-storage turnkey deployment, while LG Chem occupies a position representing cathode material specialization for regional EV assembly lines. These three anchors reflect the competitive vectors reshaping procurement relationships across Saudi and Emirati utility-scale project pipelines.
| Leading Market Players |
|---|
| Tesla |
| Exide Technologies |
| LG Chem |
| East Penn Manufacturing |
| Johnson Controls |
| Samsung SDI |
| BYD Company Limited |
| Shenzhen Honcell Energy Co. Ltd. |
| Panasonic |
| Others |
Cost & Logistics Intelligence
SASO and MOHAP certification regimes gate both supplier qualification and price differentiation in GCC rechargeable battery procurement, compressing margins for uncertified trading houses while enabling tier-one manufacturers to capture premium positioning through compliance infrastructure.
Pricing Analysis
Volume-discount tiering structures dominate procurement above 100 MWh annual offtake, with direct manufacturer relationships bypassing historical distributor margins of 12-18%. Price differentiation rests on IEC 62619 safety certification grade and local content scoring rather than brand premium alone. Cost compression in the sub-100 MWh tier is intensifying as regional trading houses compete for residual volume. Energy providers exhibit lowest price sensitivity due to long-term offtake security requirements, while consumer electronics retailers face acute margin pressure from commoditized cylindrical cell imports.
Supply Chain Analysis
Container availability constraints on Asia-Gulf trade lanes elevate inbound logistics costs for cathode active material precursors sourced from Chinese and Indonesian processing facilities. Cell manufacturing concentrates in China, South Korea, and Japan, with GCC assembly operations drawing from seaborne chemical precursor imports. Raw material dependencies span refined lithium carbonate, nickel sulfate, and cobalt hydroxide. Single-source vulnerability in cathode material processing creates geographic concentration risk. Distribution runs through Jebel Ali Free Zone bonded warehousing for duty-efficient re-export into African and South Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Saudi and Emirati utility-scale developers negotiating direct frame contracts, fragmenting historical distributor influence and reshaping supplier qualification economics.
For Market Incumbents: Shield certification infrastructure advantages by accelerating backward integration into cathode active material supply chains. Solid-state electrolyte substitution timelines threaten to strand liquid-electrolyte production investments. Priority levers include captive precursor supply agreements with Chinese LFP producers and SASO audit-ready manufacturing footprints in Jubail or Sohar free zones. For New Entrants and Emerging Players: Differentiate on second-life automotive pack refurbishment for frequency regulation applications in Kuwait's underpenetrated renewable storage pipeline. The 15% renewable mandate by 2030 offers first-mover positioning before competitive auction saturation. Target engineering-procurement-construction contractor partnerships for solar-plus-storage turnkey credibility. For Investors and Strategic Acquirers: SASO and MOHAP regulatory convergence reshapes the acquisition landscape toward certified tier-one manufacturers with existing factory audit relationships. Long-term viability favors integrated energy storage architects over pure cell traders. Acquisition target archetype: regional assemblers with IEC 62619 validation and NEOM project references. Signal to watch: carbon-border adjustment mechanism announcements affecting precursor import economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Captive LFP precursor supply from Chinese producers secures margin control for NEOM-scale deployments. |
| IEC 62619 Certification Investment | SASO-mandated industrial safety compliance compresses qualification timelines for grid-connected storage projects. |
| Second-Life Pack Refurbishment | Retired EV batteries bypass virgin cell costs for Kuwait frequency regulation applications. |
| Jebel Ali Distribution Hub Expansion | Bonded warehousing enables duty-efficient re-export positioning into African and South Asian markets. |
| Solar-Plus-Storage EPC Partnership | Turnkey delivery capability meets Saudi Electric Company procurement specifications for gigawatt-hour pipelines. |
Research Approach
The analysis maps lithium-ion chemistry transitions, utility-scale storage procurement patterns, and regulatory convergence trajectories, each validated through utility planning officers, EPC contractors, and cathode material procurement leads at regional cell assemblers. Primary fieldwork combined structured interviews with secondary validation against SASO technical regulations, MOHAP safety protocols, and customs trade data for precursor imports. Bottom-up project pipeline aggregation triangulates against top-down utility procurement forecasts across the analysis window.
Consistency checks validated volume and value outputs against IEA renewable energy deployment benchmarks and FERC-style grid interconnection filings from Saudi Electric Company and Emirates Water and Electricity Company. The analytical framework models chemistry type, application segment, end-user procurement channel, and capacity tier across the projection horizon. CAGRs derive from regression against solar-plus-storage deployment trajectories and electric vehicle fleet conversion timelines, with thermal stability requirements under Gulf climate conditions as a chemistry-specific forecast input.
The analysis sits within stated boundaries; outcomes outside sustained lithium-iron-phosphate cost competitiveness or delayed solid-state commercialization would require recalibration. Forecasts reflect assumptions regarding SASO enforcement consistency, NEOM project execution cadence, and Chinese precursor export policy stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Bio Based Battery Market
Batteries
Disposable Batteries Market
Batteries
South America Consumer Battery Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Consumer Battery Market
Batteries
Asia Pacific Electric Vehicle Battery Electrolyte Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Carbon Black in Lead-Acid Battery Market
Batteries
China Battery Market
Batteries
Global Solar Battery Charger Market
Batteries
Alkaline Battery Market
Batteries
Two Wheeler Lead Acid Batteries Market
Batteries
Stationary Lead-Acid Battery Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Electric Battery Market
Batteries
Modular Battery Market