
 Nickel-Based Battery Charger Market | 2026-2036
Nickel-Based Battery Charger Market Size, Share, and Industry Trends Forecast 2026-2036
Nickel-Based Battery Charger Market Insights
UL 1310 certification for Class 2 power units is redrawing competitive boundaries for charger manufacturers seeking North American market access. Panasonic Corporation leverages its captive battery cell production to control input costs across NiMH charger lines. Duracell Inc. competes through retail channel dominance in consumer electronics segments. GP Batteries International Limited anchors its position in European industrial aftermarket supply.
A nickel-based battery charger converts alternating current to direct current at specified voltage and current profiles optimized for nickel-metal hydride or nickel-cadmium electrochemistry, typically operating between 1.2V and 14.4V per cell string with temperature-compensated charge termination. Smart charger architectures with delta-V detection and thermal foldback now dominate product development roadmaps. Fast charger variants command premium positioning in automotive service applications where cycle time determines workshop throughput. Wall chargers retain volume leadership in consumer electronics despite portable charger growth in mobile workforce segments.
FCC Part 15 electromagnetic compatibility rules constrain charger design for devices marketed in the United States, while EU Ecodesign Directive efficiency tiers eliminate lower-performing transformer-based models from European distribution. China's GB 4943.1 safety standard for information technology equipment governs domestic charger certification and shapes export manufacturing specifications. Stakeholders must monitor evolving efficiency benchmarks and chemistry-specific charge algorithm patents as NiMH technology faces competitive pressure from lithium-ion alternatives in high-growth applications.
Market Dynamics
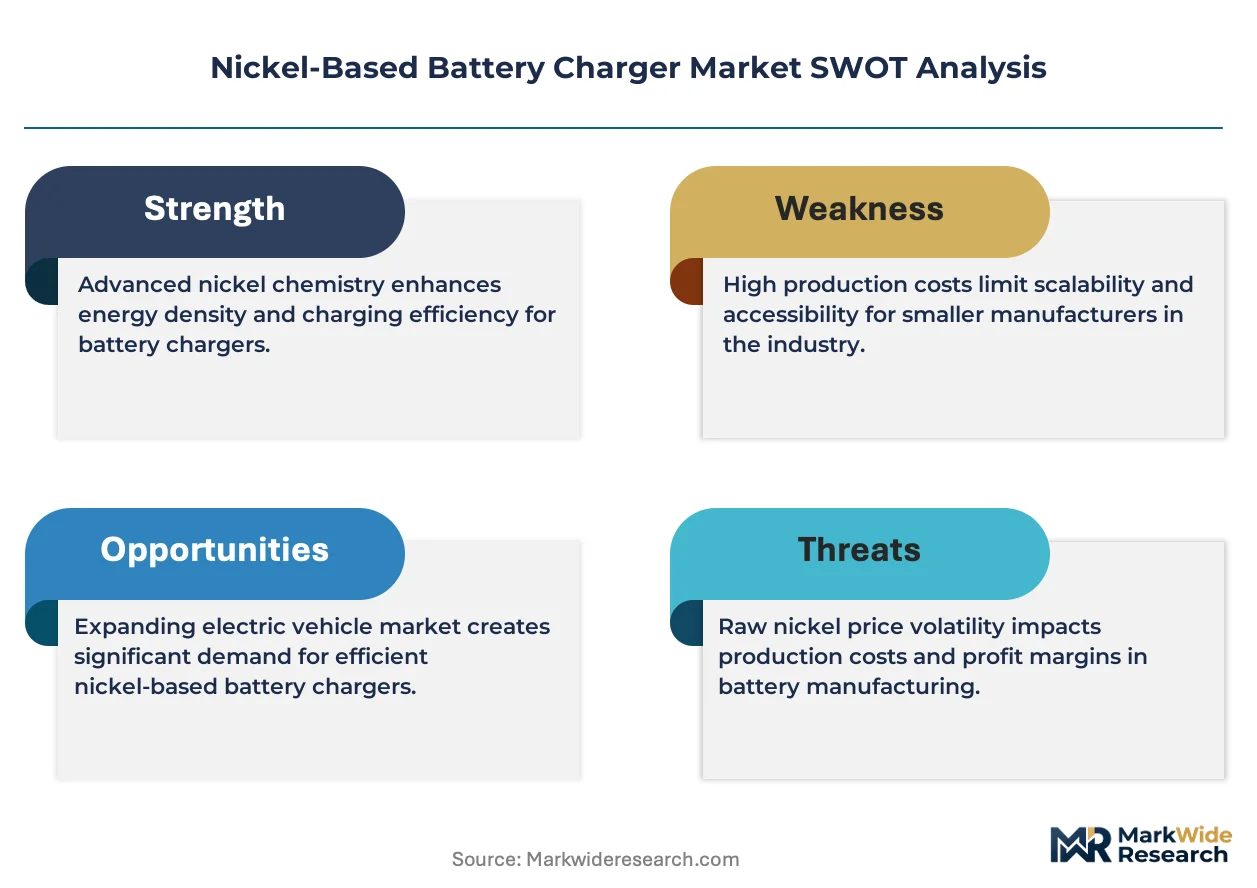
The nickel-based battery charger market faces structural pressure from lithium-ion chemistry substitution in high-performance applications, forcing incumbent suppliers to defend industrial and legacy consumer segments where NiMH retains cost and safety advantages.
Growth Catalysts
- EU Ecodesign Directive efficiency tiers:German industrial equipment operators are replacing transformer-based charger fleets to comply with mandated standby power limits, creating replacement demand across manufacturing corridors.
- Captive NiMH cell production:China's integrated battery-to-charger manufacturing ecosystems sustain cost-competitive supply chains for power tool and consumer electronics OEMs.
- Automotive service workshop throughput requirements:Fast charger variants with delta-V detection and thermal foldback are penetrating professional battery service bays where cycle time determines operational economics.
Market Restraints
- Lithium-ion chemistry substitution:Energy density advantages of Li-ion cells are displacing NiMH from cordless power tools and portable electronics, compressing addressable charger demand in growth segments.
- Rare earth magnet supply concentration:NdFeB magnet dependencies in high-efficiency charger transformers concentrate sourcing risk within China's processing infrastructure.
- UL 1310 certification cost barriers:Class 2 power unit testing requirements impose capital burdens on smaller manufacturers seeking North American market access.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Domestic cell production incentives could anchor regional charger supply chains serving South Asian industrial and automotive aftermarket demand.
- Smart charger algorithm patents:Proprietary delta-V and temperature-compensated termination IP offers differentiation in medical device and aerospace applications where charge precision commands premium positioning.
- Industrial IoT integration:Charger-to-fleet management system connectivity enables predictive maintenance and usage-based service models in material handling and warehouse automation.
Industry Challenges
- FCC Part 15 electromagnetic compliance timelines:Conducted and radiated emission testing for switching-mode charger architectures extends product development cycles for US-bound variants.
- Legacy system integration complexity:Retrofitting smart charge termination into existing NiCd infrastructure without full fleet replacement creates interoperability friction for industrial battery room operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nickel-Based Battery Charger Market |
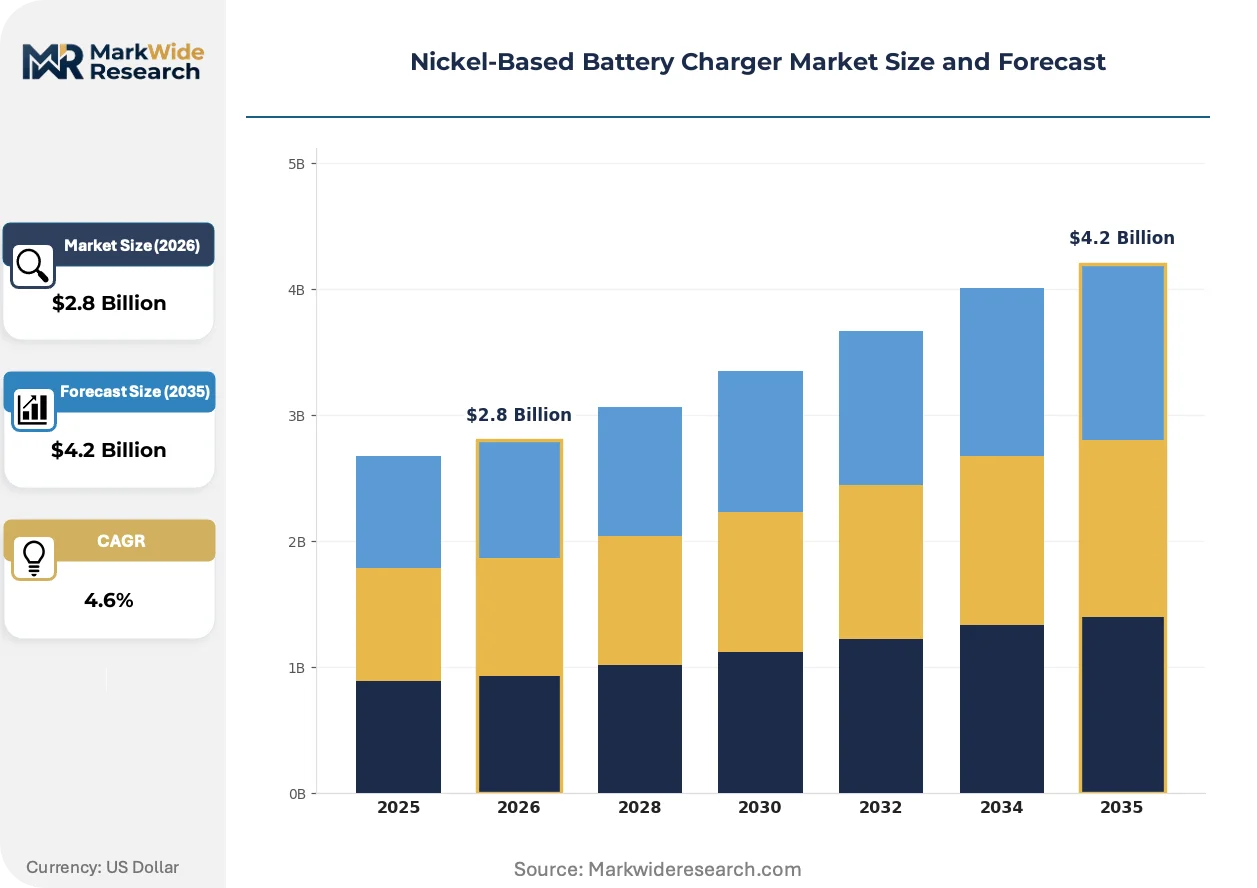
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Chargers, Portable Chargers, Fast Chargers, Smart Chargers Technology: NiMH, NiCd, Hybrid, Qi End User: Consumer Electronics, Automotive, Industrial Equipment, Renewable Energy Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Panasonic Corporation, EBL, PowerTech, Energizer Holdings Inc., Duracell Inc., GP Batteries International Limited, VARTA AG, Saft Groupe S.A., BYD Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nickel-Based Battery Charger Market Trends and Innovations
Active development in charge termination algorithms and thermal management architectures is compressing product lifecycles while regulatory efficiency mandates accelerate obsolescence of conventional transformer-based designs.
Switching-mode power conversion with synchronous rectification is supplanting linear transformer architectures in mid-to-high power charger segments. Industrial battery room operators and automotive service chains are adopting these topologies to meet EU Ecodesign standby power requirements. The shift is compressing margins for legacy transformer manufacturers while rewarding semiconductor-integrated design houses.
REACH substance restrictions on cadmium content are constraining NiCd charger demand across European industrial applications. The regulation is accelerating fleet conversion toward NiMH-compatible charge profiles in material handling and backup power systems. German and French industrial battery suppliers are prioritizing chemistry-agnostic charger platforms to hedge against further substance bans.
Specification-driven procurement is consolidating charger vendor selection around certified safety and efficiency benchmarks rather than unit cost. Large industrial fleet operators are unbundling charger supply from cell procurement, creating direct relationships with power electronics specialists. This pattern is most visible in North American warehouse automation and airport ground support equipment deployments.
Nickel-Based Battery Charger Market Segmentation
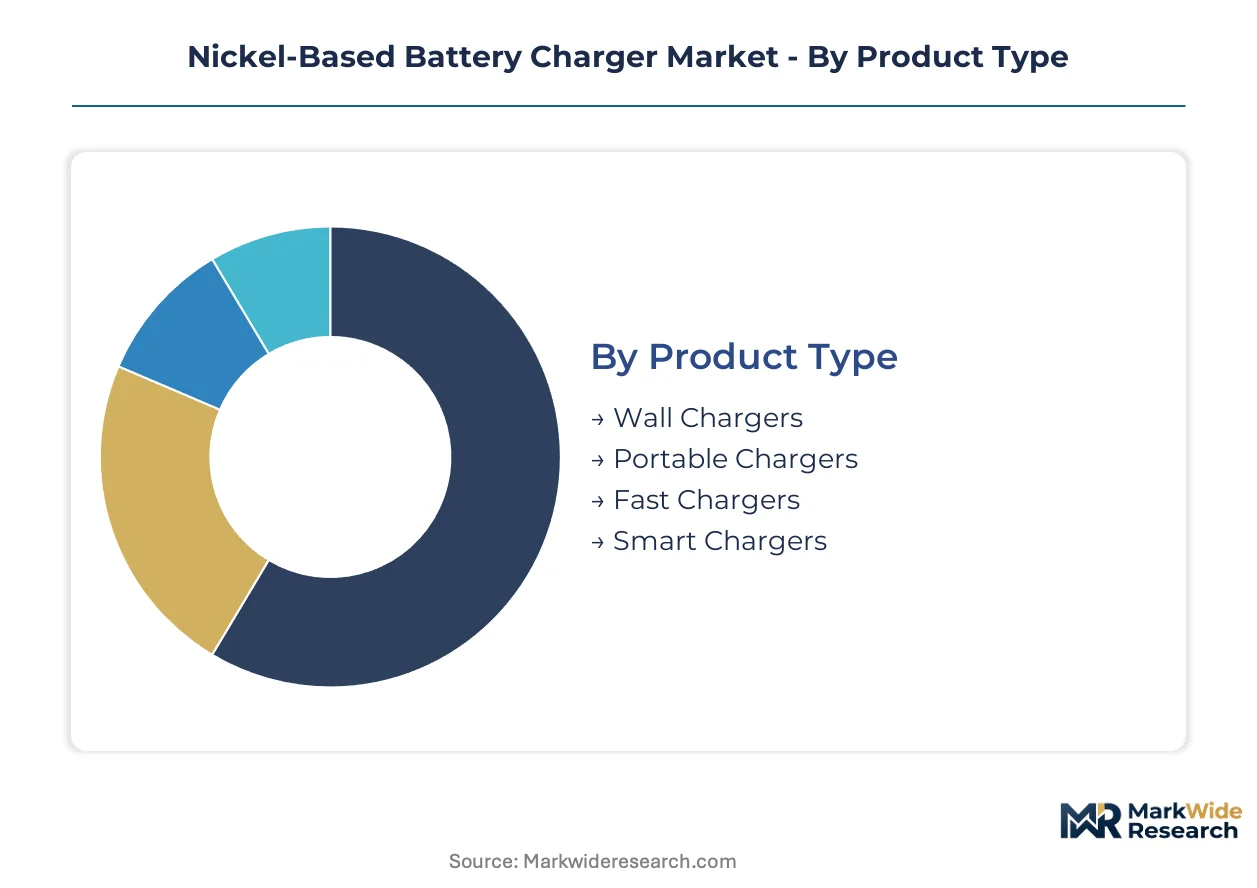
Nickel-based battery charger procurement channels favor distinct product configurations, with industrial buyers prioritizing certified fast-charging architectures while consumer segments drive volume through compact wall-mounted units. Chemistry-specific charge algorithms and regional regulatory compliance further stratify supplier selection across end-use verticals.
Product Type:
Channel mix varies sharply by product type: wall chargers and portable units flow predominantly through online retail and consumer electronics distributors, while fast chargers and smart chargers concentrate in direct sales to industrial fleet operators and automotive service chains.
- Wall Chargers:Stationary AC-to-DC converters operating between 1.2V and 14.4V per cell string, typically delivering 0.1C to 0.5C charge rates with basic timer-based or trickle termination. Demand clusters in China's manufacturing corridors where captive NiMH cell production sustains integrated OEM supply for consumer electronics and power tool brands.
- Fast Chargers:High-current architectures employing delta-V detection and thermal foldback to achieve 1C to 3C charge rates, compressing cycle times for professional battery service applications. Automotive workshops in Germany are upgrading to these variants to meet throughput requirements under Ecodesign efficiency mandates.
- Portable Chargers:Compact DC-input units for mobile workforce segments, integrating vehicle power adapters and USB-C PD compatibility. Field service technicians and warehouse automation operators drive replacement cycles in North American logistics corridors.
- Smart Chargers:Microprocessor-controlled systems with chemistry-agnostic charge profiles, temperature compensation, and fleet management connectivity. Medical device manufacturers and aerospace battery room operators specify these for charge precision in regulated environments.
By volume, wall chargers lead. By growth pace, smart chargers are expanding most quickly.
Technology:
Cost tier stratification separates legacy electrochemistry from emerging standards, with NiMH and NiCd occupying economy-to-standard tiers while hybrid and Qi-enabled platforms command premium positioning.
- NiMH:Nickel-metal hydride charge algorithms dominate industrial and consumer segments with voltage peak detection and negative delta-V termination. China's integrated battery-to-charger ecosystems sustain cost-competitive supply chains for power tool OEMs.
- NiCd:Nickel-cadmium taper and pulse charging architectures face structural decline as REACH substance restrictions constrain European industrial demand. Material handling operators in France and Germany are accelerating fleet conversion toward chemistry-agnostic platforms.
- Hybrid:Multi-chemistry chargers supporting both NiMH and NiCd profiles with automatic cell detection, reducing fleet complexity for industrial battery room operators managing mixed cell inventories.
- Qi:Inductive charging interfaces for low-power NiMH applications in consumer electronics, limited by efficiency constraints in higher-current industrial use cases.
Hybrid platforms are gaining share fastest as procurement consolidates around chemistry-agnostic specifications.
End User:
Application-specific performance requirements dictate charger specification, with automotive and industrial segments prioritizing cycle time and fleet connectivity while consumer electronics emphasizes unit cost and form factor.
- Consumer Electronics:Low-power wall and portable chargers for cordless phones, toys, and personal care devices. Retail channel dominance by battery brand licensors shapes supplier selection around packaging and placement terms rather than technical differentiation.
- Automotive:Fast charger penetration in professional battery service bays where workshop throughput determines operational economics. Delta-V detection and thermal management are mandatory specifications for garage equipment distributors.
- Industrial Equipment:Smart charger adoption in material handling, backup power systems, and warehouse automation. Fleet management connectivity enables predictive maintenance and usage-based service models.
- Renewable Energy:NiMH storage integration in off-grid and backup power applications, with charge controllers optimized for intermittent solar and wind input profiles.
Industrial equipment represents the steepest expansion trajectory as IoT integration redefines charger value propositions.
Distribution Channel:
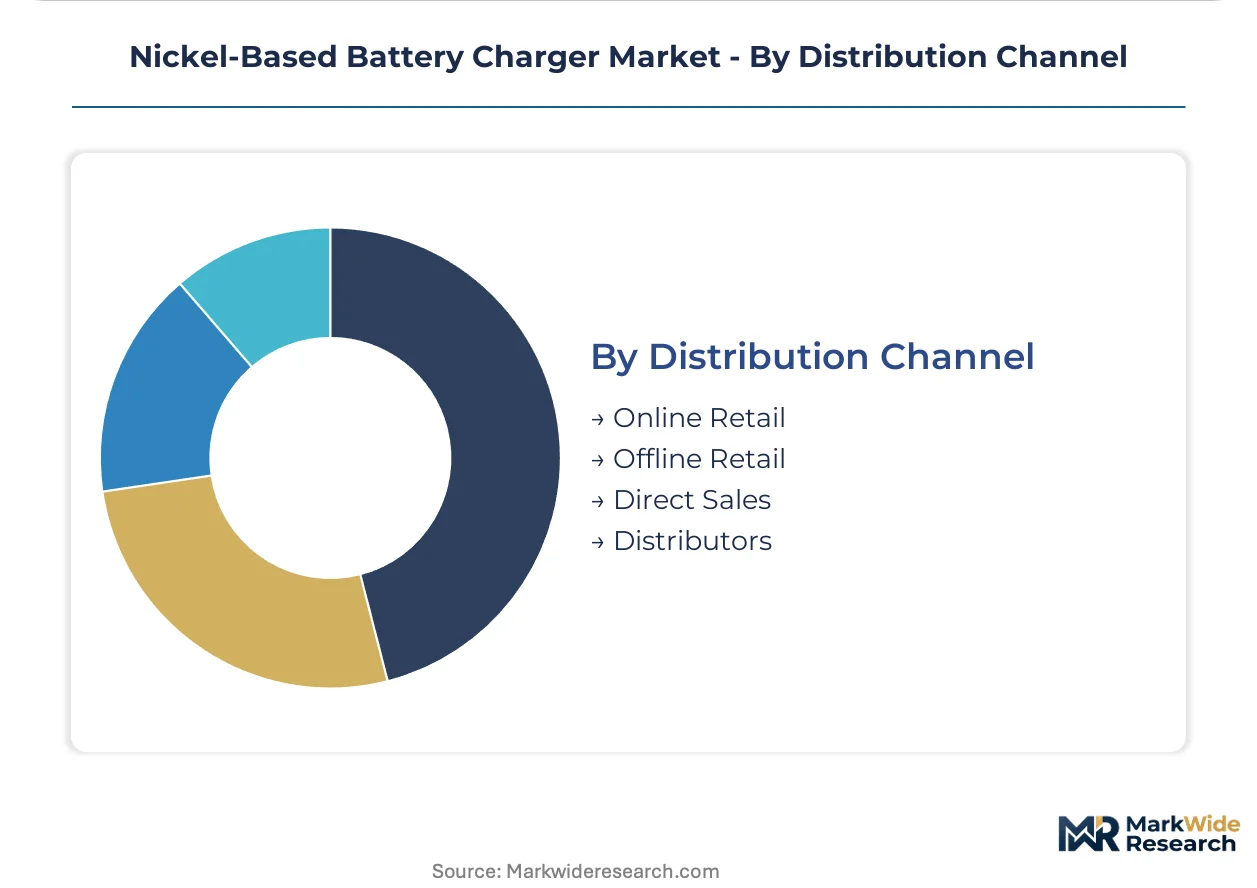
Customer type and purchase scale determine channel selection, with enterprise fleet operators bypassing retail entirely while small commercial buyers split between distributors and direct manufacturer relationships.
- Online Retail:Consumer electronics and replacement charger sales through marketplace platforms and brand-direct storefronts. Price transparency and review aggregation compress margins for undifferentiated wall charger variants.
- Offline Retail:Electronics specialty stores and home improvement chains for immediate-need replacement purchases. Battery brand licensors maintain shelf presence through retail channel exclusivity arrangements.
- Direct Sales:OEM supply agreements and enterprise fleet contracts for industrial and automotive charger procurement. Large warehouse automation deployers in North America are unbundling charger supply from cell procurement.
- Distributors:Industrial supply houses and garage equipment specialists serving automotive service chains and material handling operators. Technical support and certification documentation drive distributor selection.
Direct sales channels are climbing the fastest as specification-driven procurement consolidates vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European charger distribution logistics, while China's high-speed rail network links Pearl River Delta manufacturing clusters to inland assembly plants. These infrastructure assets shape regional supply chain configurations.
United States
Automotive service chains and warehouse automation deployers drive charger procurement, with FCC Part 15 electromagnetic compliance timelines extending product development cycles. The EPA's ENERGY STAR certification program shapes efficiency specifications for commercial charger fleets. California's logistics corridor concentrates smart charger adoption for material handling electrification.
Germany
Industrial battery room operators replace transformer-based charger fleets to meet EU Ecodesign Directive standby power mandates. REACH substance restrictions on cadmium accelerate NiCd-to-NiMH fleet conversion. Bavaria's manufacturing belt anchors automotive workshop fast-charger deployment for battery service throughput.
China
Captive NiMH cell production sustains integrated battery-to-charger manufacturing ecosystems for power tool OEMs. GB 4943.1 safety certification governs domestic charger specifications and export manufacturing standards. Shenzhen and Dongguan electronics clusters dominate wall charger volume production for consumer electronics brands.
Japan
Precision manufacturing and medical device sectors specify temperature-compensated charge termination for regulated applications. METI's energy efficiency labeling program drives smart charger adoption in industrial segments. Osaka-Kansai manufacturing corridor concentrates hybrid charger platform development for chemistry-agnostic specifications.
India
Automotive aftermarket and material handling operators create replacement demand as industrial electrification expands. The PLI scheme for advanced chemistry cell manufacturing could anchor regional charger supply chains. Maharashtra's industrial belt concentrates procurement activity for warehouse automation and logistics fleet operators.
Nickel-Based Battery Charger Market Competitive Landscape
Listed leaders compete with private specialists across certification and channel access dimensions, creating a tiered structure where scale advantages in semiconductor integration separate top-tier suppliers from transformer-dependent legacy manufacturers. The vendor base clusters around three strategic archetypes: captive cell producers controlling input costs, retail channel dominants leveraging brand licensing, and power electronics specialists winning specification-driven industrial procurement. Competitive moves concentrate on M&A for certification portfolio expansion and backward integration into magnetics and semiconductor sourcing.
Among Japanese-listed electronics conglomerates, Panasonic Corporation exemplifies the captive-production archetype through in-house cell manufacturing. Duracell Inc. and Energizer Holdings Inc. represent retail-channel dominants competing through brand presence and shelf-space arrangements. GP Batteries International Limited anchors the industrial aftermarket specialist position within European supply chains. These three patterns—captive integration, retail leverage, and aftermarket technical service—capture the competitive vectors shaping vendor selection across end-use segments.
| Leading Market Players |
|---|
| Panasonic Corporation |
| EBL |
| PowerTech |
| Energizer Holdings Inc. |
| Duracell Inc. |
| GP Batteries International Limited |
| VARTA AG |
| Saft Groupe S.A. |
| BYD Company Limited |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between German industrial fleet operators and power electronics specialists lock in multi-year supply access while insulating procurement teams from spot-market volatility in magnetics and semiconductor components. These contracts embed volume commitments that stabilize unit economics for switching-mode charger architectures facing EU Ecodesign compliance deadlines.
Pricing Analysis
Certification level creates the primary spread between charger tiers, with UL 1310 Class 2 power unit validation commanding substantial premiums over uncertified transformer-based alternatives. Three-tier pricing structure across premium certified, standard efficiency-compliant, and economy legacy tiers reflects differential compliance investment recovery timelines. Pricing pressure stems from lithium-ion substitution compressing addressable NiMH charger demand in cordless power tools. Consumer electronics buyers exhibit highest price sensitivity, while aerospace and medical device procurement prioritizes charge precision over unit cost.
Supply Chain Analysis
Strategic stockpiling of NdFeB magnets and power semiconductors characterizes procurement behavior among tier-one charger manufacturers anticipating supply disruption. Manufacturing concentrates in China, Japan, and Germany, with Shenzhen electronics clusters feeding consumer wall charger volume and Bavarian industrial specialists serving automotive workshop segments. Transformer laminations, MOSFETs, and thermal management substrates constitute critical input dependencies. Single-source vulnerability in rare earth magnet processing concentrates risk within China's separation and alloying infrastructure. Distribution runs through industrial supply houses and garage equipment specialists for professional segments, with online retail capturing consumer replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nickel-based battery charger market sits in early-cycle expansion as industrial IoT integration redefines charger value propositions beyond power conversion toward predictive maintenance platforms.
For Market Incumbents: Fortify certification portfolios through accelerated UL 1310 and GB 4943.1 testing investments to outpace smaller competitors facing capital barriers. Deepen backward integration into magnetics sourcing to offset NdFeB supply concentration risk. Prioritize chemistry-agnostic platform development to hedge against REACH-driven NiCd phase-out acceleration. For New Entrants and Emerging Players: Lead with smart charger algorithm specialization targeting medical device and aerospace segments where charge precision commands premium positioning. India's PLI scheme for advanced chemistry cell manufacturing offers the most penetrable regional entry point. Pursue direct sales relationships with warehouse automation deployers unbundling charger procurement from cell supply. For Investors and Strategic Acquirers: Semiconductor-integrated design houses with switching-mode power conversion expertise represent the most attractive acquisition archetype for exposure to efficiency mandate-driven replacement cycles. Long-term viability hinges on defending industrial and legacy consumer segments where NiMH retains cost and safety advantages against lithium-ion encroachment. Watch for inflection when automotive OEMs announce platform-standardized battery service equipment specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | UL 1310 Class 2 validation unlocks North American automotive service chain procurement. |
| Backward Integration into Magnetics | In-house NdFeB transformer core production mitigates China's rare earth processing concentration risk. |
| Smart Charger Algorithm Development | Proprietary delta-V detection IP secures premium positioning in FDA-regulated medical device applications. |
| Industrial IoT Platform Integration | Fleet management connectivity enables usage-based service models for warehouse automation operators. |
| Chemistry-Agnostic Platform Launch | Dual NiMH-NiCd compatibility reduces fleet complexity for European material handling operators facing REACH restrictions. |
Research Methodology
Initial hypotheses were tested against primary input from power electronics procurement managers, automotive service equipment distributors, industrial battery room operators, and regulatory compliance specialists, then refined through secondary validation. Primary fieldwork encompassed charger manufacturer executives, magnetics suppliers, and fleet management software integrators. Secondary sources included UL certification databases, EU Ecodesign Directive efficiency tier documentation, GB standards filings, and customs trade records for transformer and semiconductor inputs. Bottom-up volume modeling triangulated against top-down market sizing from industrial equipment deployment statistics.
Variance decomposition across the projection horizon isolates volume drivers by product type, technology platform, end-use vertical, and regional regulatory cluster. Segmentation dimensions encompass wall, fast, portable, and smart charger configurations; NiMH, NiCd, hybrid, and Qi technologies; consumer electronics, automotive, industrial equipment, and renewable energy end users; plus online retail, offline retail, direct sales, and distributor channels. CAGR derivation incorporated installed base replacement cycles, efficiency mandate compliance deadlines, and lithium-ion substitution elasticity estimates. Chemistry-specific charge algorithm patent filings and fleet management system integration adoption curves informed technology transition assumptions.
Underlying assumptions cover Ecodesign Directive enforcement continuity, REACH substance restriction trajectory, and rare earth magnet supply stability, with deviation risk concentrated in lithium-ion cost parity acceleration and automotive platform electrification timing. Forecasts reflect these conditions without claiming predictive certainty. Revision becomes warranted when lithium-ion pack pricing crosses threshold parity with NiMH in power tool applications or when major automotive OEMs announce standardized battery service equipment specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Elastic Battery Binders Market
Batteries
Battery Anode Materials Market
Batteries
Europe SLI Battery Market
Batteries
Advanced Batteries Market
Batteries
Battery Coolant-Antifreeze Refractometer Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Micro Battery Market
Batteries
US Solar Battery Market
Batteries
Sodium-Air Battery Market
Batteries
Taiwan Battery Market
Batteries
Norway Rechargeable Battery Market
Batteries
Japan Battery Market
Batteries
Forklift Battery Market
Batteries
East Africa Battery Market
Batteries
Vietnam Battery Market
Batteries
Flow Battery Market