
 North America Flame Retardant Thermoplastics Market | 2026-2036
North America Flame Retardant Thermoplastics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Flame Retardant Thermoplastics Market Intelligence
Electric vehicle OEMs are reorganizing supplier priorities around thermoplastics that meet UL 94 V-0 ratings without halogenated additives. BASF SE leverages its Ludwigshafen-derived polymer expertise to serve Detroit-area battery housing programs. RTP Company specializes in custom-compounded flame retardant formulations for thin-wall electronics enclosures. Albemarle Corporation anchors North American brominated additive supply through its Magnolia, Arkansas production complex.
Flame retardant thermoplastics incorporate phosphorus, nitrogen, or mineral-based additives into polyethylene, polypropylene, polyamide, or polyester matrices to achieve self-extinguishing behavior under ASTM E84 or UL 94 test protocols. Extrusion and injection molding dominate processing routes, with injection molding commanding premium positioning due to tight dimensional tolerances in connector and housing applications. Polyamide segments lead value contribution where high heat deflection temperature intersects with electrical insulation requirements. Aerospace applications represent the fastest-growing end-user category as OEMs substitute metal assemblies with certified thermoplastic structural components.
The EPA regulates persistent organic pollutant content under TSCA Section 6, while NHTSA enforces Federal Motor Vehicle Safety Standard 302 for passenger compartment materials. California's Department of Toxic Substances Control extends these constraints through Proposition 65 labeling requirements and Safer Consumer Products regulations. Stakeholders must monitor pending EPA action on organohalogen flame retardants under the National Recycling Strategy, as restriction scopes could force reformulation across polypropylene and polyethylene product lines before the next compliance cycle.
Market Dynamics
EPA action on organohalogen flame retardants under the National Recycling Strategy is forcing compounders to accelerate phosphorus-based and mineral-filled formulations ahead of the next compliance cycle. This regulatory compression is reorganizing raw material procurement and reformulation timelines across polypropylene and polyethylene product lines.
Growth Catalysts
- Federal Motor Vehicle Safety Standard 302:NHTSA enforcement tightens fire-safety thresholds for passenger compartment materials, pulling flame-retardant thermoplastics into EV battery enclosures and interior assemblies.
- EV battery housing programs:Electric vehicle OEMs in the US Midwest automotive corridor are specifying UL 94 V-0 rated polyamide grades for thermal runaway protection.
- Phosphorus additive technology:Non-halogenated intumescent systems achieve equivalent flame suppression with lower smoke toxicity, satisfying California Proposition 65 labeling constraints.
Market Restraints
- Brominated additive supply concentration:North American bromine derivative production clusters in Magnolia, Arkansas, creating single-point vulnerability for compounders dependent on legacy flame retardant chemistry.
- Mineral filler loading limits:High addition rates of aluminum trihydrate or magnesium hydroxide degrade mechanical properties in thin-wall electronics enclosures, constraining design freedom.
- Safer Consumer Products regulations:California's Department of Toxic Substances Control imposes extended compliance timelines and alternative assessment requirements that extend product development cycles.
Strategic Opportunities
- Texas petrochemical hub expansion:Proximity to integrated polypropylene and polyethylene resin supply enables captive compounding operations with reduced logistics exposure.
- Aerospace structural substitution:OEMs are certifying thermoplastic assemblies to replace metal brackets and housings in cabin interiors, opening qualification pathways for high-performance polyamide and PEEK grades.
- Recyclate integration:Post-industrial and post-consumer polyamide streams can incorporate flame retardant packages through reactive extrusion, aligning with EPA circular economy priorities.
Industry Challenges
- UL 94 V-0 certification timelines:Third-party testing protocols require 12-16 week turnaround, compressing product launch windows for custom-compounded formulations.
- Reactive extrusion expertise scarcity:Compounders lack sufficient process engineers capable of optimizing shear history and additive dispersion for intumescent systems in twin-screw operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Flame Retardant Thermoplastics Market |
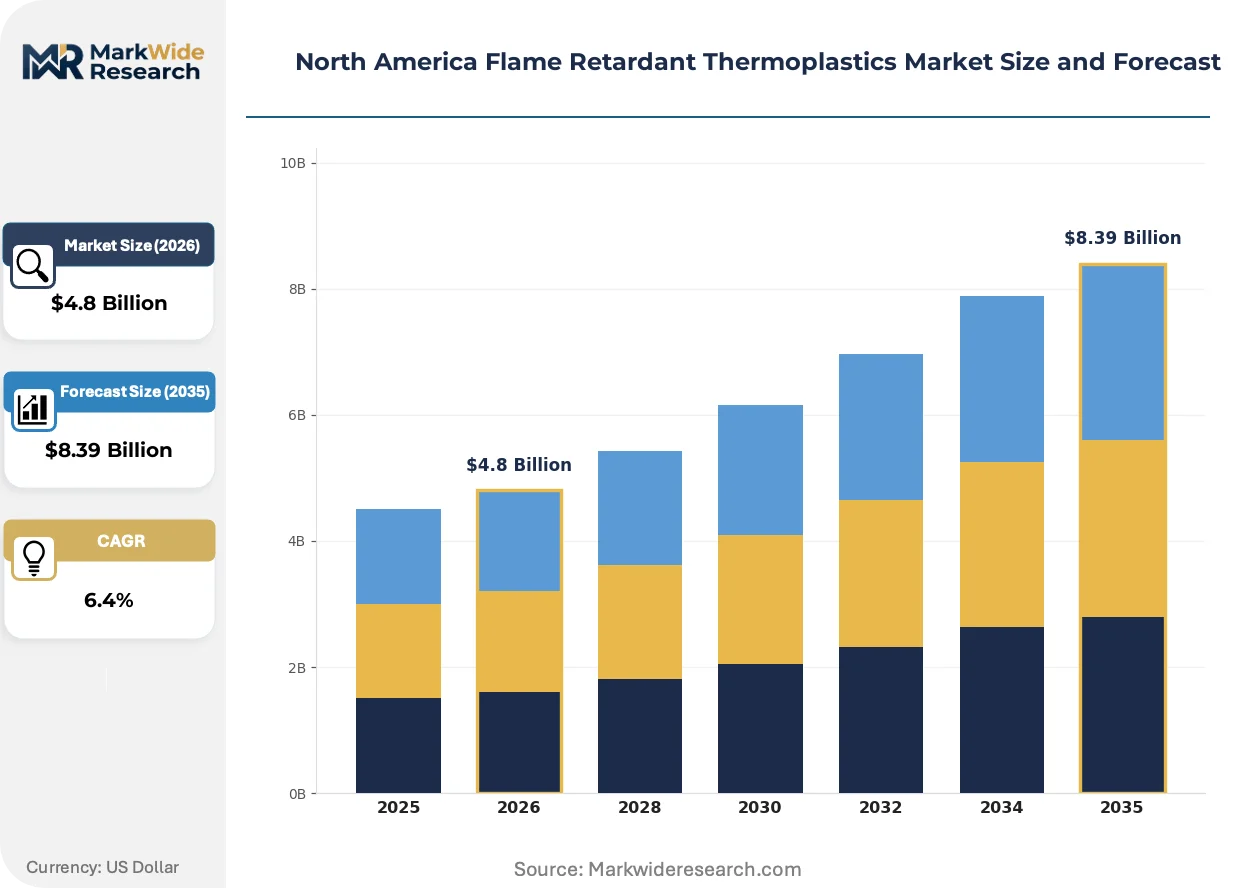
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyamide, Polyester End User: Automotive, Construction, Electronics, Aerospace Technology: Extrusion, Injection Molding, Blow Molding, 3D Printing Application: Insulation, Coatings, Additives, Structural Components |
| Companies Covered | ICL, Clariant AG, BASF SE, PolyOne Corporation, Albemarle Corporation, LANXESS, RTP Company, SABIC, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Flame Retardant Thermoplastics Market Strategic Shifts & Innovations
Formulation chemistry is pivoting away from legacy halogenated systems toward reactive and polymeric flame retardant architectures. This transition is compressing established supply relationships while opening technical partnerships between resin producers and specialty additive suppliers.
Phosphinate-based flame retardants are decomposing into char-forming phosphoric acid species at polymer surfaces, creating protective intumescent layers without halogen release. EV battery enclosure manufacturers in Michigan and Ohio are qualifying these systems for 800-volt architectures. The technology is decomposing incumbent brominated additive volumes in transportation applications where smoke toxicity regulations are tightening fastest.
EPA's pending TSCA Section 6 action on organohalogen flame retardants is extending restriction scopes to cover recycling streams and articles in commerce, not just virgin chemical production. Compounders must now document substance identity through supply chains to demonstrate compliance. Polypropylene appliance housings and polyethylene wire insulation face the most immediate reformulation pressure as the rulemaking advances.
Automotive OEMs are consolidating approved material lists around pre-certified compound grades to compress supplier qualification cycles. Tier-1 molders in the Detroit corridor now specify RTP Company and BASF SE catalog formulations rather than developing custom recipes. This concentration is visible most acutely in battery housing programs where thermal runaway testing costs exceed $500,000 per material iteration.
North America Flame Retardant Thermoplastics Market Segmentation
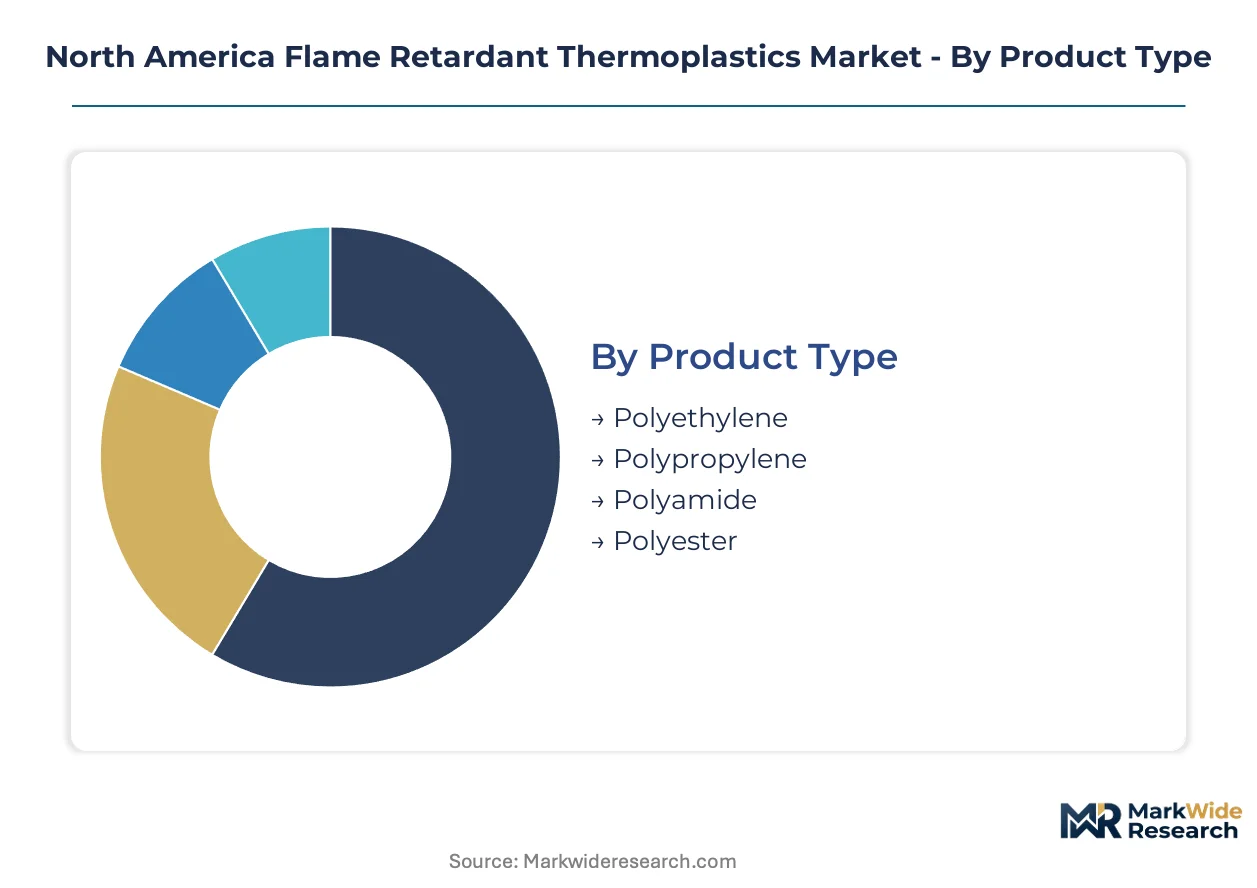
Segmentation in flame retardant thermoplastics reveals how formulation chemistry, processing constraints, and end-use certification requirements create distinct commercial battlegrounds. Each dimension exposes different vulnerability points to regulatory pressure and raw material supply disruption.
Product Type:
Domestic resin production concentrates polypropylene and polyethylene supply around Texas and Louisiana Gulf Coast complexes, while polyamide grades draw more heavily on imported caprolactam and adipic acid feedstocks.
- Polyamide:High heat deflection temperature and electrical insulation properties position this segment for EV battery enclosures and connector housings. Michigan and Ohio automotive programs specify UL 94 V-0 rated grades for thermal runaway protection, pulling compound volumes into the Midwest corridor.
- Polypropylene:Mineral-filled formulations dominate appliance housings and wire insulation where cost sensitivity limits additive loading. EPA pending TSCA Section 6 action on organohalogen flame retardants is forcing phosphorus-based reformulation across polypropylene product lines ahead of compliance deadlines.
- Polyethylene:Wire and cable jacketing applications in construction and utilities drive specification of halogen-free grades meeting low smoke zero halogen protocols.
- Polyester:Electrical insulation films and electronic component housings leverage inherent flame resistance combined with phosphorus additive synergists.
Polyamide commands the established base. The steepest expansion runs through polypropylene as regulatory compression accelerates reformulation cycles.
End User:
Customer concentration varies sharply: automotive and electronics OEMs consolidate approved material lists around pre-certified grades, while construction and aerospace maintain more fragmented qualification pathways.
- Automotive:NHTSA Federal Motor Vehicle Safety Standard 302 enforcement tightens fire-safety thresholds for passenger compartment materials. Detroit-area EV battery housing programs specify UL 94 V-0 rated polyamide grades, with thermal runaway testing costs exceeding $500,000 per material iteration compressing supplier selection.
- Aerospace:OEMs certify thermoplastic assemblies to replace metal brackets and cabin interior housings, opening qualification pathways for high-performance polyamide and PEEK grades. Smoke toxicity regulations under FAA certification protocols favor phosphorus-based intumescent systems.
- Electronics:Thin-wall connector and enclosure applications command premium positioning due to tight dimensional tolerances, with California Proposition 65 labeling constraints pushing halogen-free formulations.
- Construction:ASTM E84 testing protocols govern wall coverings and insulation applications, with mineral-filled polyethylene and polypropylene grades serving low-rise commercial and residential building codes.
Automotive anchors volume concentration. Aerospace is climbing the fastest as structural substitution programs advance through qualification cycles.
Technology:
Processing route selection determines additive dispersion quality and flame retardant efficacy, with capital intensity creating tiered competitive entry barriers across methods.
- Injection Molding:Dominates connector, housing, and battery enclosure applications where tight dimensional tolerances intersect with electrical insulation requirements. Twin-screw compounding expertise scarcity constrains intumescent system optimization for this high-value route.
- Extrusion:Wire and cable jacketing, film, and sheet applications leverage continuous processing economics. High shear history in single-screw operations challenges uniform mineral filler distribution for aluminum trihydrate loaded formulations.
- Blow Molding:Hollow structural components and fuel tank applications require specialized flame retardant packages that maintain parison stability during processing.
- 3D Printing:Emerging qualification for aerospace prototyping and low-volume end-use parts, with filament formulations incorporating reactive phosphorus additives under development.
Injection molding captures margin concentration. 3D printing is gaining share fastest as aerospace qualification protocols adapt to additive manufacturing.
Application:
Functional role in the final article determines flame retardant loading levels and regulatory exposure, with structural applications facing the most stringent certification requirements.
- Structural Components:Load-bearing brackets, housings, and battery enclosures require mechanical property retention at elevated temperatures. EV OEMs in the US Midwest specify polyamide grades with 800-volt architecture compatibility, displacing metal assemblies where weight reduction intersects with thermal runaway protection.
- Insulation:Wire and cable, electrical barrier films, and thermal management layers demand dielectric stability combined with self-extinguishing behavior. Mineral-filled polyethylene formulations serve utility and construction segments under ASTM and UL test protocols.
- Coatings:Thin-film intumescent layers applied to substrate surfaces provide fire protection without bulk material replacement, serving retrofit construction applications.
- Additives:Masterbatch and compound formats enable downstream processors to incorporate flame retardant functionality without specialized compounding equipment, concentrating supply relationships around RTP Company and BASF SE catalog formulations.
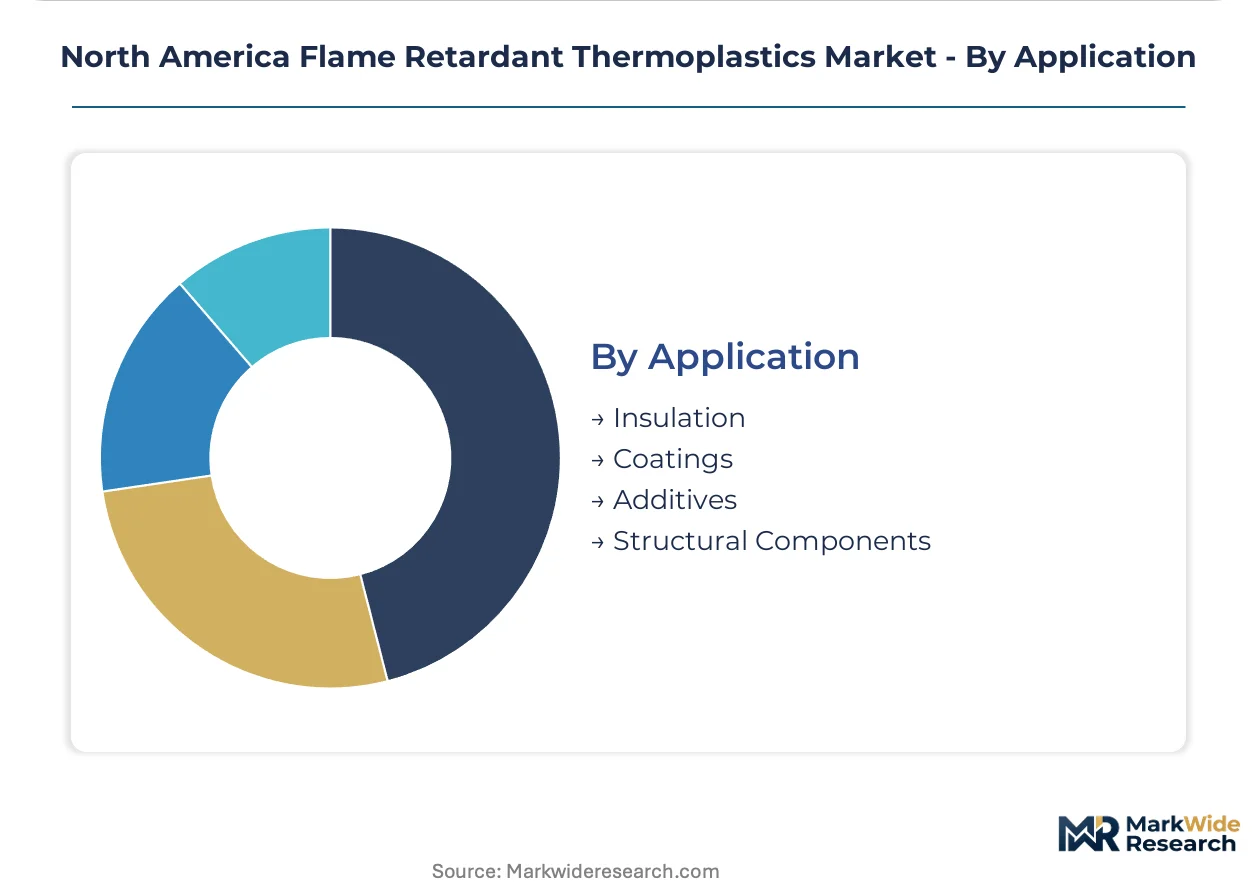
Structural components command specification authority. Insulation is expanding most quickly as electrification infrastructure buildout accelerates cable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States resin producers export compounded flame retardant formulations to Canadian automotive assembly plants and Mexican electronics manufacturing clusters, establishing cross-border supply dependencies that concentrate procurement decisions in Midwest and Gulf Coast logistics hubs.
United States
EV battery housing programs in Michigan and Ohio specify UL 94 V-0 rated polyamide grades for thermal runaway protection. NHTSA enforces Federal Motor Vehicle Safety Standard 302 for passenger compartment materials. The Texas petrochemical hub enables captive compounding operations with integrated polypropylene and polyethylene resin supply.
Canada
Automotive OEMs in Ontario source flame retardant thermoplastics for lightweight interior assemblies and battery enclosure components. Health Canada coordinates with EPA on persistent organic pollutant restrictions under aligned regulatory frameworks. The Windsor-Detroit trade corridor concentrates cross-border material flows for just-in-time automotive supply chains.
Mexico
Electronics manufacturers in Tijuana and Guadalajara import compounded grades for connector housings and appliance components serving US consumer markets. Mexico's federal environmental regulator monitors chemical substance imports against TSCA-aligned notification requirements. The Bajío Region attracts wire and cable jacketing operations leveraging proximity to Texas resin supply.
North America Flame Retardant Thermoplastics Market Key Industry Players
Listed leaders compete with private specialists across formulation chemistry and geographic coverage, creating a tiered structure where scale-driven resin producers coexist with custom compounders. European-headquartered multinationals anchor premium positioning through integrated polymer research capabilities. Private specialists capture niche applications requiring rapid formulation turnaround. Capacity expansion in Texas and strategic partnerships with EV battery programs represent the dominant competitive vectors reshaping procurement relationships.
Among diversified chemical conglomerates, BASF SE and SABIC occupy positions spanning base resin production through compounded formulations, while RTP Company exemplifies the private specialist archetype focused on custom-compounded flame retardant packages. Clariant AG and LANXESS represent European-origin players with North American compounding assets. Albemarle Corporation anchors brominated additive supply through its Arkansas production complex. These companies collectively illustrate how competitive positioning fragments across integrated supply chain control versus formulation agility.
| Leading Market Players |
|---|
| ICL |
| Clariant AG |
| BASF SE |
| PolyOne Corporation |
| Albemarle Corporation |
| LANXESS |
| RTP Company |
| SABIC |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
UL 94 V-0 certification protocols gate both supplier qualification and price differentiation, separating pre-certified compound grades from custom formulations requiring extended testing cycles. The 12-16 week third-party validation timeline compresses procurement decisions toward catalog offerings while elevating premium positioning for reactive phosphorus-based systems.
Pricing Analysis
Prior-generation brominated additive formulations trade at commodity-equivalent levels while current-generation phosphorus-based intumescent systems command 15-25% premiums for equivalent flame suppression performance. Next-generation polymeric and reactive architectures under development for 800-volt EV battery architectures carry further markup potential tied to thermal runaway certification. Three-tier pricing structure across premium certified grades, standard catalog formulations, and economy mineral-filled options stratifies by certification level and volume commitment. Pricing pressure stems from EPA pending TSCA Section 6 action forcing accelerated reformulation timelines that compress margin recovery. Construction wire and cable buyers exhibit highest price sensitivity due to specification commoditization, while automotive battery housing programs prioritize performance over unit cost.
Supply Chain Analysis
The United States concentrates polypropylene and polyethylene resin production around Texas and Louisiana Gulf Coast petrochemical complexes, while polyamide feedstocks draw more heavily on imported caprolactam and adipic acid streams. Brominated additive supply rests on Albemarle Corporation's Magnolia, Arkansas production complex, creating single-source vulnerability for legacy formulation dependencies. Phosphorus-based flame retardant precursors source from domestic phosphate mining operations and Chinese intermediate chemical exports. Tariff exposure on Chinese phosphorus chemical imports threatens cost stability for intumescent system compounders. Distribution runs through Midwest automotive corridor logistics hubs serving Detroit-area OEMs and Texas-based captive compounding operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for formulation optimization and regulatory compliance documentation are expanding faster than base compound volumes, creating recurring revenue attachment opportunities alongside transactional resin sales.
For Market Incumbents: Fortify captive compounding positions in the Texas petrochemical hub through backward integration into polypropylene and polyethylene resin supply, insulating margin structures from feedstock volatility. Accelerate UL 94 V-0 pre-certification of phosphorus-based grades to compress supplier qualification cycles before EPA TSCA Section 6 restrictions take effect. Defensive positioning against emerging mineral-filled compounders requires demonstrating mechanical property retention at equivalent loading levels in thin-wall electronics applications. For New Entrants and Emerging Players: Lead with reactive extrusion expertise for post-industrial polyamide recyclate streams, capturing EPA circular economy alignment as a qualification shortcut with sustainability-focused OEMs. Aerospace structural substitution programs represent the most penetrable white-space target, as metal-to-thermoplastic conversion creates new supplier slots outside established automotive approved material lists. Go-to-market positioning should emphasize rapid formulation turnaround for low-volume qualification batches rather than competing on catalog breadth. For Investors and Strategic Acquirers: EPA's pending TSCA Section 6 action on organohalogen flame retardants reshapes the acquisition landscape toward phosphorus-based and mineral-filled formulation specialists with established automotive qualification pathways. Long-term viability over the next decade hinges on positioning ahead of regulatory-driven chemistry transitions rather than defending legacy brominated additive exposure. Target acquisition archetypes include custom compounders with reactive extrusion capabilities and existing UL 94 V-0 certified grade portfolios. The signal to watch is thermal runaway test completion rates at NHTSA-recognized facilities as a leading indicator of supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polypropylene production in Texas reduces logistics exposure and feedstock cost volatility. |
| UL 94 V-0 Pre-Certification Investment | Pre-certified phosphorus-based grades compress 12-16 week supplier qualification cycles for EV programs. |
| Reactive Extrusion Capacity Expansion | Twin-screw compounding expertise scarcity creates defensive moat for intumescent system optimization. |
| Post-Industrial Recyclate Integration | Polyamide flame retardant compounding from recycled streams aligns with EPA circular economy priorities. |
| Aerospace Qualification Partnership | FAA smoke toxicity certification opens structural substitution pathways beyond automotive volume concentration. |
Research Approach
A standing panel of compounder plant managers, automotive Tier 1 procurement leads, flame retardant additive technical directors, and EPA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standard 302 enforcement records, EPA TSCA Section 6 rulemaking dockets, UL certification databases, and American Chemistry Council resin production statistics. Bottom-up volume estimates from end-use application sizing were cross-checked against top-down resin consumption figures through triangulation protocols.
Consistency checks against external benchmarks validated value outputs across the projection horizon. The analytical framework modeled segmentation across polymer chemistry, flame retardant additive type, processing technology, and end-use industry vertical. CAGRs were derived from regression analysis of historical volume trends adjusted for regulatory inflection timing and EV battery program procurement schedules. Forecast inputs incorporated thermal runaway testing cost trajectories and phosphorus additive technology adoption curves.
Forecasts assume regulatory continuity in EPA TSCA Section 6 and NHTSA Federal Motor Vehicle Safety Standard 302 enforcement regimes; material policy shifts would require re-modeling of reformulation timelines and chemistry transition costs. Specific risks include accelerated organohalogen restrictions, brominated supply disruption at the Arkansas production complex, and EV battery architecture voltage upgrades outpacing material qualification cycles. Recalibration cycles align with material shifts in EPA rulemaking advancement and NHTSA enforcement priority announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Epoxy Casting Potting Resin Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Sustainable Polymers Market
Polymers & Resins
Polyamide 11 & 12 Market