
 US Acrylic Solid Surface Market | 2026-2036
US Acrylic Solid Surface Market Size, Share, and Industry Trends Forecast 2026-2036
US Acrylic Solid Surface Market Analytics
NSF/ANSI Standard 51 certification for food equipment materials is unwinding competitive dynamics among acrylic solid surface manufacturers. DuPont leverages its deep R&D heritage in polymer science to sustain premium positioning across specification-driven channels. Wilsonart LLC anchors its competitive stance through extensive distribution control in the North American building products sector. Aristech Surfaces LLC specializes in cast sheet manufacturing, occupying a defensible niche in custom fabrication supply.
Acrylic solid surface comprises a mineral-filled matrix of polymethyl methacrylate (PMMA) resin, typically containing approximately one-third acrylic resin and two-thirds aluminum trihydrate filler, thermoformed or fabricated into seamless installations for countertops, bathtubs, sinks, and wall panels. The material's non-porous structure and repairable surface serve hygiene-critical and aesthetic-intensive environments across residential, commercial, hospitality, and healthcare end uses. Countertops dominate product type value capture due to kitchen and bath renovation frequency, while healthcare applications within the end user dimension command margin premiums through stringent performance specifications. Color category stratification shows solid colors maintaining volume leadership as metallics and translucents penetrate luxury hospitality and retail fixture segments.
FDA compliance for food-contact surfaces intersects with EPA formaldehyde emission regulations under TSCA Title VI to establish dual compliance thresholds for residential and commercial specification. OSHA workplace exposure standards further shape fabrication shop requirements, influencing regional production economics and contractor qualification. State-level building codes in California and Florida impose additional performance criteria that filter market access. Stakeholders must monitor evolving amendments to these frameworks alongside certification maintenance cycles to sustain specification relationships and avoid compliance-driven disqualification from project bidding.
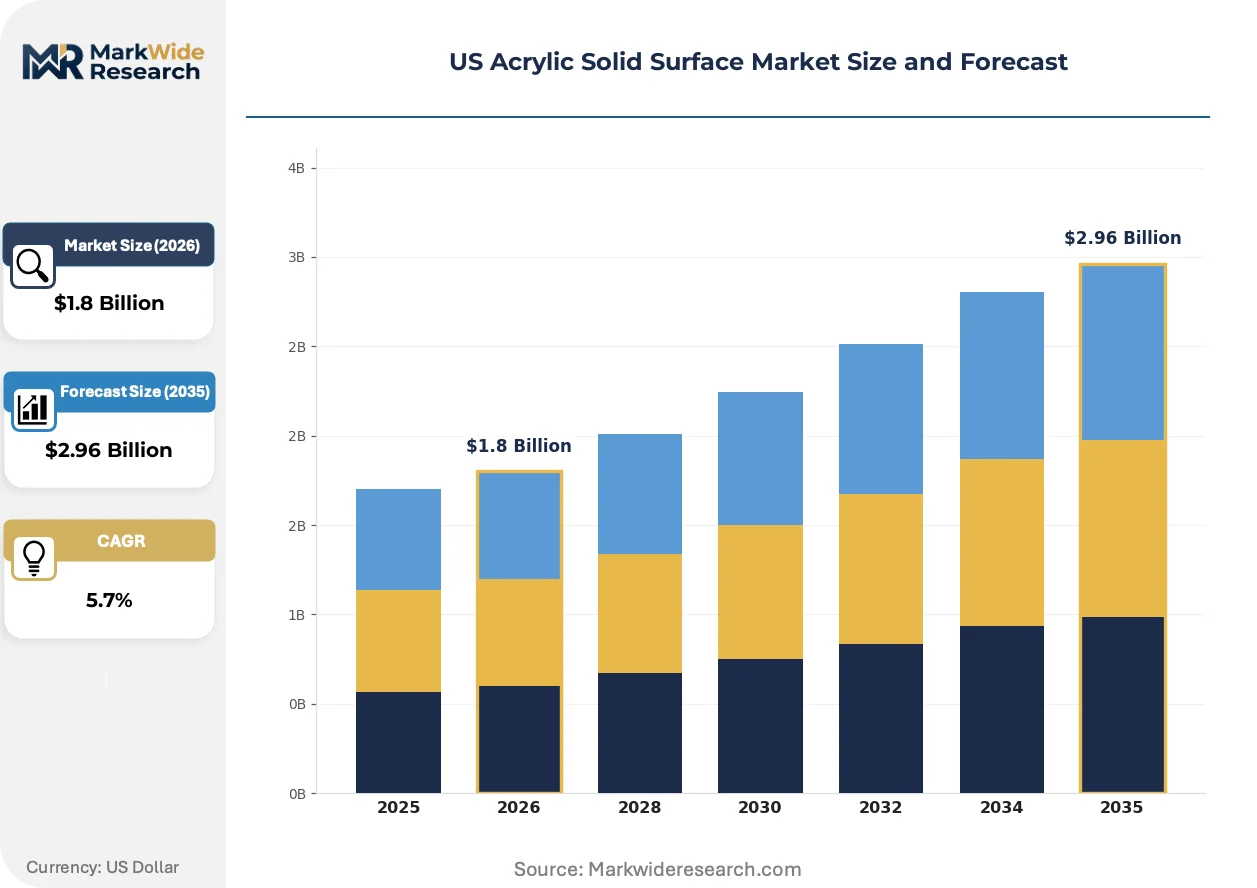
Market Dynamics
EPA formaldehyde emission standards under TSCA Title VI are compressing supplier margins while accelerating consolidation among fabricators unable to absorb compliance costs. Healthcare facility expansion across Sun Belt states sustains specification volume for non-porous surfacing materials.
Growth Catalysts
- Healthcare infection control mandates:Joint Commission accreditation standards for non-porous surfaces in patient care zones drive replacement cycles in acute care and outpatient facilities. Renovation specifications specify seamless acrylic for sink surrounds and nurse stations.
- OSHA silica exposure rules:Fabrication shop compliance investments favor centralized production over distributed job-site cutting. This concentrates demand toward certified fabricators with engineered ventilation systems.
- Sun Belt residential construction:Florida, Texas, and Arizona permit issuance for single-family housing sustains countertop volume. Kitchen and bath renovation frequency in these states exceeds national baselines.
Market Restraints
- Aluminum trihydrate supply concentration:Domestic ATH filler production clusters in Gulf Coast petrochemical corridors. Disruption to bauxite refining or alumina supply cascades through acrylic solid surface cost structures within 60-90 days.
- Quartz composite substitution:Engineered stone manufacturers have captured specification share in residential kitchen segments. Price-sensitive buyers perceive comparable aesthetics at lower installed cost points.
- TSCA Title VI testing burden:Small fabricators face third-party certification costs exceeding annual revenue thresholds. This regulatory friction eliminates regional competitors in secondary metropolitan markets.
Strategic Opportunities
- Healthcare vertical expansion:Ambulatory surgical centers and dialysis clinics remain underpenetrated relative to hospital systems. NSF/ANSI 51 certification opens food service adjacencies within these facilities.
- Metallic and translucent colorways:Luxury hospitality fixtures in Miami, Las Vegas, and Los Angeles specify premium finishes. Custom fabrication capabilities differentiate suppliers in this margin-rich tier.
- Integrated sink-basin systems:Thermoformed seamless basins eliminate grout lines in clinical environments. This application commands specification premiums in infection-critical zones.
Industry Challenges
- Thermoforming technician scarcity:Skilled fabricators capable of complex three-dimensional forming command wage premiums. Training pipelines through community college programs lag replacement demand.
- Dual certification maintenance:NSF/ANSI 51 and EPA TSCA Title VI require separate audit cycles. Documentation burden strains quality assurance staffing at mid-size fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Acrylic Solid Surface Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertops, Bathtubs, Sinks, Wall Panels End User: Residential, Commercial, Hospitality, Healthcare Color Category: Solid Colors, Metallics, Translucents, Patterns Thickness: 1/4 Inch, 1/2 Inch, 3/4 Inch, 1 Inch |
| Companies Covered | Aristech Surfaces LLC, Wilsonart LLC, DuPont, LG Hausys, Hanwha Group, LOTTE Chemical Corporation, Trinseo, PORCELANOSA Grupo A.I.E., Hyundai L&C Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Acrylic Solid Surface Market Evolving Landscape
Material science advances and regulatory stringency are compressing traditional fabrication models while opening specification pathways for certified suppliers. Three developments merit close monitoring.
Digital templating and CNC routing is supplanting manual measurement and cutout processes in countertop fabrication. Custom residential and commercial contractors now expect sub-48-hour turnaround from template to installation. This technology compression eliminates smaller fabricators lacking capital equipment, concentrating volume toward automated production facilities.
EPA enforcement of TSCA Title VI composite wood product standards has extended to acrylic solid surface substrates used in cabinet and fixture integration. Fabricators serving multi-family residential developments must now document chain-of-custody for all substrate materials. California and Florida building inspectors have incorporated these requirements into routine permitting, affecting project timelines.
Direct-to-fabricator procurement platforms are compressing traditional distributor markups in specification-grade materials. Large hospitality and healthcare contractors now source acrylic sheet directly from manufacturers, engaging certified fabricators for installation only. This channel disintermediation is most visible in Texas and Florida markets where contractor consolidation has produced sophisticated procurement functions.
US Acrylic Solid Surface Market Segmentation
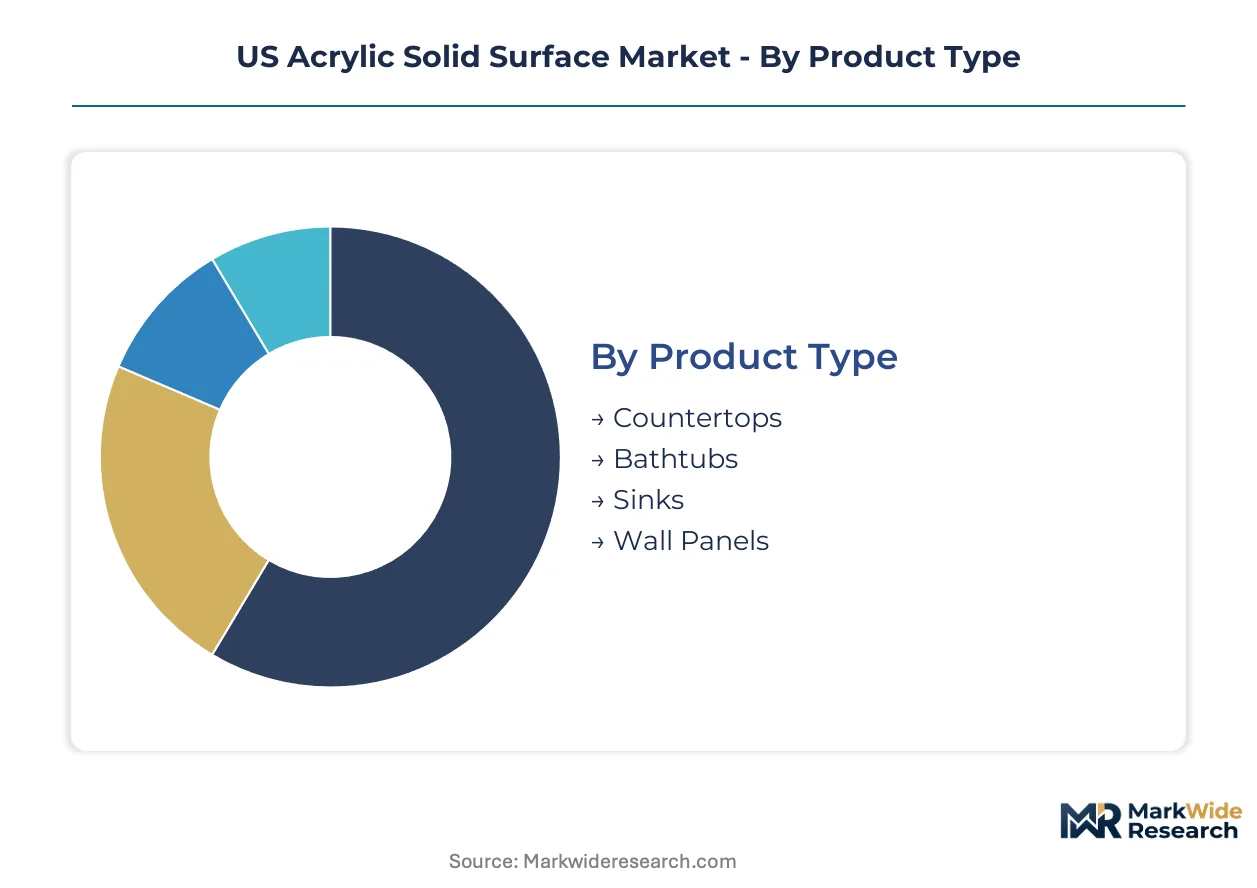
Acrylic solid surface manufacturers configure production lines around specification requirements that vary sharply across installation environments. EPA TSCA Title VI compliance thresholds and NSF/ANSI 51 certification status create divergent margin structures that reward precise segment targeting.
Product Type:
EPA formaldehyde emission standards under TSCA Title VI apply differentially based on substrate integration, with cabinet-integrated applications facing stricter documentation than standalone fixtures.
- Countertops:These installations combine PMMA resin with aluminum trihydrate filler in slab formats fabricated to kitchen and bath dimensions. Demand concentrates in Sun Belt states where Florida, Texas, and Arizona residential permit issuance sustains renovation frequency above national baselines. NSF/ANSI 51 certification opens commercial food service specifications that residential-grade material cannot access.
- Bathtubs:Thermoformed seamless basins eliminate grout lines and joint failure points through complex three-dimensional forming. Healthcare facilities in Sun Belt expansion corridors specify these for infection control in patient bathing areas, commanding margin premiums through Joint Commission accreditation alignment.
- Sinks:Integrated basin systems serve clinical environments where seamless construction supports sterilization protocols.
- Wall Panels:Vertical surfacing applications span hospitality lobbies and healthcare corridors requiring durable, repairable finishes.
Countertops handle the majority of throughput; bathtubs are expanding most quickly on specification share as healthcare infection control mandates tighten.
End User:
Cost tier differentiation separates specification-grade certified supply from economy residential channels, with compliance burden acting as a price floor discriminator.
- Residential:Kitchen and bath renovation cycles in Sun Belt states drive volume through big-box retail and contractor channels. Price-sensitive buyers face quartz composite substitution pressure, compressing margins on non-certified material.
- Healthcare:Acute care hospitals and outpatient clinics specify seamless acrylic for sink surrounds, nurse stations, and patient care zones under Joint Commission non-porous surface requirements. Dialysis clinics and ambulatory surgical centers remain underpenetrated relative to hospital systems.
- Commercial:Corporate facilities and institutional buildings specify repairable surfaces for high-traffic areas.
- Hospitality:Luxury hotel fixtures in Miami, Las Vegas, and Los Angeles drive demand for metallic and translucent colorways at premium price tiers.
Residential absorbs the greatest volume tonnage; healthcare commands the steepest expansion trajectory through regulatory-driven replacement cycles.
Color Category:
Application context determines color specification, with clinical environments favoring solid tones while luxury retail and hospitality explore premium finishes.
- Solid Colors:Standard pigmentation dominates healthcare and commercial installations where uniformity and repairability outweigh aesthetic differentiation. Volume leadership reflects specification conservatism in institutional procurement.
- Metallics:Mineral flake integration creates reflective surfaces specified for luxury hospitality fixtures in Miami, Las Vegas, and Los Angeles. Custom fabrication capabilities differentiate suppliers in this margin-rich tier.
- Translucents:Backlit applications in retail fixtures and hotel lobbies require specialized resin formulation.
- Patterns:Veined and textured finishes compete with engineered stone aesthetics in residential kitchens.
Solid colors maintain volume leadership; metallics are climbing the fastest on margin contribution as hospitality renovation accelerates.
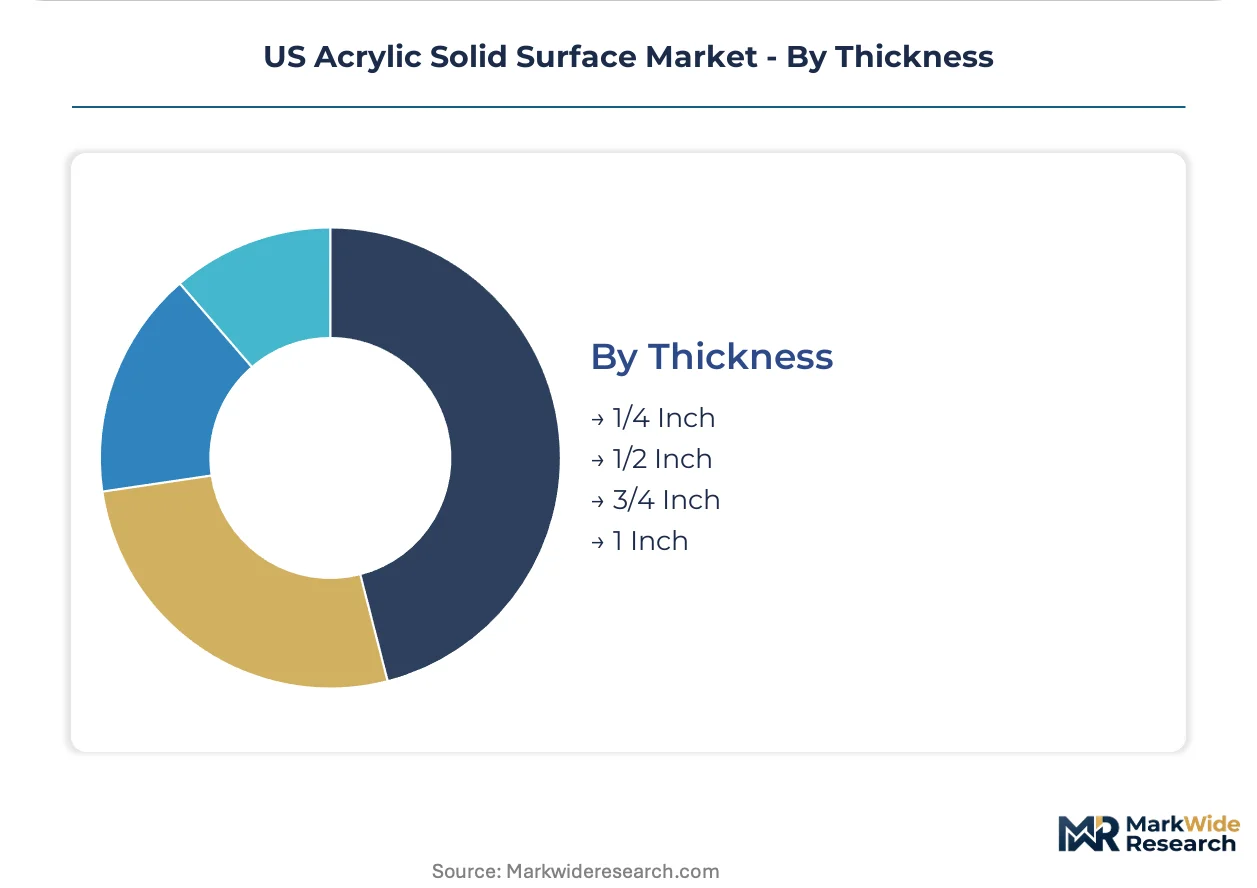
Thickness:
Structural load requirements and thermoforming complexity create tiered pricing across dimensional specifications, with thicker material commanding fabrication skill premiums.
- 3/4 Inch:Standard countertop thickness balances material cost with structural integrity for residential kitchen spans. Fabrication shops maintain highest equipment utilization on this dimension, concentrating production economics.
- 1/2 Inch:Vertical applications and thermoformed curves reduce material cost while enabling complex forming. Healthcare wall panels and hospitality fixtures specify this thickness for weight reduction and forming latitude.
- 1/4 Inch:Thin cladding applications serve overlay and resurfacing projects with minimal structural demand.
- 1 Inch:Heavy-duty commercial installations provide maximum durability for high-impact environments.
3/4 inch handles the majority of fabrication throughput; 1/2 inch is gaining share fastest as vertical surfacing specifications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare contractors and hospitality developers concentrate procurement authority in distinct state-level clusters. Sun Belt residential builders drive countertop volume through permit issuance velocity. Specification-grade fabricators align distribution with these buyer archetypes.
Florida
Healthcare facility expansion across Miami, Orlando, and Tampa sustains demand for seamless sink-basin systems in infection-critical zones. Florida building codes incorporate EPA TSCA Title VI documentation into routine permitting for multi-family developments. The Miami-Dade corridor anchors luxury hospitality renovation cycles specifying metallic and translucent colorways.
Texas
Single-family housing permits in Dallas-Fort Worth, Houston, and Austin exceed national baselines for kitchen and bath renovation frequency. OSHA silica exposure compliance concentrates fabrication toward certified shops with engineered ventilation. The Dallas metroplex hosts direct-to-fabricator procurement platforms serving large contractor consolidation.
California
Residential renovation in Los Angeles and San Francisco metros drives countertop specification despite quartz composite substitution pressure. California Air Resources Board standards extend beyond federal EPA thresholds for formaldehyde emissions. The Los Angeles basin commands premium finishes for retail fixture and hospitality lobby applications.
Arizona
Active adult community construction around Phoenix and Tucson sustains solid color volume for standard kitchen installations. State-level contractor licensing requirements filter fabrication shop qualification. The Phoenix metro anchors distribution nodes serving southwestern residential markets.
Northeast Corridor
Healthcare system consolidation in Boston, New York, and Philadelphia drives replacement cycles for Joint Commission-compliant surfacing. State environmental agencies enforce documentation burdens exceeding federal minimums. The Boston metro maintains specification relationships with academic medical centers requiring NSF/ANSI 51 certification.
US Acrylic Solid Surface Market Competitive Landscape
Player mix skews toward integrated material-science conglomerates and specialized sheet manufacturers. Market structure concentrates specification-grade supply among three to four vertically positioned suppliers while fabrication tiers fragment regionally. Strategic archetypes include polymer R&D heritage players, cast-sheet specialists, and Asian chemical conglomerates with acrylic resin backward integration. Dominant competitive moves center on distribution control consolidation and direct-to-fabricator channel disintermediation.
Within the heritage-tier, DuPont exemplifies polymer science R&D positioning across specification-driven channels. Wilsonart LLC anchors North American building products distribution control. Aristech Surfaces LLC occupies the cast-sheet manufacturing niche serving custom fabrication supply chains.
| Leading Market Players |
|---|
| Aristech Surfaces LLC |
| Wilsonart LLC |
| DuPont |
| LG Hausys |
| Hanwha Group |
| LOTTE Chemical Corporation |
| Trinseo |
| PORCELANOSA Grupo A.I.E. |
| Hyundai L&C Corporation |
| Others |
Value Network & Pricing Analysis
Quartz composite substitution in residential kitchen segments simultaneously compresses acrylic solid surface pricing power in the Sun Belt and redirects supply chain investment toward specification-grade certification tiers. This displacement dynamic concentrates margin recovery in healthcare and hospitality channels where NSF/ANSI 51 and EPA TSCA Title VI compliance create defendable price floors.
Pricing Analysis
Cost-plus contracts with aluminum trihydrate indexation dominate raw material procurement for acrylic solid surface manufacturers. Three-tier pricing structure across specification-certified, standard residential, and economy builder-grade levels separates margin profiles sharply. Pricing pressure stems from quartz composite penetration in Florida and Texas renovation markets where installed cost comparisons favor engineered stone. Residential buyers through big-box retail channels exhibit highest price sensitivity; healthcare procurement committees demonstrate lowest sensitivity due to Joint Commission compliance mandates.
Supply Chain Analysis
Strategic stockpiling of aluminum trihydrate filler prevails over just-in-tight approaches given Gulf Coast petrochemical corridor concentration and bauxite refining volatility. Domestic ATH production clusters in Texas and Louisiana; PMMA resin supply draws from Louisiana and Ohio chemical manufacturing bases. Single-source vulnerability concentrates in ATH filler supply where alumina refining disruption cascades through cost structures within 60-90 days. Distribution runs through manufacturer-direct platforms serving Texas and Florida contractor consolidation alongside traditional building products distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US acrylic solid surface market represents an early-cycle expansion story as healthcare infection control mandates penetrate ambulatory surgical centers and dialysis clinics previously underexposed to seamless surfacing specifications.
For Market Incumbents: Shield specification-grade positioning through accelerated NSF/ANSI 51 certification maintenance and EPA TSCA Title VI documentation systems. Deepen backward integration into PMMA resin production to offset aluminum trihydrate cost volatility. Consolidate distribution control in Texas and Florida where direct-to-fabricator procurement platforms threaten traditional channel economics. For New Entrants and Emerging Players: Anchor in Arizona active adult community construction and Phoenix-metro distribution nodes where solid color volume sustains entry-level fabrication economics. Target metallic and translucent colorway capabilities for Miami-Dade luxury hospitality renovation cycles. Pursue certified fabricator partnerships rather than sheet manufacturing to bypass capital-intensive production barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed cast-sheet specialists holding Aristech Surfaces LLC-type positioning in custom fabrication supply chains. Five-to-ten year viability hinges on healthcare vertical expansion durability and regulatory compliance barrier sustainability. Monitor ambulatory surgical center construction permit velocity as inflection indicator for specification-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NSF/ANSI 51 Certification Investment | Opens food service adjacencies in healthcare facilities requiring Joint Commission alignment. |
| Backward Integration into PMMA Resin | Captures margin compression from petroleum feedstock volatility in Gulf Coast corridors. |
| Direct-to-Fabricator Platform Launch | Bypasses distributor markups in Texas and Florida contractor consolidation markets. |
| Metallic Colorway Production Line | Addresses Miami, Las Vegas, and Los Angeles luxury hospitality fixture specifications. |
| Integrated Sink-Basin System Development | Eliminates grout lines for infection-critical healthcare zones commanding premium pricing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA TSCA Title VI compliance databases, state-level building permit records, and healthcare facility construction filings. Interviews with acrylic sheet plant managers, certified fabricator shop owners, healthcare procurement directors, and hospitality contractor estimators combined with customs trade data, SEC building products sector filings, and Joint Commission accreditation records. Bottom-up fabrication shop capacity modeling triangulates against top-down residential permit flow analysis.
Segmentation dimensions modeled include product type, end user category, color specification tier, and thickness grade across the projection horizon. CAGRs derive from regression analysis of permit issuance velocity, healthcare construction spending patterns, and material substitution elasticities. Industry-specific forecast inputs incorporate OSHA silica exposure compliance cost trajectories and EPA formaldehyde enforcement intensity indices.
Material uncertainties — aluminum trihydrate supply disruption, quartz composite pricing aggression, and healthcare construction cycle amplitude — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory maintenance of TSCA Title VI stringency and Joint Commission surface material standards. Revision becomes warranted when ambulatory surgical center construction permit issuance deviates substantially from healthcare system consolidation baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
North America Polycarbonate (PC) Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Europe Engineering Plastics Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
India Automotive Thermoplastic Polymer Composites Market