
 Global Polycaprolactone Market | 2026-2036
Global Polycaprolactone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polycaprolactone Market Foresight
Buyer concentration across medical device OEMs is rebalancing as specialized implant manufacturers fragment demand while large pharmaceutical packaging houses consolidate procurement. Daicel Corporation leverages its captive caprolactone feedstock to anchor polymer purity grades for long-acting drug delivery. Perstorp Holding AB competes through backward integration into renewable raw materials, sustaining cost positions in European biodegradable film. Shenzhen eSUN Industrial Co., Ltd dominates filament extrusion for desktop 3D printing, controlling distribution through direct e-commerce channels in Asia.
Polycaprolactone is a semi-crystalline aliphatic polyester synthesized via ring-opening polymerization of epsilon-caprolactone, with a low glass transition temperature near minus 60 degrees Celsius and complete biodegradability under composting conditions. Manufacturers produce it for thermoplastic processing, controlled-release pharmaceutical matrices, and tissue engineering scaffolds where hydrolytic degradation rates match tissue regeneration timelines. Granules and powder forms lead volume shipments, though filament grades for additive manufacturing represent the fastest-expanding margin pool as printer OEMs qualify bio-based feedstocks. Biomedical applications command premium pricing due to ISO 10993 biocompatibility certification burdens, while packaging segments compete on industrial composting standards.
REACH registration requirements in Europe and FDA device master file protocols in the United States shape market access timelines, forcing producers to maintain dual certification systems. China's GB standards for biodegradable plastics and evolving compostability testing under SAMR supervision are redirecting domestic capacity toward certified film and coating grades. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory as compliance thresholds tighten for residual catalyst content and degradation endpoint verification.
Market Dynamics
Medical device OEMs are fragmenting procurement authority while pharmaceutical packaging houses consolidate volume, creating asymmetric bargaining power that reshapes contract structures across biodegradable polymer supply chains.
Growth Catalysts
- ISO 10993 biocompatibility certification:Surgical implant manufacturers now require certified PCL grades for sutures and tissue scaffolds, expanding premium-grade demand.
- China's GB standards for biodegradable plastics:Domestic compostability mandates under SAMR supervision redirect filament and film capacity toward certified output.
- Desktop 3D printing adoption:Printer OEM qualification of bio-based feedstocks accelerates filament-grade consumption in maker and prototyping segments.
Market Restraints
- Epsilon-caprolactone monomer supply concentration:Captive production by integrated petrochemical majors limits merchant availability and inflates spot pricing volatility.
- Hydrolytic degradation rate variability:Batch-to-batch molecular weight distribution inconsistencies complicate long-acting drug release profile validation.
- Poly(lactic acid) substitution in packaging:PLA's lower cost and established industrial composting infrastructure displaces PCL in single-use film applications.
Strategic Opportunities
- India's CDSCO medical device regulations:Emerging domestic implant manufacturing clusters seek qualified biodegradable polymer suppliers for orthopedic and cardiovascular applications.
- Electrospinning-nanofiber convergence:Wound dressing and filtration membrane producers adopt PCL nanofiber matrices for controlled porosity and bioresorption.
- Direct e-commerce filament distribution:Asia-Pacific desktop printer users bypass traditional industrial distributors through manufacturer-direct digital channels.
Industry Challenges
- Residual catalyst content compliance:REACH and FDA device master file protocols demand sub-ppm tin and bismuth levels, extending purification validation timelines.
- Degradation endpoint verification:Industrial composting facilities require third-party certification of complete mineralization, complicating batch release workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polycaprolactone Market |
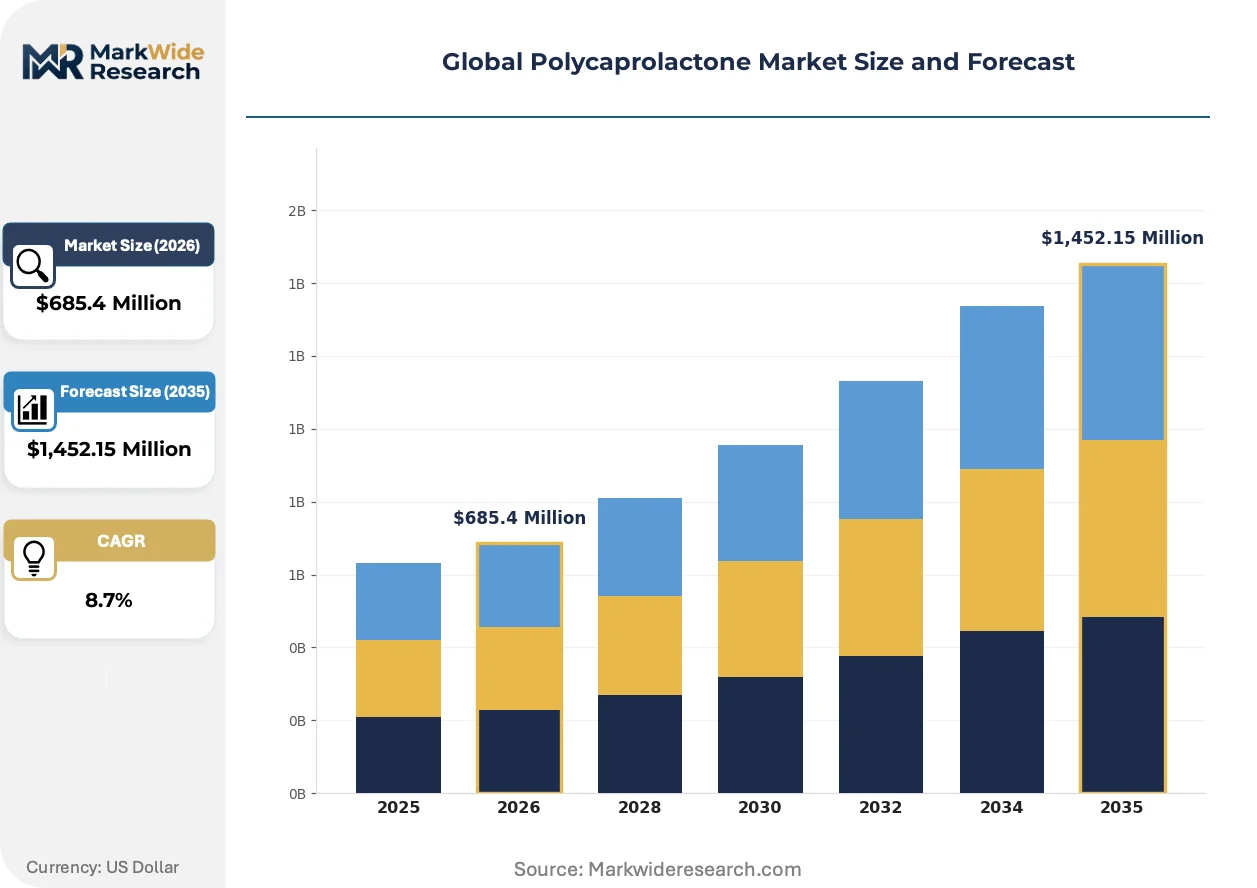
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Filaments, Solutions Application: Biomedical, Packaging, Coatings, Textiles End User: Medical Devices, Consumer Goods, Automotive Parts, Industrial Applications Form: Thermoplastic, Biodegradable Film, 3D Printing Material, Coating |
| Companies Covered | Daicel Corporation, Perstorp Holding AB, Corbion, BASF SE, Merck KGaA, Shenzhen Polymtek Biomaterial Co., Ltd, Shenzhen eSUN Industrial Co., Ltd, Durect Corporation, Haihang Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polycaprolactone Market Shifts & Advancements
Ring-opening polymerization catalyst advances and regulatory convergence on biodegradability testing protocols are compressing development cycles for medical-grade PCL formulations while expanding addressable applications.
Photocurable PCL oligomers are converging with vat photopolymerization 3D printing systems, enabling dental and maxillofacial implant manufacturers to produce patient-specific scaffolds with tunable degradation kinetics matched to bone regeneration timelines.
REACH registration requirements for polymer intermediates now mandate full substance identity dossiers, forcing non-EU producers to establish EU-based only representatives or surrender market access, with biomedical grade suppliers absorbing the highest compliance cost burden.
Large pharmaceutical packaging houses now consolidate annual PCL volume under single-source framework agreements with price renegotiation clauses tied to caprolactone monomer indices, displacing spot-market purchasing and compressing margin buffers for non-integrated compounders.
Global Polycaprolactone Market Segmentation
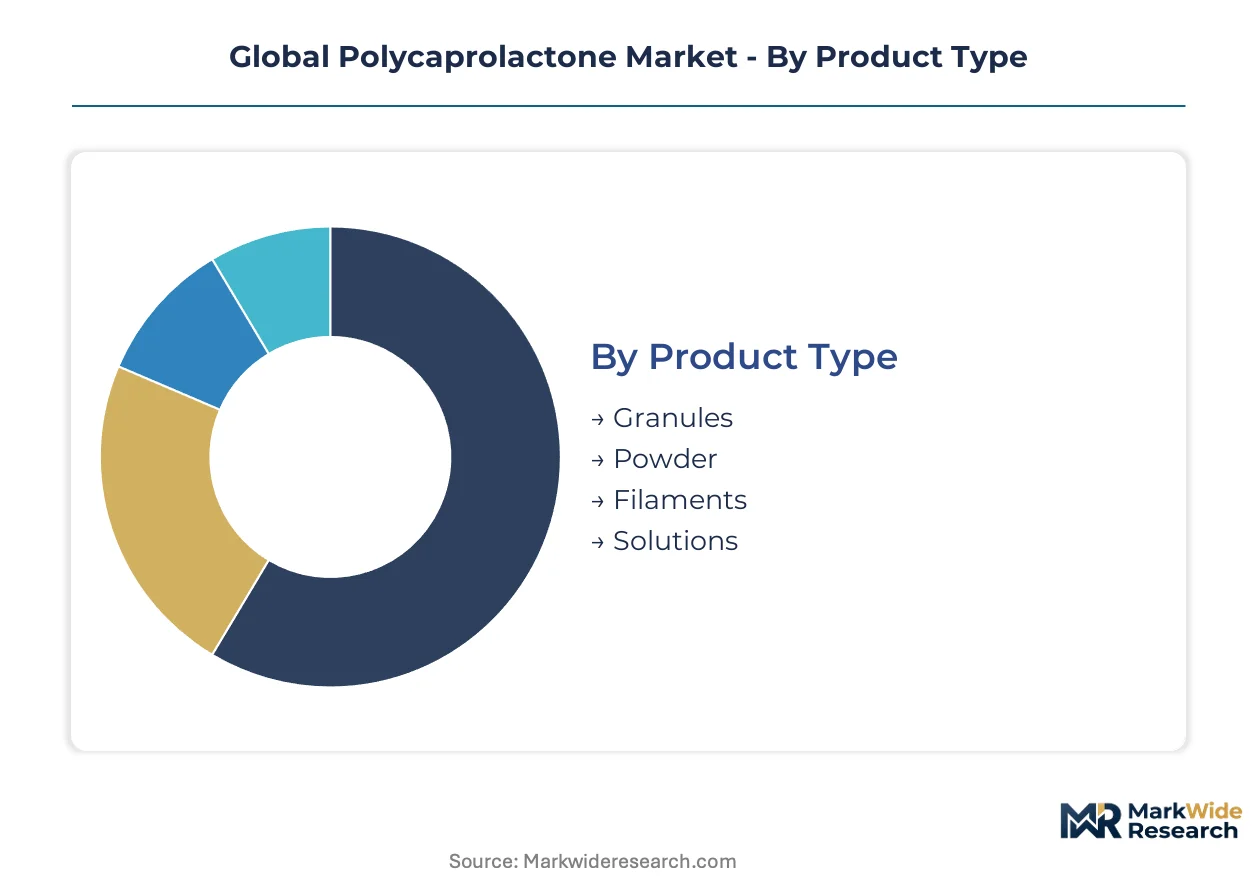
Polycaprolactone's commercial structure fragments across four intersecting dimensions, with certification requirements and processing characteristics determining margin capture. ISO 10993 biocompatibility tiers, compostability standards, and additive manufacturing feedstock qualifications create distinct pricing architectures within each category.
Product Type:
ISO 10993 certification burdens concentrate in biomedical-grade outputs, while industrial composting standards govern packaging-oriented forms. FDA device master file protocols and REACH registration requirements split validation timelines across pharmaceutical versus consumer applications.
- Granules:Semi-crystalline pellets with molecular weights ranging from 25,000 to 80,000 g/mol serve injection molding and extrusion lines. Medical device OEMs in Germany and Japan specify sub-ppm residual catalyst grades for long-acting drug delivery matrices, absorbing extended purification costs.
- Filaments:Diameter-controlled spools for fused deposition modeling, typically 1.75mm or 2.85mm, require tight ovality tolerances. Shenzhen and Shanghai-based desktop printer users drive filament-grade expansion through manufacturer-direct e-commerce channels, bypassing traditional industrial distribution.
- Powder:Fine particulate grades for solvent casting and powder metallurgy binders.
- Solutions:Solvent-dissolved PCL for dip-coating and electrospinning nanofiber production.
Leading the category by volume: Granules. Growing fastest: Filaments.
Application:
End-use differentiation separates premium-certified biomedical streams from commodity-compostable packaging volumes, with coating and textile segments occupying intermediate margin positions.
- Biomedical:Sutures, tissue engineering scaffolds, and controlled-release pharmaceutical matrices exploit PCL's tunable hydrolytic degradation matched to tissue regeneration timelines. FDA and EMA dual-certification requirements sustain pricing premiums for implant-grade material.
- Packaging:Industrial compostable films and food-contact layers compete against PLA on cost, with China's GB standards and SAMR supervision redirecting domestic capacity toward certified output.
- Coatings:Protective and functional layers for textiles and paper substrates.
- Textiles:Biodegradable fibers and nonwoven fabrics for hygiene and agricultural applications.
Highest margin concentration: Biomedical. Steepest expansion trajectory: Packaging.
End User:
Procurement authority fragments across specialized implant manufacturers and consolidated pharmaceutical packaging houses, reshaping contract structures and volume commitments.
- Medical Devices:Orthopedic and cardiovascular implant manufacturers require batch-to-batch molecular weight consistency for validated release profiles. CDSCO regulations in India are emerging as a qualification pathway for new supplier entry.
- Consumer Goods:Compostable cutlery, bags, and disposable tableware drive volume but compress margins against PLA substitution.
- Automotive Parts:Interior trim and temporary assembly fixtures leveraging biodegradability.
- Industrial Applications:Molding compounds and adhesive formulations for tooling and manufacturing aids.
Contract consolidation: Medical Devices. Volume scaling: Consumer Goods.
Form:
Processing methodology and final property requirements determine supply chain configuration, with thermoplastic and 3D printing grades commanding distinct qualification protocols.
- Thermoplastic:Meltable pellets and sheets for conventional processing equipment exploit PCL's low glass transition temperature near minus 60 degrees Celsius for flexible, tough finished parts. German automotive suppliers and Japanese electronics houses specify this form for temporary manufacturing fixtures.
- 3D Printing Material:Filament and photocurable oligomer grades for vat photopolymerization enable patient-specific dental and maxillofacial implants with degradation kinetics tuned to bone regeneration.
- Biodegradable Film:Blown and cast film structures for packaging and agricultural mulch.
- Coating:Liquid and powder formulations for surface protection and barrier functions.
Maturest supply base: Thermoplastic. Gaining share fastest: 3D Printing Material.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates polycaprolactone demand through its filament manufacturing clusters and domestic compostability mandates, while Germany and the United States anchor premium biomedical-grade consumption through implant manufacturing ecosystems.
China
Shenzhen and Shanghai-based desktop 3D printing users drive filament-grade consumption through manufacturer-direct e-commerce channels. GB standards for biodegradable plastics under SAMR supervision redirect domestic capacity toward certified film and coating grades. The Yangtze River Delta hosts scaling granule and filament output for packaging and additive manufacturing applications.
Germany
Medical device OEMs in Germany specify sub-ppm residual catalyst grades for long-acting drug delivery matrices, absorbing extended purification costs. REACH registration requirements for polymer intermediates mandate full substance identity dossiers, forcing non-EU producers to establish EU-based only representatives. The industrial cluster around Frankfurt and Düsseldorf concentrates injection molding and extrusion lines for automotive temporary fixtures.
United States
FDA device master file protocols shape market access timelines for surgical implant manufacturers requiring certified PCL grades for sutures and tissue scaffolds. The regulatory burden sustains pricing premiums for dual-certified biomedical material. Boston and Minneapolis metropolitan areas host orthopedic and cardiovascular implant manufacturing clusters seeking batch-to-batch molecular weight consistency.
Japan
PMDA oversight of absorbable polymers tightens material specifications for biodegradable implants, converging with evolving FDA guidance. METI industrial policy supports domestic production of high-purity grades for pharmaceutical packaging. The Nagoya and Osaka industrial corridors concentrate thermoplastic processing for electronics manufacturing fixtures leveraging PCL's low glass transition temperature.
India
CDSCO medical device regulations are emerging as a qualification pathway for new biodegradable polymer supplier entry into orthopedic and cardiovascular applications. Domestic implant manufacturing clusters seek qualified PCL suppliers as procurement authority fragments across specialized manufacturers. The Maharashtra and Gujarat industrial belts are developing compounding capacity for medical-grade formulations.
Global Polycaprolactone Market Competitive Landscape
Japanese and European producers anchor one tier through integrated petrochemical operations and captive caprolactone feedstock; Chinese specialists hold another through filament extrusion and direct e-commerce distribution. The vendor base splits between consolidated multinational chemical conglomerates with backward integration into monomer supply and fragmented domestic compounders serving regional additive manufacturing demand. Three archetypes dominate: integrated petrochemical majors controlling upstream epsilon-caprolactone production, biomedical-grade specialists absorbing ISO 10993 certification costs, and filament extruders leveraging digital distribution channels. Capacity expansion and strategic partnerships represent the dominant competitive moves as players seek to secure monomer supply and qualify for dual-jurisdiction regulatory compliance.
Within the integrated petrochemical tier, Daicel Corporation exemplifies upstream control through captive feedstock operations. Perstorp Holding AB and Shenzhen eSUN Industrial Co., Ltd occupy distinct positions—Perstorp represents European renewable raw material integration, while eSUN anchors Asia-Pacific filament distribution through manufacturer-direct channels. These three entities illustrate how geographic origin and structural positioning shape competitive differentiation without converging on identical capability sets.
| Leading Market Players |
|---|
| Daicel Corporation |
| Perstorp Holding AB |
| Corbion |
| BASF SE |
| Merck KGaA |
| Shenzhen Polymtek Biomaterial Co., Ltd |
| Shenzhen eSUN Industrial Co., Ltd |
| Durect Corporation |
| Haihang Industry Co., Ltd. |
| Others |
Supply & Pricing Matrix
Integrated petrochemical majors with captive epsilon-caprolactone operations anchor supply discipline and pricing power across polycaprolactone tiers. Daicel Corporation's upstream control over monomer feedstock translates directly into margin protection for biomedical-grade outputs, while merchant market volatility punishes non-integrated compounders.
Pricing Analysis
Volume concentrates in industrial packaging grades competing on industrial composting standards, while margin pools concentrate in ISO 10993-certified biomedical formulations. Three-tier pricing structure across premium implant-grade, standard thermoplastic, and economy filament levels reflects certification burden and molecular weight consistency requirements. Cost compression in packaging tiers intensifies because PLA substitution erodes PCL's cost position in single-use film. Pharmaceutical packaging houses exhibit lowest price sensitivity due to dual-jurisdiction regulatory qualification costs, while desktop 3D printing users drive hardest bargain through direct e-commerce comparison.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and European integrated producers controlling epsilon-caprolactone monomer output. Manufacturing concentrates in China, Germany, and Japan, with China scaling filament and granule capacity fastest. Raw material flows draw from petrochemical caprolactone streams, renewable feedstock experiments, and catalyst systems for ring-opening polymerization. Tariff exposure on biomedical-grade imports into the United States complicates dual-certification supply strategies. Distribution runs through manufacturer-direct digital channels for filament grades and long-term framework agreements for pharmaceutical volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epsilon-caprolactone supply concentration creates a structural capacity bottleneck that props pricing across all tiers, rewarding upstream control and punishing merchant market dependence.
For Market Incumbents: Cement monomer supply dominance through capacity additions in China and captive feedstock investments in Japan. PLA substitution in packaging threatens volume erosion; defend through backward integration into renewable raw materials per Perstorp's model. ISO 10993 certification investment remains the critical lever for premium-tier pricing power. For New Entrants and Emerging Players: CDSCO regulations in India open a window for qualified supplier entry into orthopedic and cardiovascular implant manufacturing clusters. Electrospinning nanofiber applications for wound dressing represent the most penetrable white-space target. Pursue direct e-commerce filament distribution to bypass entrenched industrial distributor relationships in Asia-Pacific. For Investors and Strategic Acquirers: Distressed-cycle entries favor biomedical-grade specialists with existing FDA device master file protocols in the United States and EU-based only representatives for REACH compliance. Long-term viability hinges on regulatory qualification moats widening faster than capital costs compound. Watch India's domestic implant manufacturing cluster formation as the inflection signal for regional supply repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Renewable Feedstock | Perstorp's model sustains European biodegradable film cost positions against petrochemical competitors. |
| ISO 10993 Certification Investment | Medical device OEMs in Germany and Japan demand sub-ppm residual catalyst grades for drug delivery matrices. |
| Direct E-Commerce Filament Distribution | Shenzhen eSUN bypasses traditional industrial channels to control Asia-Pacific desktop 3D printing feedstock access. |
| EU-Based Only Representative Establishment | Non-EU producers surrender REACH market access without local substance identity dossier representation. |
| Electrospinning Nanofiber Capacity Addition | Wound dressing producers adopt PCL matrices for controlled porosity and bioresorption timelines. |
Research Methodology
Multi-period observation of filament grade pricing spreads, regulatory filing timelines, and monomer spot market volatility anchored the trend analysis, supplemented by interviews with polymer plant managers, medical device procurement leads at German and Japanese OEMs, distribution channel partners in China, and technical R&D directors at integrated petrochemical majors. Secondary validation drew from REACH registration databases, FDA device master file protocols, Chinese customs trade data, and SEC filings of listed chemical conglomerates. Bottom-up volume modeling across product types and applications triangulated against top-down market sizing from regional production capacity assessments.
Segment-weighting approaches applied differential growth assumptions across biomedical, packaging, coating, and textile applications, with certification tier and end-use industry as cross-cutting dimensions. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs included caprolactone monomer supply forecasts, desktop 3D printer OEM qualification timelines, and evolving compostability standard adoption curves across jurisdictions.
The model assumes a particular technology adoption path for photocurable PCL oligomers in dental and maxillofacial applications; alternative pathways for vat photopolymerization systems would alter the outlook for filament versus resin demand splits. Forecasts reflect assumptions about regulatory convergence on biodegradability testing protocols and residual catalyst content thresholds that could shift with REACH or FDA guidance revisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Packaging Resins Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
Polypropylene Copolymer Market
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Liquid Saturated Polyester Resin Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Polyvinyl Chloride Resins Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market