
 South America Polyamide Market | 2026-2036
South America Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
South America Polyamide Market Insights
Brazil's petrochemical complex expansion in Camacari and Triunfo is narrowing the import dependency gap for caprolactam feedstock. Braskem leverages its integrated ethylene and benzene chain to supply regional polyamide producers with proximity advantages. BASF sustains compounding operations near Sao Paulo that anchor technical support for automotive tier ones. Domo Chemicals specializes in high-viscosity grades for film and fiber applications, occupying a defensible niche against commodity imports.
Polyamide denotes a class of thermoplastic polymers characterized by repeating amide linkages, with PA6 and PA66 dominating industrial grades due to their balance of tensile strength, thermal resistance, and processability via hydrolytic or continuous polymerization routes. The material serves primarily as a metal replacement in load-bearing automotive and machinery components where weight reduction and chemical resistance are critical. PA6 leads volume consumption across South America given its lower feedstock cost and established recycling infrastructure, while PA66 commands premium positioning in engine bay applications where heat aging requirements are stringent. Injection molding dominates the technology landscape for automotive and electronics parts, though extrusion retains importance in film and monofilament production for Brazil's agricultural and packaging sectors.
ANVISA, Brazil's national health surveillance agency, imposes migration limits on polyamide grades destined for food-contact applications, compelling compounders to maintain dual certification tracks for domestic and export markets. INMETRO's conformity assessment requirements for electrical and automotive components create compliance barriers that favor established suppliers with local testing capabilities. Argentina's IRAM standards for industrial plastics add another layer of specification complexity for cross-border trade. Stakeholders must monitor feedstock cost spreads between Asian caprolactam imports and prospective local adipic acid investments to determine optimal timing for capacity commitments.
Market Dynamics
Caprolactam feedstock localization in Brazil's petrochemical corridor is compressing import dependency and reshaping competitive positioning among compounders serving São Paulo's automotive cluster.
Growth Catalysts
- INMETRO energy efficiency labeling:Industrial material converters face mandatory performance thresholds that favor higher-grade engineered polymers over commodity alternatives in thermal management applications.
- Under-the-hood metal replacement:Automotive tier suppliers in Brazil's ABC Paulista region accelerate polyamide adoption for intake manifolds and engine covers to meet lightweighting mandates.
- Film and fiber grade specialization:Agricultural packaging demand across Argentina's Pampas grain belt sustains dedicated extrusion capacity for high-viscosity PA6 monofilament.
Market Restraints
- Adipic acid supply concentration:PA66 producers remain exposed to Asian import flows for hexamethylenediamine precursors, with no regional adipic acid capacity committed through 2030.
- ANVISA migration compliance:Dual certification tracks for food-contact polyamide grades add 8-12 month qualification timelines that deter opportunistic market entry.
- Recycled polyamide competition:Post-industrial PA6 regrind from Brazil's textile sector is displacing prime material in non-critical packaging applications.
Strategic Opportunities
- Chilean mining equipment aftermarket:Antofagasta and Calama maintenance hubs show underpenetrated demand for PA66 bushings and wear pads in haul truck suspension systems.
- Bio-based feedstock integration:Braskem's sugarcane-derived benzene chain offers pathway to renewable caprolactam for brand-owner sustainability commitments.
- Direct-to-compounder digital platforms:São Paulo-based distributors are piloting lot-traceable e-procurement for small-batch technical grades, bypassing traditional three-tier channel structures.
Industry Challenges
- Polymer processing technician scarcity:Brazil's SENAI vocational network graduates fewer than 400 certified injection molding specialists annually against industrial demand.
- IRAM-ANVISA standard misalignment:Cross-border compounders face redundant testing protocols when serving both Argentine industrial and Brazilian food-contact markets simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Polyamide Market |
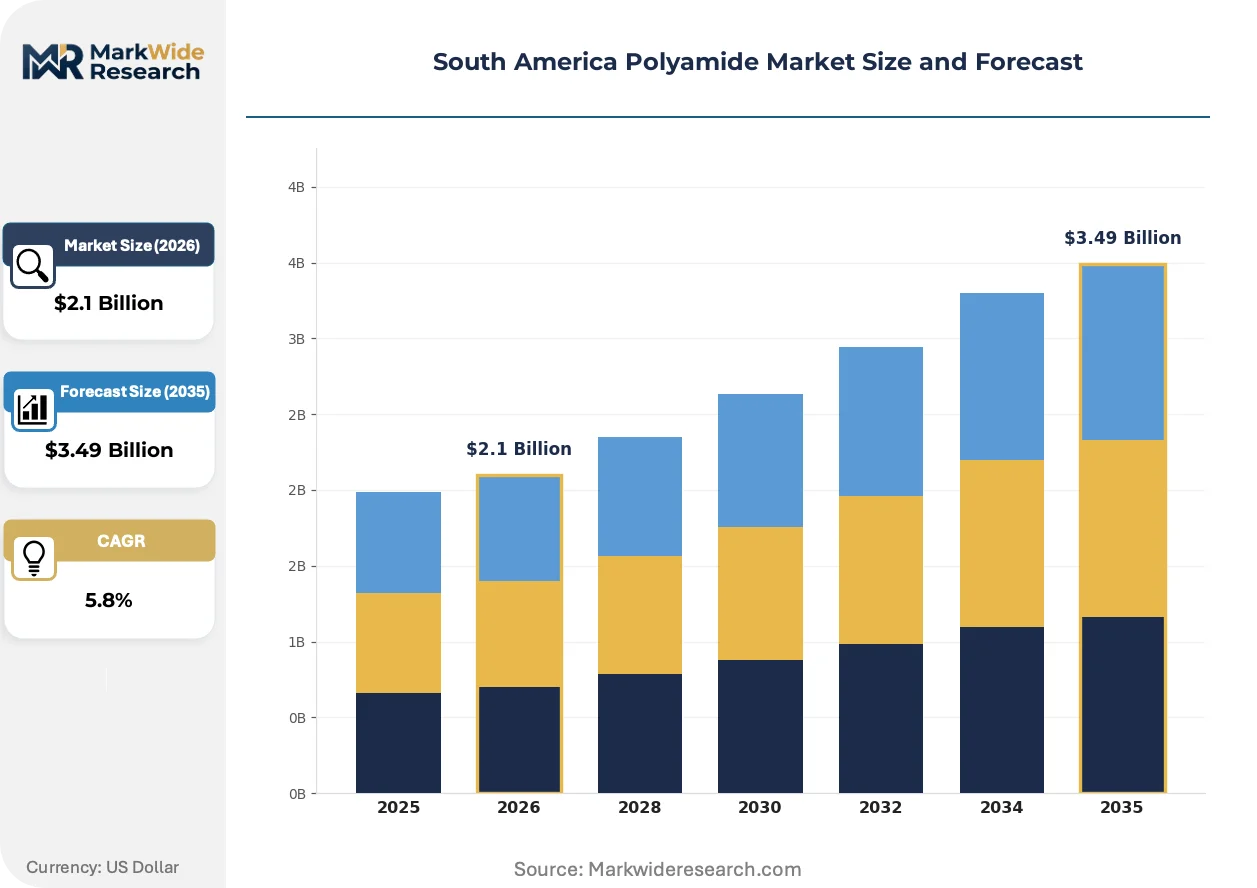
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA6, PA66, PA12, Others Application: Textiles, Automotive Components, Electronics, Industrial Machinery End User: Manufacturers, Retailers, Distributors, Exporters Technology: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | Braskem, UBE Corporation, BASF, Asahi Kasei Corporation, Domo Chemicals, Ascend Performance Materials, DSM-Firmenich, Envalior, RadiciGroup, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Polyamide Market Trends and Innovations
Hybrid material architectures and regulatory convergence are compressing traditional grade boundaries while digital procurement tools rewire distributor-compounder relationships across the continent.
Long-fiber reinforced polyamide is hybridizing conventional short-glass PA6 with continuous fiber thermoplastic tapes in hybrid overmolding cells. Automotive seating suppliers in Gravataí's Renault-Nissan cluster pilot these systems for seat pan structures. The technology is hybridizing metal-to-polyamide substitution economics by eliminating secondary assembly operations previously required for metal inserts.
ANVISA's updated food-contact polymer positive list is forcing compounders to retire legacy lubricant packages containing erucamide slip agents. Domestic packaging converters must reformulate film grades within 24 months or surrender certified supplier status to multinational rivals. Brazilian dairy film processors in Minas Gerais are accelerating qualification of alternative oleamide systems to maintain export eligibility.
Compounders now consolidate spot-buying of technical grades through integrated e-procurement platforms that bypass traditional distributor markups. Tier-two automotive suppliers in São Bernardo do Campo negotiate direct mill contracts for PA66 conditioned to 0.15% moisture specifications. Argentina's industrial buyers lag this shift by approximately 18 months due to FX settlement restrictions and IRAM documentation requirements.
South America Polyamide Market Segmentation
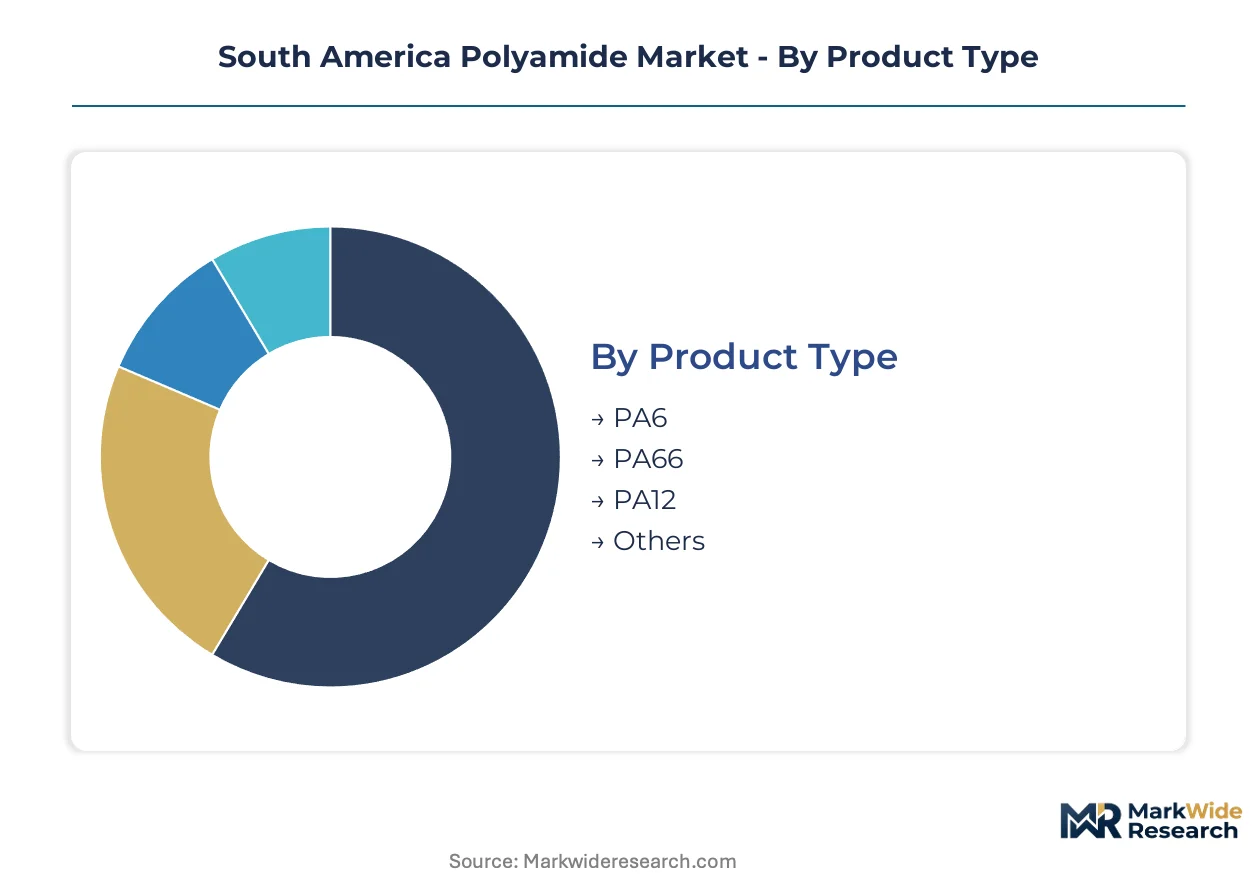
Segmentation of the South America polyamide market reveals how feedstock economics, processing infrastructure, and end-use performance requirements partition demand across distinct technical grades and conversion technologies. Each dimension carries implications for supplier positioning and margin capture.
Product Type:
Mature commodity grades dominate volume flows while specialty polymers carve defensible niches through specification premiums.
- PA6:Polymerized via caprolactam ring-opening, this grade offers lower crystallinity and easier processability than higher-performance alternatives. Brazilian automotive suppliers in São Bernardo do Campo favor PA6 for non-structural under-hood components where thermal loads remain moderate. INMETRO energy efficiency labeling for industrial equipment reinforces PA6 adoption in thermal management housings.
- PA66:Formed through condensation of adipic acid and hexamethylenediamine, PA66 delivers superior heat deflection temperature and dimensional stability. Argentina's IRAM-certified industrial machinery producers specify PA66 for continuous-use bearings and gears in Pampas grain processing equipment. Import dependency for adipic acid precursors constrains regional supply security.
- PA12:Long-chain aliphatic structure provides exceptional moisture resistance and chemical compatibility for fuel system applications.
- Others:Bio-based polyamides and high-temperature aromatic grades serve emerging sustainability mandates and aerospace prototyping.
PA6 retains volume leadership; PA12 holds the steepest expansion curve.
Application:
End-use concentration tracks Brazil's industrial corridor density and Argentina's agricultural machinery base.
- Textiles:PA6 filament yarn dominates Brazil's carpet backing and industrial cordage sectors. São Paulo state's textile recycling infrastructure generates post-industrial regrind that competes with prime resin in non-critical applications.
- Automotive Components:Metal replacement drives intake manifolds, engine covers, and cooling system modules. Gravataí's Renault-Nissan cluster sources conditioned PA66 for under-hood applications requiring 150°C continuous service temperature.
- Electronics:Connectors and circuit breaker housings demand flame-retardant compounded grades.
- Industrial Machinery:Wear-resistant gears and bushings serve mining and agricultural equipment maintenance.
Automotive Components commands the largest value share; Electronics shows the most rapid specification upgrading.
End User:
Channel structure varies by batch size requirements and technical support intensity.
- Manufacturers:Tier-one automotive and appliance OEMs negotiate direct mill contracts with moisture-conditioned material guarantees.
- Retailers:Small-batch distributors serve maintenance-repair-overhaul segments with standardized grades.
- Distributors:São Paulo-based compounders maintain regional warehouse stocks for just-in-time delivery to ABC Paulista processors.
- Exporters:ANVISA-certified suppliers ship food-contact film grades to Mercosur partners under harmonized technical regulations.
Manufacturers capture the highest volume throughput; Exporters face the most complex certification burden.
Technology:
Processing method selection depends on part geometry complexity and production scale economics.
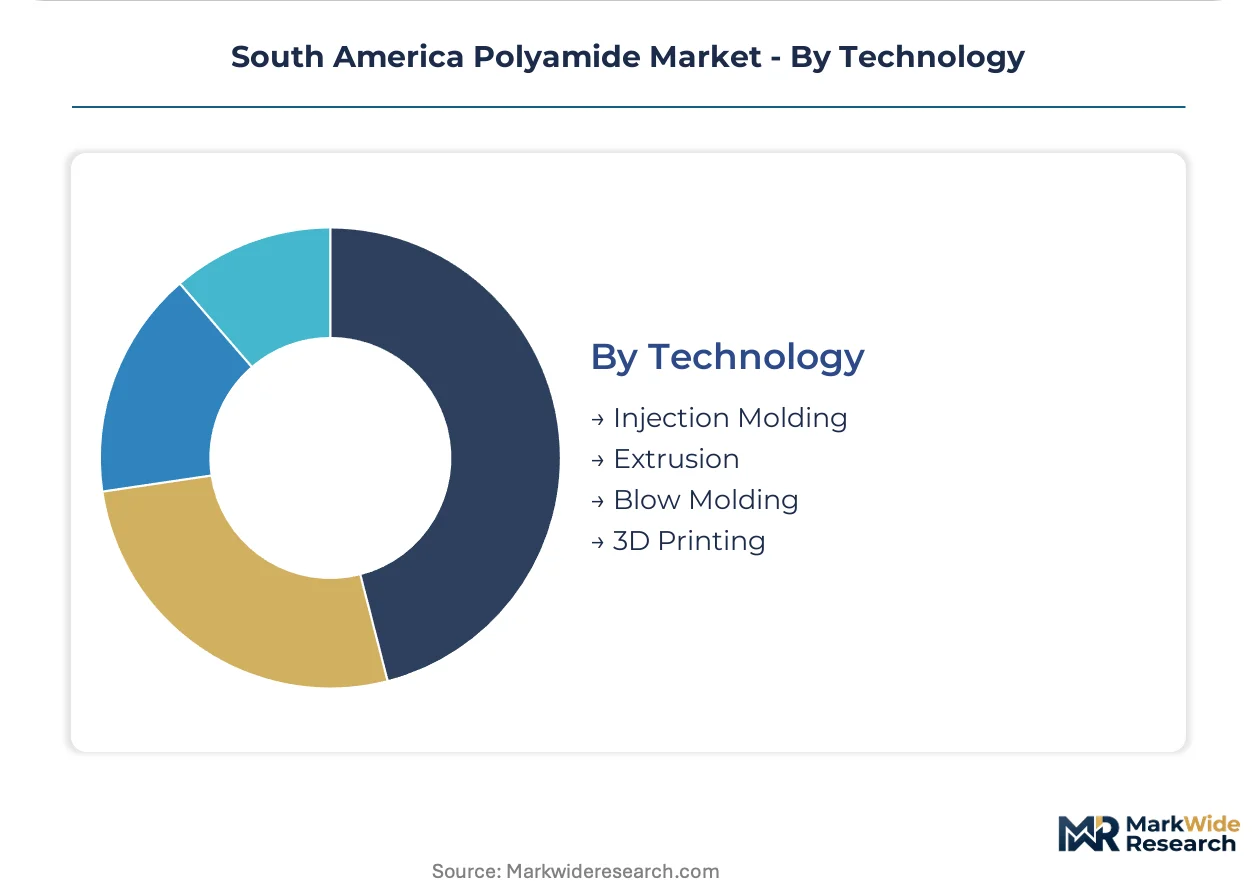
- Injection Molding:Dominates automotive and electronics part fabrication with cycle times under 60 seconds for complex geometries. São Paulo's SENAI vocational network struggles to graduate sufficient certified technicians for multicavity mold operation.
- Extrusion:Produces film, sheet, and monofilament for Brazil's agricultural packaging sector. High-viscosity PA6 grades from Domo Chemicals anchor specialty film applications in Minas Gerais dairy processing.
- Blow Molding:Limited penetration for hollow structural components and fuel tanks.
- 3D Printing:Emerging filament supply for prototyping and spare part digital warehousing in Chilean mining districts.
Injection Molding retains equipment count leadership; 3D Printing demonstrates the most rapid capability expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Santos Port petrochemical terminal anchors Brazil's polyamide import and distribution network, handling caprolactam feedstock flows that supply São Paulo's compounding corridor.
Brazil
Automotive tier suppliers in São Bernardo do Campo expand PA66 consumption for under-hood components as INMETRO energy efficiency labeling mandates favor engineered polymers over commodity substitutes. Braskem's integrated Camacari petrochemical complex narrows import dependency for benzene-derived feedstocks. São Paulo state's ABC Paulista automotive cluster sources conditioned polyamide grades for intake manifold and engine cover applications.
Argentina
Grain processing equipment manufacturers across the Pampas belt sustain demand for IRAM-certified PA66 bearings and gears in continuous-use agricultural machinery. The national industrial standards body enforces specification complexity that favors established compounders with local testing capabilities. Córdoba's agricultural machinery assembly plants specify wear-resistant grades for harvester and silo equipment components.
Chile
Antofagasta and Calama mining maintenance hubs generate underpenetrated demand for PA66 bushings and wear pads in haul truck suspension systems. The country's mining regulator maintains equipment safety standards that drive specification upgrading in aftermarket components. Northern Chile's copper extraction districts concentrate procurement for high-load polyamide replacement parts.
Colombia
Packaging converters in Bogotá's industrial zone adopt PA6 film grades for food-contact applications subject to national health surveillance migration limits. The country's standards and certification body enforces conformity assessment requirements that create compliance barriers for opportunistic suppliers. Medellín's textile sector generates post-industrial regrind that competes with prime resin in non-critical applications.
South America Polyamide Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with feedstock and compounding capabilities. The South America polyamide market structures around three archetypes: integrated petrochemical producers with captive benzene supply, regional compounders with technical service proximity to automotive clusters, and specialty grade importers serving niche film and fiber applications. Consolidation pressure concentrates among compounders seeking scale economies in São Paulo's logistics radius, while differentiation competition intensifies around bio-based feedstock certification and ANVISA food-contact compliance.
Among integrated petrochemical producers, Braskem anchors the feedstock security tier with its Brazilian ethylene and benzene chain. BASF and Domo Chemicals occupy positions within the regional compounding and specialty grade segments, representing distinct strategic archetypes—BASF with technical service infrastructure near São Paulo automotive customers, Domo Chemicals with high-viscosity grade specialization for film and fiber end-uses. These three exemplify how geographic proximity to demand clusters and feedstock integration depth determine competitive positioning.
| Leading Market Players |
|---|
| Braskem |
| UBE Corporation |
| BASF |
| Asahi Kasei Corporation |
| Domo Chemicals |
| Ascend Performance Materials |
| DSM-Firmenich |
| Envalior |
| RadiciGroup |
| Others |
Pricing and Supply Chain Analysis
Caprolactam concentration in Brazil's Camacari and Triunfo petrochemical corridor anchors feedstock security for São Paulo compounders, compressing import dependency and shifting margin pools toward integrated producers with captive benzene supply chains.
Pricing Analysis
ANVISA migration compliance dictates the pricing tier structure across South American polyamide markets, separating ANVISA-certified food-contact grades from industrial-only alternatives. Three-tier pricing structure across premium certified, standard industrial, and economy regrind levels tracks certification investment and testing burden. Cost compression in standard PA6 grades is intensifying because Brazil's textile sector floods non-critical packaging with post-industrial regrind. Small-batch agricultural converters in Argentina's Pampas belt show highest price sensitivity, while tier-one automotive suppliers in São Bernardo do Campo prioritize moisture-conditioned material guarantees over unit cost.
Supply Chain Analysis
Extended payment terms from São Paulo distributors to ABC Paulista automotive processors are compressing working capital cycles across the conversion tier. Geographic supply concentrates in Brazil, Argentina, and Chile, with Brazilian petrochemical corridors feeding regional compounders. Raw material dependencies center on caprolactam, adipic acid, and hexamethylenediamine precursors. Single-source vulnerability persists for adipic acid, with no regional capacity committed through the projection horizon. Distribution runs through São Paulo-based compounders maintaining regional warehouse stocks for just-in-time delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyamide incumbents face substitution defense against long-fiber reinforced thermoplastic composites and recycled polymer regrind, requiring strategic positioning around certification moats and feedstock integration.
For Market Incumbents: Build regulatory certification moats by accelerating ANVISA food-contact positive list compliance ahead of the 24-month reformulation deadline. Deepen backward integration into caprolactam production to match Braskem's integrated ethylene-benzene chain economics. Acquire distressed extrusion capacity in Minas Gerais dairy film processing to consolidate position against Domo Chemicals' high-viscosity specialization.
For New Entrants and Emerging Players: Build out direct-to-compounder digital procurement platforms targeting São Bernardo do Campo tier-two automotive suppliers with lot-traceable technical grades. Chilean mining equipment aftermarket in Antofagasta and Calama offers the most penetrable white-space for PA66 bushings and wear pads. Pursue ANVISA certification as the primary go-to-market angle to bypass commodity regrind competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed regional compounders lacking feedstock integration but holding ANVISA certification and São Paulo logistics radius. Long-term viability across the analysis window favors integrated producers with captive benzene supply and technical service proximity to automotive clusters. Monitor feedstock cost spreads between Asian caprolactam imports and prospective local adipic acid investments as the inflection signal for capacity commitment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Braskem's integrated ethylene-benzene chain demonstrates feedstock security advantages for regional producers. |
| ANVISA Certification Investment | Food-contact positive list compliance creates 8-12 month qualification barriers against opportunistic importers. |
| Direct-to-Compounder Digital Platform | São Paulo distributors pilot lot-traceable e-procurement bypassing traditional three-tier channel markups. |
| Chilean Mining Aftermarket Expansion | Antofagasta and Calama maintenance hubs show underpenetrated demand for PA66 haul truck components. |
| High-Viscosity Grade Specialization | Domo Chemicals anchors defensible film and fiber niche against commodity PA6 imports in agricultural packaging. |
Research Methodology
Initial hypotheses were tested against primary input from polyamide plant managers, automotive tier-one procurement leads, distribution channel partners, and technical R&D directors, and refined through secondary validation against customs and trade data, ACC and Plastics Europe reports, SEC 10-K filings from listed petrochemical producers, and ANVISA regulatory filings. Bottom-up volume estimates from end-use consumption patterns were triangulated against top-down feedstock capacity assessments across the analysis window.
Demand-supply balance dynamics anchored the analytical framework throughout the projection horizon, with segmentation modeled across product grade tier, end-use industry, conversion technology, and regional production hub. CAGRs were derived from trend extrapolation of historical consumption patterns adjusted for announced capacity additions and regulatory mandate timelines. Key inputs included INMETRO energy efficiency labeling adoption curves, automotive lightweighting content-per-vehicle trajectories, and ANVISA compliance cost burdens.
Stress conditions across caprolactam import price volatility, adipic acid supply disruption, and ANVISA regulatory timeline compression were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about feedstock localization progress and regulatory enforcement intensity. Macroeconomic deviation, regulatory acceleration, or bio-based feedstock technological breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Methyl Silicone Resins Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Australia Engineering Plastics Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Global Acrylic Solid Surface Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Agar Resin Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
Global One Component Polyurethane Foam Market