
 Floor Adhesive Market | 2026-2036
Floor Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Adhesive Market Intelligence
Specialty distribution through flooring contractor supply houses is rewriting procurement patterns in the adhesive trade. Henkel AG leverages its global manufacturing footprint to sustain bulk supply agreements with national flooring chains. Sika AG anchors its position through specification relationships with commercial builders seeking warranty-backed installation systems. MAPEI S.p.A. differentiates by specializing in epoxy and polyurethane formulations for heavy-traffic environments.
Floor adhesive comprises bonding agents formulated from synthetic resins, fillers, and additives, designed to achieve specific shear strength and open-time parameters for substrate attachment. These products serve the essential commercial purpose of creating durable, dimensionally stable bonds between flooring materials and underlying subfloors across residential, commercial, and industrial construction. Water-based adhesives lead volume due to regulatory alignment and indoor air quality mandates, while polyurethane commands premium positioning in moisture-prone applications. Epoxy systems represent the fastest-growing structural category for industrial and healthcare installations where chemical resistance and load-bearing performance justify higher material costs.
EPA VOC regulations in the United States, REACH in Europe, and state-level air quality standards in California shape permissible solvent content and drive low-emission formulation investment. BIS certification requirements in India and GB standards in China further fragment compliance obligations for multinational suppliers. Stakeholders must monitor evolving chemical restriction schedules and building code harmonization efforts to anticipate reformulation costs and regional product registration timelines.
Market Dynamics
EU F-Gas Regulation and REACH compliance frameworks are forcing wholesale reformulation across adhesive portfolios, compressing solvent-based margins while elevating water-based and hybrid chemistries in specification pipelines. Commercial builders in healthcare and hospitality now demand warranty-backed installation systems that lock in multi-year supply relationships.
Growth Catalysts
- Green building certification mandates:LEED and BREEAM point systems reward low-VOC adhesive specification, pulling volume toward water-based acrylic and hybrid polymer formulations in commercial construction.
- Healthcare infrastructure expansion:Hospital renovation cycles and infection-control flooring upgrades in Germany, France, and the Netherlands are expanding epoxy and polyurethane adhesive procurement for seamless, chemical-resistant surfaces.
- Moisture-barrier technology maturation:Single-step adhesive systems combining bonding and vapor protection are displacing multi-layer subfloor preparation in basement and ground-level residential applications.
Market Restraints
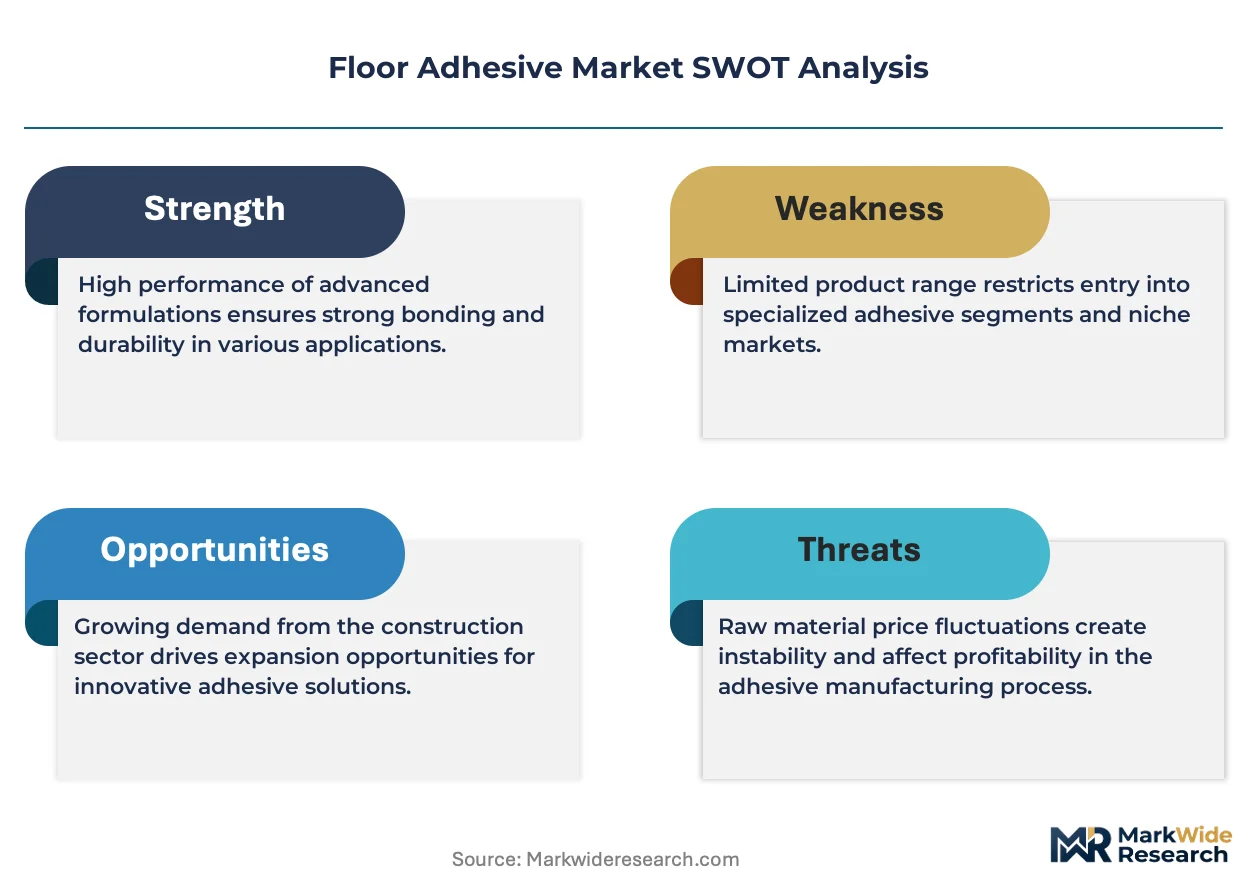
- Petrochemical feedstock volatility:Polyol and isocyanate price swings squeeze polyurethane adhesive margins, forcing reformulation toward bio-based alternatives with unproven long-term performance data.
- Regional supply concentration:Specialty epoxy resin production clusters in the Rhine-Ruhr industrial corridor create geographic vulnerability for European specification-grade adhesive supply.
- Technical curing limitations:Water-based adhesives require extended open times and controlled humidity conditions that conflict with fast-track commercial construction schedules.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland renovation rates lag Germany by 40 percent, presenting white space for low-temperature-curing adhesive systems adapted to subarctic construction windows.
- Regulatory tailwind from EU Green Deal:Carbon border adjustment mechanisms and embodied carbon scoring in public procurement favor locally manufactured, bio-content adhesives with verified lifecycle data.
- Direct-to-contractor digital platforms:Flooring installer networks in the Netherlands are bypassing traditional distribution through specialized e-procurement portals that aggregate small-batch orders.
Industry Challenges
- Certification timeline compression:CE marking and harmonized European Technical Assessment pathways for novel bio-based chemistries extend product launch cycles by 18-24 months versus conventional formulations.
- Installer skill stratification:Specification-grade epoxy and polyurethane application demands trained certification that smaller flooring contractors struggle to resource, creating execution gaps in warranty-backed installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Adhesive Market |
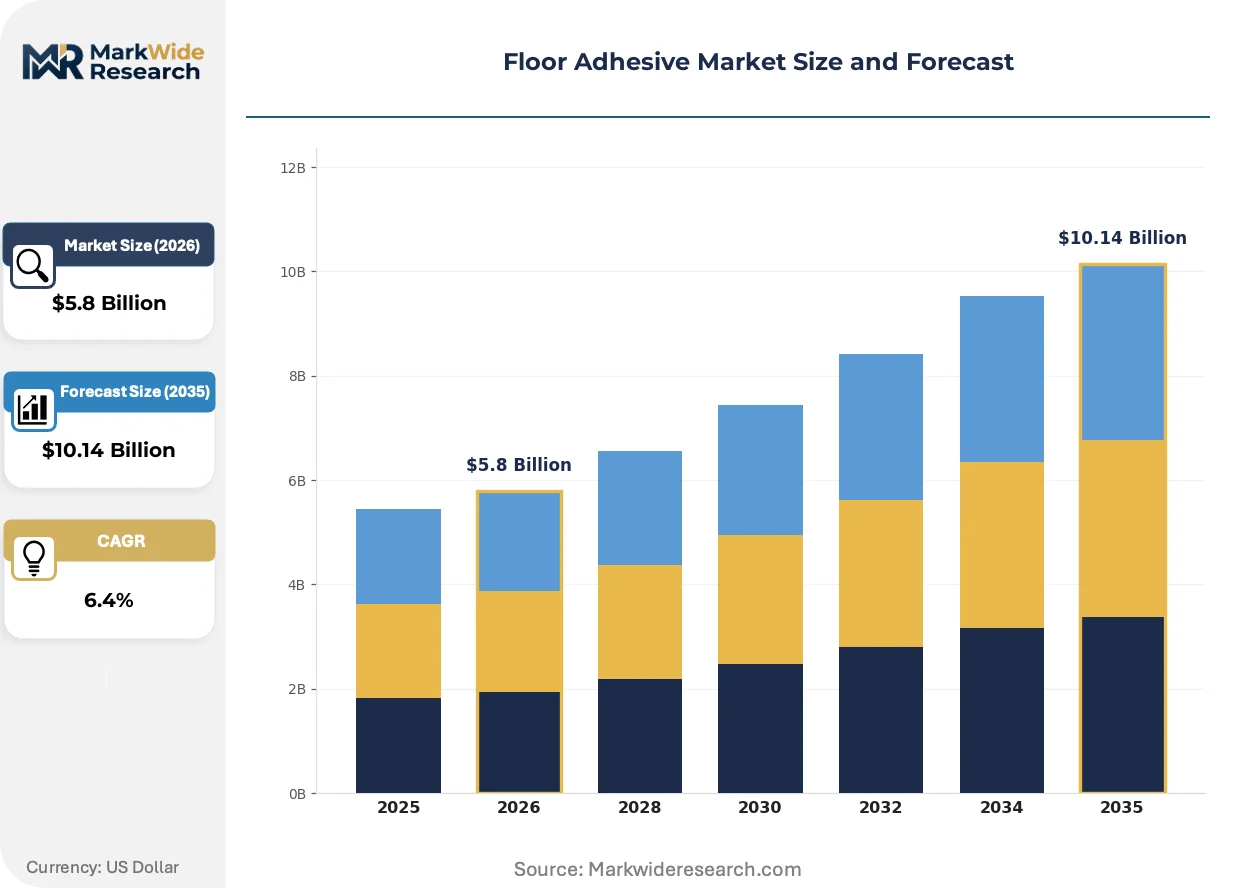
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Epoxy, Polyurethane, Acrylic Application: Vinyl Flooring, Wood Flooring, Tile Flooring, Carpet Installation, Laminate Flooring End User: Homeowners, Flooring Contractors, Commercial Builders, Facility Managers, DIY Enthusiasts Packaging Type: Buckets, Tubes, Cans, Squeeze Bottles, Cartridges |
| Companies Covered | Henkel AG, Sika AG, MAPEI S.p.A., H.B. Fuller Company, Arkema (Bostik SA), BASF SE, Pidilite Industries Limited, ARDEX GmbH, Dow Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Adhesive Market Strategic Shifts & Innovations
Digital tools are penetrating adhesive specification and application workflows, compressing information asymmetry between manufacturers and end-users while enabling predictive performance modeling. Reformulation chemistry and supply chain transparency are simultaneously advancing under regulatory pressure.
Smart dispensing systems equipped with RFID-enabled cartridges are digitizing on-site adhesive consumption tracking. Large commercial flooring contractors in Germany and France are piloting these systems to automate inventory replenishment and document installation parameters for warranty claims. This technology is digitizing quality assurance workflows while creating data assets that manufacturers leverage for predictive formulation refinement.
REACH Annex XVII restrictions on isocyanate content in professional-grade products are accelerating aliphatic polyurethane and silane-terminated polymer development. Adhesive formulators must revalidate shear strength and open-time specifications under tightened occupational exposure limits. Industrial and healthcare segments in Belgium and the Netherlands are absorbing premium pricing for compliant systems to maintain installation crew certification.
Specification authority is migrating from general contractors to flooring installer cooperatives with direct manufacturer relationships. These networks in Austria and Switzerland aggregate project volume to negotiate project-specific pricing and technical support packages. Hospitality and senior living developers in these markets now route adhesive selection through installer-engineered system warranties rather than architect specifications.
Floor Adhesive Market Segmentation
Segmentation in floor adhesives reveals how formulation chemistry, installation method, and buyer sophistication create distinct commercial battlegrounds. Each dimension carries different margin profiles, certification requirements, and supply chain configurations that shape competitive positioning.
Product Type:
Mature water-based systems dominate volume while emerging bio-based hybrids capture specification attention in green building pipelines.
- Water-Based:Acrylic and vinyl acetate copolymer emulsions serve residential and light commercial installation where indoor air quality mandates restrict solvent content. German renovation contractors specify these for LEED and BREEAM point accumulation in multi-family housing retrofits.
- Solvent-Based:Synthetic rubber and neoprene formulations retain niche positioning in outdoor and high-moisture transition zones where rapid tack development outweighs VOC exposure concerns. REACH Annex XVII restrictions compress professional-grade availability to specialized industrial maintenance channels.
- Epoxy:Two-part thermosetting systems deliver chemical resistance and load-bearing performance for healthcare and food processing environments.
- Polyurethane:Moisture-curing isocyanate-terminated prepolymers anchor premium positioning in subfloor vapor protection applications.
- Acrylic:Pressure-sensitive and hard-setting variants serve carpet and resilient flooring attachment with forgiving open-time windows for less skilled installers.
Water-Based handles the majority of throughput; Epoxy is climbing the fastest on specification share.
Application:
Volume concentrates in flooring categories with standardized installation protocols and recurring maintenance cycles.
- Vinyl Flooring:Luxury vinyl tile and sheet goods demand high-tack, fast-grab adhesives that accommodate floating and fully bonded methods. Hospital renovation programs in the Netherlands specify antimicrobial-grade systems for seamless sheet installation in operating theaters.
- Wood Flooring:Engineered and solid hardwood installation requires moisture-barrier-integrated adhesives that accommodate seasonal expansion. Belgian contractors favor silane-modified polymer systems for basement and ground-level applications with elevated subfloor vapor emission.
- Tile Flooring:Cementitious and epoxy thin-set mortars serve ceramic and stone attachment with shear strength requirements that exceed resilient flooring standards.
- Carpet Installation:Pressure-sensitive and releasable adhesives accommodate commercial tenant improvement cycles with reduced subfloor damage on removal.
- Laminate Flooring:Click-lock floating systems have displaced adhesive attachment in residential segments, compressing demand to specialized acoustic underlayment bonding.
Vinyl Flooring commands the largest adhesive volume; Wood Flooring is expanding most quickly on moisture-barrier system adoption.
End User:
Buyer sophistication stratifies between specification authority holders and price-sensitive volume purchasers.
- Homeowners:Small-batch retail purchases through home improvement centers prioritize convenience packaging and forgiving application windows over technical performance metrics.
- Flooring Contractors:Trade supply house procurement concentrates on bulk pricing, warranty backing, and manufacturer technical support availability for installation crew training.
- Commercial Builders:General contractors and construction managers specify adhesive systems through architect-engineered master specifications with locked-in supply agreements for multi-phase developments.
- Facility Managers:Maintenance and renovation departments in healthcare, education, and hospitality institutions prioritize rapid-cure systems that minimize operational downtime.
- DIY Enthusiasts:Online and retail channel purchases respond to video tutorial compatibility and pre-mixed convenience formulations with extended shelf stability.
Flooring Contractors move the highest adhesive tonnage; Commercial Builders are gaining specification authority fastest through warranty-backed installation system procurement.
Packaging Type:
Container format aligns with application scale, jobsite logistics, and product rheology requirements.
- Buckets:Bulk pail packaging serves commercial flooring crews with high-volume trowel application of water-based and acrylic adhesives.
- Tubes:Squeeze tube formats accommodate repair, transition strip, and detail work with controlled dispensing for small-area bonding.
- Cans:Metal canisters package solvent-based contact cements and specialty formulations requiring oxygen exclusion for shelf stability.
- Squeeze Bottles:Precision-tip containers target DIY wood flooring and laminate installation with metered bead application.
- Cartridges:Caulk-gun compatible cartridges enable two-part epoxy and polyurethane dispensing with static mixing nozzles for on-site ratio control.
Buckets carry the majority of commercial volume; Cartridges are advancing fastest on two-part system specification growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance anchors European adhesive demand, with renovation cycles and green building certification creating concentrated procurement in Germany, France, and the Netherlands. Healthcare infrastructure investment and moisture-barrier technology maturation pull specification-grade volume toward water-based and epoxy systems.
Germany
Hospital renovation programs in Berlin and Hamburg expand epoxy adhesive procurement for seamless, chemical-resistant flooring. EU F-Gas Regulation and REACH Annex XVII restrictions compress solvent-based availability while elevating water-based acrylic specifications. The Rhine-Ruhr industrial corridor clusters specialty epoxy resin production, creating geographic concentration for European specification-grade supply.
France
Healthcare infrastructure expansion in Paris and Lyon drives antimicrobial-grade adhesive specification for operating theater installations. ECHA occupational exposure limits on isocyanate content accelerate aliphatic polyurethane development. Smart dispensing systems with RFID-enabled cartridges pilot in large commercial flooring contractor networks, digitizing inventory replenishment and warranty documentation.
United States
EPA VOC regulations and California state-level air quality standards shape permissible solvent content, driving low-emission formulation investment across residential and commercial construction. Moisture-barrier-integrated adhesives gain traction in basement and ground-level applications in the Southeast and Midwest. Fast-track commercial construction schedules in Texas and Florida conflict with water-based adhesive curing limitations.
Netherlands
Flooring installer cooperatives in Amsterdam and Rotterdam aggregate project volume to negotiate project-specific pricing and technical support packages. Direct-to-contractor digital platforms bypass traditional distribution channels for small-batch order aggregation. REACH compliance frameworks position Dutch contractors as early adopters of silane-terminated polymer systems for moisture-prone subfloor applications.
India
BIS certification requirements fragment compliance obligations for multinational suppliers entering residential and commercial construction markets. Urban infrastructure development in Mumbai and Delhi-NCR expands specification-grade adhesive procurement for multi-phase developments. Green building certification adoption lags European rates, compressing premium water-based formulation penetration.
Floor Adhesive Market Key Industry Players
Diversified chemical conglomerates and specialty construction chemical manufacturers split the market between scale-driven supply security and specification-grade technical service. The vendor base concentrates around three strategic archetypes: global adhesive portfolios with flooring-specific divisions, construction chemical specialists with installation system integration, and regional formulators with price-competitive water-based lines. Competitive dynamics center on multi-year supply agreements with national flooring chains and warranty-backed installation system procurement by commercial builders.
Within the diversified chemical conglomerate tier, Henkel AG and BASF SE anchor positions through global manufacturing footprints that sustain bulk supply agreements. Sika AG and MAPEI S.p.A. exemplify the construction chemical specialist archetype, occupying positions anchored through specification relationships and heavy-traffic formulation expertise. These named entities represent the competitive tension between scale-driven supply security and technical service depth that shapes procurement patterns across healthcare, hospitality, and residential renovation segments.
| Leading Market Players |
|---|
| Henkel AG |
| Sika AG |
| MAPEI S.p.A. |
| H.B. Fuller Company |
| Arkema (Bostik SA) |
| BASF SE |
| Pidilite Industries Limited |
| ARDEX GmbH |
| Dow Inc |
| Others |
Cost & Logistics Intelligence
Petrochemical feedstock volatility in polyurethane raw materials determines both the widening spread between specification-grade and commodity adhesive tiers and the geographic clustering of resin production capacity. Polyol and isocyanate price swings compress margins on moisture-curing systems while concentrating supply chain leverage with Rhine-Ruhr corridor manufacturers who control specialty epoxy resin output.
Pricing Analysis
Configured-to-order pricing for warranty-backed installation systems commands substantial premiums over standard water-based formulations. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade epoxy systems with CE marking and installer certification from bulk acrylic emulsions sold through retail channels. Price differentiation rests on REACH compliance tier and volume scale, with commercial builders in healthcare absorbing premium pricing for aliphatic polyurethane to maintain crew certification. Cost compression in solvent-based tiers is intensifying because REACH Annex XVII restrictions compress professional-grade availability.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities have become standard in flooring contractor procurement, with Dutch installer cooperatives leveraging aggregated volume for 90-day terms. Geographic supply concentration centers on Germany, Belgium, and the Netherlands for specialty resin production, with raw material dependencies on petrochemical feedstocks, epoxy curing agents, and silane-terminated polymer intermediates. Single-source vulnerability runs through Rhine-Ruhr specialty epoxy clusters. Distribution runs through flooring contractor supply houses and direct-to-contractor digital platforms bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where installation system warranties and crew certification programs expand faster than base adhesive volume. Technical support bundling and predictive maintenance contracts for smart dispensing systems represent the fastest-growing recurring revenue layer.
For Market Incumbents: Harden specification relationships with commercial builders by embedding RFID-enabled cartridge systems into multi-year supply agreements. Deepen backward integration into specialty epoxy resin production to defend against Rhine-Ruhr supply concentration risks. Invest in aliphatic polyurethane R&D ahead of tightened ECHA occupational exposure limits.
For New Entrants and Emerging Players: Establish a beachhead in Nordic renovation markets where low-temperature-curing systems face underpenetrated demand. Target Swedish and Finnish flooring contractors with silane-modified polymer formulations adapted to subarctic construction windows. Route go-to-market through direct-to-contractor digital platforms that aggregate small-batch orders and bypass established distribution.
For Investors and Strategic Acquirers: Regional formulators with bio-based adhesive pipelines and verified lifecycle data represent the most attractive acquisition target archetype. Long-term viability in this market hinges on carbon border adjustment alignment and embodied carbon scoring in EU public procurement. Watch for CE marking timeline compression on novel bio-based chemistries as the inflection signal for portfolio restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resins | Captive supply of epoxy curing agents insulates margins from Rhine-Ruhr price volatility. |
| Smart Dispensing System Deployment | RFID-enabled cartridges digitize warranty documentation for German healthcare contractors. |
| Bio-Based Formulation Certification | Verified lifecycle data unlocks EU Green Deal procurement preference in public construction. |
| Installer Cooperative Partnership | Direct relationships with Dutch flooring networks bypass traditional distribution markups. |
| Low-Temperature Curing Development | Subarctic-adapted systems address 40 percent renovation rate gaps in Nordic markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical sector filings, Cefic industry reports, and ECHA regulatory databases. Primary interviews engaged adhesive formulators, flooring contractor procurement leads, commercial builder specification managers, and distribution channel partners across Germany, France, and the Netherlands. Secondary validation drew from REACH Annex XVII restriction schedules, BIS certification requirements, and EPA VOC compliance frameworks. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Forecast inputs span formulation chemistry, end-use industry, installation method, and regional regulatory cluster across the analysis window. Segmentation dimensions include water-based, solvent-based, epoxy, polyurethane, and acrylic product types; vinyl, wood, tile, carpet, and laminate applications; and homeowner, contractor, commercial builder, and facility manager end users. CAGRs were derived from regression analysis against renovation cycle data and green building certification adoption curves, incorporating petrochemical feedstock price elasticity and REACH compliance timeline impacts.
Stress conditions across polyol price volatility, CE marking approval delays, and Nordic market penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts assume documented regulatory trajectories and construction activity levels. Macroeconomic contraction, accelerated chemical restriction schedules, or breakthrough bio-based performance validation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Europe Automotive Adhesives and Sealants Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Asia-Pacific Urea-Formaldehyde Glues and Resins Market
Adhesives & Sealants
Joint Sealants Market
Adhesives & Sealants
Die Cut Adhesive Market
Adhesives & Sealants
Wearable Adhesives Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
North America Contact Adhesives Market
Adhesives & Sealants
High Performance Adhesives Market
Adhesives & Sealants
North America Laminating Adhesives Market
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Europe Waterborne Adhesives Market