
 Global Specialty Polystyrene Resin Market | 2026-2036
Global Specialty Polystyrene Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Polystyrene Resin Market Foresight
Asian polystyrene producers is recalibrating capacity allocations amid feedstock volatility and shifting export destinations. BASF SE leverages its integrated Verbund sites in Ludwigshafen to sustain cost-advantaged high-impact grades for automotive interior applications. INEOS Styrolution Group GmbH anchors European demand through specialized extruded polystyrene for building insulation, competing against polyurethane foam alternatives.
Specialty polystyrene resin denotes thermoplastic polymers derived from styrene monomer with controlled molecular weights, impact modifiers, or blowing agents, typically processed via continuous bulk polymerization or suspension methods to achieve glass transition temperatures near 100°C for dimensional stability in molded components. High impact polystyrene dominates volume flows through appliance housings and electronics chassis where toughness requirements exceed general purpose grades, while expanded polystyrene captures margin concentration in construction thermal insulation where energy code stringency elevates specification premiums. Packaging solutions across food service and pharmaceutical cold-chain applications represent the fastest-expanding application dimension, driven by sterilization compatibility and moisture barrier performance.
REACH registration requirements and ECHA substance evaluations constrain styrene monomer classifications across European value chains, while China's GB standards and MEE environmental inspections tighten volatile organic compound emissions at polymerization facilities. FDA food contact notifications and EPA toxic substance controls shape product formulations for US-bound packaging and consumer goods exports. Stakeholders must monitor feedstock substitution timelines as bio-attributed and chemically recycled styrene pathways mature.
Market Dynamics
REACH registration deadlines and ECHA substance evaluations are compressing styrene monomer availability across European value chains, forcing producers to accelerate bio-attributed feedstock qualification timelines while appliance manufacturers in China pull high-impact grades for export-oriented production.
Growth Catalysts
- EU Green Deal emission thresholds:Tightening styrene monomer limits under REACH are redirecting capital toward chemically recycled and bio-based feedstock R&D, creating first-mover advantage for integrated producers with pilot-scale pyrolysis partnerships.
- Cold-chain pharmaceutical packaging:Sterilization-compatible expanded polystyrene demand is accelerating from mRNA vaccine distribution infrastructure and temperature-sensitive biologics logistics in North America and Western Europe.
- China appliance export surge:E-commerce platform expansion and white-goods manufacturing concentration in Jiangsu and Guangdong provinces are concentrating regional offtake for high-impact grades with enhanced dimensional stability.
Market Restraints
- Benzene-ethylene feedstock volatility:Crude-linked naphtha cracking economics and regional refinery maintenance cycles are compressing margin predictability for non-integrated polymerization facilities.
- Polyurethane foam substitution:Extruded polystyrene building insulation faces displacement from spray polyurethane systems in EU energy retrofit programs where lambda-value performance thresholds are tightening.
- MEE environmental inspection intensity:China's Ministry of Ecology and Environment VOC emission audits at Shandong and Zhejiang polymerization plants are forcing unplanned shutdowns and spot supply tightness.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO cold-chain compliance mandates for temperature-sensitive generics distribution are creating specification windows for sterilization-grade expanded polystyrene with moisture barrier certification.
- Chemical recycling infrastructure:Pyrolysis-based styrene monomer recovery from post-consumer polystyrene waste streams is modularizing supply chains for brand-owner circularity commitments under EU Single-Use Plastics Directive implementation.
- Direct-to-manufacturer digital channels:B2B platform procurement for specialty resin grades is compressing distributor markups and enabling real-time specification matching for mid-volume appliance molders.
Industry Challenges
- Polymerization process control expertise:Continuous bulk polymerization optimization for narrow molecular weight distribution requires scarce chemical engineering talent familiar with high-impact modifier integration.
- FDA food contact notification timelines:New additive packages for microwaveable packaging applications face extended safety review cycles, delaying commercialization for reformulated grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Polystyrene Resin Market |
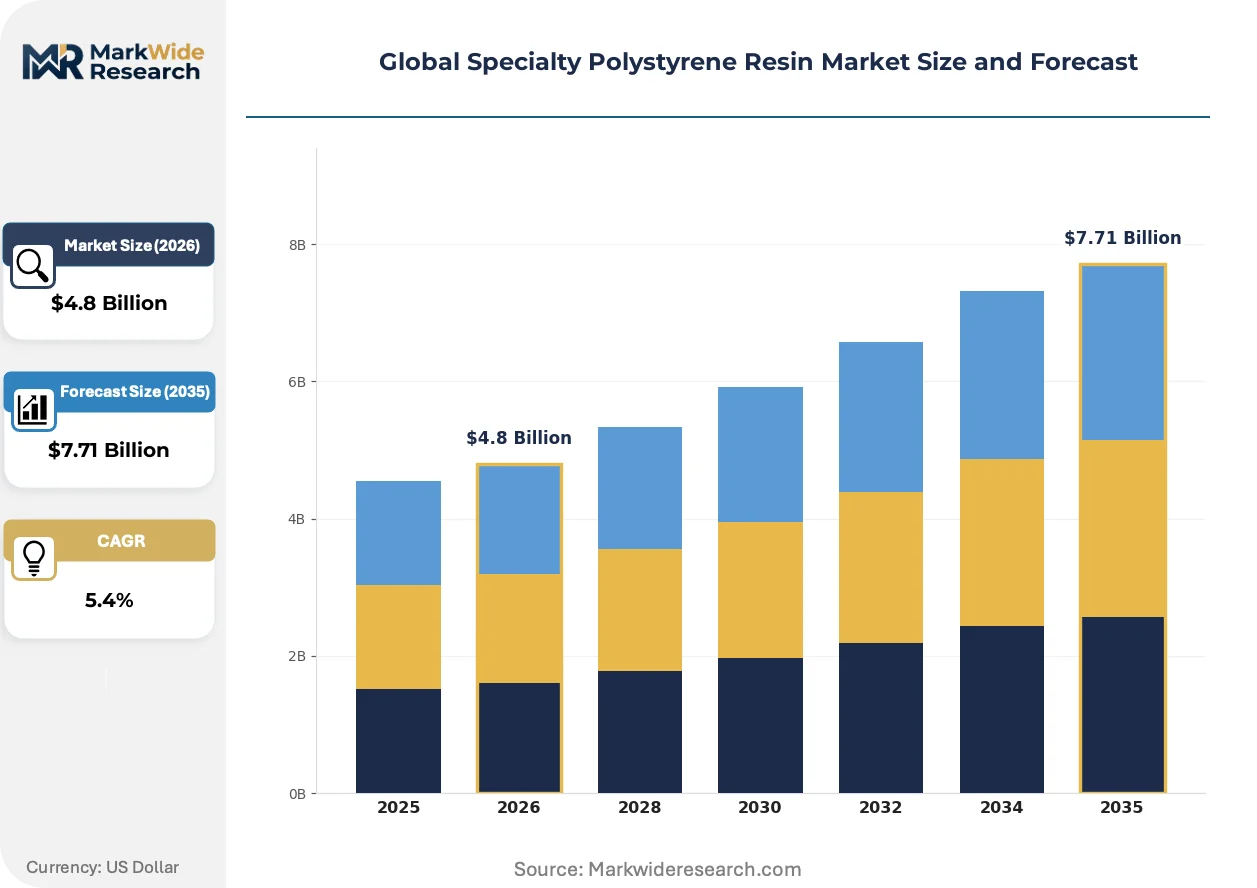
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose Polystyrene, High Impact Polystyrene, Expanded Polystyrene, Extruded Polystyrene Application: Packaging Solutions, Electrical Components, Consumer Goods, Construction Materials End User Industry: Consumer Electronics, Food & Beverage, Appliance Manufacturing, Building Products Form: Pellets, Beads, Sheets, Films |
| Companies Covered | Synthos, BASF SE, Sekisui Kasei Co., Ltd., SUNPOR, INEOS Styrolution Group GmbH, SABIC, Trinseo, LG Chem, Ltd., NOVA Chemicals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Polystyrene Resin Market Shifts & Advancements
Bio-attributed feedstock certification and modular production architectures are fragmenting traditional petrochemical value chains, while regulatory pressure on styrene monomer classifications accelerates investment in alternative synthesis pathways.
Advanced dissolution recycling using selective solvent extraction is modularizing post-industrial and post-consumer polystyrene recovery operations. Appliance manufacturers in Germany and appliance exporters in China are piloting mass-balance certified recycled content for corporate sustainability reporting. This technology is modularizing regional supply loops and compressing reliance on virgin naphtha-derived monomer.
REACH authorization requirements for styrene under Substance of Very High Concern candidate listing are forcing reformulation investments across European compounders. Industrial consequences include accelerated substitution testing for food-contact applications and insulation-grade blowing agent compatibility. Medical packaging producers in France and Benelux are responding with bio-attributed grade qualification programs to preempt supply disruption.
Buyer consolidation among major appliance OEMs is compressing supplier negotiation leverage and unbundling technical service from material supply contracts. Direct specification-setting by Haier, Midea, and Whirlpool procurement centers is displacing distributor-mediated relationships in Asia-Pacific supply chains. This concentration is most visible in Jiangsu province molding clusters serving export-oriented refrigerator and freezer production.
Global Specialty Polystyrene Resin Market Segmentation
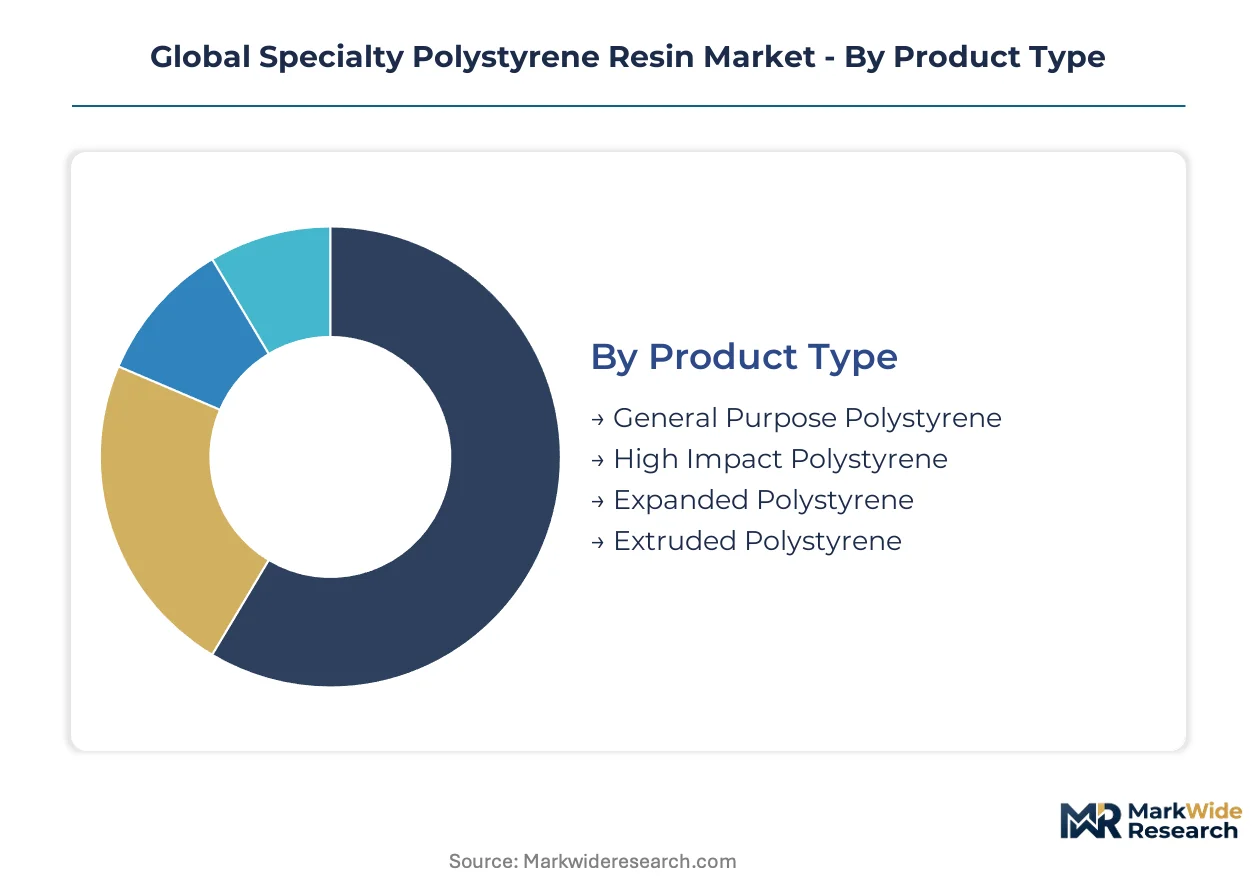
Specialty polystyrene resin segmentation reveals how molecular architecture, processing method, and end-use performance requirements partition value capture across the value chain. Distinct specification tiers command margin premiums based on impact resistance, thermal insulation coefficients, and regulatory compliance burdens.
Product Type:
Customization intensity spans from commodity-grade general purpose resins to engineered high-impact and expanded variants requiring precise additive integration.
- High Impact Polystyrene:Styrene-butadiene rubber modification creates a two-phase morphology delivering toughness retention down to sub-zero temperatures. Appliance manufacturers in Jiangsu province specify these grades for refrigerator liner vacuum-forming operations where dimensional stability under thermal cycling is non-negotiable. REACH-compliant additive packages are becoming mandatory for EU-bound appliance exports.
- Expanded Polystyrene:Pentane-blown bead expansion yields closed-cell structures with lambda values below 0.040 W/m·K, positioning this segment for energy code compliance in German and French building retrofit programs. Cold-chain pharmaceutical packaging specifications from CDSCO in India and FDA in the US are accelerating medical-grade qualification timelines.
- General Purpose Polystyrene:Unmodified linear polymers serve cost-sensitive disposable applications where clarity and ease of thermoforming outweigh mechanical performance requirements.
- Extruded Polystyrene:Continuous foaming produces rigid insulation boards with compressive strength above 200 kPa for inverted roof and perimeter foundation applications.
Most installed capacity flows through General Purpose Polystyrene. Expansion is steepest in Expanded Polystyrene.
Application:
Margin structure diverges sharply between regulated food-contact and medical packaging versus commodity construction and electrical applications.
- Packaging Solutions:Sterilization-compatible expanded polystyrene formats for mRNA vaccine distribution infrastructure combine moisture barrier performance with gamma-radiation stability. FDA food contact notification requirements for microwaveable trays are extending qualification timelines for new additive packages.
- Construction Materials:Extruded polystyrene boards face displacement pressure from spray polyurethane systems in EU energy retrofit programs where lambda-value thresholds are tightening. German KfW funding programs and French CEE certificate schemes still support specification in passive house envelopes.
- Electrical Components:High-impact grades with flame-retardant packages serve junction boxes and switch housings where UL94 V-0 ratings are mandatory.
- Consumer Goods:General purpose clarity grades dominate disposable cutlery and cosmetic packaging where cost minimization overrides performance engineering.
Construction Materials absorbs the largest volume share. Packaging Solutions is climbing the fastest.
End User Industry:
Customer concentration and technical service requirements vary dramatically across OEM procurement sophistication levels.
- Appliance Manufacturing:Haier, Midea, and Whirlpool procurement centers in China are consolidating supplier relationships and unbundling technical service from material contracts. High-impact grades with mass-balance certified recycled content are piloting for corporate sustainability reporting compliance.
- Food & Beverage:Quick-service restaurant chains and dairy processors specify food-contact grades with migration testing documentation for FDA and EFSA compliance. Bio-attributed feedstock certifications are emerging as a procurement differentiator.
- Consumer Electronics:Television and monitor chassis applications demand high-impact grades with electrostatic discharge protection and thin-wall moldability.
- Building Products:Insulation distributors and roofing contractors prioritize compressive strength consistency and dimensional stability under freeze-thaw cycling.
Building Products channels the greatest resin tonnage. Appliance Manufacturing is gaining share fastest.
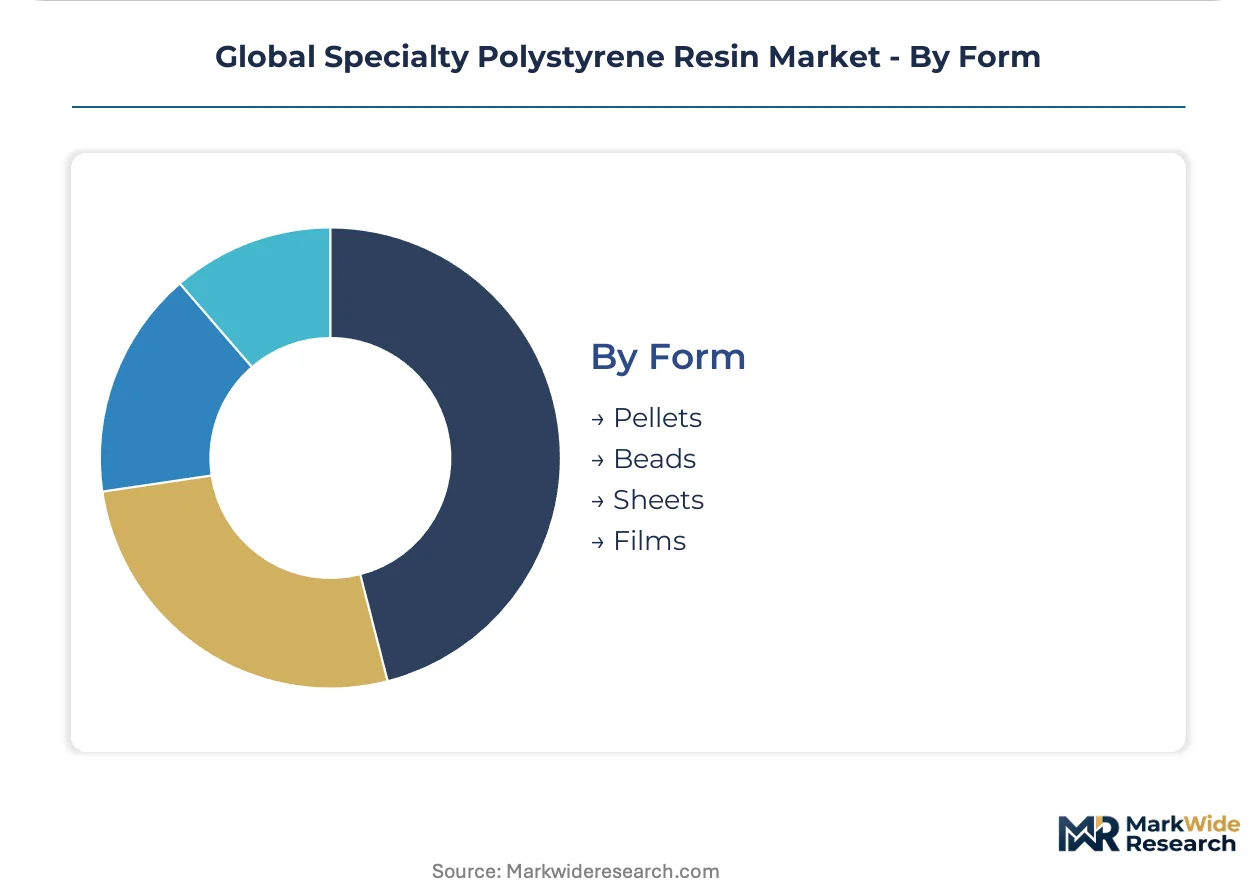
Form:
Processing method and logistics economics determine form factor selection across injection molding, thermoforming, and block molding value chains.
- Pellets:Extrusion-grade and injection-molding compounds ship in bulk railcar quantities to integrated appliance manufacturing campuses where silo storage and pneumatic conveying minimize handling costs.
- Beads:Expandable polystyrene beads require pre-expansion and molding operations at construction sites or packaging fabricators, creating distributed processing networks with regional supply radius constraints.
- Sheets:Extruded sheet formats serve thermoforming operations for food trays and medical device packaging where thickness tolerance and surface finish specifications are critical.
- Films:Oriented and cast film grades occupy niche applications in label stock and flexible packaging where biaxial orientation enhances clarity and stiffness.
Most resin conversion flows through Pellets. Beads is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting specialty polystyrene resin production toward jurisdictions with lower compliance costs, as REACH-mandated styrene thresholds in Europe widen cost-of-production gaps against Asian manufacturing bases.
China
Jiangsu and Guangdong province appliance clusters pull high-impact grades for refrigerator and freezer exports to North American and European markets. MEE environmental inspections at Shandong polymerization facilities enforce VOC emission limits, forcing unplanned shutdowns that tighten spot supply. Zhejiang molding corridors serving Haier and Midea procurement centers concentrate regional offtake for mass-balance certified recycled content grades.
Germany
Automotive interior applications sustain demand for high-impact grades at BASF SE's Ludwigshafen Verbund complex, where integrated production preserves margin advantage. REACH authorization timelines for styrene monomer under Substance of Very High Concern candidate listings compress formulation flexibility for food-contact applications. KfW funding programs for passive house construction sustain specification premiums for extruded polystyrene insulation in energy retrofit markets.
United States
mRNA vaccine distribution infrastructure drives sterilization-compatible expanded polystyrene demand for pharmaceutical cold-chain packaging. FDA food contact notification requirements for microwaveable tray formulations extend qualification timelines for new additive packages. Gulf Coast petrochemical corridors leverage integrated naphtha cracking to supply non-integrated polymerization facilities with cost-advantaged benzene-ethylene feedstocks.
India
CDSCO cold-chain compliance mandates for temperature-sensitive generics distribution create specification windows for medical-grade expanded polystyrene with moisture barrier certification. Maharashtra and Gujarat pharmaceutical packaging corridors concentrate demand for sterilization-grade formats. Central government PLI scheme incentives for specialty chemicals manufacturing attract greenfield polymerization investments targeting export markets.
Saudi Arabia
SABIC's integrated petrochemical complexes at Jubail supply cost-advantaged styrene monomer to regional polymerization facilities serving construction insulation markets across Gulf Cooperation Council states. SAMR technical regulations for building materials enforce thermal performance standards that elevate specification requirements for extruded grades. Eastern Province industrial cities anchor downstream conversion operations for Middle East and North Africa export destinations.
Global Specialty Polystyrene Resin Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-attributed feedstock certification and chemical recycling partnerships to differentiate positioning. The vendor base concentrates around integrated petrochemical conglomerates with captive styrene monomer supply, alongside specialized compounders serving medical packaging and appliance manufacturing niches. Three archetypes dominate: integrated majors with Verbund economics, regional specialists with logistics-advantaged distribution, and sustainability-focused innovators with mass-balance certification capabilities. Capacity expansion and strategic pyrolysis partnerships constitute the dominant competitive moves.
Among European integrated producers, INEOS Styrolution Group GmbH and BASF SE exemplify the Verbund-advantaged archetype with backward integration into styrene monomer production. Synthos anchors Central European supply for high-impact and expanded grades. These three companies represent contrasting strategic postures: German-based integrated majors pursuing circularity investments, a Polish-headquartered regional specialist with logistics reach into Eastern European construction markets, and diversified chemical conglomerates balancing commodity and specialty grade portfolios.
| Leading Market Players |
|---|
| Synthos |
| BASF SE |
| Sekisui Kasei Co., Ltd. |
| SUNPOR |
| INEOS Styrolution Group GmbH |
| SABIC |
| Trinseo |
| LG Chem, Ltd. |
| NOVA Chemicals Corporation |
| Others |
Supply & Pricing Matrix
Appliance OEM procurement centers in Jiangsu and Guangdong provinces command contract-based long-term offtake agreements that compress distributor margins and anchor pricing power with volume-scaled buyers. REACH-compliant additive packages for EU-bound exports command certification premiums that separate qualified grades from commodity alternatives.
Pricing Analysis
Distributor markups in Asian supply chains face compression as Haier, Midea, and Whirlpool procurement centers negotiate direct-to-manufacturer terms. Three-tier pricing structure across premium, standard, and economy levels stratifies by REACH compliance status and mass-balance certification. Cost compression in standard grades is intensifying because benzene-ethylene feedstock volatility squeezes non-integrated polymerization facilities. Food-contact and medical packaging buyers show least price sensitivity; disposable cutlery processors exhibit highest.
Supply Chain Analysis
Styrene monomer supply rests on integrated petrochemical complexes in China, Germany, and Saudi Arabia. Benzene-ethylene feedstocks, pentane blowing agents, and rubber impact modifiers constitute critical input dependencies. Single-source vulnerability concentrates at Shandong and Zhejiang polymerization corridors where MEE environmental inspections trigger unplanned shutdowns. Distribution runs through bulk railcar shipments to integrated appliance campuses and regional bead pre-expansion networks for construction applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal emission thresholds and REACH authorization timelines for styrene monomer are redirecting capital toward bio-attributed feedstock R&D and creating first-mover advantage windows.
For Market Incumbents: Lock in pyrolysis partnerships with post-consumer waste aggregators to secure chemically recycled styrene monomer streams before feedstock substitution mandates tighten. Defend margin position by accelerating mass-balance certification at Ludwigshafen and Jubail integrated sites to preempt bio-attributed grade qualification disruption from emerging sustainability-focused compounders.
For New Entrants and Emerging Players: Capture CDSCO cold-chain compliance specification windows in Maharashtra and Gujarat pharmaceutical packaging corridors where sterilization-grade expanded polystyrene demand outruns qualified supply. Target mid-volume appliance molders through B2B platform procurement channels that bypass entrenched distributor relationships and enable real-time specification matching.
For Investors and Strategic Acquirers: Chemical recycling infrastructure specialists are the most active acquirer in this space, consolidating modular pyrolysis technology providers and regional waste-stream aggregators. Long-term viability hinges on feedstock substitution timeline acceleration rather than virgin naphtha economics. Monitor EU ECHA substance evaluation announcements for styrene monomer as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Pyrolysis Partnership Formation | Secures chemically recycled styrene monomer streams for EU circularity compliance. |
| Mass-Balance Certification Investment | Enables bio-attributed grade qualification for REACH-compliant appliance exports. |
| B2B Platform Channel Development | Compresses distributor markups for mid-volume Jiangsu province molders. |
| CDSCO Medical-Grade Qualification | Captures sterilization-grade expanded polystyrene specification windows in India. |
| Integrated Verbund Capacity Expansion | Preserves cost advantage in high-impact grades for automotive interior applications. |
Research Methodology
Bottom-up appliance and packaging modeling reconciled against top-down styrene monomer production tracking forms the analytical core of this study. Primary interviews with polymerization plant managers, procurement leads at Haier and Midea, distribution channel partners, and technical R&D directors at INEOS Styrolution and BASF SE combined with secondary validation from customs/trade data, ECHA substance evaluation databases, SEC 10-K filings, and ACC industry reports. Triangulation across stakeholder inputs and documentary sources ensures cross-verified demand and supply estimates.
Input-output matrices map benzene-ethylene feedstock costs through polymerization economics to grade-specific pricing across the projection horizon. Segmentation dimensions span product architecture, application performance tier, end-use industry procurement sophistication, and regional regulatory cluster. CAGRs derive from trend extrapolation of historical capacity utilization, feedstock substitution timelines, and compliance-driven specification shifts. Forecast inputs incorporate MEE environmental inspection intensity cycles and EU REACH authorization milestone schedules.
Underlying measurement precision varies by segment; REACH-compliant and medical-grade categories carry tighter precision than commodity construction applications due to documented certification audit trails. Forecasts reflect assumptions about feedstock volatility persistence and regulatory implementation cadence. Material deviation in EU ECHA styrene monomer classification timelines or China MEE enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Poly(P-Phenylene Ether) (PPE) Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Global Bio Polyols Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Global Polymer Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Global Ethylene Vinyl Acetate Resins Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Polymer Seals Market