
 Global Unsaturated Polyester Resins Market | 2026-2036
Global Unsaturated Polyester Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Unsaturated Polyester Resins Market Foresight
EU REACH regulation is hardening the cost-of-entry calculus for unsaturated polyester resin manufacturers seeking European market access. INEOS leverages its integrated petrochemical feedstock position to manage raw material volatility across multiple continents. BASF SE sustains technology leadership through specialized isophthalic formulations targeting high-performance marine and electrical applications. Polynt Group anchors its competitive stance with extensive European manufacturing infrastructure and backward integration into anhydride intermediates.
Unsaturated polyester resins are thermosetting polymers synthesized through condensation of dicarboxylic acids with glycols, subsequently cross-linked with vinyl monomers like styrene to achieve dimensional stability and chemical resistance. These resins serve primarily as matrix materials in fiber-reinforced composites for corrosion-resistant equipment, structural panels, and molded components. Orthophthalic grades occupy the mature volume core of the market, while isophthalic formulations command premium positioning in marine and chemical processing applications where hydrolytic stability proves critical. The renewable energy end-use segment represents the fastest-growing demand pool, driven by wind turbine blade manufacturing requirements for large-scale, fatigue-resistant composite structures.
The EPA enforces stringent volatile organic compound limits on styrene emissions from resin processing facilities across the United States. ECHA administers REACH authorization requirements that restrict certain phthalic anhydride derivatives and mandate substitution planning for hazardous cross-linking agents. China's MEE implements dual carbon goals that pressure domestic producers toward cleaner curing technologies and reduced styrene content. Stakeholders must monitor evolving chemical hazard classifications across these jurisdictions, as reclassification of key raw materials would force immediate reformulation investments and disrupt established supply relationships.
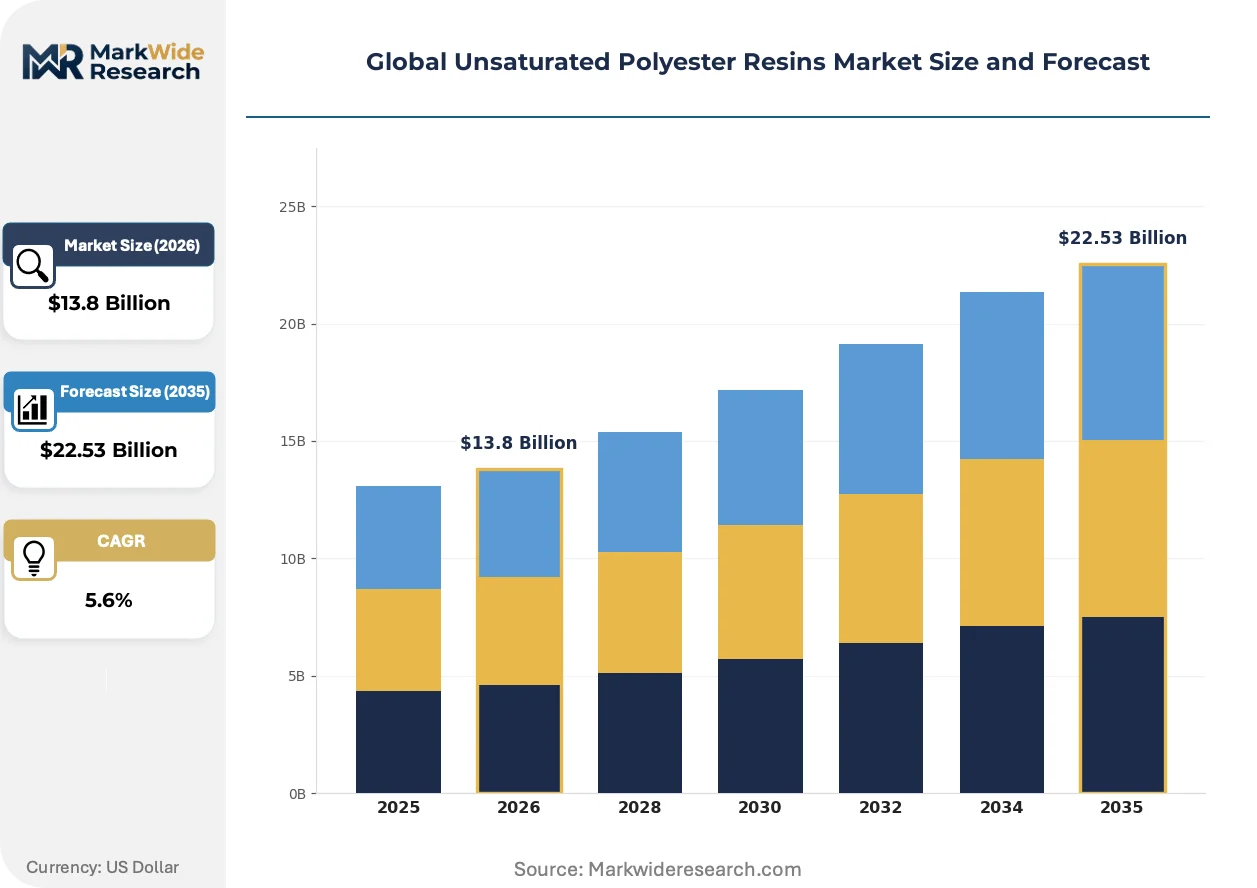
Market Dynamics
Wind turbine blade manufacturing is compressing demand cycles for fatigue-resistant composite matrices, while styrene emission controls in China, Europe, and the United States simultaneously tighten formulation constraints on producers across all three continents.
Growth Catalysts
- China's dual carbon goals:MEE mandates are accelerating wind farm buildouts that consume large-format orthophthalic and isophthalic resin grades for turbine blade production.
- Marine composite substitution:Boat builders are replacing metal hulls with lighter fiber-reinforced structures that require hydrolytically stable isophthalic formulations.
- REACH authorization pathways:ECHA's substitution planning requirements for hazardous cross-linking agents are pulling low-emission resin development investment into European manufacturing.
Market Restraints
- Phthalic anhydride supply concentration:Backward integration into anhydride intermediates limits viable supplier pools to integrated petrochemical complexes in China and Western Europe.
- Styreene volatility:Vinyl monomer price swings directly compress resin blending margins without corresponding pass-through mechanisms in construction contracts.
- Thermoset recyclability limits:Cross-linked polymer structures prevent mechanical reprocessing, constraining circular economy positioning against emerging thermoplastic composites.
Strategic Opportunities
- India infrastructure buildout:National highway and railway panel programs present underpenetrated demand for corrosion-resistant structural composites.
- UV-curing technology convergence:Photoinitiator advances combined with LED curing systems enable styrene-reduced formulations for closed-mold fabrication.
- EU Green Deal procurement:Public tender environmental criteria are creating preferential purchasing channels for bio-based glycol resins in municipal construction.
Industry Challenges
- Composite laminate technician scarcity:Manual layup expertise gaps in Germany and the United States constrain throughput scaling for custom marine and industrial fabricators.
- Multijurisdictional hazard reclassification:ECHA, EPA, and China's MEE maintain divergent chemical hazard lists that force parallel compliance documentation for export-oriented producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Unsaturated Polyester Resins Market |
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.53 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orthophthalic, Isophthalic, Terephthalic, Vinylic, Others Application: Marine, Construction, Electrical & Electronics, Consumer Goods, Transportation Manufacturing Process: Bulk, Solution, Suspension, Emulsion End Use Industry: Building & Infrastructure, Renewable Energy, Packaging, Textiles |
| Companies Covered | INEOS, BASF SE, Polynt Group, AOC, LLC, Covestro AG, Scott Bader Company Ltd., U-PICA Company Ltd., Eternal Materials Co., Ltd., Reichhold LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Unsaturated Polyester Resins Market Shifts & Advancements
Formulation chemistry is pivoting toward reduced-styrene and bio-sourced feedstocks as regulatory thresholds tighten across major manufacturing geographies, compressing legacy orthophthalic market positions while opening specialty grade premiums.
Hybrid epoxy-unsaturated polyester resin systems are expanding into wind turbine blade root sections and spar caps where load-bearing requirements exceed conventional polyester mechanical limits. Blade OEMs in Denmark and China are qualifying these intermediates for 80-meter-plus rotor designs. The technology is expanding into previously epoxy-dominated structural zones while maintaining polyester cost structures in non-critical blade areas.
EPA volatile organic compound enforcement under the Clean Air Act is forcing open-mold fabricators in Florida and California toward closed-mold infusion or thermal oxidizer investments. Small-to-mid composite shops face capital intensity thresholds that favor consolidation into larger integrated operations. Marine and corrosion equipment segments in the United States are responding with cooperative emissions pooling arrangements and shared abatement infrastructure.
Specification-driven procurement now dominates wind energy and infrastructure tenders, with engineering firms mandating certified fatigue test data and batch traceability that disqualifies commodity resin traders. Direct mill relationships are displacing distributor intermediaries for volume composite manufacturers in China and Germany. This concentration is most visible in turbine blade supply chains where OEMs audit resin plants for continuous quality systems.
Global Unsaturated Polyester Resins Market Segmentation
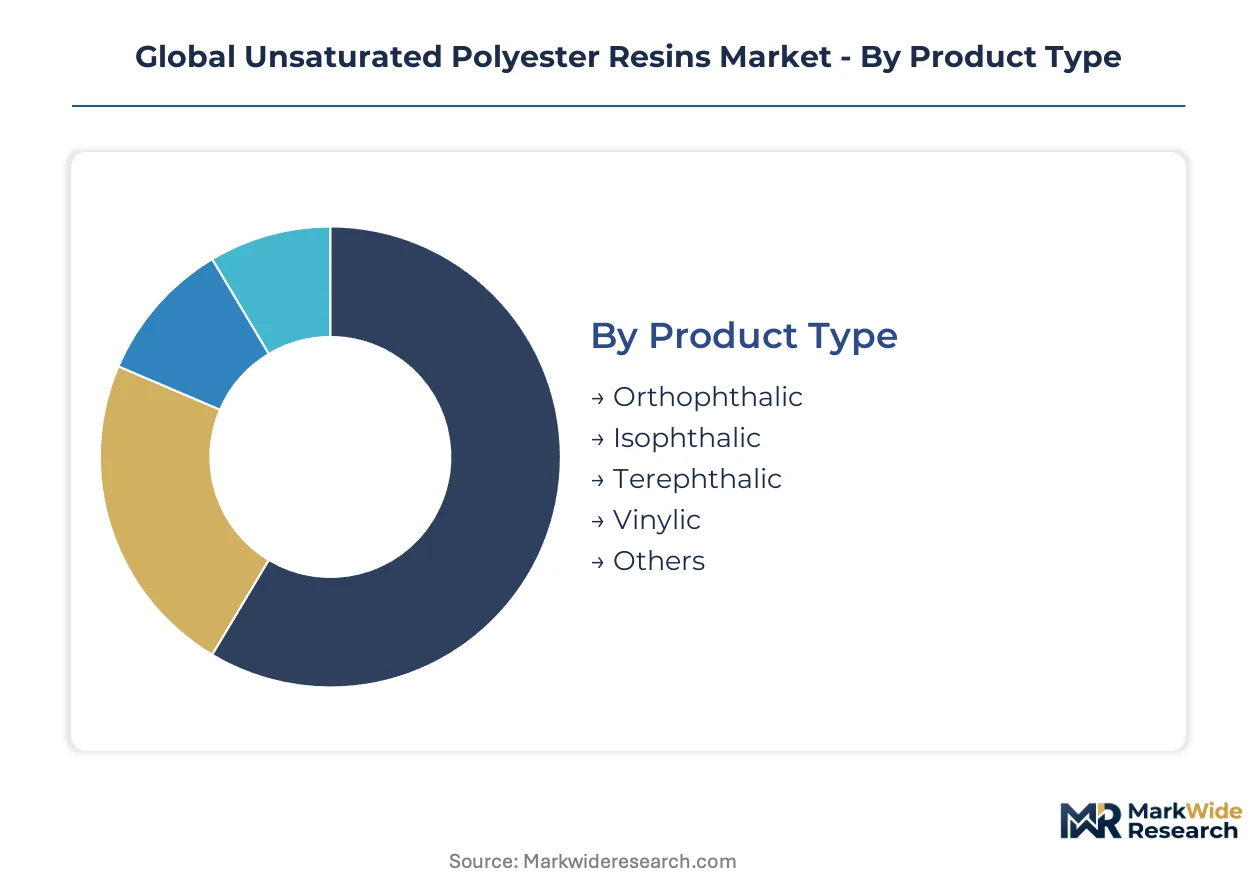
Segmentation in unsaturated polyester resins reveals how formulation chemistry, application requirements, and manufacturing scale create distinct competitive arenas. Buyers self-select across these dimensions based on performance specifications, emission compliance burdens, and supply security needs.
Product Type:
Cost tiers separate commodity buyers from performance-driven specifiers in this category.
- Orthophthalic:Standard-grade resins formulated with phthalic anhydride and maleic anhydride deliver baseline mechanical properties at lowest unit cost. Construction panel manufacturers across India and Southeast Asia specify these grades for non-structural cladding where hydrolytic exposure remains limited. Price volatility in phthalic anhydride feedstock compresses blender margins without pass-through protection in fixed infrastructure contracts.
- Isophthalic:Higher-performance resins incorporating isophthalic acid substitution provide superior water resistance and dimensional stability under cyclic loading. Marine hull fabricators in Italy and Florida mandate these formulations for osmotic blister prevention in fiberglass boat construction. REACH authorization pressures on traditional cross-linkers are accelerating low-emission isophthalic development investments at European resin plants.
- Terephthalic:Specialty grades leveraging purified terephthalic acid deliver enhanced chemical resistance for industrial tank and pipe applications.
- Vinylic:Modified resins with higher vinyl content enable faster cure cycles in automated pultrusion lines.
- Others:Niche formulations including dicyclopentadiene and hybrid epoxy-polyester systems serve wind blade root sections.
Orthophthalic leads volumes today; isophthalic is gaining share fastest.
Application:
Application selection tracks directly to laminate complexity and regulatory exposure intensity.
- Marine:Boat builders specify hydrolytically stable formulations for hull laminates exposed to continuous saltwater immersion. Italian and Turkish shipyards are converting metal superstructures to fiber-reinforced composites for weight reduction and fuel efficiency compliance.
- Construction:Structural panels, roofing sheets, and corrosion-resistant cladding consume the largest resin volumes across infrastructure buildouts. China's highway and railway programs specify fire-retardant grades for tunnel lining applications.
- Electrical & Electronics:Encapsulation and insulating components require low-smoke, halogen-free formulations for transformer and switchgear manufacturing.
- Consumer Goods:Sanitary ware, artificial marble, and recreational equipment use filled, pigmented resins with cosmetic surface finish requirements.
- Transportation:Truck body panels, rail interior components, and automotive aftermarket parts demand impact-resistant formulations with Class A surface capability.
Construction dominates current offtake; marine is expanding most quickly on composite substitution trends.
Manufacturing Process:
Process selection reflects batch scale economics and emission control capital availability.
- Bulk:Continuous stirred-tank polymerization at elevated temperatures produces commodity-grade resins at highest throughput rates. Large integrated producers in Germany and China operate bulk lines with captive anhydride feedstock integration.
- Solution:Solvent-based condensation enables lower-temperature processing for heat-sensitive monomer combinations. Specialty formulators in Japan and Switzerland utilize solution processes for high-purity electrical-grade resins.
- Suspension:Dispersed-phase polymerization creates bead-form resins for powder coating and solid surface applications.
- Emulsion:Water-based systems serve low-VOC coating formulations where solvent emission restrictions are most stringent.
Bulk processing commands volume leadership; emulsion is climbing the fastest on environmental compliance drivers.
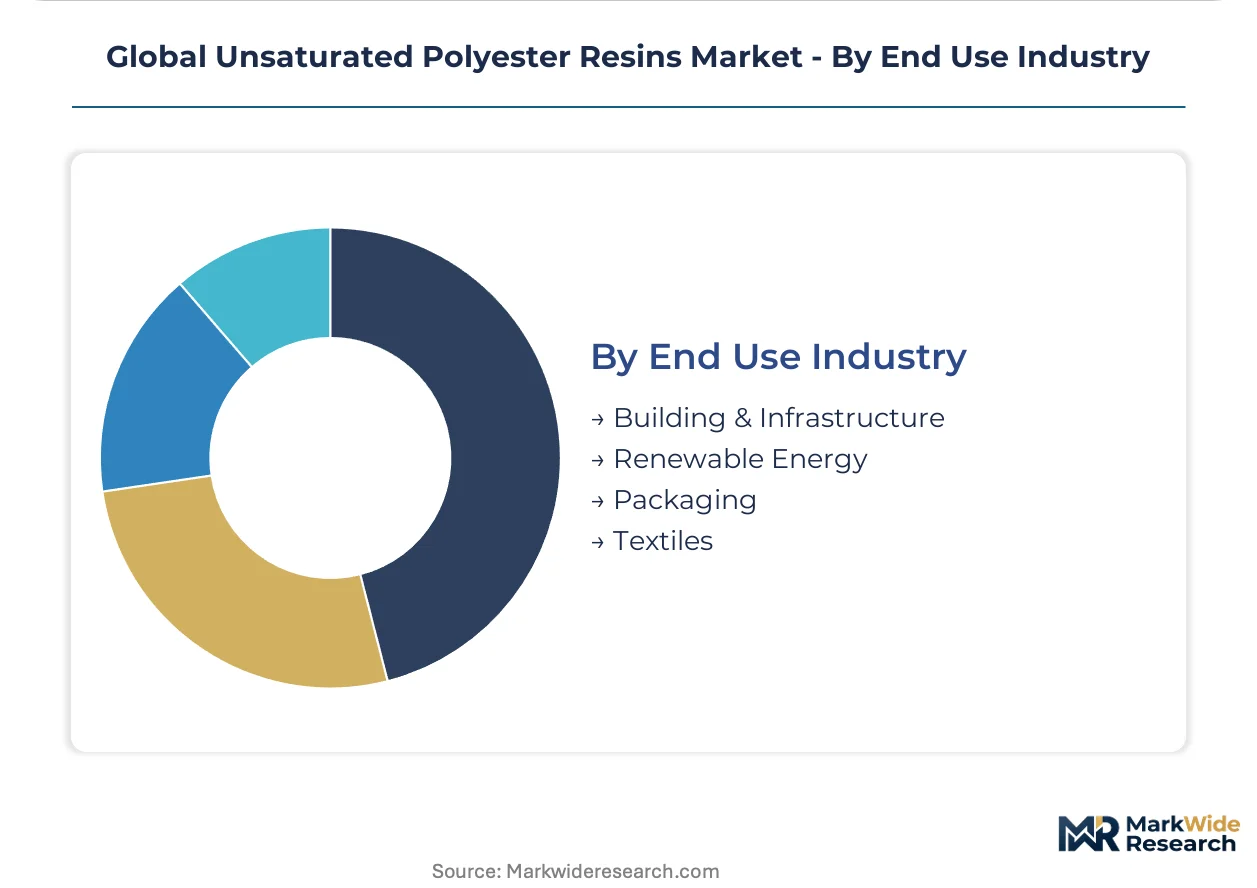
End Use Industry:
End-use concentration determines specification stringency and supplier qualification barriers.
- Building & Infrastructure:Corrosion-resistant equipment, architectural panels, and rehabilitation composites consume orthophthalic and isophthalic grades across municipal and industrial projects. India's national highway development program is qualifying resin suppliers for precast concrete panel bonding applications.
- Renewable Energy:Wind turbine blade manufacturing demands fatigue-resistant matrices with certified mechanical property traceability. Blade OEMs in Denmark and China audit resin plants for continuous quality systems and batch documentation.
- Packaging:Chemical-resistant drums and intermediate bulk containers use reinforced polyester linings for aggressive material containment.
- Textiles:Fiber sizing and nonwoven reinforcement binders utilize low-viscosity resin emulsions for processing compatibility.
Building & Infrastructure anchors current demand; renewable energy shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized composite laminate technicians concentrate in Germany's industrial belt, China's coastal manufacturing zones, and the US Gulf Coast, creating regional capability clusters that constrain capacity expansion where labor scarcity bites hardest.
China
Wind turbine blade manufacturing clusters in Jiangsu and Guangdong provinces consume substantial orthophthalic and isophthalic resin volumes for 80-meter-plus rotor designs. MEE dual carbon mandates accelerate cleaner curing technology adoption while pressuring domestic producers toward reduced styrene formulations. The Yangtze River Delta hosts integrated petrochemical complexes supplying captive anhydride feedstock to major resin blenders.
United States
Marine hull fabricators in Florida and corrosion equipment manufacturers along the Gulf Coast drive specialty isophthalic grade consumption. EPA Clean Air Act enforcement forces open-mold operations toward closed-mold infusion or thermal oxidizer capital investments. Small-to-mid composite shops in California face consolidation pressure from emissions compliance thresholds.
Germany
Wind energy OEMs in northern states audit resin plants for continuous quality systems and batch traceability documentation. ECHA REACH authorization requirements pull low-emission formulation development investment into European manufacturing infrastructure. The Ruhr industrial corridor retains backward-integrated anhydride production feeding specialty resin lines.
India
National highway and railway panel programs generate underpenetrated demand for corrosion-resistant structural composites in construction applications. Central Electricity Authority standards and Bureau of Indian Safety certification requirements shape procurement specifications for infrastructure resin grades. Gujarat and Maharashtra industrial zones host emerging composite fabrication clusters serving domestic infrastructure buildouts.
Italy
Marine hull builders in Liguria and Tuscany specify hydrolytically stable isophthalic formulations for osmotic blister prevention in fiberglass boat construction. EU Green Deal public tender environmental criteria create preferential purchasing channels for bio-based glycol resins in municipal projects. The Adriatic shipyard belt converts metal superstructures to fiber-reinforced composites for weight reduction compliance.
Global Unsaturated Polyester Resins Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where integrated petrochemical groups anchor commodity supply while regional blenders capture specialty premiums. Market concentration clusters around backward-integrated producers with captive anhydride feedstock positions. Three archetypes dominate: multinational chemical conglomerates with global resin portfolios, European specialists with deep isophthalic formulation expertise, and Asia-Pacific volume producers serving wind energy OEMs. Capacity expansion and low-emission formulation licensing constitute the dominant competitive moves as regulatory thresholds tighten.
Among integrated petrochemical conglomerates, INEOS and BASF SE exemplify archetypes leveraging global feedstock positions to manage raw material volatility across multiple continents. BASF SE occupies a position within the premium formulation tier through specialized isophthalic grades. Polynt Group anchors the European specialist archetype with extensive manufacturing infrastructure and backward integration into anhydride intermediates. These three companies represent distinct strategic postures: feedstock-integrated scale, technology-led specialty positioning, and regional manufacturing depth.
| Leading Market Players |
|---|
| INEOS |
| BASF SE |
| Polynt Group |
| AOC, LLC |
| Covestro AG |
| Scott Bader Company Ltd. |
| U-PICA Company Ltd. |
| Eternal Materials Co., Ltd. |
| Reichhold LLC |
| Others |
Supply & Pricing Matrix
Wind turbine blade OEMs in Denmark and China now mandate certified fatigue test data and batch traceability that disqualifies commodity resin traders, forcing supply consolidation around qualified producers with captive anhydride positions and compressing pricing power for unqualified distributors.
Pricing Analysis
Certified resin supply versus uncertified commodity trade splits the market into two pricing regimes. Three-tier pricing structure across premium certified, standard industrial, and economy construction grades separates blade OEM contracts from municipal panel programs. Cost compression in orthophthalic construction grades is intensifying because Indian and Southeast Asian buyers lack pass-through mechanisms in fixed infrastructure contracts. Marine fabricators in Italy and Florida show lowest price sensitivity due to osmotic blister liability risks, while Indian highway contractors represent the most price-constrained segment.
Supply Chain Analysis
Dual-sourcing requirements from wind blade OEMs in Germany and China force qualification of at least two resin plants per supply contract, spreading demand across integrated producers. Supply concentrates in Germany, China, and the United States for bulk polymerization capacity. Production draws from phthalic anhydride, maleic anhydride, and styrene monomer feedstocks. Single-source vulnerability in anhydride intermediates threatens supply security when petrochemical complexes schedule turnarounds. Distribution runs through direct mill relationships for volume composite manufacturers, displacing distributor intermediaries in turbine blade supply chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ECHA REACH compliance costs in Europe exceed MEE environmental mandates in China, creating cost-advantaged supply positions for Asia-Pacific producers serving export markets.
For Market Incumbents: Cement backward integration into anhydride intermediates before phthalic anhydride supply concentration tightens further. Lock in long-term offtake agreements with wind blade OEMs in Denmark and China to defend against hybrid epoxy-polyester substitution in root sections. Prioritize low-emission formulation licensing to European compounders facing EPA and ECHA enforcement convergence. For New Entrants and Emerging Players: UV-curing photoinitiator advances combined with LED curing systems offer a technology-first wedge into closed-mold fabrication segments where styrene-reduced formulations command specification premiums. Target India's national highway and railway panel programs as the most penetrable geography with underqualified local supply. Lead with bio-based glycol resin formulations to capture EU Green Deal municipal tender preferences. For Investors and Strategic Acquirers: Asymmetric upside sits with European specialists possessing deep isophthalic formulation expertise and REACH-authorized product portfolios. Five-to-ten year viability favors producers with demonstrated blade OEM audit compliance and continuous quality systems rather than commodity blenders. Watch for ECHA hazard reclassification of key cross-linking agents as the inflection signal forcing immediate reformulation investment and supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive anhydride supply insulates margin from phthalic anhydride volatility at German and Chinese complexes. |
| Low-Emission Formulation Licensing | Technology transfer agreements enable European resin plants to meet ECHA substitution planning requirements. |
| Long-term Supply Agreement | Direct mill relationships with Vestas and Goldwind displace distributor intermediaries in blade supply chains. |
| Joint Venture | Local partnerships in Gujarat and Maharashtra accelerate qualification for India's highway development program. |
| Capacity Expansion | Additional bulk polymerization lines in Jiangsu province capture wind turbine blade demand from coastal OEM clusters. |
Research Methodology
Bottom-up construction and renewable energy modeling reconciled against top-down petrochemical feedstock tracking forms the analytical core of this study. Primary interviews with resin plant managers, wind blade procurement leads at OEMs, composite fabricator technical directors, and specialty chemical distribution channel partners combined with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA Clean Air Act enforcement records. Triangulation across these sources ensures supply-side production estimates align with demand-side consumption patterns.
Input-output matrices map phthalic anhydride, maleic anhydride, and glycol feedstock availability against orthophthalic, isophthalic, and specialty grade output across the projection horizon. Segmentation dimensions include product grade tier, end-use industry concentration, manufacturing process scale, and regional production hub configuration. CAGRs derive from elasticity-adjusted demand projections and capacity utilization trends. Wind turbine blade length evolution and MEE dual carbon mandate implementation pace serve as key forecast inputs.
The model holds under stable regulatory classification of cross-linking agents; deviation in ECHA, EPA, or MEE hazard reclassification would shift the outlook materially. Forecasts reflect documented assumptions regarding feedstock price pass-through mechanisms and blade OEM qualification timelines. Deviation in hybrid epoxy-polyester substitution rates or thermoplastic composite recycling breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Polypropylene and High-Impact Polystyrene Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
North America Plastic Compounding Market