
 Acrylic Surface Coating Market | 2026-2036
Acrylic Surface Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Surface Coating Market Analysis
Asset-light leasing models for coating application equipment are reshaping competitive entry barriers for mid-scale contractors and regional formulators. PPG Industries Inc. leverages captive resin supply networks to sustain margin stability across volatile raw material cycles. Akzo Nobel N.V. anchors its position through water-based technology leadership in European architectural segments. Asian Paints Ltd. dominates South Asian distribution channels with tiered contractor loyalty programs that lock in specification influence.
Acrylic surface coatings are thermoplastic or thermosetting films formed from acrylic polymer dispersions or solvent-borne resins, typically applied at dry film thicknesses of 25–100 microns to provide weathering resistance, gloss retention, and substrate protection across metal, wood, and masonry surfaces. Water-based acrylics lead volume in architectural applications where VOC regulations have displaced alkyd alternatives, while UV-resistant coatings command premium positioning in automotive clear coats exposed to prolonged solar irradiance. Solvent-based acrylics retain structural share in industrial finishes requiring rapid cure cycles and chemical resistance that aqueous systems cannot yet match.
EPA VOC rules under 40 CFR Part 59 constrain solvent-based formulation across US architectural and industrial segments, while REACH registration requirements and the EU F-Gas Regulation govern raw material transparency and fluorinated additive phase-out in European supply chains. China's MEE enforces GB standards for industrial coating VOC emissions that redirect demand toward water-based acrylic systems in Yangtze River Delta manufacturing clusters. Stakeholders must monitor regulatory divergence between jurisdictions where compliance investments in one geography do not transfer to another, forcing parallel formulation tracks or selective market exit.
Market Dynamics
Automotive OEMs are consolidating specification-grade acrylic clear coat programs around UV-resistant thermosetting formulations, while REACH and EU Green Deal compliance timelines compress VOC thresholds for solvent-based systems across European supply chains.
Growth Catalysts
- Automotive specification-grade programs:OEMs in Germany and Japan are mandating premium acrylic clear coats with enhanced weathering resistance for extended warranty coverage.
- China's infrastructure investment cycle:State-directed spending on transportation and commercial construction in the Yangtze River Delta is driving architectural coating consumption at scale.
- Water-based technology maturation:Advances in aqueous acrylic dispersion chemistry are closing the performance gap with solvent-borne systems in metal finishing applications.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer costs fluctuate with propylene and MMA pricing, squeezing formulation margins without forward-contract hedging.
- Fluorinated additive phase-out:The EU F-Gas Regulation restricts perfluorinated surfactants used in high-performance coatings, forcing reformulation investments.
- Alkyd substitution ceiling:Solvent-based alkyds retain cost advantage in price-sensitive industrial maintenance segments where cure speed is secondary.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for domestic coating capacity are attracting formulator investment in Gujarat and Maharashtra industrial corridors.
- UV-curable acrylic convergence:Hybrid systems combining UV cure with water-based carriers are opening electronics and furniture finishing applications.
- Asset-light equipment leasing:Application machinery rental models are lowering entry barriers for mid-scale contractors in Southeast Asian markets.
Industry Challenges
- Formulation chemist shortage:Specialized expertise in rheology modification and dispersion stability is concentrated among aging technical workforces in Western Europe and Japan.
- Parallel compliance tracks:Divergent VOC regulations across EPA 40 CFR Part 59, REACH, and China's GB standards force redundant R&D investments without cross-border transferability.
- Specification influence fragmentation:Contractor loyalty programs in South Asia are locking independent formulators out of project pipelines controlled by integrated distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Surface Coating Market |
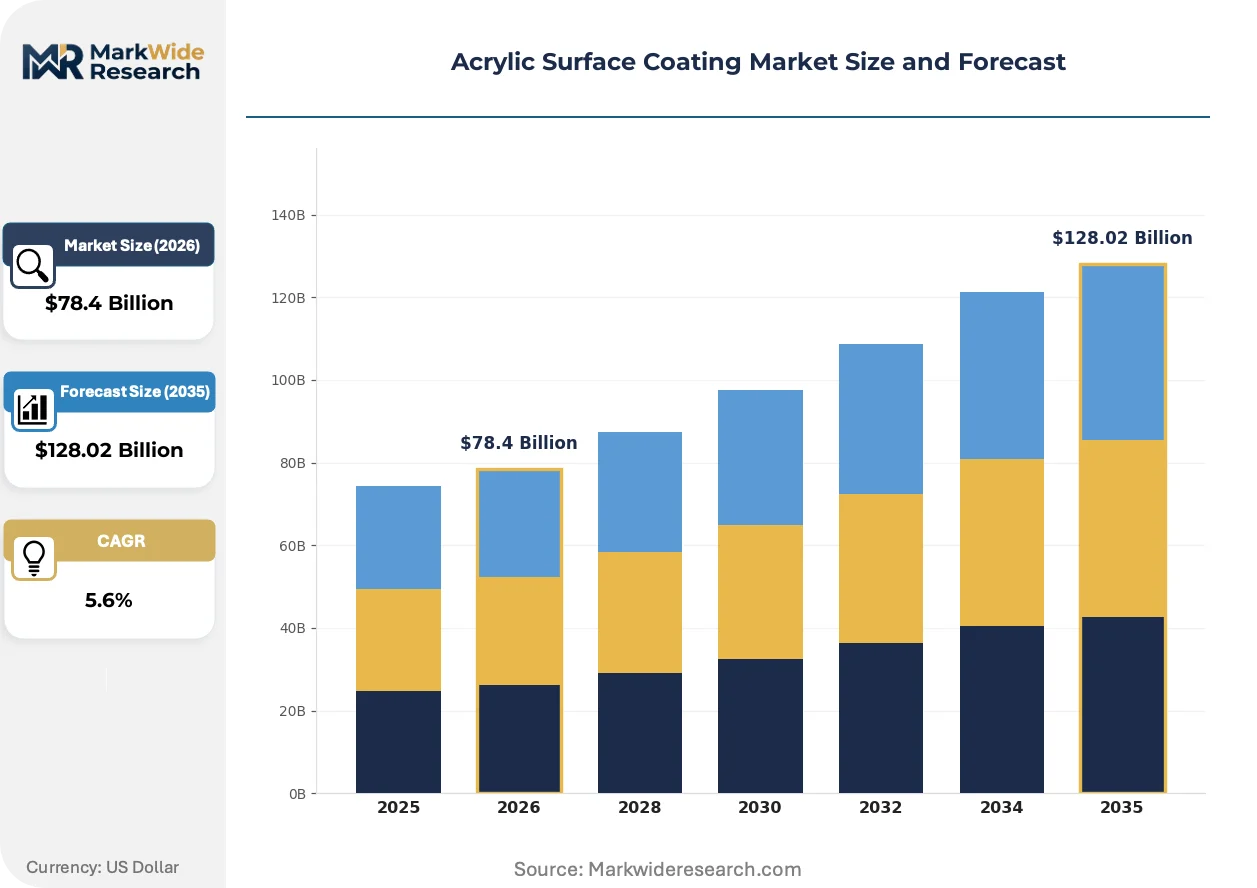
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $128.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Acrylics, Solvent-Based Acrylics, UV-Resistant Coatings, Specialty Acrylics Application: Automotive Coatings, Industrial Finishes, Architectural Paints, Wood Coatings End User: Manufacturers, Contractors, DIY Consumers, Distributors Formulation: Polymer Blends, Pigmented Coatings, Clear Coatings, Textured Finishes |
| Companies Covered | Akzo Nobel N.V., Asian Paints Ltd., BASF SE, Jotun A/S, Nippon Paint Holdings Co Ltd, The Sherwin-Williams Company, Sika AG, Axalta Coating Systems LLC, PPG Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Surface Coating Market Emerging Trajectories
Formulation chemistry is pivoting toward lower-carbon curing systems as regulatory thresholds tighten and automotive OEMs demand extended durability warranties. Three concurrent developments are restructuring competitive positioning.
Self-healing acrylic clear coat technology is migrating from concept validation to production specification. German and Japanese automotive OEMs are qualifying coatings with microencapsulated healing agents for scratch recovery. This migration from laboratory demonstration to assembly-line integration is compressing development cycles for specialty resin suppliers.
The EU Green Deal's Chemicals Strategy for Sustainability is accelerating substance restriction timelines beyond REACH registration requirements. ECHA screening of polymer constituents is forcing raw material transparency investments across European supply chains. Water-based architectural segments are responding fastest, with major formulators pre-emptively reformulating ahead of restriction lists.
Asset-light leasing for spray application equipment is displacing capital purchase models among mid-scale contractors. Regional distributors in India and Vietnam are bundling coating supply with equipment access, locking in volume commitments. This shift is most visible in South Asian commercial construction where project-based contracting dominates.
Acrylic Surface Coating Market Segmentation
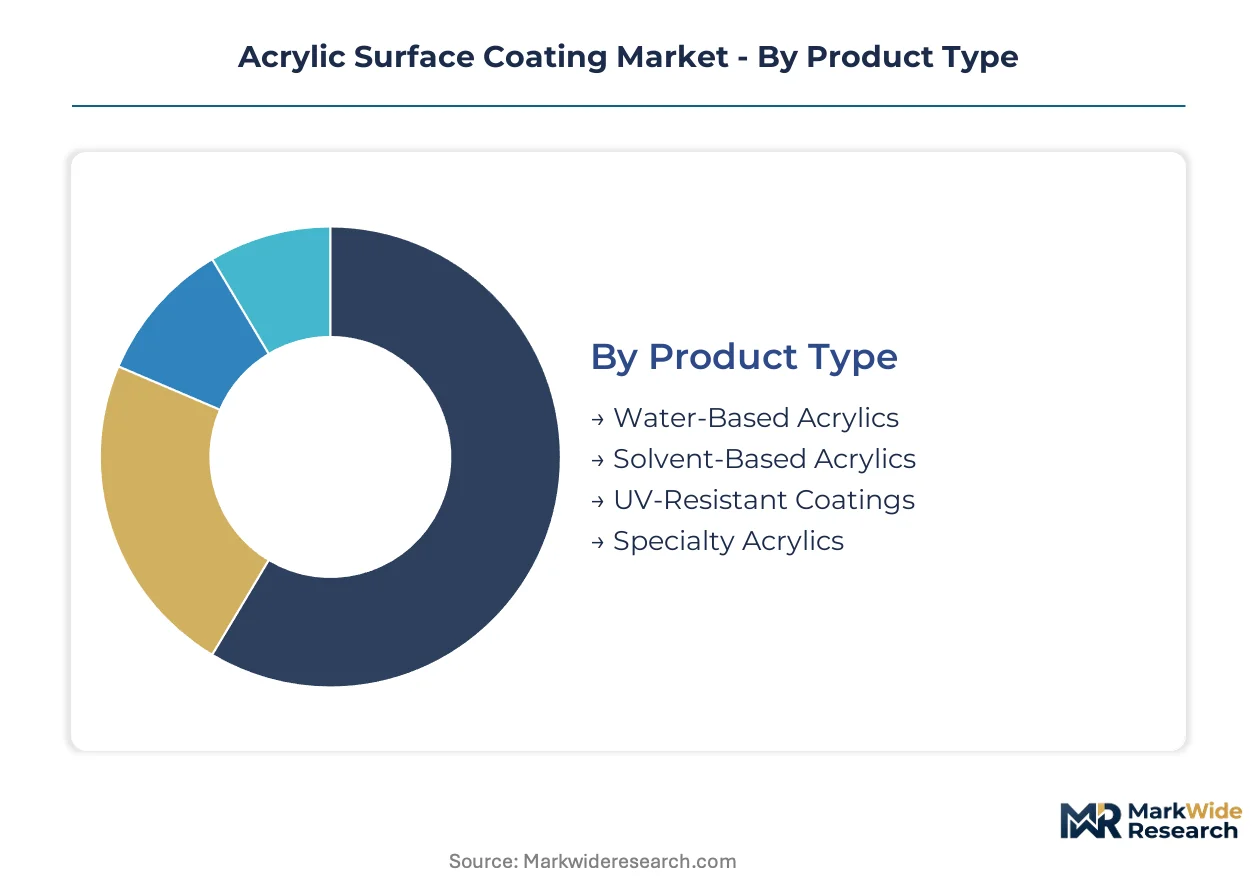
Segmentation in acrylic surface coatings reveals divergent margin profiles and specification cycles across chemistry types and end-use verticals. Water-based systems turn inventory faster in architectural channels, while automotive clear coats lock in longer qualification timelines with OEMs. Understanding these velocity differentials shapes resource allocation for formulators and distributors alike.
Product Type:
Cycle times vary dramatically across acrylic chemistry platforms, with architectural water-based systems refreshing annually versus automotive clear coats that sustain five-to-seven-year specification locks.
- Water-Based Acrylics:Aqueous polymer dispersions formulated with acrylic emulsions achieve 25–75 micron dry film thickness for interior and exterior architectural protection. Demand concentrates in China's Yangtze River Delta manufacturing clusters where MEE enforcement of GB VOC standards redirects volume from solvent alternatives.
- Solvent-Based Acrylics:Thermoplastic or thermosetting films dissolved in organic carriers deliver rapid cure cycles and chemical resistance for industrial metal finishing. European REACH compliance timelines compress specification windows as formulators reformulate ahead of tightening EU Green Deal thresholds.
- UV-Resistant Coatings:Automotive clear coat programs with enhanced photostability command extended warranty coverage from German and Japanese OEMs.
- Specialty Acrylics:Self-healing microencapsulated formulations and fluorinated variants serve niche aerospace and marine specifications.
Water-based acrylics anchor the volume base while UV-resistant coatings gain share at the steepest rate.
Application:
Margin concentration follows specification complexity, with automotive OEM programs capturing premium pricing against commoditized architectural volume plays.
- Automotive Coatings:Specification-grade clear coats and basecoat systems requiring OEM qualification cycles of 18–36 months. German and Japanese manufacturers mandate UV-resistant thermosetting formulations for extended corrosion and gloss warranties, concentrating demand in premium vehicle assembly.
- Architectural Paints:Interior and exterior wall coatings, trim enamels, and decorative finishes applied across commercial and residential construction. China's state-directed infrastructure investment in transportation hubs and commercial development drives coating consumption at scale in provincial urban clusters.
- Industrial Finishes:Protective coatings for machinery, equipment, and metal substrates requiring chemical and abrasion resistance.
- Wood Coatings:Furniture, flooring, and cabinetry finishes where UV-curable acrylic convergence is penetrating electronics and premium furniture segments.
Architectural paints generate the highest absolute volume while automotive coatings deliver the steepest margin expansion trajectory.
End User:
Procurement authority fragments across specification influence tiers, with integrated distributors capturing project pipeline control in South Asian markets.
- Manufacturers:OEMs and fabricators with captive coating operations or direct formulation supply agreements. Automotive manufacturers in Germany and Japan consolidate specification-grade acrylic clear coat programs around qualified resin suppliers.
- Contractors:Professional applicators in commercial construction and industrial maintenance where asset-light equipment leasing models reshape competitive entry barriers in India and Vietnam.
- DIY Consumers:Retail purchasers of architectural paints through home improvement channels, concentrated in North American and European residential renovation cycles.
- Distributors:Integrated supply chain players bundling coating procurement with application equipment access and contractor loyalty programs across South Asian tiered markets.
Contractors anchor the transaction volume base while distributors gain structural influence at the fastest rate through bundled equipment leasing.
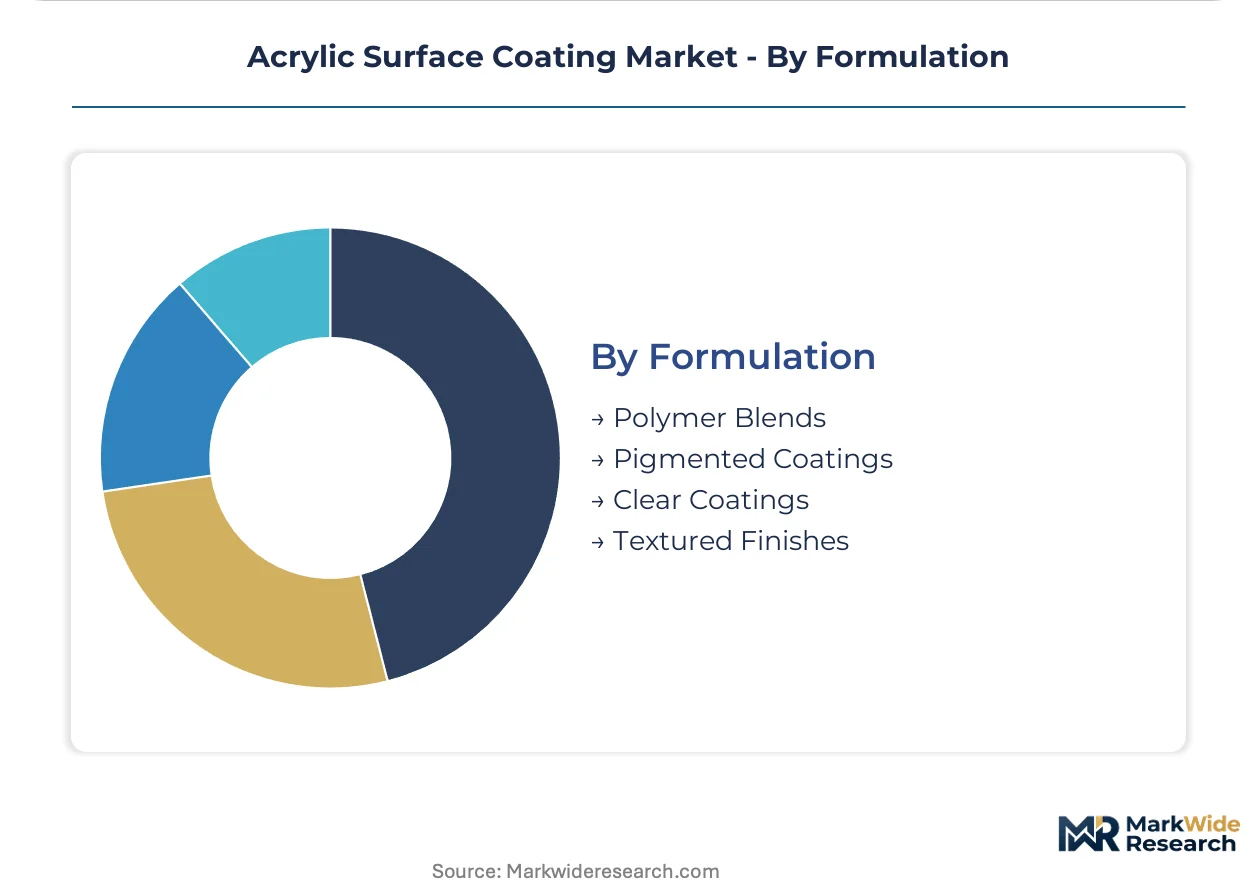
Formulation:
Raw material transparency requirements under ECHA screening are forcing disclosure investments that favor integrated formulators with captive resin networks.
- Polymer Blends:Hybrid acrylic-urethane or acrylic-alkyd systems combining durability with application versatility for industrial maintenance and specialty architectural segments.
- Pigmented Coatings:Opaque finishes with titanium dioxide and colorant dispersions for aesthetic and protective coverage across architectural and industrial applications.
- Clear Coatings:Transparent protective films preserving substrate appearance while delivering UV and chemical resistance, dominating automotive OEM specification programs.
- Textured Finishes:Aggregate-modified coatings for slip resistance and aesthetic depth in commercial flooring and exterior cladding applications.
Pigmented coatings anchor the formulation volume base while clear coatings capture the steepest specification-grade margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese automotive coating specifications while Chinese architectural volume competes on scale. European regulatory compliance costs compress margins in solvent-based segments. India's PLI scheme is attracting formulator investment into industrial corridors.
United States
Automotive OEM clear coat programs and residential renovation cycles drive coating demand. EPA 40 CFR Part 59 constrains solvent-based architectural formulations. Industrial clusters in Michigan and Ohio concentrate specification-grade supply relationships with domestic automakers.
Germany
Premium vehicle assembly mandates UV-resistant thermosetting clear coats for extended warranty coverage. REACH registration requirements and EU Green Deal timelines compress VOC thresholds. The Rhine-Ruhr industrial corridor anchors formulation R&D and automotive supply chain integration.
China
State-directed infrastructure investment in transportation hubs and commercial construction scales architectural consumption. MEE enforcement of GB VOC standards redirects demand toward water-based systems. Yangtze River Delta manufacturing clusters absorb the fastest capacity expansion for industrial finishes.
Japan
Automotive OEMs consolidate specification-grade programs around qualified resin suppliers. METI oversees chemical substance management aligning with international regulatory convergence. Kanto and Kansai industrial regions concentrate high-performance coating development for export markets.
India
Domestic manufacturing incentives and commercial construction expansion concentrate demand in Gujarat and Maharashtra. The PLI scheme for coating capacity attracts multinational formulator investment. Tiered contractor loyalty programs lock distribution influence among integrated regional players.
Acrylic Surface Coating Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and additive supply. The market structures around consolidated multinational formulators with captive distribution networks and fragmented regional applicators. Three archetypes dominate: integrated chemical conglomerates with backward resin control, specialty coating formulators with specification-grade automotive relationships, and regional distributors bundling supply with equipment access. Competitive moves concentrate on strategic partnerships for regulatory compliance and capacity expansion into PLI-subsidized Indian corridors.
Among integrated chemical conglomerates, BASF SE and PPG Industries Inc. exemplify the archetype combining captive resin networks with specification influence across automotive OEM programs. Akzo Nobel N.V. occupies a position within European water-based technology leadership, anchoring architectural segment reformulation ahead of ECHA screening timelines. These three entities represent the dominant competitive anchors shaping margin stability through raw material cycle volatility.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Asian Paints Ltd. |
| BASF SE |
| Jotun A/S |
| Nippon Paint Holdings Co Ltd |
| The Sherwin-Williams Company |
| Sika AG |
| Axalta Coating Systems LLC |
| PPG Industries Inc. |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters absorb the fastest capacity expansion for water-based acrylic systems, concentrating supply-side leverage among integrated formulators with captive resin networks and compressing margins for mid-scale competitors dependent on spot monomer purchases.
Pricing Analysis
Configured-to-order pricing for specification-grade automotive clear coats commands substantial premiums over standard architectural formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade, with OEM-qualified systems capturing margin multiples against commodity volume plays. Pricing pressure stems from propylene and MMA feedstock volatility squeezing formulation economics. DIY consumers in North American retail channels exhibit highest price sensitivity, while German automotive OEMs demonstrate lowest sensitivity due to warranty-driven specification lock-ins.
Supply Chain Analysis
Upstream acrylic monomer production concentrates in China, Germany, and the United States, with propylene oxidation facilities anchoring regional supply basins. Formulation draws from MMA, acrylic acid, and specialty additive feedstocks, with perfluorinated surfactant dependencies exposed to EU F-Gas Regulation phase-out timelines. Single-source vulnerability runs through German and Japanese automotive resin qualification programs that lock out secondary suppliers. Distribution runs through integrated distributors bundling coating supply with equipment leasing in South Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification-grade coating programs are coalescing around platform-economics dynamics where captive resin networks and OEM qualification systems create interoperability moats that compound competitive advantage over multi-year warranty cycles.
For Market Incumbents: Build captive supply moats through backward integration into acrylic monomer production or long-term offtake agreements with propylene crackers. Consolidate specification influence by deepening OEM qualification relationships in German and Japanese automotive programs. Defend against water-based technology disruption by accelerating reformulation ahead of ECHA screening timelines. Prioritize channel control through tiered contractor loyalty programs in Gujarat and Maharashtra corridors. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized manufacturing corridors where domestic capacity incentives attract formulator investment without incumbent distribution lock-in. Target UV-curable acrylic convergence segments in electronics and furniture finishing where qualification timelines remain shorter than automotive programs. Penetrate Southeast Asian markets through asset-light equipment leasing partnerships that bypass capital barriers for mid-scale contractors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specification-grade automotive relationships and captive resin networks compound margin stability across raw material cycles. Acquisition targets should display backward integration into monomer supply or locked OEM qualification status with German or Japanese manufacturers. Watch for inflection signals in ECHA substance restriction announcements that force accelerated reformulation investments and separate integrated formulators from dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Captive MMA production insulates margin stability against propylene price volatility cycles. |
| OEM Qualification Program Expansion | German and Japanese automotive warranty mandates lock in five-to-seven-year specification cycles. |
| Water-Based Technology Transition | Reformulation ahead of REACH and EU Green Deal thresholds captures regulatory compliance premium. |
| Asset-Light Equipment Leasing Rollout | Bundled machinery access locks volume commitments from mid-scale contractors in India and Vietnam. |
| PLI Corridor Capacity Buildout | Domestic manufacturing incentives in Gujarat and Maharashtra attract formulator investment at subsidized cost structures. |
Methodological Framework
Operator-level perspectives from plant managers, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed formulators, and MEE enforcement records for GB VOC standards. Bottom-up volume modeling triangulated against top-down market sizing across chemistry platforms and end-use verticals.
Scenario-bracketing framed the analytical approach across conservative, baseline, and expansion assumptions over the projection horizon. Segmentation dimensions modeled include chemistry type, application vertical, formulation grade, and regional production hub cluster. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and capacity expansion timelines. Forecast inputs incorporated OEM specification cycle durations, monomer price elasticity coefficients, and PLI subsidy absorption rates for Indian manufacturing corridors.
Stress conditions across propylene feedstock volatility, REACH substance restriction acceleration, and Chinese infrastructure investment cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and OEM warranty program continuity. Cross-checking against customs trade data and Cefic production statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Cellulosic Fire Protection Intumescent Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Global Metal Coatings Market
Coatings
Hydrophilic Coatings Market
Coatings
Clear Coatings Market
Coatings
Dispersion Coating Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
Soft Touch Polyurethane Coatings Market
Coatings
Bio-Based Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Transparent Conductive Coatings Market
Coatings
Gelcoat Market
Coatings
Global Plastic Coatings Market
Coatings
Fluoropolymer Coating Market