
 Non-Ionic Polyacrylamide Market | 2026-2036
Non-Ionic Polyacrylamide Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Ionic Polyacrylamide Market Analytics
China is reshaping supply dynamics through capacity additions in Shandong and Jiangsu provinces. SNF Group leverages backward integration into acrylamide monomer production to secure feedstock costs. BASF SE sustains technology leadership in high-molecular-weight emulsion formulations for oilfield applications. Kemira Oyj anchors European water treatment demand through long-term municipal contracts.
Non-ionic polyacrylamide is a water-soluble polymer synthesized through free-radical polymerization of acrylamide monomer without ionic charge modification, typically achieving molecular weights between 5 and 20 million Daltons for optimal flocculation bridging. Its primary commercial purpose centers on solid-liquid separation processes where charge-neutral suspension stability requires non-electrostatic destabilization mechanisms. Powder grades dominate volume consumption in mining tailings management due to storage stability and freight efficiency, while emulsion formulations command margin premiums in offshore oil recovery where rapid hydration kinetics prove critical. Water treatment applications anchor baseline demand across municipal and industrial effluent sectors.
EPA National Pollutant Discharge Elimination System permits and China's MEE wastewater discharge standards are tightening total suspended solids limits, directly expanding specified polymer dosages in treatment protocols. REACH registration requirements in Europe restrict monomer residual thresholds, favoring producers with advanced purification infrastructure. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification portfolios with regional compliance thresholds.
Market Dynamics
Water treatment utilities in China are expanding procurement of non-ionic polyacrylamide for sludge dewatering applications, while stricter EPA discharge standards in the United States compel industrial facilities to upgrade flocculation systems. This dual regulatory pressure is compressing product certification timelines and reshaping supply allocation.
Growth Catalysts
- EPA National Pollutant Discharge Elimination System:Tightening total suspended solids limits directly expand specified polymer dosages in municipal and industrial effluent protocols across the United States.
- Shandong province capacity expansion:Local Chinese manufacturers have scaled emulsion-grade production, reducing import dependency for water treatment utilities in East Asia.
- Oilfield enhanced oil recovery:Offshore platforms require rapid-hydration emulsion formulations for produced water treatment, creating specialized demand pull.
Market Restraints
- Acrylamide monomer price volatility:Feedstock cost swings compress margin stability for non-integrated producers lacking backward integration into monomer production.
- REACH registration thresholds:Europe's residual monomer limits favor producers with advanced purification infrastructure, creating compliance barriers for smaller manufacturers.
- Natural flocculant substitution:Chitosan and starch-based alternatives gain traction in food-grade and sensitive ecological applications.
Strategic Opportunities
- India's municipal water infrastructure:Underpenetrated urban sewage treatment capacity offers expansion vectors as BIS standards tighten discharge parameters.
- Digital dosing systems convergence:Integration of polymer feed systems with IoT-enabled flow monitoring enables precision consumption models.
- EU Green Deal procurement mandates:Public tender preferences for low-carbon manufacturing processes reward producers with verified carbon footprint reductions.
Industry Challenges
- Polymer chemist talent scarcity:Specialized expertise in high-molecular-weight emulsion synthesis remains concentrated among legacy technical workforces in Germany and Japan.
- Legacy system integration friction:Municipal treatment plants face capex barriers when retrofitting automated polymer make-down equipment into existing sludge handling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Ionic Polyacrylamide Market |
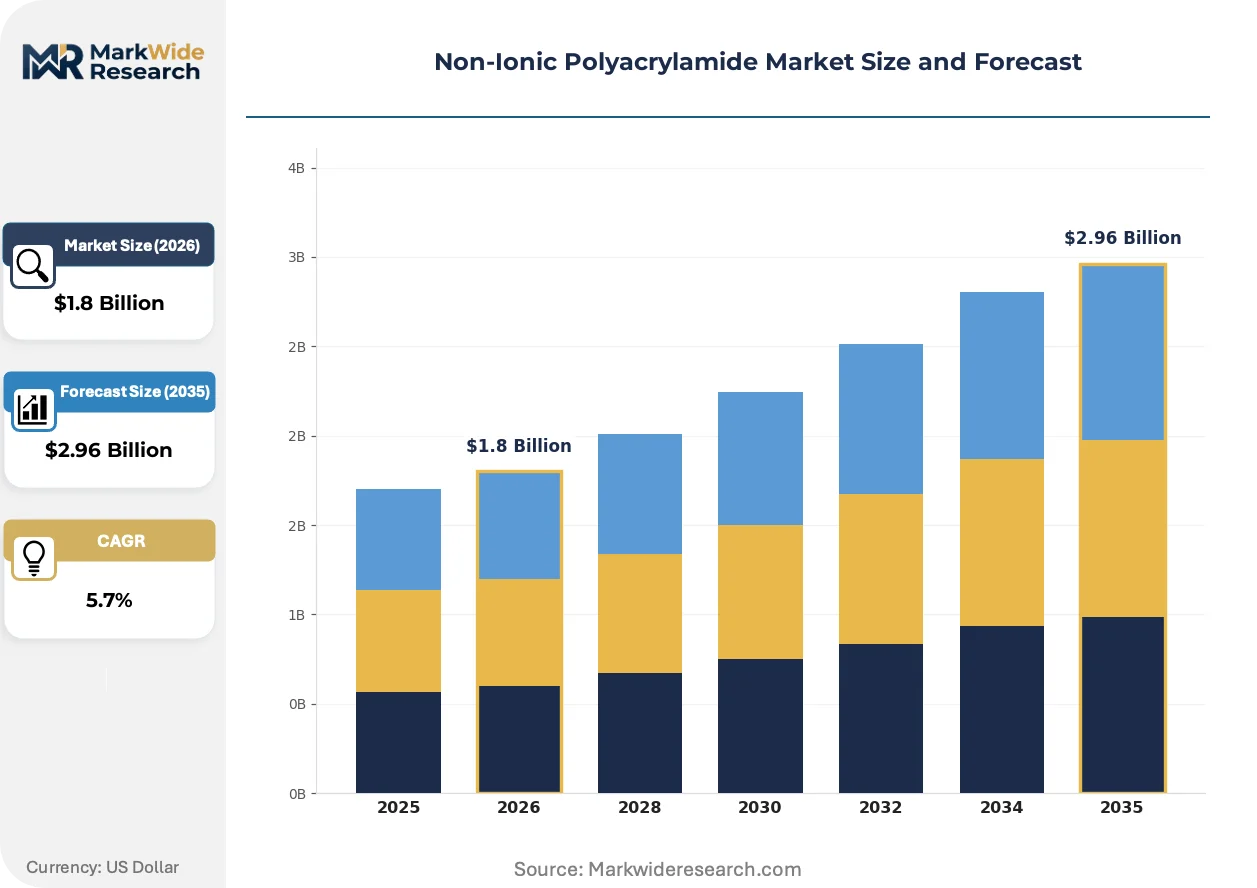
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granular, Powder, Emulsion, Liquid Application: Water Treatment, Oil Recovery, Agriculture, Paper Making End User: Chemical Industry, Food Processing, Construction, Mining Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | SNF Group, BASF SE, Kemira Oyj, Anhui Jucheng Fine Chemicals Co., Ltd., Ashland Inc., Solvay S.A., Shandong Polymer Bio-Chemicals Co., Ltd., Xitao Polymer Co., Ltd., Black Rose Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Ionic Polyacrylamide Market Evolving Landscape
Process intensification in polymer manufacturing is compressing batch cycle times while digitalization of dosing systems enables real-time optimization. These shifts are redefining competitive differentiation beyond molecular weight specifications.
Continuous flow reactor technology for polyacrylamide synthesis is virtualizing traditional batch production economics. Specialty chemical manufacturers in the Netherlands and Japan are adopting these systems to reduce solvent waste and improve molecular weight distribution control. The technology is virtualizing capital efficiency benchmarks for mid-scale producers.
China's MEE wastewater discharge standards are tightening COD and suspended solids parameters for industrial clusters in the Yangtze River basin. Chemical processing and textile dyeing facilities must upgrade clarification systems, directly expanding specified polymer dosages in treatment protocols. Shandong and Jiangsu provinces are witnessing accelerated specification updates in municipal procurement tenders.
Water treatment utilities are consolidating supplier relationships toward integrated service contracts bundling polymer supply with technical dosing optimization. Industrial end-users in the United States are displacing transactional procurement with performance-guaranteed arrangements. This pattern concentrates procurement volume among producers with field service capabilities in the Great Lakes and Gulf Coast manufacturing corridors.
Non-Ionic Polyacrylamide Market Segmentation
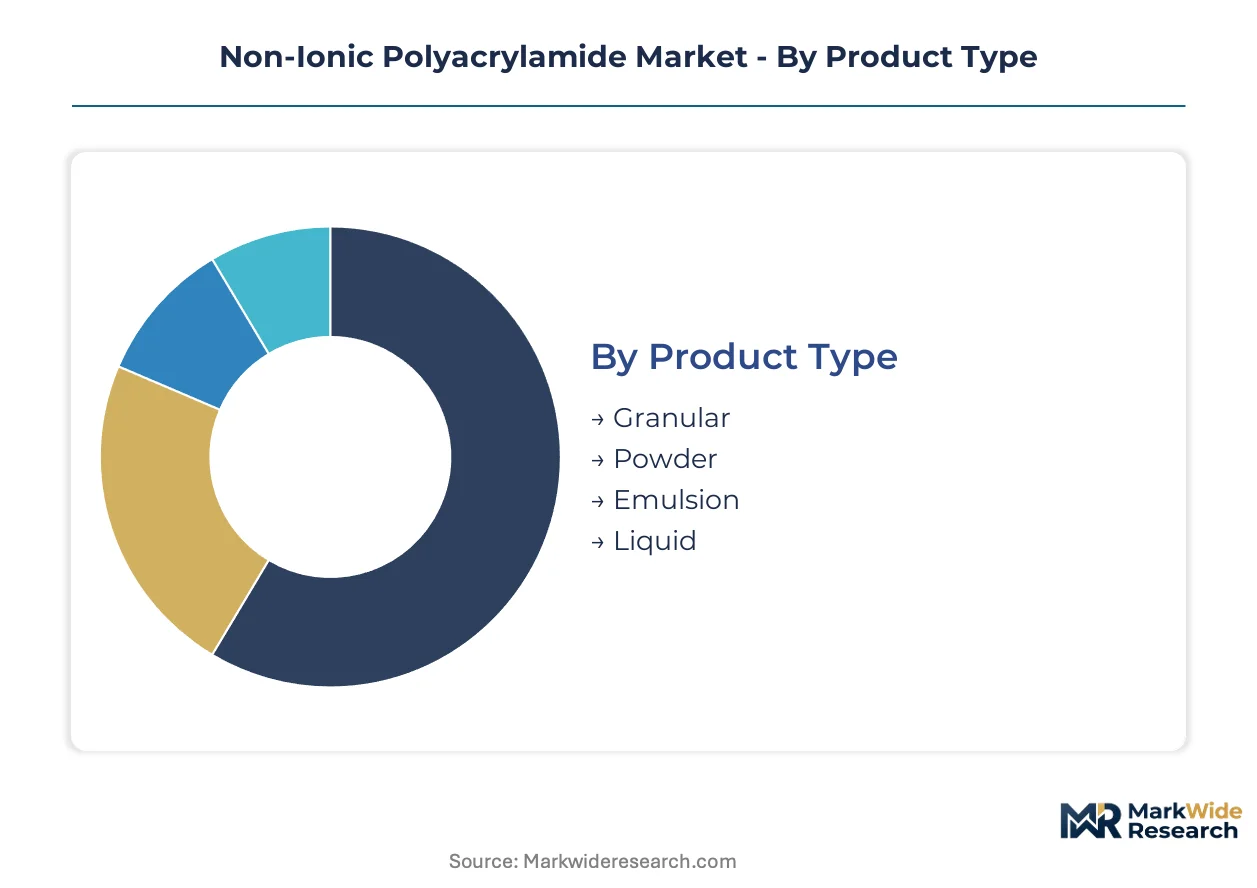
Segmentation in non-ionic polyacrylamide markets reveals distinct technical service requirements across product forms and end-use intensities. Each category carries differentiated margin profiles driven by formulation complexity and customer integration depth.
Product Type:
After-sales-service intensity varies sharply across physical forms, with emulsion grades demanding field technical support for hydration system calibration while powder grades require minimal ongoing intervention.
- Emulsion:High-molecular-weight polymer dispersed in hydrocarbon carrier with rapid inversion kinetics. Offshore oil platforms in the Gulf of Mexico specify emulsion formulations for produced water treatment, where hydration speed determines operational uptime. Technical service teams co-locate with major EOR operators to optimize dosing protocols.
- Powder:Spray-dried polymer with 90%+ active content and extended shelf stability. Mining tailings operations in Western Australia prefer powder grades for containerized freight efficiency and bulk storage in remote locations. Dust control and dissolution equipment commissioning represent primary service touchpoints.
- Granular:Controlled particle size distribution for automated make-down systems. Municipal water utilities in Germany deploy granular grades for continuous sludge dewatering operations.
- Liquid:Pre-hydrated solution with immediate availability but elevated freight costs. Food processing facilities in Japan specify liquid forms for rapid deployment in wastewater pre-treatment.
Powder holds the largest share; momentum sits with emulsion grades in specialized oilfield applications.
Application:
Cost tier stratification separates commodity water treatment from premium oil recovery segments, with pricing spreads reflecting formulation precision and performance guarantees.
- Water Treatment:Municipal and industrial effluent clarification, sludge thickening, and dewatering operations. China's Yangtze River basin industrial clusters are expanding polymer specifications under tightened MEE discharge standards. Procurement concentrates among state-owned water utilities with multi-year framework agreements.
- Oil Recovery:Enhanced oil recovery through polymer flooding and produced water treatment. North Sea platforms require rapid-hydration emulsions with molecular weight precision above 18 million Daltons. Technical performance contracts tie supplier compensation to oil recovery coefficients.
- Agriculture:Soil conditioning and irrigation water management. Israeli drip irrigation systems specify low-dust powder grades for incorporation into fertigation protocols.
- Paper Making:Retention and drainage aids in pulp processing. Scandinavian integrated mills favor high-purity grades with minimal monomer residual for food-contact paperboard.
Water treatment commands volume leadership; oil recovery delivers steepest expansion trajectory through EOR deployment.
End User:
Customer type differentiation separates process-integrated chemical producers from project-based construction and mining buyers with discrete procurement cycles.
- Chemical Industry:Process water recycling and effluent polishing in petrochemical and specialty chemical manufacturing. BASF's Ludwigshafen complex operates captive polymer make-down systems with automated dosing control.
- Mining:Tailings thickening and process water recovery. Copper operations in Chile deploy high-molecular-weight powder grades for acid mine drainage treatment.
- Construction:Tunneling slurry treatment and foundation dewatering. Urban rail projects in India specify polymer flocculation for bentonite recovery.
- Food Processing:Wastewater pre-treatment with strict monomer residual limits. EU facilities require REACH-compliant grades with verified purification certificates.
Chemical industry integration runs deepest; mining exhibits the most volatile demand cyclicality tied to commodity prices.
Distribution Channel:
Supply concentration favors direct relationships for volume accounts while fragmented regional distributors serve smaller municipal and industrial facilities.
- Direct Sales:Producer-to-end-user contracts with embedded technical service and inventory management. SNF Group maintains direct sales teams co-located with major water utilities in France and the United States.
- Distributors:Regional stocking with localized technical support for mid-scale industrial accounts. German specialty chemical distributors serve Mittelstand manufacturers with just-in-time powder deliveries.
- Wholesalers:Bulk aggregation for commodity grades with minimal value-added services. Chinese trading companies consolidate Shandong production for domestic redistribution.
- Online Retail:Emerging channel for small-volume liquid and powder grades. Japanese industrial procurement platforms list standardized grades for research and pilot-scale applications.
Direct sales capture value concentration; distributors expand geographic reach fastest in underpenetrated markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA discharge standards and China's MEE wastewater regulations are compressing certification timelines across the two dominant procurement jurisdictions. Industrial clusters in Shandong province and the US Gulf Coast are expanding polymer specifications simultaneously.
United States
EPA National Pollutant Discharge Elimination System permits are tightening total suspended solids limits for municipal and industrial effluent. Industrial facilities in Texas and Louisiana must upgrade flocculation systems to meet revised discharge parameters. The Gulf Coast manufacturing corridor is consolidating supplier relationships toward performance-guaranteed service contracts.
China
MEE wastewater discharge standards are tightening COD and suspended solids parameters for industrial clusters in the Yangtze River basin. Shandong province manufacturers have scaled emulsion-grade production capacity, reducing import dependency for East Asian water treatment utilities. Chemical processing and textile dyeing facilities in Jiangsu province are accelerating specification updates in municipal procurement tenders.
Germany
REACH registration requirements restrict acrylamide monomer residual thresholds, favoring producers with advanced purification infrastructure. Municipal water utilities deploy granular grades for continuous sludge dewatering operations. The Ruhr industrial region maintains stringent effluent protocols that specify high-purity polymer formulations.
India
BIS standards are tightening discharge parameters for underpenetrated urban sewage treatment capacity. Urban rail projects in Maharashtra and Karnataka specify polymer flocculation for bentonite recovery in tunneling slurry treatment. State water boards are expanding framework agreements for integrated chemical supply contracts.
Japan
METI industrial water recycling mandates are expanding process water recovery specifications for chemical and electronics manufacturing. Food processing facilities in the Kanto region specify liquid forms for rapid deployment in wastewater pre-treatment. The country's national chemical regulator maintains strict monomer residual verification protocols.
Non-Ionic Polyacrylamide Market Competitive Landscape
Capability concentration sits with integrated manufacturers controlling acrylamide monomer supply; scale advantage sits with regional emulsion specialists serving oilfield and mining accounts. The vendor base separates into three tiers: backward-integrated multinationals, province-level Chinese producers, and application-focused service bundlers. Dominant competitive moves include capacity expansion in Shandong and Jiangsu provinces and the displacement of transactional procurement with performance-guaranteed arrangements.
Within the integrated multinational tier, SNF Group and BASF SE exemplify archetypes combining captive monomer production with field technical service capabilities. Among China-based specialists, Shandong Polymer Bio-Chemicals Co., Ltd. and Xitao Polymer Co., Ltd. occupy positions scaling emulsion-grade output for domestic water treatment demand. These groupings represent the primary competitive fault lines separating feedstock-integrated producers from regional formulation specialists.
| Leading Market Players |
|---|
| SNF Group |
| BASF SE |
| Kemira Oyj |
| Anhui Jucheng Fine Chemicals Co., Ltd. |
| Ashland Inc. |
| Solvay S.A. |
| Shandong Polymer Bio-Chemicals Co., Ltd. |
| Xitao Polymer Co., Ltd. |
| Black Rose Industries Ltd. |
| Others |
Value Network & Pricing Analysis
Shandong province's emulsion-grade capacity expansion has compressed regional price premiums while amplifying pricing power for backward-integrated multinationals serving oilfield accounts. The supply-demand balance in East Asia now dictates benchmark formation for powder grades consumed in mining tailings operations.
Pricing Analysis
Contract-based long-term offtake dominates procurement for municipal water utilities, while spot transactions persist for mining and construction project work. Price differentiation rests on certification grade—REACH-compliant emulsions with sub-500 ppm monomer residual command substantial premiums over standard industrial grades. Pricing pressure stems from Shandong manufacturers' aggressive capacity additions in emulsion formulations. Mining operators exhibit highest price sensitivity due to commodity-linked capex cycles, whereas offshore oil platforms prioritize hydration kinetics over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with SNF Group and BASF SE facilities in France, Germany, and the United States. Geographic supply concentration centers on China, France, and the United States, with Shandong and Jiangsu provinces anchoring Asian output. Feedstock dependencies include acrylamide monomer, hydrocarbon carrier fluids, and initiator chemicals. Single-source vulnerability runs through acrylamide monomer supply where non-integrated producers lack captive production. Distribution runs through direct sales teams for major water utilities and regional distributors for mid-scale industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from chitosan and starch-based flocculants in food-grade and ecological-sensitive applications, requiring active portfolio defense.
For Market Incumbents: Pre-empt natural flocculant substitution by securing REACH-compliant purification infrastructure and embedding field technical teams with major municipal utilities. Backward integration into acrylamide monomer production remains essential for margin defense against Shandong capacity expansions. Long-term supply agreements with Yangtze River basin industrial clusters lock in volume against regional Chinese competitors.
For New Entrants and Emerging Players: India's underpenetrated municipal sewage treatment infrastructure represents the most penetrable entry point, particularly state water boards in Maharashtra and Karnataka expanding framework tender programs. Specialized emulsion formulations for offshore EOR operators in the Gulf of Mexico offer premium positioning away from commodity water treatment competition. Go-to-market success requires co-locating technical service capabilities with major operator clusters rather than distributor-dependent models.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service contract providers bundling polymer supply with dosing optimization and equipment commissioning. Long-term viability over the projection horizon favors targets with verified low-carbon manufacturing processes aligned to EU Green Deal procurement mandates. The signal to watch is municipal tender specification shifts toward performance-guaranteed arrangements displacing transactional procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylamide monomer production insulates margin stability from feedstock volatility. |
| Capacity Expansion | Shandong and Jiangsu province additions reshape supply allocation across East Asian utilities. |
| Long-term Supply Agreement | Multi-year municipal frameworks in France and the United States concentrate procurement volume. |
| Green Manufacturing Transition | Verified carbon footprint reductions unlock EU Green Deal public tender preferences. |
| Joint Venture | Regional partnerships in India enable technical service co-location with state water boards. |
Research Methodology
Desk research of trade customs data, EPA discharge permit filings, and MEE regulatory updates preceded structured interviews with polymer plant managers, municipal procurement directors, oilfield chemical supply leads, and distribution channel partners. Primary fieldwork across the United States, China, Germany, and India validated secondary estimates of capacity utilization and specification trends. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers anchored the value forecast.
Assumptions held regulatory stringency trajectories and crude oil price bands fixed while varying industrial production indices and mining capex cycles across scenarios. The analytical framework modeled product form, end-use industry, and regional production hub dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted volume projections incorporating polymer dosage coefficients under tightening discharge standards. Forecast inputs included municipal wastewater treatment capacity expansion pipelines and offshore platform development backlogs.
Practitioners should monitor acrylamide monomer price volatility and natural flocculant certification progress for early signals of margin compression or substitution acceleration. Forecasts reflect assumptions about MEE and EPA regulatory enforcement continuity and EOR deployment rates. Quarterly review of municipal tender specification updates and Shandong capacity utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Circular Polymers Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Europe Engineering Plastics Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market