
 Germany Polymer Emulsion Market | 2026-2036
Germany Polymer Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Polymer Emulsion Market Foresight
Automotive suppliers is rotating toward high-performance acrylic emulsions for interior trim and underbody coatings, displacing traditional solvent-based systems in volume terms. BASF SE anchors this transition through its Ludwigshafen manufacturing complex, where captive monomer supply sustains cost discipline across acrylic and styrene butadiene grades. Wacker Chemie AG specializes in vinyl acetate ethylene emulsions for construction adhesives, leveraging its Burghausen silicones-to-polymers integration to control raw material pathways.
Germany polymer emulsion denotes a colloidal dispersion of polymer particles in water, typically manufactured through batch or semi-continuous emulsion polymerization at solids contents of 40-60 percent, serving as binders in coatings, adhesives, and nonwoven textiles. Acrylic formulations dominate value capture in paints coatings due to superior weatherability and UV resistance, while vinyl acetate ethylene maintains volume leadership in construction chemicals where cost elasticity drives specification. Styrene butadiene competes intensely in paper industry applications, though margin compression from Asian imports limits domestic expansion.
Germany's Federal Institute for Risk Assessment and the EU REACH framework enforce strict residual monomer limits and hazard classification protocols that elevate compliance costs for imported emulsions. The EU Green Deal and national packaging ordinances additionally pressure suppliers to validate biodegradability claims and reduce plastic-intensive packaging formats. Stakeholders must monitor how the EU's forthcoming microplastics restriction reshapes formulation standards for textile coating and leather finishing segments before committing capital to capacity additions.
Market Dynamics
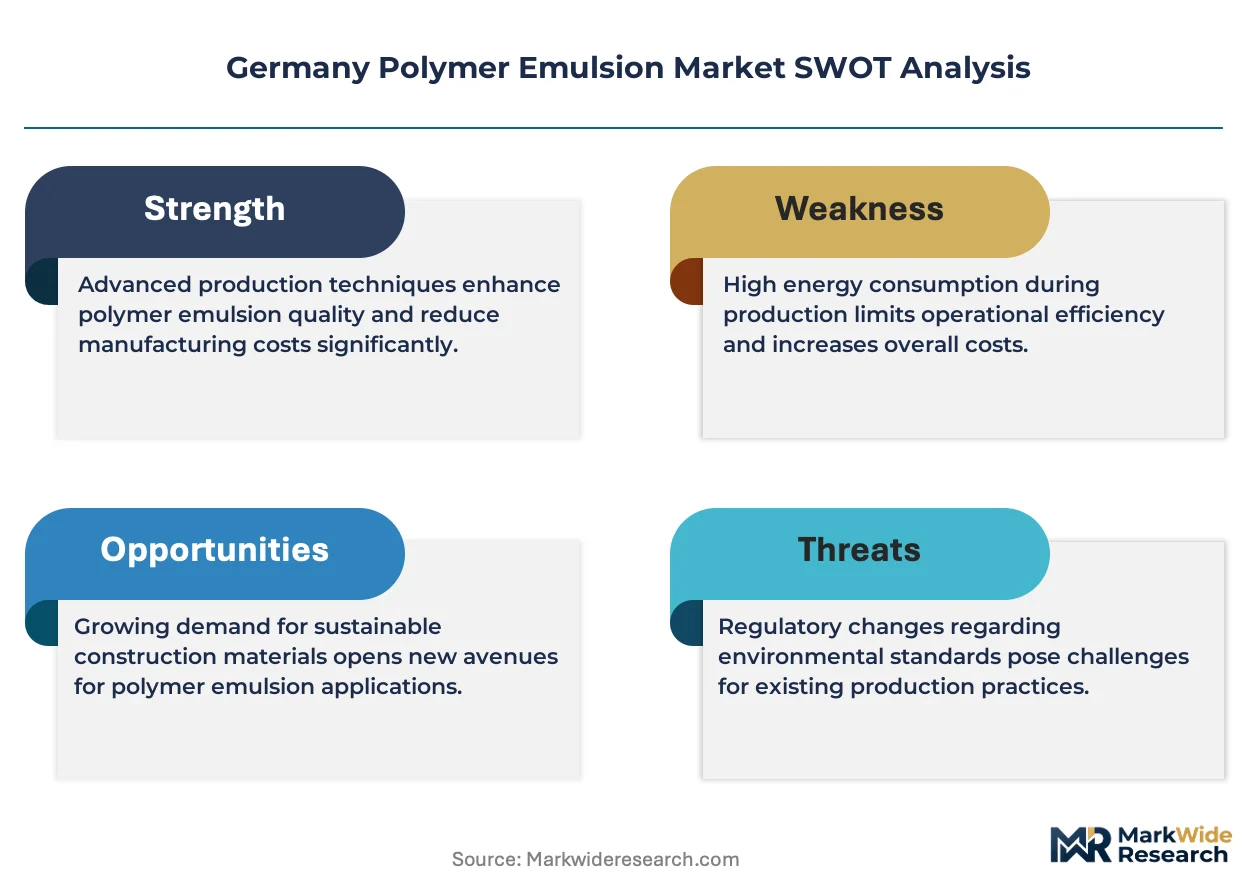
Water-based polymer emulsions are displacing solvent-borne systems across automotive interior coatings and construction adhesives, driven by EU REACH VOC limits and Germany's Chemicals Act enforcement. This transition concentrates procurement power among integrated monomer producers in the Rhine-Neckar and Upper Bavaria chemical corridors.
Growth Catalysts
- EU REACH Phase-Down:Tightening residual monomer limits force coating formulators to source low-VOC acrylic emulsions, expanding specification windows for domestic producers.
- Automotive Lightweighting:Interior trim manufacturers adopt high-performance styrene-butadiene emulsions for foam-backed fabrics, replacing heavier solvent-bonded laminates.
- Baden-Württemberg Cluster Density:Proximity between BASF Ludwigshafen and Mercedes-Benz Sindelfingen compresses logistics costs for just-in-time emulsion delivery.
Market Restraints
- Asian Import Pressure:Styrene-butadiene emulsions from South Korean and Chinese producers undercut domestic margins in paper coating applications.
- Propylene Oxide Volatility:Acrylic emulsion producers face margin compression when propylene feedstock costs spike, as Germany lacks integrated propylene dehydrogenation capacity.
- Microplastics Uncertainty:Pending EU restrictions on synthetic polymer microparticles in textile coatings create formulation freeze among leather finishing compounders.
Strategic Opportunities
- Bio-Based Monomer Integration:Fermentation-derived acrylic acid from Braskem's European pilot facilities enables carbon-negative emulsion claims for packaging adhesives.
- North Rhine-Westphalia Construction Chemicals:Infrastructure stimulus programs in the Ruhr region expand specification volume for vinyl acetate-ethylene tile adhesives.
- Digital Color Matching:AI-driven spectrophotometry reduces reformulation cycles for custom automotive interior shades, compressing customer acquisition costs.
Industry Challenges
- Emulsion Polymerization Expertise Gap:Retiring process engineers in Bavaria and Saxony-Anhalt outpace university polymer chemistry graduates, delaying plant debottlenecking projects.
- REACH Registration Costs:Small and mid-sized importers struggle with SIEF consortium fees for novel copolymer compositions, ceding share to established registrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Polymer Emulsion Market |
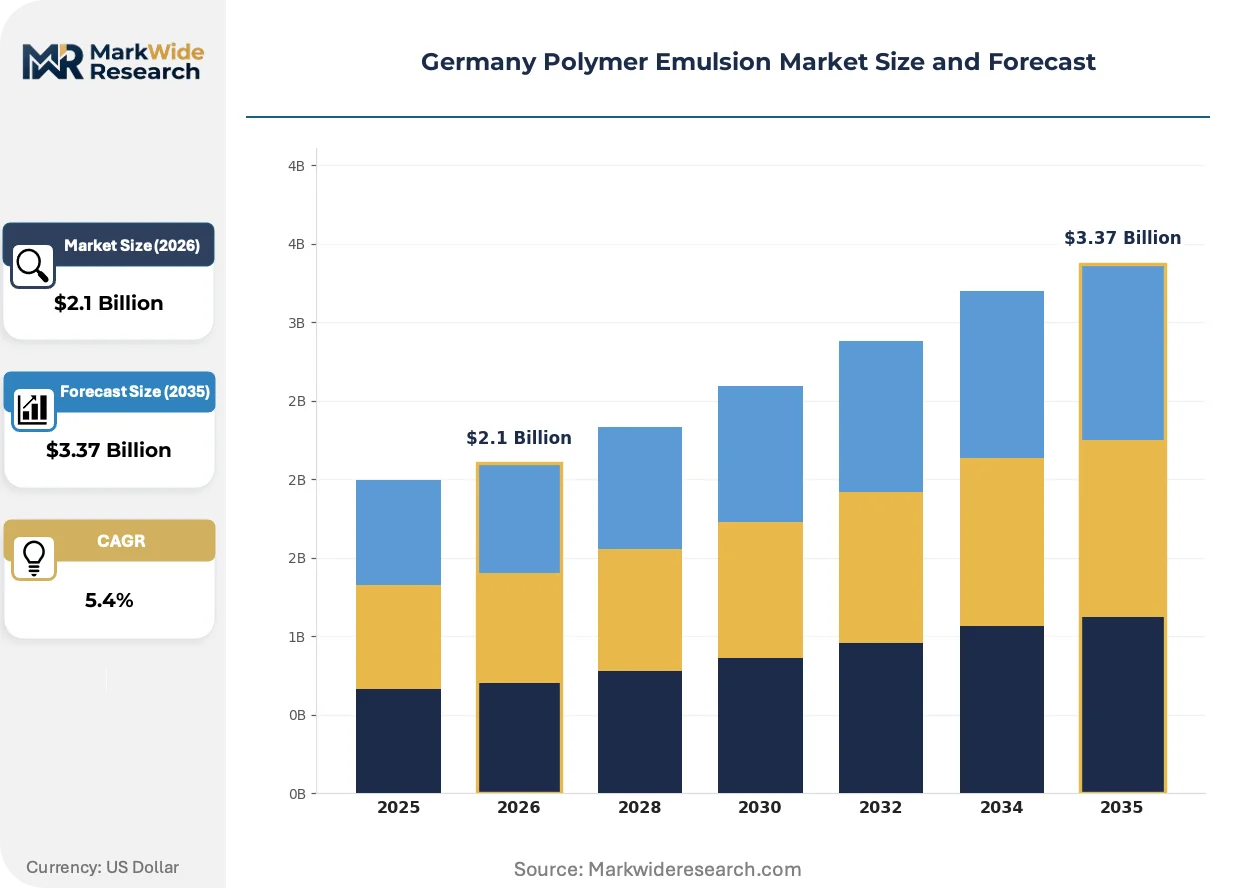
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene Butadiene, Vinyl Acetate Ethylene, Acrylic, Polyvinyl Acetate, Ethylene Vinyl Acetate, Polyacrylic Application: Adhesives Sealants, Textile Coating, Paints Coatings, Paper Industry, Construction Chemicals, Leather Finishing End User Industry: Building Materials Manufacturers, Textile Producers, Packaging Firms, Automotive Suppliers, Footwear Manufacturers, Furniture Makers Packaging Type: Drums, Intermediate Bulk Containers, Pails, Totes, Bags, Carboys |
| Companies Covered | BASF SE, Wacker Chemie AG, Arkema Group, Akzo Nobel N.V., Clariant, Dow, Celanese Corporation, Asahi Kasei Corporation, Solvay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Polymer Emulsion Market Shifts & Advancements
Formulation science is pivoting toward bio-attributed feedstocks and closed-loop water recovery, while digital tools compress development cycles. These shifts favor integrated producers with captive monomer supply and in-house application testing laboratories.
Hybrid acrylic-silicone emulsions are supplanting conventional pure-acrylic binders in exterior wood coatings. German window and façade manufacturers specify these materials for 20-year durability guarantees. The technology is compressing warranty claim reserves across the building chemicals sector.
Germany's Chemicals Act transposes EU REACH amendments on polymer registration thresholds, elevating compliance costs for imported specialty emulsions. Domestic compounders with existing REACH dossiers capture specification share in textile coating applications. The leather finishing segment faces the steepest re-registration burden.
Automotive tier-one suppliers now require lot-level carbon footprint certificates from emulsion vendors, displacing price-only procurement matrices. BMW Group and Volkswagen AG sourcing teams audit Scope 3 emissions back to monomer production. This behavioral shift concentrates volume among producers with renewable energy PPAs in Rhineland-Palatinate.
Germany Polymer Emulsion Market Segmentation
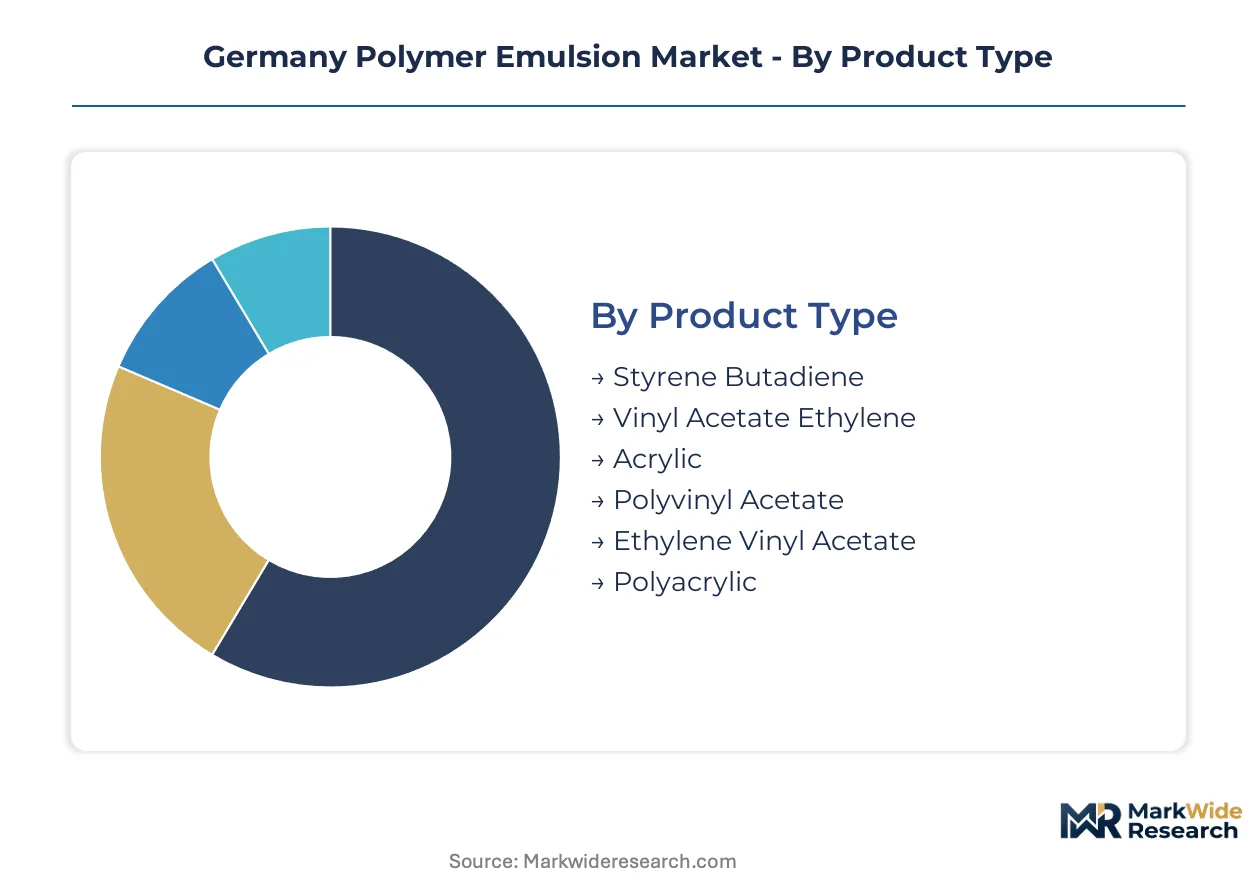
Segmentation in Germany's polymer emulsion market reveals how regulatory pressure and end-use specifications fragment procurement patterns. Each dimension exposes different vulnerability to substitution, cost pass-through capability, and compliance burden intensity.
Product Type:
Styrene butadiene faces the most acute substitution pressure from Asian imports, while acrylic grades benefit from captive domestic monomer supply that insulates them from direct displacement.
- Acrylic:These emulsions incorporate methacrylate and acrylate monomers in copolymer architectures delivering superior UV resistance and color retention. Demand concentrates in exterior architectural coatings across Rhineland-Palatinate, where facade manufacturers specify 20-year durability guarantees under Germany's Energy Saving Ordinance thermal retrofit programs.
- Vinyl Acetate Ethylene:Flexible copolymers with ethylene content between 5-30 percent by weight provide tack and adhesion for construction adhesives. North Rhine-Westphalia infrastructure stimulus drives specification volume for tile adhesives and flooring compounds in the Ruhr urban regeneration corridor.
- Styrene Butadiene:Carboxylated latex grades serve paper coating and carpet backing applications where Asian producers undercut domestic pricing.
- Polyvinyl Acetate:Homopolymer emulsions with limited hydrolysis resistance dominate low-cost woodworking adhesives.
- Ethylene Vinyl Acetate:High-VAE grades with 40-50 percent vinyl acetate content enable heat-seal packaging adhesives.
- Polyacrylic:Crosslinked variants provide solvent resistance for industrial metal coatings.
Vinyl acetate ethylene anchors the volume base while acrylic gains share at the steepest rate.
Application:
Cost tier stratification separates commodity construction applications from premium automotive and textile specifications where formulation complexity commands margin protection.
- Paints Coatings:Architectural and industrial formulations demand emulsions with controlled particle size distribution between 100-300 nanometers for film formation. Baden-Württemberg paint compounders near BASF Ludwigshafen compress logistics costs for just-in-time acrylic delivery to Mercedes-Benz supplier parks.
- Adhesives Sealants:Pressure-sensitive and structural bonding applications require tailored tack and creep resistance profiles. Automotive interior trim laminators in Upper Bavaria specify high-solids styrene-butadiene emulsions to displace solvent-bonded systems under EU REACH VOC phase-down.
- Construction Chemicals:Tile adhesives, waterproofing membranes, and cement modifiers consume volume grades with price elasticity.
- Paper Industry:Coating and sizing applications face margin compression from South Korean import competition.
- Textile Coating:Nonwoven binders and fabric finishing face pending EU microplastics restriction uncertainty.
- Leather Finishing:Topcoat and basecoat formulations carry the steepest REACH re-registration burden among imported specialty grades.
Construction chemicals anchors the volume base while adhesives sealants expands most quickly.
End User Industry:
Customer type concentration determines specification power, with automotive and building materials sectors driving compliance standards that cascade to smaller end users.
- Automotive Suppliers:Tier-one interior trim manufacturers in Sindelfingen and Ingolstadt mandate lot-level carbon footprint certificates from emulsion vendors. BMW Group and Volkswagen AG sourcing teams audit Scope 3 emissions back to monomer production, concentrating volume among producers with renewable energy PPAs.
- Building Materials Manufacturers:Window and facade producers specify hybrid acrylic-silicone emulsions for 20-year warranty coverage. The segment's fragmented customer base limits individual buyer leverage versus integrated chemical suppliers.
- Textile Producers:Nonwoven and technical fabric manufacturers face formulation freeze pending EU microplastics restriction clarity.
- Packaging Firms:Corrugated board and flexible packaging adhesives seek bio-attributed monomer claims for brand owner sustainability mandates.
- Footwear Manufacturers:Synthetic leather and sole bonding applications compete with Asian finished goods import pressure.
- Furniture Makers:Woodworking adhesives represent price-sensitive volume with limited differentiation.
Building materials manufacturers anchors the volume base while automotive suppliers gains share at the steepest rate.
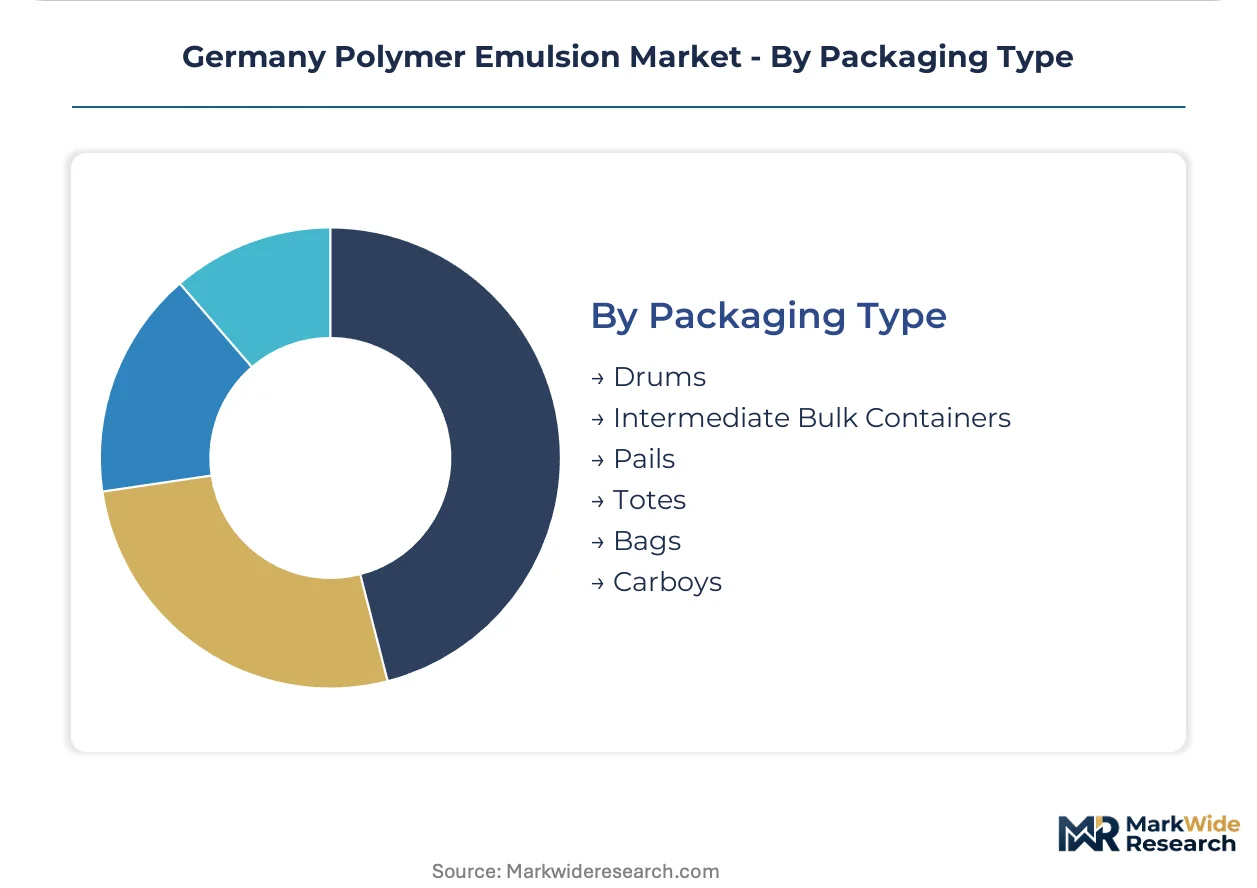
Packaging Type:
Packaging format selection reflects shipment scale and handling infrastructure, with bulk formats dominating integrated chemical corridors and smaller units serving fragmented downstream compounders.
- Intermediate Bulk Containers:1000-liter totes with integrated discharge valves enable pump-to-pump transfer at automotive supplier parks. BASF Ludwigshafen ships IBC quantities direct to Mercedes-Benz Sindelfingen on dedicated tanker circuits, eliminating drum handling labor.
- Drums:200-liter steel and polyethylene drums serve mid-volume paint compounders lacking bulk storage infrastructure. The format maintains share in Saxony-Anhalt where smaller coating manufacturers cluster.
- Totes:Flexible intermediate bulk containers reduce return logistics costs for construction chemical distributors.
- Pails:20-30 liter polyethylene containers target artisan applicators and repair maintenance channels.
- Bags:Powdered redispersible polymer emulsions in multi-layer packaging serve dry-mix mortar producers.
- Carboys:5-25 liter glass or plastic containers preserve sample integrity for laboratory and specialty formulation development.
Drums anchors the volume base while intermediate bulk containers climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube Canal and Rhine River barge network underwrite Germany's polymer emulsion distribution efficiency, connecting Ludwigshafen production basins to industrial clusters across Central Europe with minimal transshipment costs.
Baden-Württemberg
Automotive interior trim manufacturing and exterior facade coatings drive emulsion consumption in this southwestern state. The EU REACH enforcement through Germany's Chemicals Act mandates low-VOC formulations for Mercedes-Benz supplier parks in Sindelfingen. BASF Ludwigshafen ships acrylic emulsions via dedicated tanker circuits to Stuttgart-region automotive compounders.
North Rhine-Westphalia
Infrastructure stimulus programs and urban regeneration in the Ruhr corridor expand specification volume for vinyl acetate-ethylene tile adhesives. The state's building energy retrofit ordinances accelerate demand for high-performance waterproofing membranes. Cologne-Düsseldorf chemical distributors maintain dense storage infrastructure for construction chemical just-in-time delivery.
Bavaria
Upper Bavaria hosts automotive adhesive laminators specifying high-solids styrene-butadiene emulsions to displace solvent-bonded systems under VOC phase-down requirements. The Munich metropolitan area concentrates specialty packaging adhesive formulators seeking bio-attributed monomer claims. Retiring process engineers in this region outpace polymer chemistry graduate supply.
Lower Saxony
Volkswagen Group operations in Wolfsburg and Hannover anchor demand for lot-level carbon footprint certified emulsions in automotive seating and interior applications. The state's wind energy infrastructure supports renewable energy PPAs that satisfy Scope 3 audit requirements from tier-one suppliers. Brunswick-area technical textile producers face formulation freeze pending EU microplastics restriction clarity.
Hesse
Frankfurt-Rhine-Main logistics hubs intermediate between Ludwigshafen production and downstream compounders across southwestern Germany. The region's packaging adhesive sector serves corrugated board and flexible packaging manufacturers with sustainability mandates from brand owners. Darmstadt-area research institutions collaborate on hybrid acrylic-silicone emulsion development for exterior wood coatings.
Germany Polymer Emulsion Market Competitive Landscape
Concentration sits with integrated petrochemical conglomerates possessing captive monomer supply and established REACH dossiers. The market structure exhibits tiered segmentation between multinational chemical majors with Ludwigshafen manufacturing complexes and specialized regional compounders serving fragmented construction chemical distributors. Three archetypes dominate: integrated monomer-to-emulsion producers, application-specific formulation specialists, and import-dependent trading houses facing registration cost barriers. Competitive moves center on backward integration into renewable feedstock sourcing and strategic partnerships with automotive OEMs for carbon footprint certification protocols.
Within the integrated chemical major tier, BASF SE and Wacker Chemie AG exemplify archetypes of captive supply chain control. BASF SE anchors acrylic and styrene-butadiene production through its Ludwigshafen Verbund site with direct pipeline connections to monomer units. Wacker Chemie AG occupies a specialist position in vinyl acetate-ethylene emulsions leveraging Burghausen silicones-to-polymers integration. Arkema Group represents the diversified multinational archetype with European emulsion assets complementing broader specialty materials portfolios.
| Leading Market Players |
|---|
| BASF SE |
| Wacker Chemie AG |
| Arkema Group |
| Akzo Nobel N.V. |
| Clariant |
| Dow |
| Celanese Corporation |
| Asahi Kasei Corporation |
| Solvay |
| Others |
Supply & Pricing Matrix
EU REACH registration dossiers gate both supplier qualification and price differentiation simultaneously, concentrating premium specification among established registrants while Asian imports undercut domestic margins in commodity grades. This dual-gating mechanism compresses mid-tier pricing power and rewards integrated producers with captive monomer supply.
Pricing Analysis
Volume-discount tiering structures stratify across premium REACH-certified, standard domestic-grade, and economy Asian-import levels. Pricing differentiation hinges on carbon footprint certification grade and automotive OEM audit compliance, with BMW Group and Volkswagen AG sourcing teams demanding lot-level Scope 3 documentation. Cost compression in styrene-butadiene paper coating grades is intensifying because South Korean and Chinese producers undercut Ludwigshafen-based supply. Construction chemical distributors show highest price sensitivity, while automotive tier-one suppliers prioritize certification compliance over unit cost.
Supply Chain Analysis
Inbound logistics costs from Rotterdam-Antwerp barge corridors and Rhine River container availability shape procurement economics for Baden-Württemberg automotive compounders. Feedstock concentration draws from Ludwigshafen Verbund complexes, Burghausen silicones integration, and imported Asian monomer streams. Raw material pathways rest on propylene oxide, acrylic acid, and VAE copolymer feedstocks. Single-source vulnerability sits with propylene supply given Germany lacks integrated dehydrogenation capacity. Distribution runs through dedicated tanker circuits to Mercedes-Benz supplier parks and construction chemical distributors in the Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against solvent-borne coating substitution in automotive interiors and Asian import displacement in paper applications. Water-based emulsion specifications are consolidating procurement power among integrated producers with REACH dossiers and renewable energy PPAs.
For Market Incumbents: Secure captive bio-based monomer supply through partnerships with Braskem's European pilot facilities to validate carbon-negative claims for packaging adhesive specifications. Deepen automotive OEM certification protocols by auditing Scope 3 emissions back to renewable energy PPAs in Rhineland-Palatinate. Defensive positioning against Asian styrene-butadiene imports requires emphasizing REACH compliance and lot-level traceability that commodity traders cannot match.
For New Entrants and Emerging Players: Differentiate on bio-attributed feedstock claims for corrugated board and flexible packaging adhesives serving brand owner sustainability mandates. Target North Rhine-Westphalia infrastructure stimulus programs in the Ruhr urban regeneration corridor where vinyl acetate-ethylene tile adhesive specifications are expanding. Go-to-market leverage rests on digital color matching capabilities that compress reformulation cycles for custom automotive interior shades.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across acrylic emulsion capacity additions requiring integrated monomer-to-polymer infrastructure. Long-term viability over the next decade favors producers with existing REACH dossiers and captive renewable energy supply. Acquisition targets should exhibit application-specific formulation expertise in textile coating or leather finishing segments. The signal to watch is clarity on EU microplastics restrictions that would trigger formulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Monomers | Fermentation-derived acrylic acid from Braskem enables carbon-negative emulsion claims for sustainable packaging. |
| Automotive OEM Carbon Certification Partnership | Lot-level Scope 3 audits by BMW Group and Volkswagen AG concentrate volume among renewable PPA holders. |
| Digital Color Matching Platform Deployment | AI-driven spectrophotometry compresses customer acquisition costs for custom automotive interior specifications. |
| Ruhr Corridor Distribution Infrastructure Expansion | Cologne-Düsseldorf storage hubs capture infrastructure stimulus-driven demand for construction chemical delivery. |
| REACH Dossier Portfolio Acquisition | Existing registration assets overcome SIEF consortium fee barriers that exclude small and mid-sized importers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork and secondary validation. Interview subjects included BASF Ludwigshafen plant managers, Mercedes-Benz and Volkswagen procurement leads, construction chemical distributors in North Rhine-Westphalia, technical R&D directors at Wacker Chemie Burghausen, and leather finishing compounders facing REACH re-registration. Secondary sources encompassed ECHA registration databases, German Chemicals Act amendments, Cefic trade flow reports, customs data on Asian styrene-butadiene imports, and SEC filings from multinational chemical majors. Bottom-up volume modeling triangulated against top-down value estimates from production capacity and pricing benchmarks.
Across the analysis window, forecasts incorporated product type segmentation by acrylic, vinyl acetate ethylene, and styrene-butadiene chemistries; application splits across paints coatings, adhesives sealants, and construction chemicals; and end-use industry concentration in automotive suppliers and building materials manufacturers. CAGRs were derived from regression analysis against macro drivers including EU REACH enforcement intensity, automotive production forecasts, and infrastructure stimulus allocation. Industry-specific inputs captured propylene oxide feedstock volatility and renewable energy PPA penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal implementation, stable automotive OEM carbon audit requirements, or resolved microplastics regulatory clarity would require recalibration. Forecasts reflect documented assumptions on REACH registration cost trajectories and Asian import pricing behavior. Specific risk factors include propylene supply disruptions, accelerated microplastics restriction timelines, and renewable energy certificate market volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Polyaryletherketone (PAEK) Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Global Thermoset Resin Market