
 Automotive Rocker Panel Market | 2026-2036
Automotive Rocker Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rocker Panel Market Intelligence
OEM-direct supply contracts is reconfiguring how tier-one stampers allocate press capacity across North America and Europe. ArcelorMittal sustains its position through captive steel supply and high-strength blanking operations in Belgium and Mexico. Magna International Inc. differentiates via modular rocker-skirt assemblies that integrate acoustic dampening and corrosion coatings. Hyundai Mobis Co. Ltd. anchors Asian supply chains through just-in-time deliveries to Hyundai-Kia assembly complexes in Korea and Alabama.
Automotive rocker panels are structural stampings or extrusions mounted along the lower body side between wheel wells, typically fabricated from dual-phase steel, 6xxx-series aluminum, or glass-fiber-reinforced thermoplastics, and engineered to resist side-impact intrusion while supporting door-sealing geometry. Steel remains the volume leader for full-frame trucks and budget sedans where raw material cost governs sourcing decisions, yet aluminum and composite variants are gaining share in premium SUVs and electric vehicle platforms where mass reduction directly extends range. OEM Panels command the largest revenue pool due to design-lock specifications and long-term platform contracts, while Aftermarket Panels serve collision repair channels with shorter lead times and lower certification barriers.
EPA Corporate Average Fuel Economy mandates and NHTSA side-impact protocols in the United States compel manufacturers to lightweight rocker structures without sacrificing crash performance, while ECHA REACH restrictions on hexavalent chromium coatings push suppliers toward zinc-flake and organic alternatives. China's MIIT new-energy vehicle technical standards incorporate rocker-panel battery protection requirements that favor thicker-gauge aluminum extrusions. Stakeholders must monitor how evolving side-pole impact test protocols and battery enclosure integration reshape material selection and welding process investments.
Market Dynamics
OEM platform consolidation around electric vehicle architectures is compressing rocker panel design cycles, forcing stampers to reconfigure blanking lines for mixed-material production while NHTSA side-pole impact protocols demand thicker-gauge sections without mass penalties.
Growth Catalysts
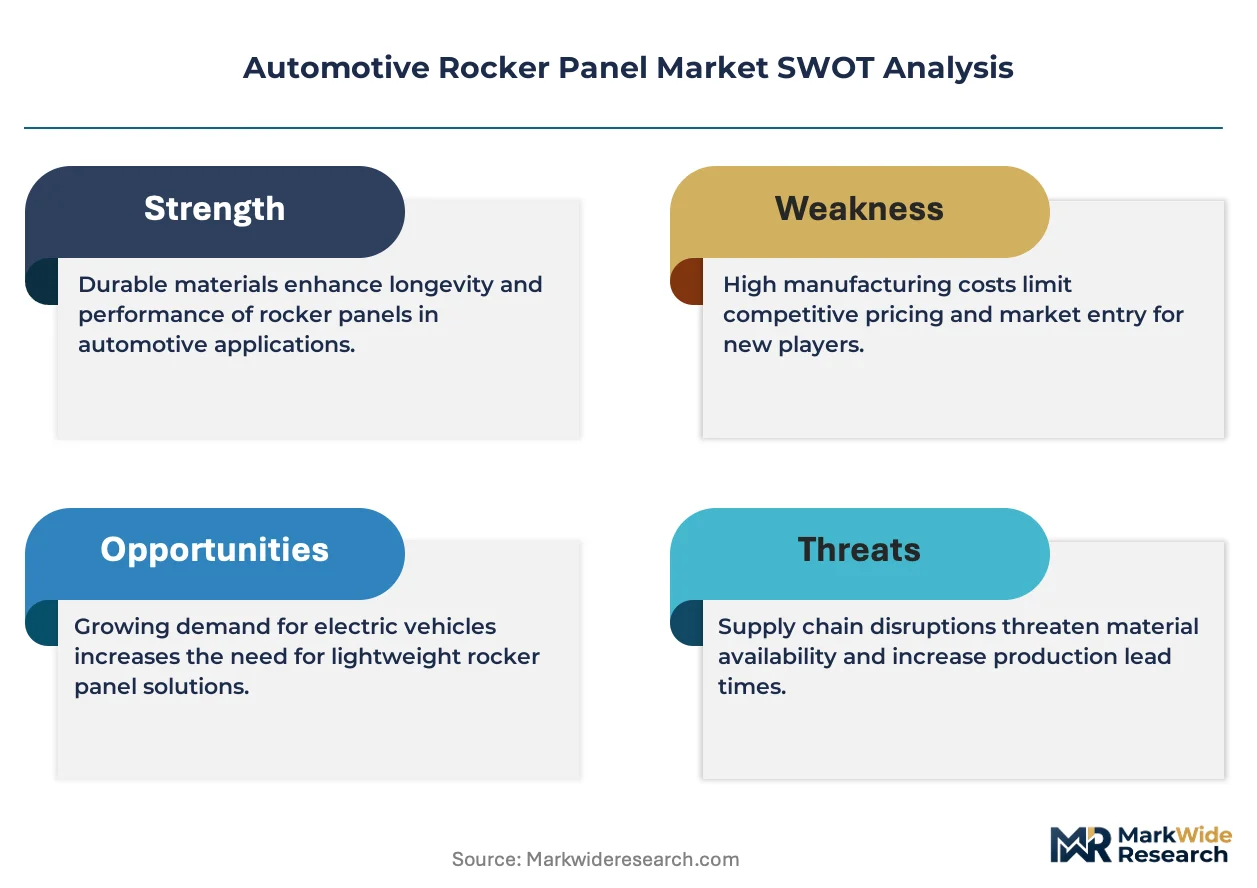
- EPA Corporate Average Fuel Economy mandates:Tightening fleet efficiency targets compel automakers to substitute aluminum and composite rocker panels for steel in next-generation platforms, particularly in full-size SUVs and light trucks where mass reduction yields disproportionate fuel savings.
- China MIIT battery protection standards:New-energy vehicle technical regulations mandate enhanced rocker-panel structural integrity for battery enclosure protection, driving specification upgrades across domestic EV production lines.
- Hot-stamping process maturation:Advanced high-strength steel forming technologies enable thinner-gauge parts with equivalent crash performance, reducing per-unit material consumption while maintaining OEM qualification thresholds.
Market Restraints
- Aluminum price volatility:London Metal Exchange pricing swings for primary aluminum create margin compression for extrusion-dependent suppliers serving premium SUV and EV segments.
- Hexavalent chromium coating phase-out:ECHA REACH restrictions on Cr(VI) corrosion protection force capital-intensive conversion to zinc-flake and organic coating lines across European supply bases.
- Steel mill supply concentration:Captive supply relationships between ArcelorMittal and major OEMs limit third-party stamper access to competitively priced dual-phase steel blanks in Belgium and Mexico.
Strategic Opportunities
- India automotive production expansion:PLI scheme incentives for electric vehicle manufacturing create first-mover advantage for localized aluminum extrusion capacity serving Maruti Suzuki and Tata Motors assembly plants.
- Modular rocker-skirt integration:Convergence of acoustic dampening layers, corrosion coatings, and structural reinforcement into single-source assemblies enables tier-one suppliers to capture value previously fragmented across multiple vendors.
- Collision repair channel digitization:B2B platform procurement of certified aftermarket panels is displacing traditional distributor networks in United States and Germany, shortening lead times for independent body shops.
Industry Challenges
- Welding process qualification:Mixed-material joining of aluminum extrusions to steel unibody structures requires new resistance spot-welding and flow-drill screw investments that strain mid-tier stamper balance sheets.
- Platform-specific tooling amortization:Shorter OEM vehicle lifecycles compress payback periods for dedicated blanking dies, forcing suppliers to negotiate multi-platform contract bundles or absorb residual tooling risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rocker Panel Market |
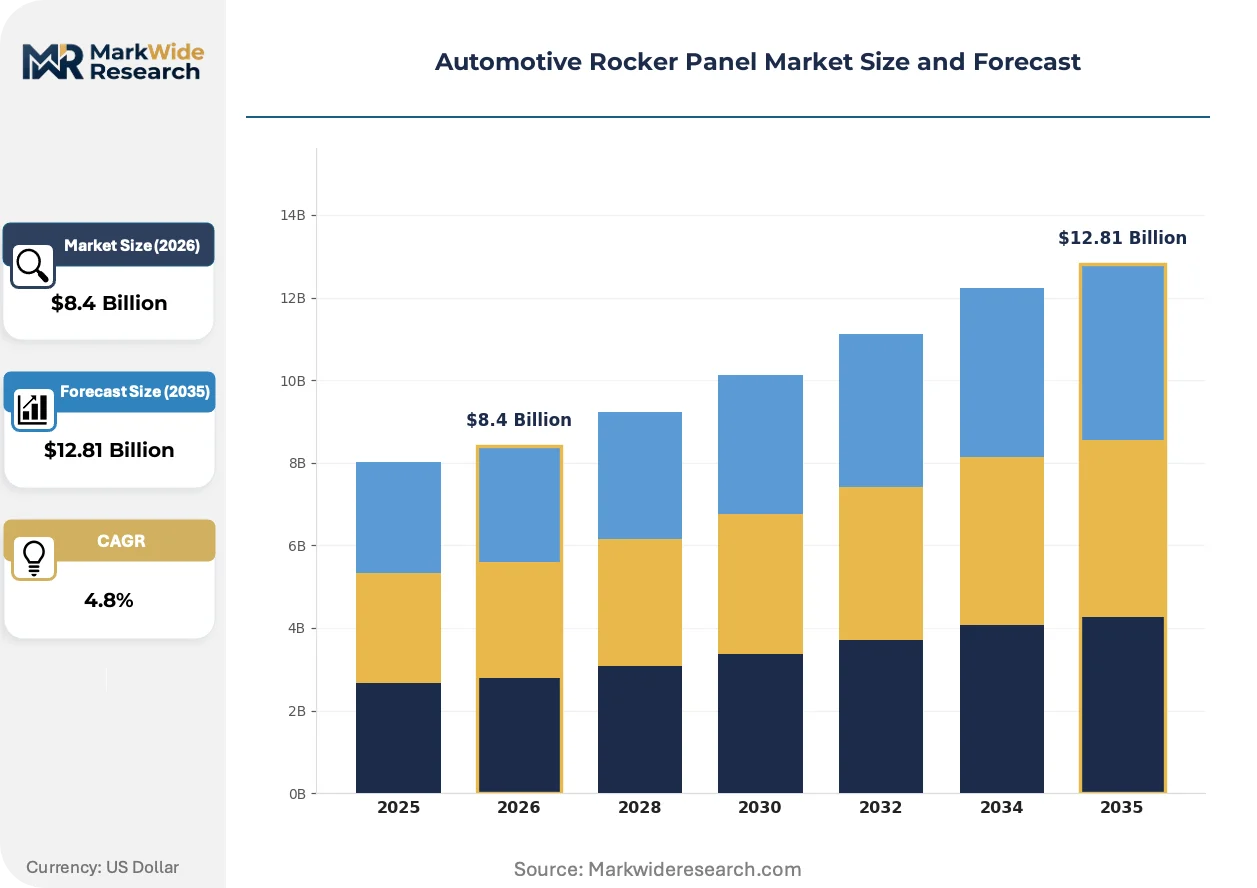
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OEM Panels, Aftermarket Panels, Racing Panels, Custom Panels Material: Steel, Aluminum, Composite, Plastic Vehicle Type: SUVs, Sedans, Trucks, Coupes Installation Method: Welded, Bolted, Adhesive, Snap-fit |
| Companies Covered | Thyssenkrupp AG, ArcelorMittal, Magna International Inc., Toyota Boshoku Corporation, Benteler International AG, Gestamp Automoción, Shiloh Industries, Hyundai Mobis Co. Ltd., Aisin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rocker Panel Market Strategic Shifts & Innovations
Material science advances and regulatory pressure on crash performance are converging to redefine rocker panel engineering specifications, with suppliers racing to qualify multi-material architectures before next-generation platform design locks.
Glass-fiber-reinforced thermoplastic composites are rendering obsolete conventional stamped steel assemblies in electric vehicle skateboard platforms, with Tesla and Rivian specifying pultruded sections for battery-side protection. Tier-one molders in Germany and China are scaling press capacity to meet 2025-2026 platform launches. The technology is rendering obsolete legacy single-material sourcing strategies that dominated full-frame truck production.
REACH restrictions on hexavalent chromium conversion coatings are mandating wholesale process conversion across European supply chains, with ECHA enforcement timelines accelerating zinc-flake and organic silane adoption. Surface treatment vendors in Belgium and Spain are qualifying alternative chemistries under accelerated corrosion protocols. Premium German OEMs are most affected, with Audi and BMW specifying coating performance warranties that exceed prior Cr(VI) benchmarks.
Fleet procurement centralization among North American rental and commercial vehicle operators is consolidating aftermarket panel demand through direct manufacturer agreements, bypassing traditional jobber distribution. Enterprise Holdings and Avis Budget Group now specify certified collision parts through consolidated national contracts. This concentration is most visible in United States Sun Belt states where high vehicle turnover sustains dedicated supply agreements.
Automotive Rocker Panel Market Segmentation
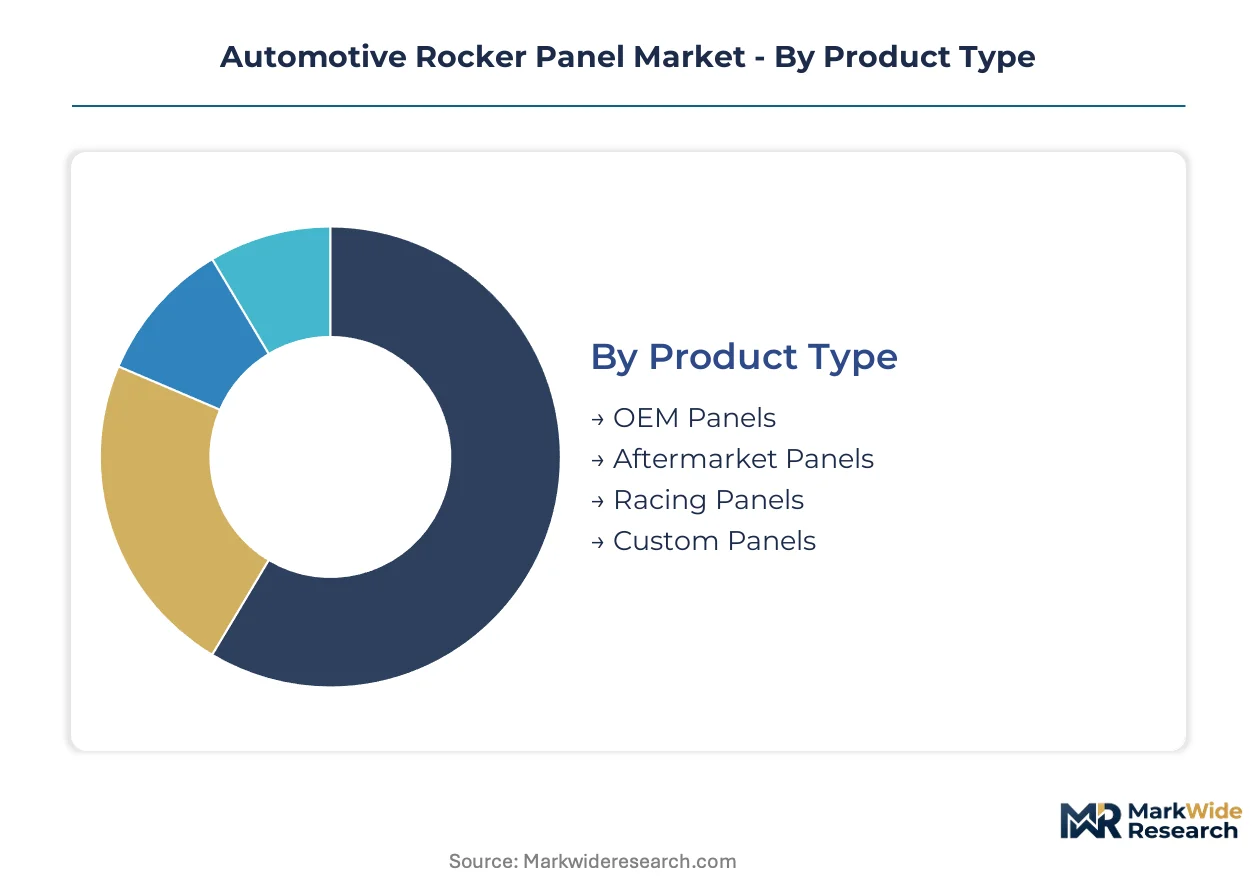
Rocker panel segmentation reveals how material science, regulatory pressure, and vehicle architecture reshape procurement priorities. Each dimension exposes distinct margin structures and qualification barriers that separate incumbent suppliers from challengers.
Product Type:
Mature supply relationships dominate the high-volume segments while emerging channels fragment around specialized applications and shorter lead-time requirements.
- OEM Panels:Design-locked stampings or extrusions fabricated to automaker platform specifications with multi-year supply agreements. ArcelorMittal and Magna International anchor production in Belgium, Mexico, and Ontario to service Detroit Three and German premium OEM assembly lines.
- Aftermarket Panels:Certified collision repair components with shorter qualification cycles and lower barrier-to-entry for independent stampers. Demand concentrates in United States Sun Belt states and Germany's Autobahn corridor where high vehicle turnover sustains dedicated supply agreements through Enterprise Holdings and Avis Budget Group national contracts.
- Racing Panels:Lightweight composite or tubular assemblies engineered for FIA and NHRA safety compliance with minimal production volume.
- Custom Panels:Small-batch fabrications for restoration and modification shops with highly variable specification tolerance.
OEM Panels retain volume leadership; Aftermarket Panels hold the steepest expansion curve as collision repair digitization displaces traditional distributor networks.
Material:
Cost tier stratification separates commodity metal supply from premium lightweight alternatives where mass reduction directly extends vehicle range or improves fleet efficiency metrics.
- Steel:Dual-phase and advanced high-strength steel grades processed through hot-stamping lines for full-frame trucks and budget sedans. Raw material cost governs sourcing decisions, with ArcelorMittal's captive supply relationships in Belgium and Mexico limiting third-party stamper access to competitively priced blanks.
- Aluminum:6xxx-series extrusions specified for premium SUVs and electric vehicle platforms where mass reduction yields disproportionate fuel savings or battery range extension. London Metal Exchange price volatility creates margin compression for extrusion-dependent suppliers.
- Composite:Glass-fiber-reinforced thermoplastic pultrusions rendering obsolete conventional stamped steel in Tesla and Rivian skateboard platforms for battery-side protection.
- Plastic:Injection-molded thermoplastics for non-structural skirt applications with minimal crash-load requirements.
Steel retains volume leadership; Composite holds the steepest expansion curve as tier-one molders in Germany and China scale press capacity for 2025-2026 platform launches.
Vehicle Type:
Application-specific load cases and regulatory exposure drive material selection divergence across passenger and commercial vehicle architectures.
- SUVs:High-clearance unibody and body-on-frame designs demanding thicker-gauge rocker sections for side-impact protection without mass penalties. EPA Corporate Average Fuel Economy mandates compel aluminum substitution in next-generation full-size SUV platforms.
- Trucks:Full-frame architectures with highest structural load requirements sustaining steel volume despite lightweighting pressure in Detroit Three product planning.
- Sedans:Declining production mix in United States and Europe compresses dedicated tooling investment, forcing suppliers toward multi-platform blanking line configurations.
- Coupes:Low-volume specialty applications with design-driven styling requirements and minimal standardization.
Trucks retain volume leadership; SUVs hold the steepest expansion curve as MIIT battery protection standards in China mandate enhanced structural integrity for electric vehicle variants.
Installation Method:
Joining technology qualification requirements separate OEM-integrated production from service-channel repair procedures with divergent capital intensity.
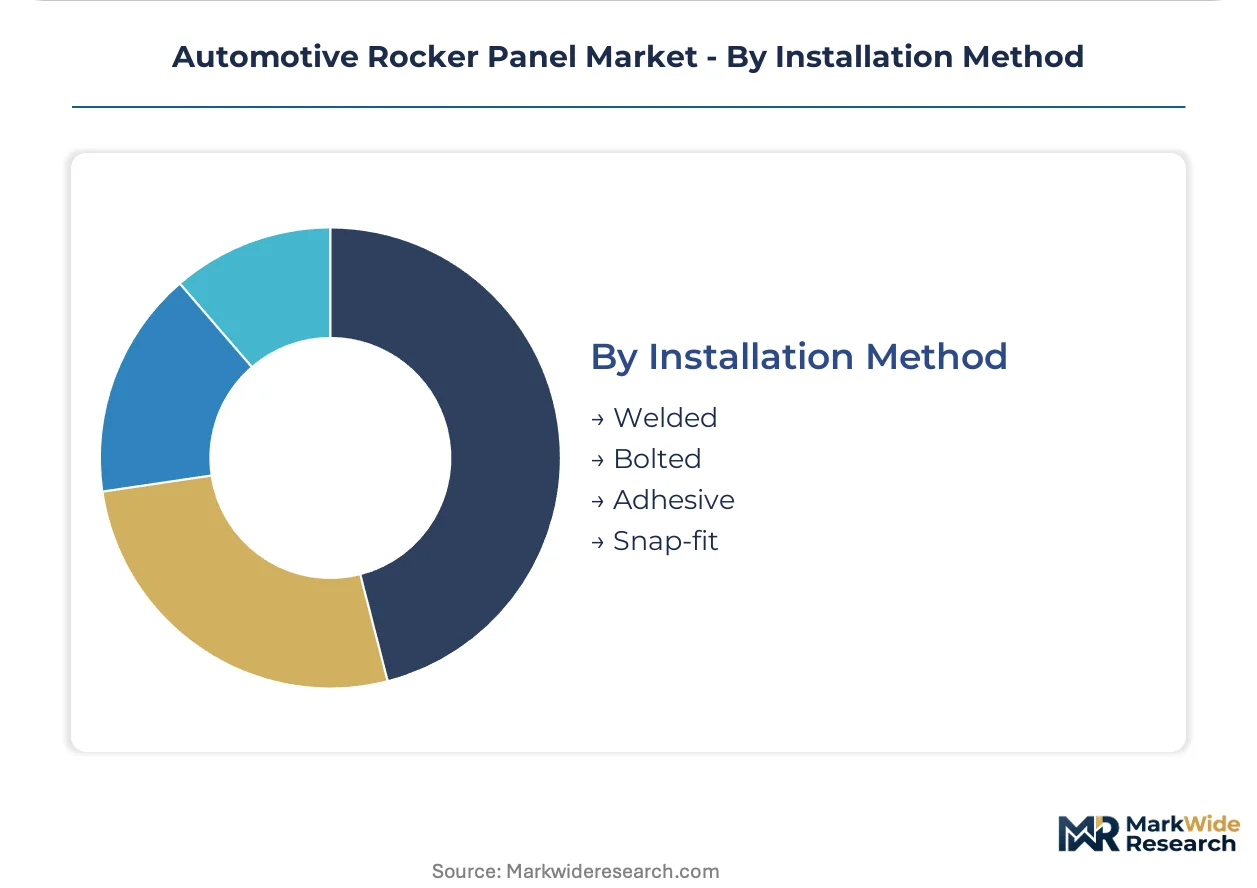
- Welded:Resistance spot-welding and laser welding of steel stampings in OEM assembly plants with robotic automation and real-time quality monitoring. Mixed-material joining of aluminum extrusions to steel unibody structures requires new capital investment that strains mid-tier stamper balance sheets.
- Bolted:Mechanical fastening for modular rocker-skirt assemblies enabling acoustic dampening and corrosion coating integration by tier-one suppliers.
- Adhesive:Structural bonding agents specified for composite-to-metal interfaces in electric vehicle platforms with dissimilar material joining requirements.
- Snap-fit:Plastic and composite attachment systems for non-structural trim components with minimal load-bearing function.
Welded retains volume leadership; Adhesive holds the steepest expansion curve as multi-material architectures proliferate across EV platform design locks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where premium OEM specifications command material premiums, while Chinese suppliers compete on scale for domestic EV platform volumes.
United States
Pickup trucks and full-size SUVs sustain steel rocker panel demand despite EPA fuel-economy mandates pressuring aluminum substitution. NHTSA side-pole impact protocols compel thicker-gauge sections without mass penalties. Detroit Three assembly complexes in Michigan and Ohio anchor North American stamping capacity.
Germany
Premium OEMs Audi and BMW drive specification upgrades for acoustic dampening and corrosion coating integration. ECHA REACH restrictions on hexavalent chromium coatings accelerate zinc-flake and organic silane adoption across supply chains. Surface treatment vendors in Belgium and Spain qualify alternative chemistries under accelerated corrosion protocols.
China
Domestic EV production scales drive demand for aluminum extrusions and glass-fiber-reinforced thermoplastics in battery-side protection applications. MIIT new-energy vehicle technical standards mandate enhanced rocker-panel structural integrity for battery enclosure protection. Tier-one molders in the Yangtze River Delta scale press capacity for 2025-2026 platform launches.
Mexico
Nearshoring of Detroit Three supply chains expands stamping and extrusion capacity for cross-border just-in-time delivery. USMCA rules of origin govern material sourcing for duty-free vehicle exports to the United States. Industrial clusters in Nuevo León and the Bajío Region concentrate new capacity investments.
India
PLI scheme incentives for electric vehicle manufacturing create first-mover opportunity for localized aluminum extrusion capacity. Maruti Suzuki and Tata Motors assembly plants drive specification development for budget and premium segments. Automotive supplier parks in Maharashtra and Gujarat anchor component manufacturing zones.
Automotive Rocker Panel Market Key Industry Players
Integrated steelmakers and modular assembly specialists split the market between captive material supply and value-added integration. The vendor base concentrates around three strategic archetypes: steel producers with captive blanking operations, tier-one integrators of multi-material assemblies, and regional stampers serving aftermarket collision repair. Dominant competitive moves include backward integration into high-strength steel supply and geographic co-location with OEM assembly complexes.
Among European-integrated fabricators, Thyssenkrupp AG and ArcelorMittal exemplify the steel-backed archetype through captive supply relationships. Magna International Inc. occupies a position within the modular integration tier, representing the shift toward single-source assemblies that consolidate acoustic and corrosion functions. Hyundai Mobis Co. Ltd. anchors the Asia-Pacific supply chain vector through proximity to Hyundai-Kia manufacturing complexes in Korea and Alabama.
| Leading Market Players |
|---|
| Thyssenkrupp AG |
| ArcelorMittal |
| Magna International Inc. |
| Toyota Boshoku Corporation |
| Benteler International AG |
| Gestamp Automoción |
| Shiloh Industries |
| Hyundai Mobis Co. Ltd. |
| Aisin Corporation |
| Others |
Cost & Logistics Intelligence
Aluminum price volatility on the London Metal Exchange determines both pricing tier spreads and supply chain shape in the automotive rocker panel market, compressing margins for extrusion-dependent suppliers while pushing procurement toward captive steel relationships and composite alternatives.
Pricing Analysis
Configured-to-order pricing for OEM-locked aluminum extrusions commands substantial premiums over standard dual-phase steel stampings. Pricing stratifies across premium, standard, and economy tiers based on material certification grade and volume scale commitments. Cost compression in the aluminum tier is intensifying because of commodity exchange volatility. Aftermarket collision repair channels exhibit highest price sensitivity, while premium German OEMs demonstrate lowest sensitivity due to performance warranty requirements.
Supply Chain Analysis
Export-control regimes on advanced high-strength steel forming technologies limit equipment flows to certain fabrication facilities, constraining capacity expansion in emerging production zones. Supply concentrates in Belgium, Mexico, and the Yangtze River Delta, with raw material dependencies on dual-phase steel blanks, 6xxx-series aluminum ingots, and glass-fiber-reinforced thermoplastic resins. Single-source vulnerability runs through ArcelorMittal's captive blanking operations. Distribution runs through tier-one modular assembly specialists co-located with OEM vehicle assembly complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-specific tooling amortization pressures and mixed-material welding qualification barriers fragment competitive positioning, creating entry niches for specialized suppliers targeting EV battery protection and collision repair digitization.
For Market Incumbents: Harden supply security through backward integration into high-strength steel blanking capacity in Mexico and Belgium, insulating against raw material access restrictions. Deepen modular assembly capabilities to capture value from acoustic dampening and corrosion coating convergence, defending against tier-one integrators like Magna International. For New Entrants and Emerging Players: India's PLI scheme electric vehicle manufacturing incentives represent the most penetrable entry point for localized aluminum extrusion capacity serving Maruti Suzuki and Tata Motors assembly plants. Collision repair channel digitization in the United States Sun Belt offers a secondary white-space target. A direct B2B platform procurement model bypasses traditional distributor networks and shortens customer acquisition cycles. For Investors and Strategic Acquirers: ECHA REACH hexavalent chromium coating phase-out deadlines reshape the acquisition landscape, elevating surface treatment vendors with qualified zinc-flake and organic silane alternatives. The five-to-ten-year viability window favors targets with multi-material joining capabilities and OEM platform contract bundles. Monitor NHTSA side-pole impact protocol evolution as the critical signal for material specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Joining Qualification | Enables tier-one suppliers to capture mixed-material EV platform contracts from OEMs like Tesla and Rivian. |
| Modular Rocker-Skirt Integration | Consolidates acoustic dampening and corrosion functions previously fragmented across multiple vendors. |
| Geographic Co-Location with OEM Assembly | Hyundai Mobis anchors just-in-time delivery to Hyundai-Kia complexes in Korea and Alabama. |
| Alternative Coating Process Conversion | Belgian and Spanish surface treatment vendors qualify zinc-flake chemistries under accelerated corrosion protocols. |
| Collision Repair Channel Digitization | Enterprise Holdings and Avis Budget Group consolidated national contracts displace traditional jobber distribution. |
Research Approach
Cross-validation between OEM platform engineering disclosures and tier-one supplier production data anchors the qualitative findings in this study. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and dealership operations heads combined with secondary validation from vehicle production databases, IHS Markit registration data, SEC filings, and EPA fuel-economy compliance reports. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates.
Calibration against historical production volumes and material substitution trends shaped the analytical framework across the analysis window. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, material grade tier, and regional production cluster. CAGRs derived from regression analysis of platform launch schedules and regulatory compliance timelines incorporate battery enclosure protection requirements and side-impact protocol evolution as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in aluminum exchange pricing, steel mill capacity utilization, and OEM platform consolidation velocity would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and technology adoption curves. Material shifts in NHTSA side-pole impact test protocols or ECHA REACH coating restriction implementation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Low-Noise Anti-Squeak Additives for Automotive Interiors Market
Automotive Interior & Exterior
Zero Gravity Seat Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market