
 Japan Road Freight Transport Market | 2026-2036
Japan Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Road Freight Transport Market Foresight
Market Context
Japan's commercial vehicle manufacturing base is broadening output capacity for medium-duty and heavy-duty freight carriers serving domestic logistics networks. Nippon Express Holdings leverages its integrated warehousing and highway distribution assets to anchor national supply chains. Yamato Transport Co., Ltd. sustains dominance in parcel express through dense collection-delivery infrastructure. SG Holdings competes aggressively on cross-border road-rail intermodal services linking major industrial zones.
Technical and Structural Dimensions
Japan road freight transport encompasses the motorized movement of goods over national and prefectural highway networks using commercial vehicles with gross vehicle weights ranging from two-ton vans to twenty-ton tractor-trailers, primarily serving just-in-time manufacturing, retail replenishment, and temperature-sensitive cargo delivery. Trucks within the vehicle type category carry the majority of tonnage kilometers, while cold chain logistics within service type commands premium rate structures due to pharmaceutical and fresh food handling requirements. The e-commerce vertical absorbs expanding capacity as same-day and next-day delivery modes tighten scheduling constraints across fleet operators.
Regulatory Environment and Outlook
METI enforces fuel efficiency standards under the Top Runner program, while Japan's Ministry of Land, Infrastructure, Transport and Tourism governs driver hours-of-service rules and vehicle dimension regulations that directly constrain fleet utilization rates. JIS standards for commercial vehicle safety equipment and emissions testing protocols shape procurement specifications for domestic carriers. Stakeholders must monitor electric truck charging infrastructure deployment along the Tomei and Meishin expressway corridors to assess zero-emission fleet transition feasibility.
Market Dynamics
Japan's road freight sector faces acute pressure from the 2024 amendments to driver hours-of-service rules, which compress fleet utilization rates while e-commerce volumes surge across Honshu island corridors. METI's Top Runner fuel efficiency mandates are simultaneously forcing capital-intensive fleet turnover toward electric and hybrid platforms.
Growth Catalysts
- E-commerce fulfillment density:Same-day and next-day delivery commitments from major retail platforms are tightening scheduling constraints and absorbing incremental trucking capacity across Greater Tokyo Area distribution nodes.
- Cold chain pharmaceutical handling:Temperature-controlled transport for biologics and vaccines commands premium rate structures as PMDA storage-and-distribution regulations tighten custody documentation requirements.
- Expressway charging infrastructure:Deployment of high-power electric truck charging stations along the Tomei and Meishin corridors is enabling zero-emission fleet trials among major logistics operators.
Market Restraints
- Diesel fuel cost volatility:Fleet operators face margin compression from crude-linked diesel pricing that defies pass-through mechanisms in contracted freight rates.
- Driver shortage concentration:Aging workforce demographics in rural prefectures limit operational expansion outside the Tokyo-Osaka-Nagoya triangle.
- Vehicle dimension regulations:Japan's Ministry of Land, Infrastructure, Transport and Tourism length and weight limits constrain payload optimization versus European and North American standards.
Strategic Opportunities
- Hokkaido agricultural export corridors:Underdeveloped cold chain infrastructure connecting northern dairy and seafood producers to international air cargo terminals offers greenfield investment potential.
- Platooning automation:Cooperative adaptive cruise control systems linking multiple trucks are converging with V2X roadside communication networks to enable driver-assist convoys on expressway segments.
- Carbon border adjustment alignment:METI green logistics certification programs provide regulatory tailwinds for operators investing in renewable diesel and battery-electric transition pathways.
Industry Challenges
- Telematics integration complexity:Legacy dispatch and warehouse management systems resist seamless data exchange with real-time vehicle tracking platforms, delaying fleet optimization.
- Commercial driver license renewal timelines:Medical certification and skills revalidation requirements create operational coverage gaps during peak seasonal demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Road Freight Transport Market |
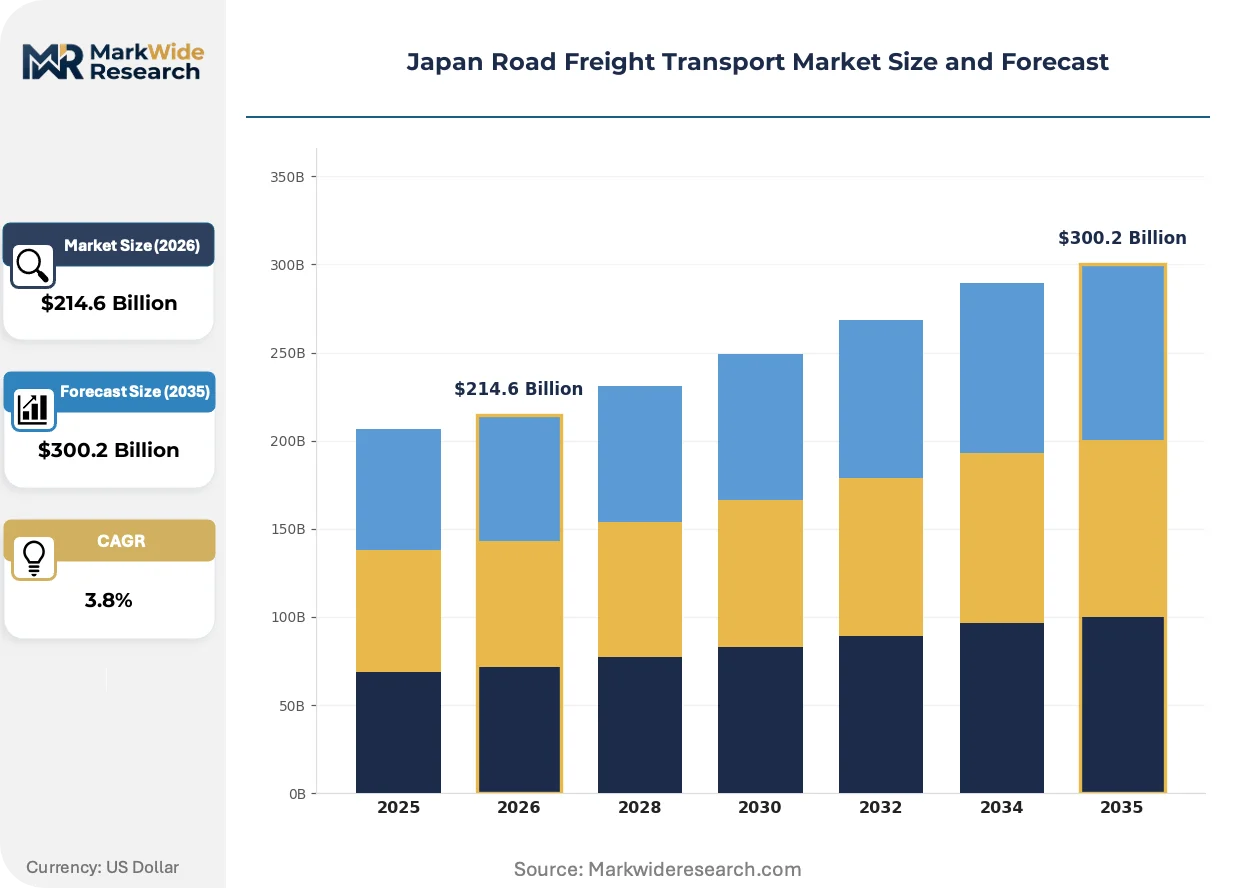
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $300.2 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Vans, Trailers, Buses Service Type: Full Truck Load, Less Than Truck Load, Express Delivery, Cold Chain Logistics Industry Vertical: Automotive, E-commerce, Retail, Manufacturing Delivery Mode: Same Day, Next Day, Scheduled, Freight Forwarding |
| Companies Covered | Nippon Express Holdings, Yamato Transport Co., Ltd., SG Holdings, Seino Holdings Co., Ltd., Hitachi Transport System, Mitsui-Soko Holdings Co., Ltd., SENKO Co., Ltd., Kokusai Express Co., Ltd., Fukuyama Transporting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Road Freight Transport Market Shifts & Advancements
Digital freight matching platforms are actively reshaping how shippers procure trucking capacity, compressing traditional broker networks while real-time pricing algorithms replace annual contract negotiations. Three developments are accelerating this transformation.
Battery-electric medium-duty trucks are expanding into urban last-mile distribution as charging infrastructure density improves in metropolitan warehouse clusters. Major parcel carriers are piloting overnight depot charging for next-day delivery routes. This technology is expanding into refrigerated applications as thermal management systems achieve parity with diesel auxiliary power units.
METI's 2023 revision to the Act on Rationalizing Energy Use mandates real-time fuel consumption monitoring for commercial fleets above specified tonnage thresholds. Operators must install certified telematics devices and submit aggregated efficiency data. Heavy-duty long-haul segments face the steepest compliance costs, accelerating consolidation among smaller fleet owners.
Shippers are unbundling transportation management from integrated logistics contracts, awarding lane-specific freight to lowest-cost digital brokers. Traditional asset-heavy carriers are responding with dynamic spot pricing APIs. This disintermediation is most visible in automotive parts replenishment between Nagoya industrial zones and Kyushu assembly plants.
Japan Road Freight Transport Market Segmentation
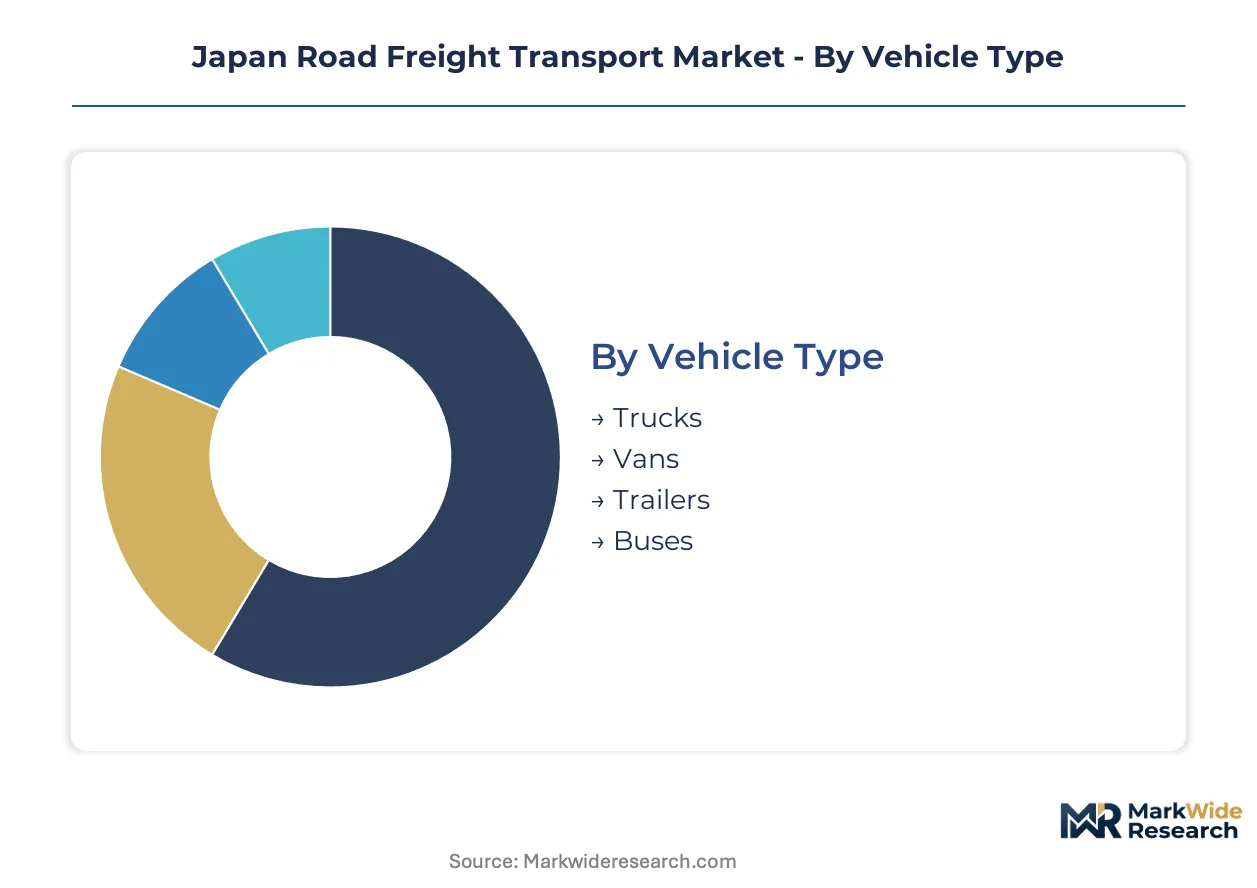
Japan's road freight market segments along operational and customer dimensions that determine equipment procurement cycles and service rate structures. Fleet operators align vehicle specifications and service tiers with the density patterns of Honshu island logistics corridors and the regulatory constraints of METI emissions mandates.
Vehicle Type:
Replacement cycles for commercial vehicles accelerate under METI's Top Runner fuel efficiency standards, compressing fleet turnover toward cleaner platforms.
- Trucks:Medium-duty and heavy-duty freight carriers with gross vehicle weights from eight to twenty tons dominate tonnage-kilometers across just-in-time manufacturing supply chains. Demand concentrates in the Greater Tokyo Area where port-to-warehouse volumes and automotive parts replenishment between Nagoya industrial zones and Kyushu assembly plants absorb the majority of heavy-duty capacity.
- Vans:Two-ton to four-ton commercial vehicles serve urban last-mile distribution and parcel express networks with frequent stop-start routing. Metropolitan warehouse clusters in Osaka and Yokohama drive procurement as e-commerce fulfillment density tightens delivery windows for same-day service commitments.
- Trailers:Tractor-trailer combinations optimized for long-haul expressway corridors connecting the Tokyo-Osaka-Nagoya triangle.
- Buses:Commercial passenger vehicles repurposed for crew transport and mobile logistics support in remote prefectures.
Volume placements concentrate in Trucks; the faster expansion belongs to Vans.
Service Type:
Margin structures diverge sharply based on cargo handling complexity and custody documentation requirements.
- Full Truck Load:Dedicated vehicle capacity for single-shipper movements between manufacturing plants and distribution centers. Automotive and electronics manufacturers in Aichi and Shizuoka prefectures lock in contracted lane capacity with penalties for scheduling deviations.
- Less Than Truck Load:Consolidated shipments from multiple shippers sharing trailer space through hub-and-spoke terminal networks. Regional freight terminals in Nagoya and Osaka sort mixed cargo for final-mile delivery across secondary cities.
- Express Delivery:Time-definite parcel and document services with guaranteed delivery windows. Yamato Transport and Nippon Express maintain dense collection-delivery infrastructure for next-day commitments.
- Cold Chain Logistics:Temperature-controlled transport maintaining specified ranges for pharmaceuticals and perishables. PMDA storage-and-distribution regulations tighten custody documentation for biologics moving between Osaka pharmaceutical clusters and Tokyo medical distributors.
Revenue concentration sits with Full Truck Load; Cold Chain Logistics commands the steepest rate premiums.
Industry Vertical:
End-use demand patterns shape fleet utilization rates and equipment specialization requirements.
- Automotive:Just-in-time parts replenishment and finished vehicle distribution requiring precise sequencing. Toyota and Honda assembly plants in Aichi prefecture generate continuous loop movements between tier-1 supplier parks and production lines.
- E-commerce:Surging parcel volumes from digital retail platforms demanding same-day and next-day fulfillment. Major platforms absorb incremental trucking capacity across Greater Tokyo Area distribution nodes with tightened scheduling constraints.
- Retail:Scheduled replenishment of fast-moving consumer goods to convenience store and supermarket networks.
- Manufacturing:Industrial equipment and raw materials transport serving factory construction and maintenance cycles.
Contracted volumes anchor in Automotive; E-commerce is climbing the fastest.
Delivery Mode:
Speed tiers determine pricing structures and fleet deployment intensity across metropolitan corridors.
- Same Day:Expedited delivery completing pickup and delivery within single operating windows. Dense urban zones in central Tokyo and Osaka absorb premium-priced capacity for urgent document and pharmaceutical movements.
- Next Day:Overnight network operations with terminal sorting and early-morning delivery. Parcel carriers pilot overnight depot charging for battery-electric routes serving this tier.
- Scheduled:Pre-booked capacity with defined pickup and delivery windows for predictable manufacturing supply chains.
- Freight Forwarding:Intermodal coordination combining road segments with rail or air legs for international cargo.
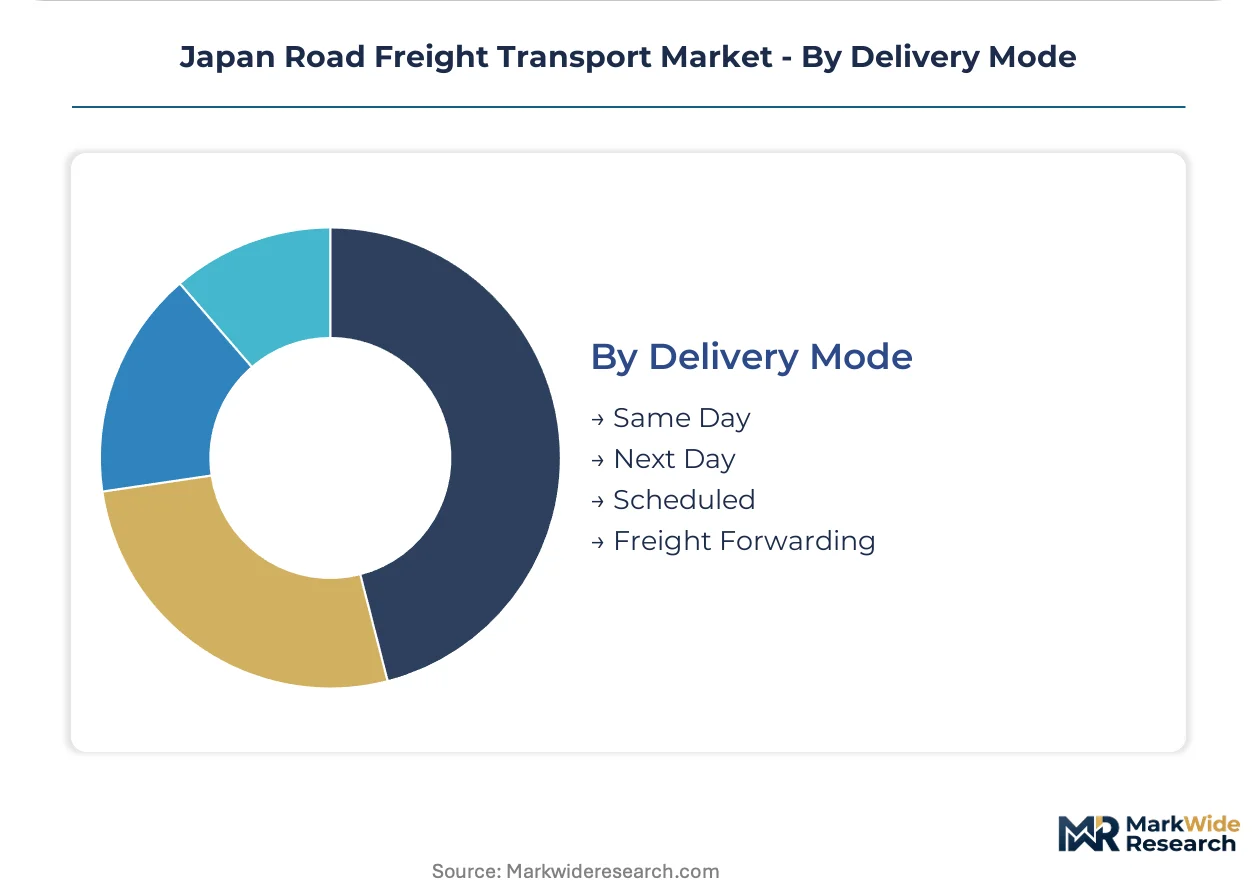
Operational density peaks in Next Day; Same Day shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petroleum refining clusters in Yokkaichi and Mizushima anchor Japan's diesel supply networks that feed heavy-duty trucking corridors across Honshu island.
Kanto/Tokyo
Port-to-warehouse volumes from Tokyo Bay container terminals absorb the majority of Japan's heavy-duty trucking capacity. METI's Top Runner fuel efficiency standards accelerate fleet turnover toward electric platforms in this corridor. The Greater Tokyo Area distribution nodes handle the densest e-commerce fulfillment traffic, with same-day delivery commitments tightening scheduling constraints across parcel carriers.
Kansai/Osaka
Pharmaceutical clusters in Osaka generate temperature-controlled cargo movements bound for Tokyo medical distributors under PMDA custody documentation rules. The country's Ministry of Land, Infrastructure, Transport and Tourism governs expressway access permits for oversized vehicles serving this lane. Kobe port's international container flows create continuous loop movements between warehousing zones and customs clearance facilities.
Chubu/Nagoya
Toyota and Honda assembly plants in Aichi prefecture anchor just-in-time parts replenishment requiring precise sequencing from tier-1 supplier parks. JIS standards for commercial vehicle safety equipment shape procurement specifications for dedicated contract fleets. The Tomei Expressway corridor connecting Nagoya to Tokyo carries the highest tonnage-kilometer density for automotive components nationally.
Kyushu
Semiconductor and electronics assembly plants in Kumamoto and Miyazaki prefectures generate scheduled freight movements to Honshu distribution centers. The 2024 amendments to driver hours-of-service rules compress fleet utilization rates on this inter-island route. Fukuoka's emerging logistics zone offers consolidation points for cross-border road-rail intermodal services.
Hokkaido
Dairy and seafood producers in northern prefectures face underdeveloped cold chain infrastructure connecting to international air cargo terminals. METI green logistics certification programs provide regulatory tailwinds for operators investing in refrigerated electric vehicle trials. Sapporo's distribution networks remain isolated from Honshu density patterns, creating greenfield investment potential for temperature-controlled export corridors.
Japan Road Freight Transport Market Competitive Landscape
Global majors compete with regional champions across integrated warehousing and highway distribution assets. The market structure concentrates around asset-heavy operators with dense terminal networks and contracted lane capacity with manufacturing clients. Three archetypes dominate: integrated logistics conglomerates with warehousing and freight assets, parcel express specialists with collection-delivery infrastructure, and cross-border intermodal coordinators. Competitive moves center on fleet electrification partnerships and dynamic pricing API development for spot market participation.
Within the integrated logistics tier, Nippon Express Holdings occupies a position exemplifying warehousing-highway integration, while Yamato Transport Co., Ltd. anchors the parcel express archetype through dense metropolitan infrastructure. SG Holdings represents the cross-border intermodal specialization, linking industrial zones through coordinated road-rail services. These three operators collectively illustrate the strategic positioning patterns visible across Japan's road freight sector.
| Leading Market Players |
|---|
| Nippon Express Holdings |
| Yamato Transport Co., Ltd. |
| SG Holdings |
| Seino Holdings Co., Ltd. |
| Hitachi Transport System |
| Mitsui-Soko Holdings Co., Ltd. |
| SENKO Co., Ltd. |
| Kokusai Express Co., Ltd. |
| Fukuyama Transporting |
| Others |
Supply & Pricing Matrix
Cold chain certification tiers bifurcate Japan's road freight market into premium temperature-controlled lanes and standard dry cargo corridors, with PMDA custody documentation requirements and METI green logistics standards simultaneously reshaping rate structures and fleet procurement decisions across the Tokyo-Osaka-Nagoya triangle.
Pricing Analysis
Service bundling separates contract rates from spot market transactions, with dedicated lane commitments from automotive manufacturers in Aichi prefecture commanding premium stability while digital freight platforms unbundle transportation management for lane-specific spot pricing. Price differentiation stems from temperature-control certification grade and volume scale commitments, with pharmaceutical shippers in Osaka showing lowest sensitivity due to regulatory custody requirements. Pricing pressure intensifies in standard dry freight as diesel cost volatility defies pass-through mechanisms, compressing margins for non-specialized operators.
Supply Chain Analysis
Diesel supply rests on petroleum refining clusters in Yokkaichi and Mizushima, while electric truck battery cells draw from South Korean and Chinese cathode material producers. Fleet operators face single-source vulnerability in charging infrastructure deployment along Tomei and Meishin expressway corridors. Distribution runs through hub-and-spoke terminal networks anchored by Nippon Express and Yamato Transport collection-delivery infrastructure across Greater Tokyo Area nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's road freight sector is consolidating around vertical-integration races, with fleet operators pursuing captive warehousing assets and charging infrastructure control to defend margin positions against digital broker disintermediation.
For Market Incumbents: Anchor contracted lane capacity with automotive and pharmaceutical manufacturers through integrated warehousing-highway service bundles, while accelerating fleet electrification partnerships to preempt METI emissions compliance penalties. Defend against digital freight platform encroachment by deploying dynamic pricing APIs for spot market participation. Prioritize cold chain certification investments to maintain premium rate access in pharmaceutical distribution corridors.
For New Entrants and Emerging Players: Regional freight terminals in secondary cities offer white-space penetration opportunities, particularly in Hokkaido agricultural export corridors where underdeveloped cold chain infrastructure creates greenfield potential. Target temperature-controlled logistics for northern dairy and seafood producers seeking direct air cargo terminal connections. Pursue METI green logistics certification as a differentiated go-to-market credential for carbon-conscious shippers.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier fleet operators possessing dense terminal networks in the Tokyo-Osaka-Nagoya triangle, given accelerating consolidation pressure from Top Runner fuel efficiency mandates and telematics compliance costs. Long-term viability favors asset-heavy operators with integrated warehousing and highway distribution capabilities. Watch electric truck charging infrastructure deployment timelines along expressway corridors as an inflection indicator for zero-emission fleet transition feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Partnership | Battery-electric truck trials with METI charging infrastructure subsidies reduce compliance cost exposure. |
| Cold Chain Certification Investment | PMDA custody documentation capabilities unlock pharmaceutical rate premiums in Osaka-Tokyo lanes. |
| Dynamic Pricing API Development | Real-time spot market participation counters digital freight broker disintermediation in automotive parts. |
| Warehousing-Highway Integration | Captive depot networks enable overnight electric vehicle charging for next-day delivery commitments. |
| Green Logistics Certification Program | METI carbon border alignment provides regulatory tailwinds for renewable diesel transition pathways. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews involving fleet operations directors, logistics procurement managers at automotive OEMs, pharmaceutical distribution executives, and METI policy specialists. Japan Trucking Association tonnage statistics, MLIT vehicle registration databases, and Nippon Express Holdings securities disclosures provided quantitative foundations. Bottom-up vehicle deployment modeling and top-down corridor flow analysis were triangulated against METI energy consumption benchmarks.
Data-stream reconciliation across vehicle type, service tier, industry vertical, and delivery mode dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented fleet capacity expansion trajectories and e-commerce fulfillment density projections. Forecast inputs incorporated Top Runner fuel efficiency compliance timelines and PMDA pharmaceutical distribution regulatory amendments.
Caveats apply where METI emissions mandate acceleration, diesel price volatility spikes, or driver hours-of-service rule amendments could materially shift the outlook. A small set of triggers—expressway charging infrastructure deployment rates, cold chain pharmaceutical volume growth, and digital freight platform market penetration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Brazil Cold Chain Logistics Market
Transportation & Logistics
Boxcar Scars Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
On Demand Transportation Market
Transportation & Logistics
United States Customs Brokerage Market
Transportation & Logistics
Saudi Arabia Land-Based Fuel Transportation Market
Transportation & Logistics
Ski Conveyor Lift Market
Transportation & Logistics
ASEAN Cold Chain Logistics Market
Transportation & Logistics
Hong Kong Customs Brokerage Market
Transportation & Logistics
India less than-Truck-Load (LTL) Market
Transportation & Logistics
Saudi Arabia Road Freight Transport Market
Transportation & Logistics
Indonesia Road Freight Transport Market
Transportation & Logistics
Europe Road Freight Transport Market
Transportation & Logistics
Hazardous Chemicals Transportation Solution Market
Transportation & Logistics
US Reverse Logistics Market