
 Automotive Mirror System Market | 2026-2036
Automotive Mirror System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Mirror System Market Outlook
Camera-to-display substitution is fragmenting the traditional automotive mirror stack into parallel hardware and software supply chains. Gentex Corporation leverages its electrochromatic expertise to anchor the smart dimming segment across North American OEM programs. Magna International Inc. competes through integrated module assembly that bundles camera, display, and control electronics into factory-installed packages. Valeo SA specializes in camera-based vision systems that extend beyond mirror replacement into full surround-view architectures.
An automotive mirror system comprises reflective or camera-based visibility devices mounted at strategic vehicle positions to eliminate blind spots and enhance rearward observation, typically incorporating glass substrates with precision curvature between 1000mm and 1400mm radius or CMOS image sensors paired with OLED displays operating at 60Hz refresh rates. These systems serve the critical safety function of providing real-time environmental awareness to drivers during lane changes, reversing, and parking maneuvers. Side mirrors retain the largest installed base but face margin compression as camera-based technology captures premium vehicle programs and regulatory approvals expand. Digital mirrors represent the fastest-growing product category, concentrated in luxury OEM channels where factory-installed integration commands higher value per vehicle.
NHTSA in the United States and the United Nations Economic Commission for Europe through ECE R46 govern mirror replacement permissions, with both frameworks progressively accommodating camera-monitor systems contingent on field-of-view and latency performance criteria. ISO 16505 provides the technical baseline for camera-based system validation, shaping how suppliers design image processing pipelines and display quality benchmarks. Stakeholders must monitor regulatory divergence between jurisdictions that accept full mirror substitution and those maintaining glass backup requirements, as this split determines platform engineering costs and market access for camera-first architectures.
Market Dynamics
Camera-to-display substitution is fragmenting the traditional automotive mirror stack into parallel hardware and software supply chains, forcing suppliers to choose between glass-based refinement and full digital architectures as NHTSA and ECE R46 frameworks evolve.
Growth Catalysts
- ECE R46 mirror substitution permissions:The United Nations Economic Commission for Europe framework progressively accommodates camera-monitor systems, enabling OEMs to eliminate exterior glass mirrors on premium vehicle platforms.
- CMOS image sensor cost curves:Semiconductor manufacturing scale is collapsing camera module economics, making digital mirror bill-of-materials competitive with electrochromatic glass assemblies.
- German OEM platform integration:Mercedes-Benz and BMW factory-installed programs are validating camera-based architectures for mass-market deployment across next-generation vehicle lines.
Market Restraints
- ISO 16505 validation costs:Camera-based systems require extensive field-of-view and latency testing, adding engineering overhead that glass mirror suppliers avoid.
- Glass substrate supply concentration:Precision-curved mirror glass manufacturing clusters in Japan and Germany, creating geographic vulnerability for traditional supply chains.
- Dual-stack platform requirements:Jurisdictions mandating glass backup mirrors force OEMs to engineer redundant systems, compressing margins on camera-first architectures.
Strategic Opportunities
- Japan commercial vehicle retrofit:METI safety mandates for heavy-duty visibility systems create aftermarket demand for camera-monitor retrofits on existing truck fleets.
- OLED display convergence:Integration of 60Hz automotive-grade panels with camera pipelines enables surround-view architectures that extend beyond mirror replacement.
- United States regulatory harmonization:NHTSA rulemaking momentum toward full mirror substitution would unlock single-stack engineering for North American OEM programs.
Industry Challenges
- Image processing pipeline talent scarcity:Real-time latency optimization for safety-critical camera systems requires specialized embedded software engineers concentrated at semiconductor suppliers.
- Legacy vehicle integration complexity:Camera-monitor retrofits demand CAN bus architecture modifications that conflict with older vehicle electronics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Mirror System Market |
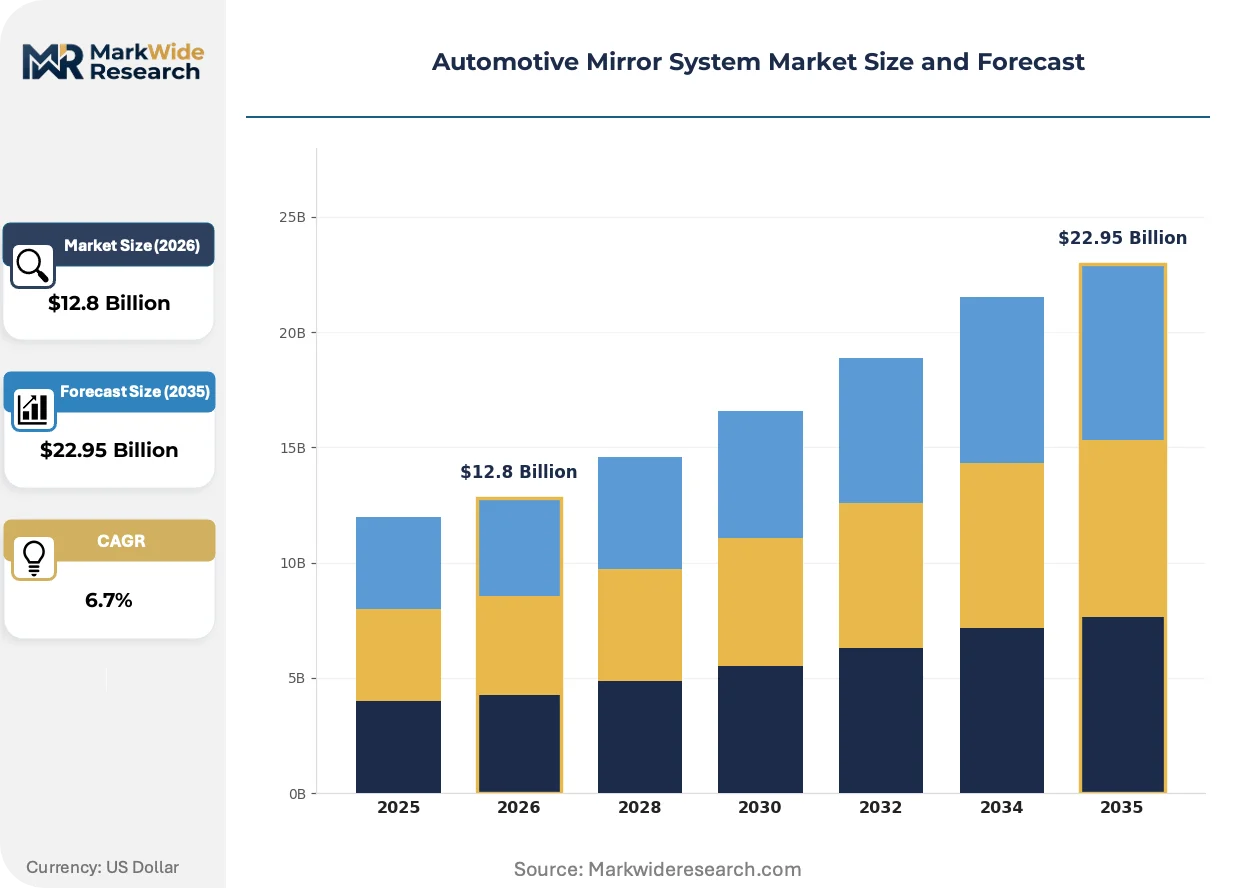
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Side Mirrors, Rear-View Mirrors, Digital Mirrors, Adaptive Mirrors Technology: Electrochromatic, LCD, Camera-Based, Traditional End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation Type: Self-Install, Factory-Installed, Third-Party Installed, Mobile Install |
| Companies Covered | Ficosa International S.A., SL Corporation, Gentex Corporation, FLABEG Automotive Glass Group GmbH, Panasonic Holdings Corp., Magna International Inc., Murakami Corporation, Ichikoh Industries Ltd., Valeo SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Mirror System Market Strategic Shifts
Active matrix OLED display technology is compressing the physical depth of interior mirror assemblies while expanding field-of-view capabilities, reshaping how Tier 1 suppliers architect visibility modules.
Camera-based exterior visibility systems are migrating from luxury sedan applications to commercial truck and bus platforms as image processing latency meets safety-critical thresholds. Fleet operators in long-haul logistics are piloting these configurations to eliminate blind-spot collisions during lane changes. The technology is migrating from premium OEM channels toward standardized factory installations across medium-duty vehicle categories.
NHTSA regulatory review of full mirror substitution is accelerating compliance documentation requirements for camera-monitor suppliers seeking type approval. The agency's evolving interpretation of field-of-view equivalence is forcing suppliers to redesign lens geometries and display aspect ratios. United States OEM engineering teams are pre-validating dual-stack architectures pending final rule publication.
Automotive procurement organizations are consolidating mirror system sourcing under integrated cockpit electronics contracts rather than discrete body-in-white component purchasing. Tier 1 suppliers with combined display and camera capabilities are capturing consolidated awards that previously split between glass and electronics specialists. This pattern concentrates most visibly in German and Japanese OEM program structures where cockpit integration complexity favors bundled suppliers.
Automotive Mirror System Market Segmentation
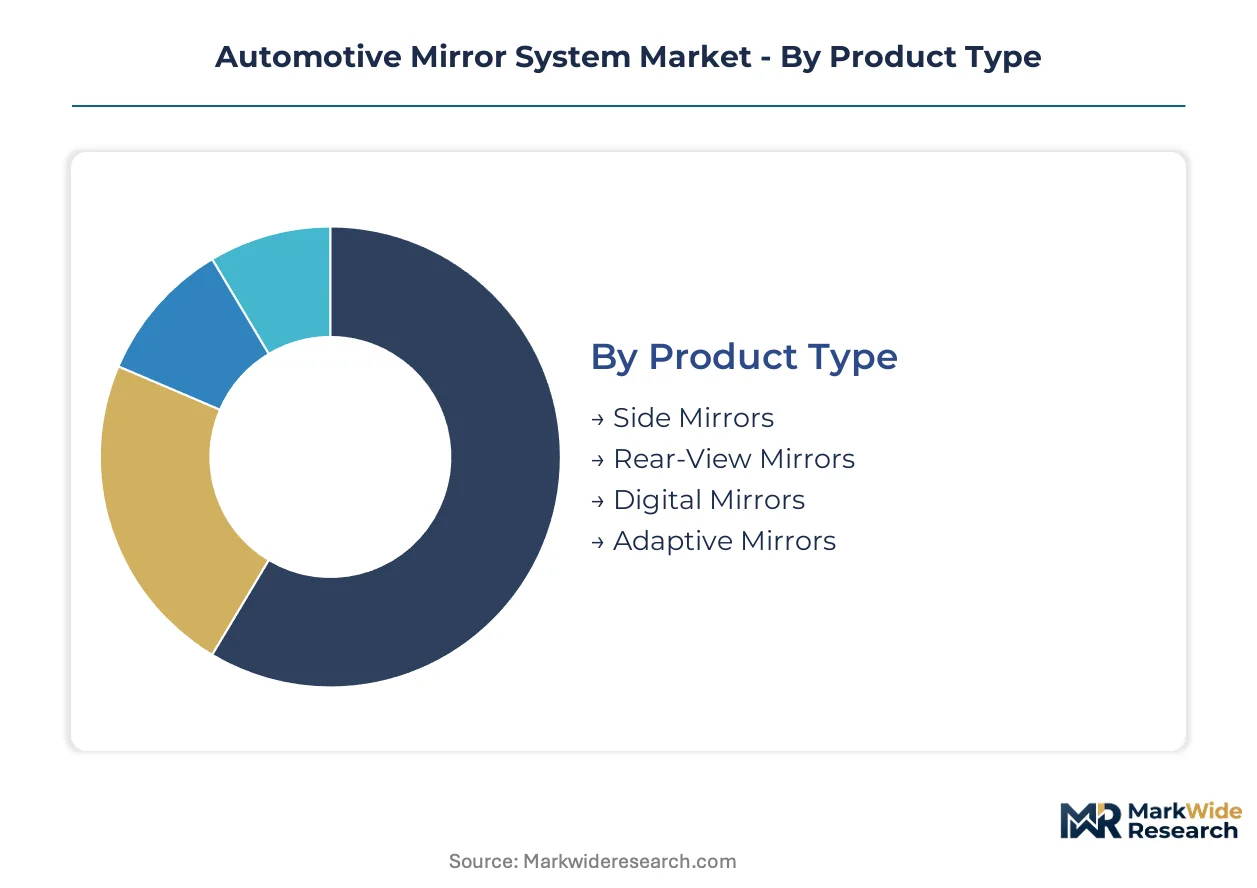
Mirror system segmentation reveals how hardware economics, regulatory permissions, and integration complexity fragment procurement patterns across vehicle programs. Each dimension exposes different margin structures and supplier capability requirements.
Product Type:
Cost tier differentiation separates commodity glass assemblies from premium digital architectures with diverging bill-of-materials trajectories.
- Side Mirrors:Exterior assemblies with precision-curved glass substrates between 1000mm and 1400mm radius dominate volume production. Fleet operators in Germany and Japan prioritize these units for commercial vehicle compliance with METI and KBA visibility mandates.
- Digital Mirrors:CMOS image sensors paired with OLED displays operating at 60Hz refresh rates command factory-installed premiums. Mercedes-Benz and BMW programs in Germany validate these architectures for mass-market deployment as ECE R46 permissions expand.
- Rear-View Mirrors:Interior-mounted units with electrochromatic dimming anchor mid-tier vehicle configurations across North American OEM programs.
- Adaptive Mirrors:Electro-mechanical assemblies with integrated turn signals and heating elements serve cold-climate vehicle specifications.
Side mirrors hold installed capacity. Digital mirrors are rotating up the share rankings.
Technology:
Application requirements determine whether latency tolerance permits camera-based substitution or mandates glass retention.
- Camera-Based:Image processing pipelines with sub-50ms latency thresholds enable full mirror replacement where NHTSA and ECE R46 frameworks permit. United States regulatory harmonization momentum would unlock single-stack engineering for North American OEM programs.
- Electrochromatic:Gel-filled glass assemblies with voltage-controlled dimming retain cost advantages in high-volume production. Gentex Corporation anchors this segment across North American OEM supply chains.
- LCD:Transmissive display layers integrated with prism optics serve hybrid mirror architectures requiring glass backup compliance.
- Traditional:Unpowered reflective glass with manual adjustment dominates emerging market vehicle configurations and aftermarket replacement demand.
Traditional technology holds installed capacity. Camera-based systems are climbing the fastest.
End User:
Customer type determines whether procurement flows through consolidated cockpit electronics contracts or discrete component sourcing.
- OEMs:Factory-installed integration programs bundle mirror systems with display and camera capabilities under consolidated cockpit electronics awards. German and Japanese OEM structures favor bundled suppliers with combined hardware competencies.
- Tier-1 Suppliers:Module assembly specialists like Magna International compete through integrated packages that bundle camera, display, and control electronics for direct OEM delivery.
- Aftermarket Providers:Retrofit specialists serve vehicle owners seeking visibility upgrades outside factory warranty periods.
- Vehicle Assemblers:Contract manufacturers without captive mirror production source complete assemblies from designated Tier-1 partners.
OEMs hold installed capacity. Tier-1 suppliers are gaining share fastest.
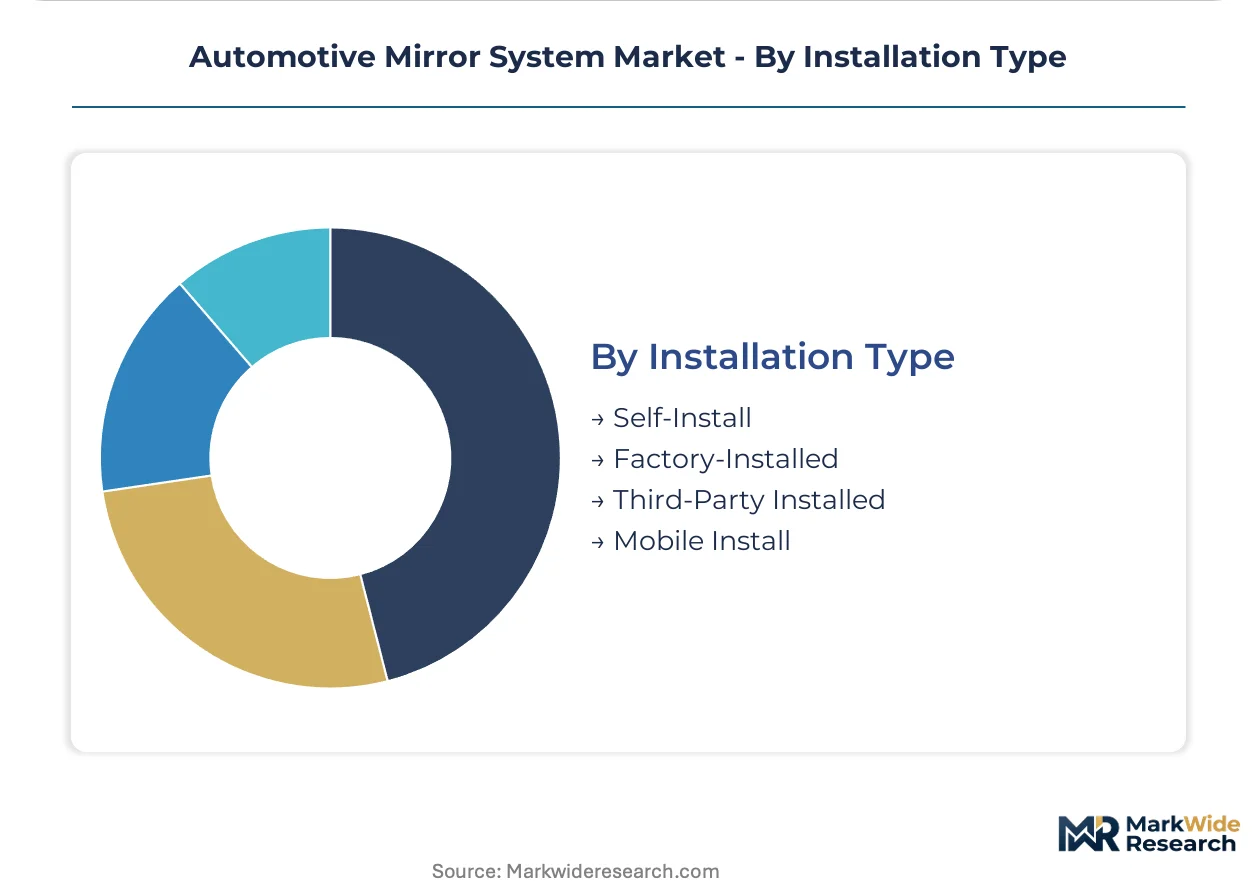
Installation Type:
Volume concentration separates high-margin factory integration from price-sensitive service channel alternatives.
- Factory-Installed:Production-line integration at vehicle assembly plants commands premium pricing through warranty alignment and calibration precision. OEM engineering teams pre-validate dual-stack architectures pending NHTSA final rule publication.
- Self-Install:Consumer-purchased replacement units with clip-on or adhesive mounting serve cost-sensitive vehicle owners.
- Third-Party Installed:Independent service centers handle warranty-adjacent replacements and visibility system upgrades.
- Mobile Install:Fleet service providers deliver on-site mirror replacement for commercial vehicle operators minimizing downtime.
Factory-installed holds installed capacity. Third-party installed is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium OEM engineering teams in Germany, Japan, and the United States drive factory-installed program development for next-generation mirror architectures. These buyers prioritize consolidated cockpit electronics sourcing over discrete component procurement.
United States
NHTSA regulatory review momentum is accelerating compliance documentation requirements for camera-monitor suppliers seeking type approval. The agency's evolving field-of-view equivalence interpretation is forcing lens geometry redesigns. Detroit-area OEM engineering teams are pre-validating dual-stack architectures pending final rule publication.
Germany
Mercedes-Benz and BMW platform integration programs validate camera-based architectures for mass-market deployment across next-generation vehicle lines. KBA visibility mandates align with ECE R46 permissions expanding mirror substitution allowances. Stuttgart and Munich industrial clusters concentrate electrochromatic glass and CMOS sensor module assembly capacity.
Japan
METI safety mandates for heavy-duty visibility systems create aftermarket demand for camera-monitor retrofits on existing truck fleets. Precision-curved mirror glass manufacturing concentrates in regional supply chains serving domestic OEM programs. Nagoya-area Tier-1 suppliers bundle camera, display, and control electronics for integrated module delivery.
South Korea
Hyundai and Kia factory-installed integration programs favor bundled suppliers with combined display and camera capabilities under consolidated cockpit electronics awards. Domestic semiconductor manufacturing scale is collapsing camera module economics. Seoul Capital Area module assemblers compete through integrated packages bundling image processing pipelines.
China
Domestic OEMs are piloting camera-based exterior visibility systems for commercial truck and bus platforms as image processing latency meets safety-critical thresholds. MIIT automotive standards shape local validation requirements for camera-monitor systems. Yangtze River Delta electronics clusters concentrate CMOS image sensor packaging and OLED display panel integration capacity.
Automotive Mirror System Market Competitive Environment
Channel-controlling players compete with product-specialist players for consolidated cockpit electronics awards. The vendor base organizes around three strategic archetypes: integrated module assemblers bundling camera-display-control packages, electrochromatic glass specialists anchoring smart dimming segments, and camera-vision system providers extending into surround-view architectures. Dominant competitive moves include strategic partnerships for image processing pipeline access and portfolio diversification into adjacent cockpit electronics.
Among North American-based suppliers, Gentex Corporation and Magna International Inc. occupy positions within the integrated electronics tier. Valeo SA represents the European camera-vision archetype. These three companies exemplify how geographic origin and company structure correlate with strategic positioning across glass-based refinement and digital architecture pathways.
| Leading Market Players |
|---|
| Ficosa International S.A. |
| SL Corporation |
| Gentex Corporation |
| FLABEG Automotive Glass Group GmbH |
| Panasonic Holdings Corp. |
| Magna International Inc. |
| Murakami Corporation |
| Ichikoh Industries Ltd. |
| Valeo SA |
| Others |
Value Chain & Pricing Dynamics
Yokohama-to-Long Beach container lane volatility feeds directly into camera module landed costs, compressing margins for digital mirror suppliers while amplifying price spreads between Japanese electrochromatic glass and Korean OLED-display alternatives. OEM procurement teams exploit this freight asymmetry to extract tiered concessions from suppliers clustered in East Asian manufacturing corridors.
Pricing Analysis
Cost-plus contracts with quarterly semiconductor indexation dominate OEM-Tier 1 agreements, embedding CMOS sensor spot-market swings directly into component pricing. Three-tier pricing structure across premium digital, mid-tier electrochromatic, and economy traditional glass separates Mercedes-Benz flagship programs from fleet-vehicle commodity procurement. Pricing pressure stems from collapsing image sensor economics as Korean foundries expand automotive-grade CMOS capacity. Aftermarket retrofit channels exhibit highest price sensitivity; factory-installed OEM programs retain lowest sensitivity due to warranty bundling and calibration service lock-in.
Supply Chain Analysis
Export-control restrictions on advanced CMOS image sensors and OLED driver ICs limit technology flows from Taiwan and South Korea to Chinese module assemblers, fragmenting procurement networks. Precision-curved glass substrates draw from Japanese and German specialty manufacturers; CMOS sensors and OLED panels rest on Taiwanese and Korean semiconductor fabs. Single-source vulnerability concentrates in automotive-grade OLED display supply, where three panel makers control factory-installed qualification pathways. Distribution runs through consolidated cockpit electronics contracts rather than discrete component sourcing, favoring bundled Tier 1 suppliers with direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Camera-to-display substitution threatens glass-based incumbents with platform-level displacement as regulatory permissions expand; defensive repositioning around integrated electronics bundling becomes essential for margin preservation.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into CMOS sensor packaging and OLED display driver firmware, securing supply continuity as Taiwan export controls tighten. Anchor electrochromatic glass positions through exclusive Mercedes-Benz and BMW platform contracts while building parallel camera-monitor engineering capacity to serve dual-stack OEM requirements. Certification investment in ISO 16505 validation laboratories creates switching costs that lock out emerging competitors. For New Entrants and Emerging Players: Establish a beachhead in Japan commercial vehicle retrofit channels where METI mandates drive fleet-upgrade demand and incumbent presence remains thin. Target heavy-duty truck camera-monitor retrofits as the most penetrable segment, exploiting legacy vehicle electronics compatibility gaps that Tier 1 suppliers ignore. Pursue direct fleet-operator sales partnerships bypassing traditional aftermarket distribution layers. For Investors and Strategic Acquirers: NHTSA final rule publication on full mirror substitution reshapes the acquisition landscape by validating single-stack engineering economics and de-risking camera-first platform bets. Long-term viability favors suppliers with combined glass and digital competencies that span regulatory regime uncertainty. Watch ECE R46 expansion into mass-market vehicle categories as the signal indicating acceleration toward camera-dominant architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Stack Platform Engineering | Maintains market access across jurisdictions with divergent glass-backup requirements. |
| CMOS Sensor Backward Integration | Captures cost compression from Korean foundry expansion while securing supply priority. |
| OLED Display Convergence Investment | Enables surround-view architectures extending beyond mirror replacement into full cabin visibility. |
| Commercial Vehicle Retrofit Channel Development | Accesses Japan heavy-duty fleet demand driven by METI safety mandate compliance deadlines. |
| ISO 16505 Validation Laboratory Certification | Creates regulatory compliance barriers that disadvantage unqualified competitors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distribution specialists, and fleet operations managers at commercial vehicle operators. Secondary validation drew from NHTSA rulemaking dockets, ECE R46 regulatory submissions, vehicle production databases, and semiconductor trade flow records. Bottom-up component demand modeling triangulated against top-down OEM program value estimates.
Calibration against historical technology substitution patterns in adjacent automotive electronics categories anchored projection confidence intervals. Segmentation modeling spanned product type, technology architecture, installation channel, and regional regulatory cluster across the analysis window. CAGRs derived from bill-of-materials trajectory analysis and OEM program volume ramps, with image sensor cost curves and display panel supply expansion as primary forecast inputs.
Stress conditions across NHTSA rulemaking delays, Taiwan semiconductor export escalation, and German OEM platform cancellation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against IHS Markit vehicle registration data and semiconductor foundry capacity announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Whiplash Protection System Market
Automotive Safety and Security Systems
Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Anti-Fog Lights Market
Automotive Safety and Security Systems
Automotive Airbag and Seat Belt Market
Automotive Safety and Security Systems
Automotive Anti Lock Braking System and Electronic Stability Control Market
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Automotive Brake Actuation Systems Market
Automotive Safety and Security Systems
Start Stop System Market
Automotive Safety and Security Systems
Electronic Stability Control System Market
Automotive Safety and Security Systems
Automotive Anti-Roll Bar Market
Automotive Safety and Security Systems
Automotive Lane Warning System Market