
 Automotive Upholstery Market | 2026-2036
Automotive Upholstery Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Upholstery Market Intelligence
Synthetic microfiber blends replacing traditional leather in mass-market seating is recalibrating cost structures across tier-one supply chains. Lear Corporation leverages captive polymer research to anchor North American OEM contracts. Faurecia dominates European sustainable upholstery programs through integrated recycling streams. Seiren Co. Ltd specializes in precision-knit fabrics for Asian premium platforms.
Automotive upholstery encompasses engineered textiles, coated polymers, and treated hides applied to vehicle interior surfaces, typically meeting abrasion resistance above 100,000 Martindale cycles and flame-retardant standards for occupant safety. Its primary purpose spans aesthetic cabin finishing, ergonomic support, and thermal-acoustic management. Leather and vinyl command margin pools in premium SUV configurations where customization levels stratify across luxury and standard tiers. Fabric and polyester segments lead hatchback and sedan volume production across cost-sensitive markets.
EPA emissions protocols and REACH chemical frameworks restrict volatile organic compound release from adhesive and coating processes, compelling suppliers to reformulate solvent systems. ECHA substance evaluations further pressure chrome-tanning substitution in European leather supply chains. NHTSA flammability standards govern seating materials in the United States, creating compliance differentiation among exporters. Stakeholders must monitor regulatory convergence between EU Green Deal material circularity requirements and emerging state-level restrictions in California and New York.
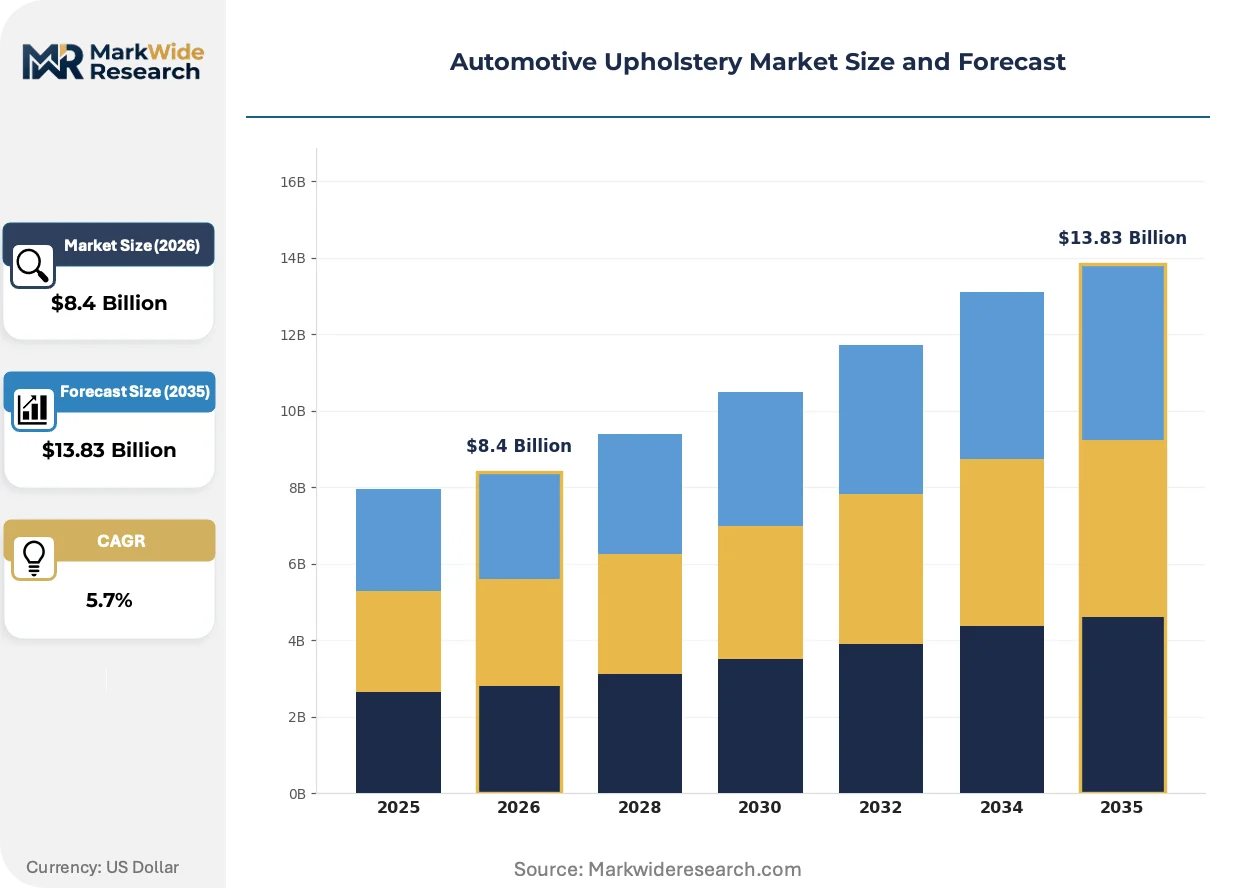
Market Dynamics
Synthetic microfiber blends are compressing traditional leather economics across mass-market seating tiers, forcing tier-one suppliers to recalibrate polymer sourcing strategies and captive production investments.
Growth Catalysts
- REACH chemical restrictions:European ECHA substance evaluations mandate chrome-free tanning processes, accelerating bio-based leather alternative development across German and Italian supply chains.
- Luxury SUV customization:Premium vehicle configurations now specify multi-zone climate-adaptive upholstery with integrated heating elements, expanding material specification complexity per vehicle.
- China:Domestic OEMs concentrate next-generation cabin system sourcing decisions in Shanghai and Guangzhou, anchoring regional polymer textile innovation clusters.
Market Restraints
- Petrochemical feedstock volatility:Polyester and polyurethane input costs fluctuate with crude oil indices, compressing margin predictability for synthetic upholstery producers.
- Chrome-tanning substitution costs:Vegetable and synthetic tanning agents require 40% longer processing cycles, limiting throughput at European tanneries under ECHA pressure.
- Technical abrasion thresholds:Martindale cycle requirements above 100,000 for commercial fleet applications exclude lower-grade fabric suppliers from contract eligibility.
Strategic Opportunities
- India:PLI scheme incentives for automotive component manufacturing attract upholstery suppliers to Tamil Nadu and Gujarat production corridors.
- Closed-loop recycling:EU Green Deal material circularity requirements create first-mover advantage for suppliers with integrated fiber-to-fiber regeneration capabilities.
- Digital textile printing:On-demand pattern customization enables micro-batch production for limited-edition vehicle runs, collapsing traditional minimum order quantities.
Industry Challenges
- Polymer chemistry specialization:Formulating low-VOC adhesives compliant with both EPA guidelines and REACH frameworks requires scarce cross-disciplinary expertise in materials science and regulatory affairs.
- Flammability certification timelines:NHTSA testing protocols for seating materials extend validation cycles by 8-12 months, delaying contract awards for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Upholstery Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Vinyl, Fabric, Polyester Vehicle Type: Sedan, SUV, Hatchback, Truck Application: Seating, Door Panels, Headliners, Carpets Customization Level: Standard, Customized, Premium, Luxury |
| Companies Covered | Faurencia, Sage Automotive Interiors, Lear Corporation, Hayashi Telempu, Grupo Antolin, Adient, Seiren Co. Ltd, Toyobo, Toyota Boshoku Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Upholstery Market Strategic Shifts & Innovations
Material science convergence with digital manufacturing is collapsing traditional upholstery production economics, enabling mass customization at previously unattainable unit costs.
Algae-based bio-leather alternatives are rewriting supply assumptions for premium vehicle interiors. BMW and Mercedes-Benz specification teams now source pilot volumes from European biotechnology suppliers. This material compression is forcing traditional tanneries to defend position through accelerated chrome-free process investment.
California and New York state-level restrictions on perfluorinated compounds are extending beyond federal EPA baselines, creating a bifurcated compliance landscape for North American suppliers. Upholstery producers serving multi-state OEM distribution must maintain dual formulation inventories. Fleet operators in these jurisdictions now specify certified fluorine-free interior packages as standard procurement terms.
Direct-to-OEM digital sampling platforms are compressing traditional distributor channels. Tier-one seating manufacturers now specify materials through virtual renderings and accelerated physical prototyping, bypassing historical textile merchant intermediaries. This disintermediation is most advanced in German and Japanese premium supply relationships, where specification cycles have shortened from 18 months to 9 months.
Automotive Upholstery Market Segmentation
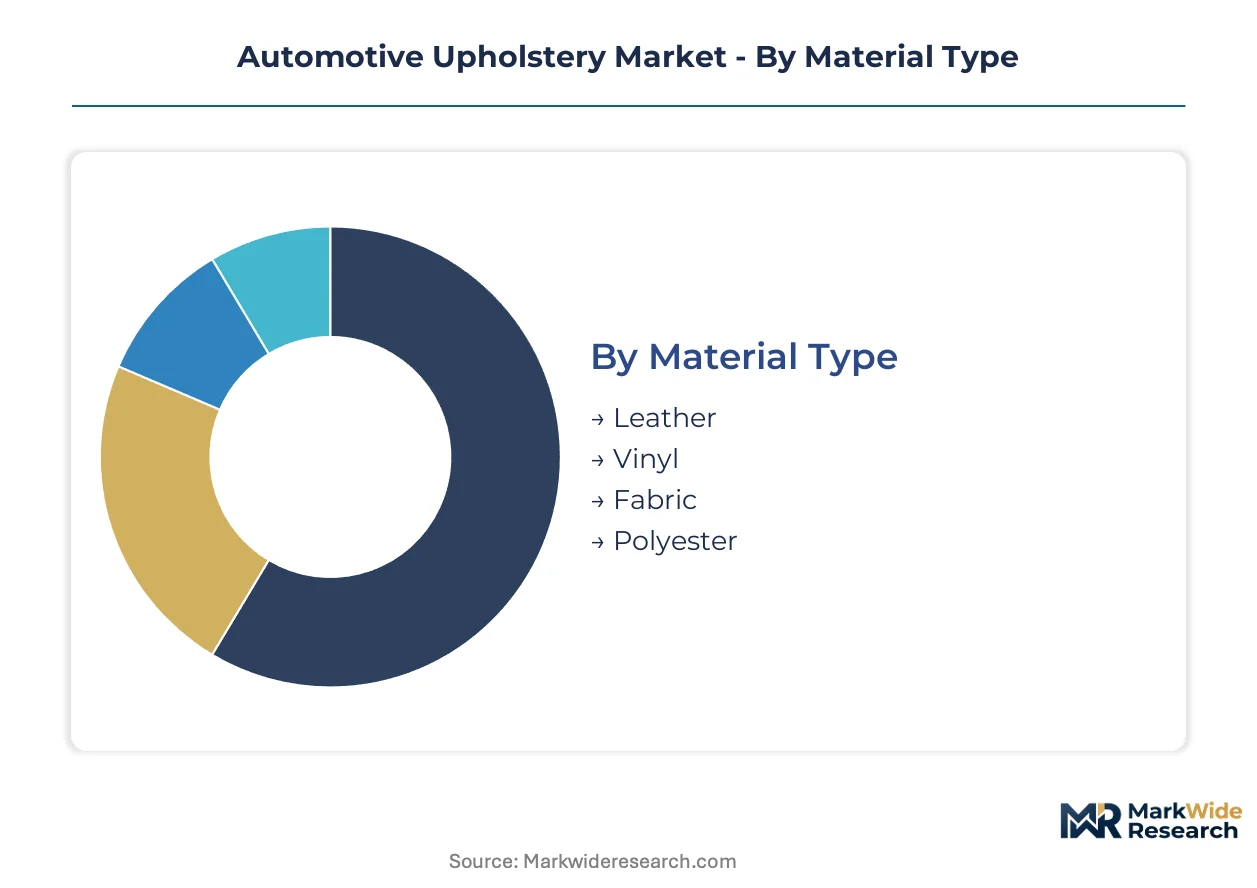
Material specification and vehicle architecture determine cost structures and margin pools across automotive upholstery supply chains. Tier-one suppliers calibrate production investments against these segment boundaries to align with OEM platform strategies.
Material Type:
Customization intensity escalates from commodity synthetics through precision-engineered hides, with each tier demanding distinct polymer chemistry or tanning expertise.
- Leather:Chrome-free and vegetable-tanned hides meet REACH ECHA mandates for European premium vehicle programs. German and Italian OEM specification teams now require bio-based alternatives for luxury SUV configurations.
- Vinyl:Polyvinyl chloride formulations with phthalate-free plasticizers dominate commercial fleet seating where abrasion resistance thresholds exceed 100,000 Martindale cycles. Cost predictability attracts mass-market procurement teams despite petrochemical feedstock volatility.
- Fabric:Woven nylon and wool blends serve mid-tier sedan production with balanced durability-to-cost ratios.
- Polyester:Recycled PET fiber streams align with EU Green Deal circularity requirements for hatchback volume programs.
Most installed capacity flows through vinyl for fleet and mass-market applications. Expansion is steepest in leather alternatives as bio-based tanning technologies mature.
Vehicle Type:
Cabin architecture scales upholstery complexity from compact passenger compartments through multi-zone commercial configurations.
- Sedan:Standardized seat frames and door panel geometries enable high-volume fabric and polyester deployment across cost-sensitive markets.
- SUV:Multi-row seating configurations with integrated climate elements command premium leather and microfiber specifications. Chinese domestic OEMs anchor next-generation cabin sourcing for this segment in Shanghai innovation clusters.
- Hatchback:Compact interior surfaces prioritize lightweight synthetic textiles for fuel efficiency compliance.
- Truck:Heavy-duty abrasion standards and commercial fleet procurement terms favor reinforced vinyl and coated fabric systems.
Production volume concentrates in sedan platforms. Margin expansion is most pronounced in SUV configurations where customization tiers multiply per-vehicle material value.
Application:
Surface area exposure and occupant contact frequency differentiate material performance requirements across cabin zones.
- Seating:Ergonomic support structures with integrated heating elements specify multi-layer foam and textile laminates. NHTSA flammability certification extends validation timelines for new seating material entrants.
- Door Panels:Aesthetic finishing with acoustic dampening properties employs coated fabrics and synthetic leather in premium configurations.
- Headliners:Lightweight knit fabrics with thermal insulation properties reduce HVAC energy load in electric vehicle architectures.
- Carpets:Tufted nylon and recycled polymer backings meet abrasion and moisture resistance standards for footwell exposure.
Seating applications command the largest material volume share. Technical specification complexity is advancing fastest in headliner systems as thermal management integrates with battery thermal strategies.
Customization Level:
Procurement tiering separates fleet standardization from atelier-level personalization with direct consumer specification involvement.
- Standard:Fixed specification catalogs with 12-18 month production runs minimize tooling changeover costs for high-volume OEM contracts.
- Customized:Digital textile printing enables micro-batch pattern variation for limited-edition vehicle programs. On-demand production collapses traditional minimum order quantities.
- Premium:Multi-zone climate-adaptive upholstery with contrast stitching and branded embossing differentiates mid-luxury SUV tiers.
- Luxury:Bespoke hide selection and hand-finished detailing serve flagship sedan and ultra-premium SUV segments where material origin documentation is mandatory.
Standard specifications absorb the majority of production capacity. Value expansion is most rapid in customized tiers where digital manufacturing compresses batch economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors next-generation cabin system sourcing decisions for automotive upholstery, concentrating polymer textile innovation clusters that serve domestic OEM specification teams across multiple vehicle platforms.
China
Domestic OEMs in Shanghai and Guangzhou drive specification complexity for multi-zone climate-adaptive seating systems. MIIT dual carbon goals pressure suppliers toward recycled PET fiber streams and low-VOC adhesive formulations. The Yangtze River Delta hosts the densest concentration of precision-knit fabric production for Asian premium platforms.
Germany
Luxury SUV customization tiers multiply per-vehicle material value as BMW and Mercedes-Benz specification teams source bio-leather alternatives. ECHA REACH frameworks mandate chrome-free tanning processes, accelerating vegetable-tanning investment across Baden-Württemberg tanneries. Bavaria hosts integrated recycling streams that dominate European sustainable upholstery programs.
United States
EPA emissions protocols restrict volatile organic compound release from adhesive and coating processes, compelling reformulation of solvent systems across Michigan and Ohio production corridors. NHTSA flammability standards govern seating materials, extending validation cycles for new market entrants. California state-level restrictions on perfluorinated compounds create bifurcated compliance requirements for multi-state suppliers.
India
PLI scheme incentives for automotive component manufacturing attract upholstery suppliers to Tamil Nadu and Gujarat production corridors. BIS standards govern textile abrasion resistance for domestic vehicle programs. Domestic OEM procurement teams in Pune and Chennai concentrate sourcing decisions for hatchback volume production.
Japan
METI industrial policy supports precision-knit fabric development for premium vehicle exports. JIS standards establish technical abrasion thresholds that exclude lower-grade suppliers from contract eligibility. The Nagoya industrial corridor concentrates seating system integration expertise for global OEM supply relationships.
Automotive Upholstery Market Key Industry Players
Global majors compete with regional champions across material technology and OEM specification relationships. The vendor base organizes around three tiers: integrated seating system suppliers with captive polymer research, specialized textile manufacturers with precision-knit capabilities, and diversified automotive component groups with cross-platform upholstery portfolios. Strategic differentiation flows from backward integration into polymer chemistry, geographic proximity to OEM engineering centers, and regulatory compliance certification breadth. M&A activity targets digital textile printing capabilities and bio-based material startups, while capacity expansion concentrates in Indian and Southeast Asian production corridors.
Within the integrated seating tier, Lear Corporation exemplifies North American OEM contract anchoring through captive polymer research infrastructure. Faurecia occupies a position representing European sustainable upholstery leadership through integrated recycling capabilities. Seiren Co. Ltd anchors the precision-knit specialization archetype for Asian premium platform supply. These three entities represent distinct competitive vectors: polymer chemistry control, circular production systems, and textile engineering precision.
| Leading Market Players |
|---|
| Faurencia |
| Sage Automotive Interiors |
| Lear Corporation |
| Hayashi Telempu |
| Grupo Antolin |
| Adient |
| Seiren Co. Ltd |
| Toyobo |
| Toyota Boshoku Corporation |
| Others |
Cost & Logistics Intelligence
Synthetic microfiber blend adoption is compressing traditional leather economics while simultaneously concentrating polymer sourcing decisions among suppliers with captive R&D infrastructure. This production-method transition rewards tier-one seating manufacturers with backward integration into polymer chemistry, while marginalizing merchant textile distributors unable to absorb petrochemical feedstock volatility.
Pricing Analysis
Petrochemical feedstock pass-through dominates synthetic upholstery cost structures, with polyester and polyurethane input fluctuations transmitted directly to OEM contract renegotiations. Pricing stratifies across premium, standard, and economy tiers based on abrasion certification thresholds and climate-adaptive feature integration. Cost compression in mass-market vinyl seating is intensifying because of crude oil index volatility. Fleet procurement teams exhibit highest price sensitivity, while luxury SUV specification teams prioritize material origin documentation over unit cost.
Supply Chain Analysis
India's PLI scheme local-content requirements are reshaping sourcing patterns, compelling established suppliers to establish Tamil Nadu and Gujarat production footprints or forfeit domestic OEM eligibility. Raw material flows draw from German tanning chemical specialists, Chinese polymer fiber streams, and Japanese precision-knit equipment manufacturers. Single-source vulnerability concentrates in chrome-free tanning agent supply from Baden-Württemberg chemical producers. Distribution runs through tier-one seating system integrators with direct OEM engineering relationships, bypassing traditional textile merchant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive upholstery market reads as a late-cycle quality story, with luxury SUV multi-zone climate-adaptive specifications commanding expanding material investment per vehicle despite plateauing global production volumes.
For Market Incumbents: Hedge against bio-leather substitution by accelerating vegetable-tanning process investment and securing exclusive biotechnology supplier partnerships. Chrome-free certification breadth represents the critical defensive lever against emerging European tanneries with integrated recycling streams. Capacity addition in Indian production corridors captures PLI scheme incentives before qualification windows narrow. For New Entrants and Emerging Players: Enter via digital textile printing capabilities serving limited-edition vehicle programs, where on-demand pattern customization collapses traditional minimum order quantities. The most penetrable white-space sits in micro-batch production for Chinese domestic OEM premium platforms, with virtual rendering specification relationships as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among precision-knit fabric specialists with Asian premium platform supply relationships and unexploited EU Green Deal circularity certification potential. Long-term viability hinges on fiber-to-fiber regeneration capabilities aligning with material circularity mandates. The signal to monitor is accelerated OEM specification team adoption of algae-based bio-leather alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Tanning Process Investment | ECHA REACH compliance secures European luxury SUV contract eligibility for German and Italian supply chains. |
| Digital Textile Printing Capability Acquisition | On-demand pattern customization collapses minimum order quantities for limited-edition vehicle programs. |
| Recycled PET Fiber Stream Integration | EU Green Deal material circularity requirements create first-mover advantage in hatchback volume production. |
| Precision-Knit Fabric R&D Expansion | Asian premium platform specifications demand Seiren Co. Ltd-level textile engineering precision. |
| India PLI Scheme Production Footprint | Tamil Nadu and Gujarat corridors attract upholstery suppliers seeking domestic OEM contract access. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tier-one seating procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers with secondary validation against vehicle production databases, IHS Markit registration data, customs records, and SEC filings from listed automotive component suppliers. Bottom-up segment sizing and top-down market triangulation checked for consistency across modeling approaches.
Segment-weighting across material type, vehicle architecture, application surface, and customization tier determined value distribution throughout the projection horizon. CAGRs derived from fitted growth curves applied to baseline volume data, with specific inputs including Martindale cycle certification thresholds, REACH chemical restriction implementation timelines, and MIIT dual carbon goal compliance trajectories.
Inputs from OEM specification teams and tier-one supplier procurement leads were available through the study window; gaps in real-time bio-leather alternative production cost data introduce uncertainty bands around premium segment forecasts. Forecasts reflect documented assumptions regarding regulatory convergence between EU Green Deal requirements and emerging state-level restrictions. A small set of named triggers—including accelerated algae-based material adoption, petrochemical price spike duration, and PLI scheme incentive modification—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Seats Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Global Automotive Anti Vibration Mounting Market
Automotive Interior & Exterior
LED Fog Lamp Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Africa and Middle East Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Decorative Interior Trim Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Display Market