
 Asia-Pacific Automotive Flooring Market | 2026-2036
Asia-Pacific Automotive Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Flooring Market Analytics
Fleet operators are reorganizing procurement priorities toward durable, low-maintenance flooring solutions as ride-sharing platforms expand vehicle utilization rates across Southeast Asia. Toyota Boshoku Corporation leverages its captive textile operations to control nylon carpet supply chains from polymer to finished mat. Hyundai Mobis Co. Limited anchors its flooring division within broader interior module integration, bundling carpets with acoustic packages for Hyundai-Kia platforms. Suminoe Textile Co., Ltd. specializes in needle-punch and tufted constructions for Japanese OEM specifications, sustaining long-term supply relationships with Toyota and Honda.
Asia-Pacific automotive flooring encompasses textile and polymer-based surface systems installed in passenger and commercial vehicle cabins, typically manufactured through tufting, needle-punching, or extrusion processes with pile weights ranging from 400 to 1200 grams per square meter and integrated foam backing layers for acoustic absorption. These systems serve primarily to enhance occupant comfort, reduce road noise transmission, and protect vehicle structural substrates from wear and moisture ingress. Nylon material formulations lead volume share due to superior abrasion resistance and dyeability for premium color matching, while polypropylene competes aggressively on cost in entry-level segments where OEMs prioritize lightweighting targets. The aftermarket installation channel grows fastest as Indonesia, Thailand, and Vietnam see rising vehicle age profiles and independent service network expansion, though OEM integrated flooring retains the deepest margin pools through long-term platform contracts.
China's MIIT enforces GB standards for interior material emissions and recyclability, while Japan's METI administers JIS specifications for flame resistance and VOC limits in automotive textiles. India's BIS and CDSCO frameworks are converging toward mandatory ELV compliance for carpet and mat constituents, tightening market access for uncertified imports. Stakeholders must monitor how ASEAN harmonization of automotive material standards reshapes cross-border supplier qualification requirements.
Market Dynamics
Electric vehicle OEMs across China, Japan, and South Korea are mandating lighter, recyclable flooring systems to meet aggressive weight-reduction targets tied to battery range extension and carbon compliance frameworks.
Growth Catalysts
- China's MIIT dual carbon goals:Mandatory recyclability quotas for automotive interior materials are accelerating OEM adoption of thermoplastic olefin backing layers in Yangtze River Delta assembly plants.
- Ride-sharing fleet expansion:Grab, Gojek, and regional operators across Southeast Asia are prioritizing stain-resistant nylon formulations that withstand utilization rates exceeding 200,000 kilometers annually.
- Needle-punch process innovation:Advanced fiber entanglement technologies enable 15-20% weight reduction versus traditional tufting while maintaining acoustic absorption performance for EV platforms.
Market Restraints
- Caprolactam price volatility:Nylon 6 raw material costs fluctuate with crude oil derivatives, compressing margins for carpet manufacturers serving entry-level vehicle segments.
- Supply concentration in Zhejiang Province:Over 60% of Asia-Pacific polypropylene resin for automotive textiles originates from a three-facility cluster vulnerable to environmental compliance shutdowns.
- Flame-retardant formulation limits:Japan's METI JIS standards restrict halogen-based additives, forcing costly reformulation of established PVC backing chemistries.
Strategic Opportunities
- Indonesia aftermarket channel:Vehicle age profiles exceeding eight years and independent service network expansion create demand for replacement carpet and mat systems outside OEM capture.
- Acoustic-thermal integration:Convergence of flooring substrates with battery pack insulation layers opens module bundling opportunities for tier-one suppliers serving dedicated EV architectures.
- India's PLI scheme for auto components:Production-linked incentives for advanced materials manufacturing are attracting carpet system investments in Tamil Nadu and Gujarat industrial corridors.
Industry Challenges
- Multi-standard certification complexity:Suppliers must simultaneously validate products against China's GB emissions standards, Japan's JIS flame resistance protocols, and emerging ASEAN harmonization drafts, extending qualification timelines by 8-12 months.
- Recycled-content traceability:OEMs require polymer-to-finished-goods documentation for post-consumer nylon feedstocks, demanding capital investment in spectroscopic verification equipment across subcontractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Flooring Market |
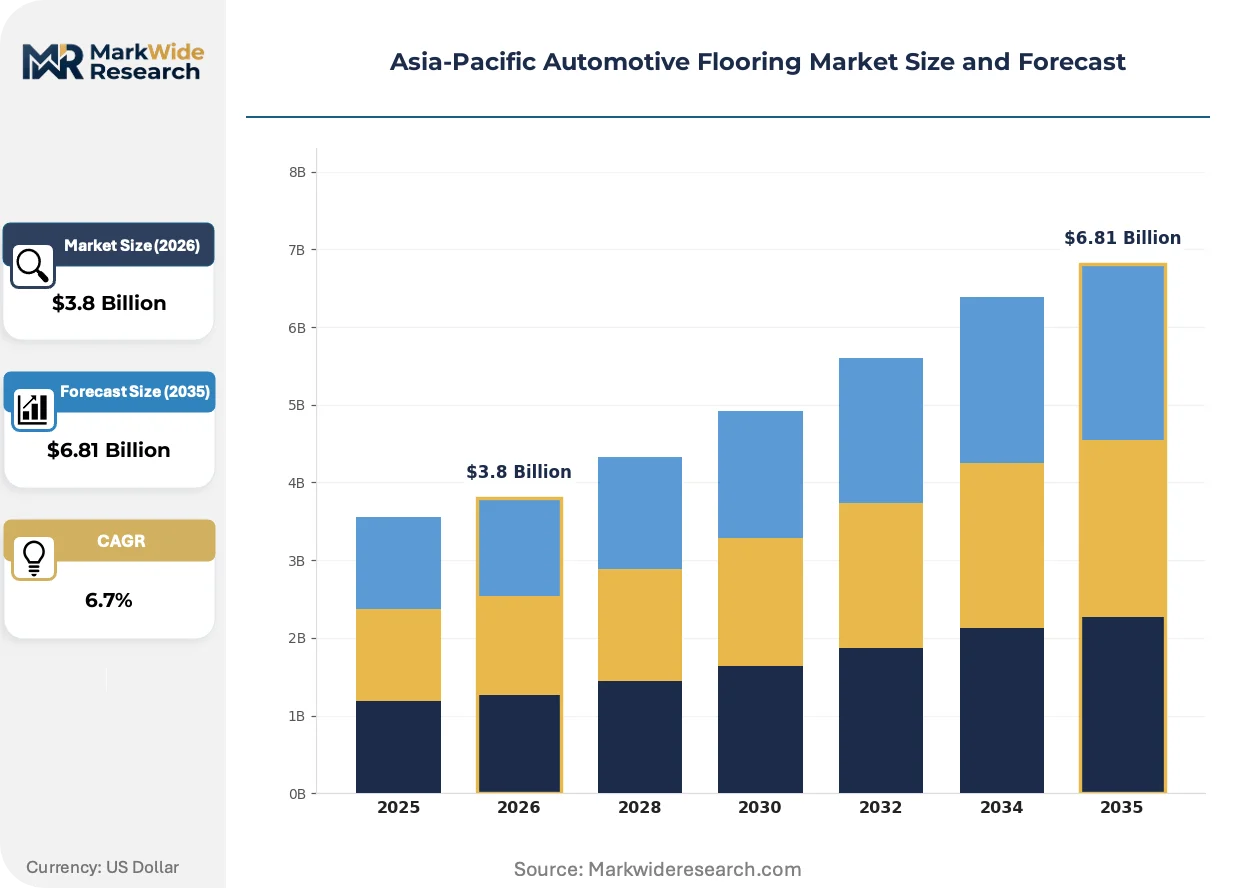
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpets, Mats, Liners, Sound Deadening Material: Rubber, Polypropylene, Nylon, Vinyl End User: OEMs, Aftermarket, Dealers, Fleet Operators Installation Type: Integrated, Custom Fit, Universal Fit, DIY |
| Companies Covered | Toyota Boshoku Corporation, Hyundai Mobis Co. Limited, Suminoe Textile Co., Ltd., Hayashi Telempu, Shanghai Shenda, Autoneum Holding AG, Lear Corporation, Magna International Inc, Shandong Exceeding Auto Interior Parts Co., Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Flooring Market Evolving Landscape
Material science breakthroughs and regulatory tightening are converging to transform how flooring systems are engineered, certified, and procured across Asia-Pacific vehicle programs.
Bio-based polyamide formulations derived from castor oil feedstocks are displacing petroleum-based nylon 6,6 in premium EV applications. Mercedes-Benz and BMW sourcing teams in China have qualified these materials for 2026 platform launches. The shift is compressing demand for conventional caprolactam supply chains while opening qualification pathways for Indian and Thai agricultural processors.
Japan's METI has tightened JIS L 1091 flame resistance testing protocols for automotive textiles, requiring self-extinguishing performance within three seconds versus the previous five-second threshold. Tier-one suppliers serving Toyota and Honda must retest entire product lines, with commercial vehicle segments facing the steepest compliance cost increases due to heavier pile weight constructions.
Fleet procurement teams at Grab and regional leasing operators are unbundling flooring replacement cycles from traditional full-vehicle maintenance schedules. Standalone carpet refresh contracts now cover 60,000-kilometer intervals in Thailand and Vietnam, displacing OEM-specified 100,000-kilometer replacement norms. This compression is redirecting volume toward fast-turn regional compounders capable of 72-hour color-matching turnaround.
Asia-Pacific Automotive Flooring Market Segmentation
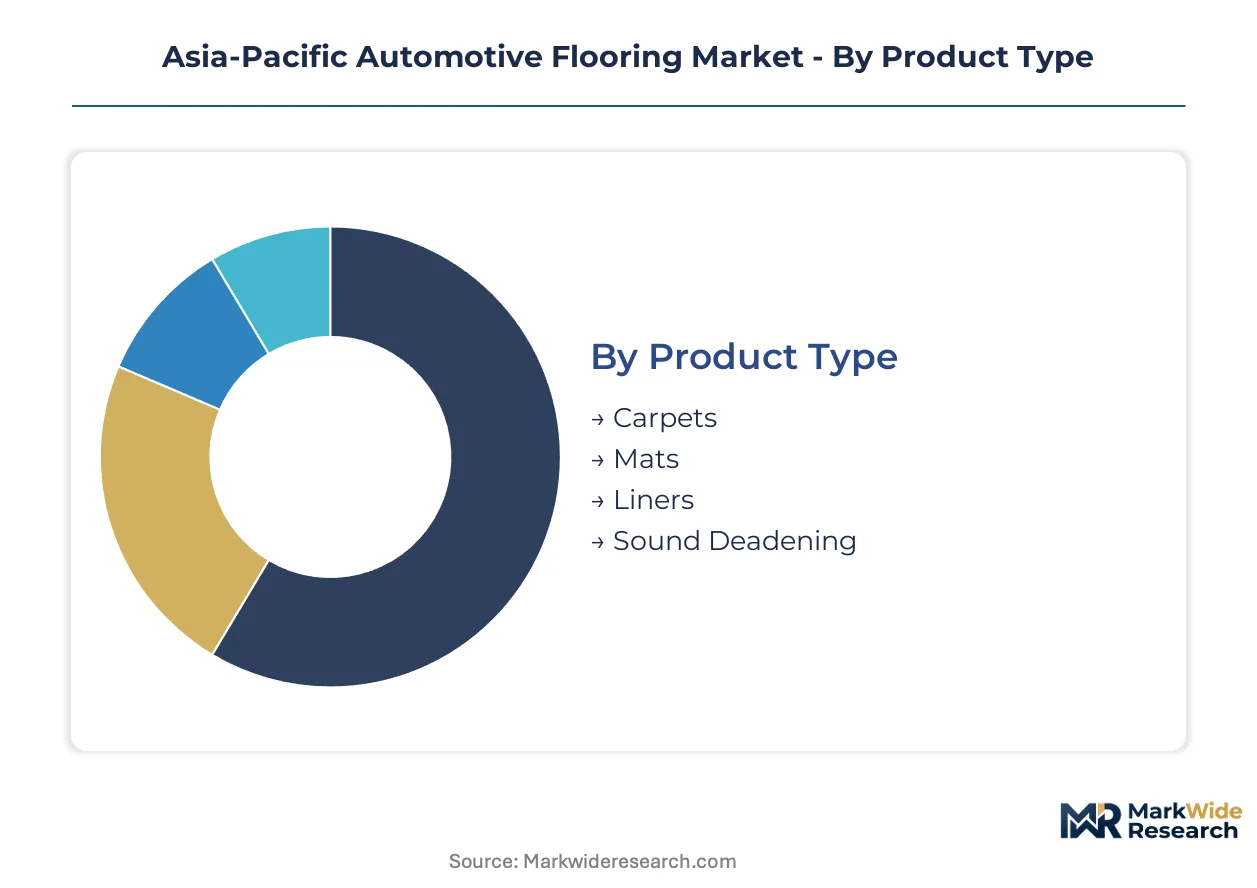
Asia-Pacific automotive flooring procurement splits sharply between domestic vehicle assembly and export-driven component supply. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume expansion accelerates.
Product Type:
Carpets dominate domestic OEM supply in China and Japan, while mats and liners flow disproportionately to Southeast Asian aftermarket channels serving aging vehicle parc.
- Carpets:Tufted and needle-punch constructions with 400-1200 gram per square meter pile weights serve as primary cabin flooring in passenger vehicles. Toyota, BYD, and NIO assembly plants in the Yangtze River Delta anchor demand for integrated acoustic-backed systems meeting MIIT recyclability mandates.
- Mats:Removable floor protection systems in rubber, polymer, or carpet-face constructions address replacement cycles compressed by Grab and Gojek fleet operators to 60,000-kilometer intervals across Thailand and Vietnam.
- Liners:Thermoformed polymer trays for cargo and footwell zones gain traction in commercial vehicle specifications requiring moisture containment.
- Sound Deadening:Multi-layer foam and mass-loaded vinyl composites integrate with flooring substrates to meet EV platform NVH targets.
Carpets command the established base. The steepest expansion runs through mats as fleet utilization rates reshape replacement economics.
Material:
Material selection tracks directly against vehicle segment positioning and regulatory compliance tier, with premium EV platforms demanding traceable recycled content.
- Nylon:Superior abrasion resistance and dyeability sustain dominance in premium passenger vehicle programs. Mercedes-Benz and BMW sourcing teams in China have qualified bio-based polyamide formulations for upcoming platform launches, compressing conventional caprolactam demand.
- Polypropylene:Cost-optimized formulations compete aggressively in entry-level segments where OEMs prioritize lightweighting targets, though supply concentration in Zhejiang Province creates vulnerability to environmental compliance shutdowns.
- Rubber:Heavy-duty formulations serve commercial vehicle and fleet applications requiring extended durability under high-utilization regimes.
- Vinyl:PVC backing chemistries face forced reformulation as Japan's METI JIS standards restrict halogen-based flame retardant additives.
Nylon retains the premium tier. Polypropylene captures volume scale in cost-sensitive domestic markets.
End User:
Procurement authority concentrates with OEMs for integrated systems, while aftermarket channels fragment across independent service networks and fleet direct contracts.
- OEMs:Integrated flooring contracts tied to long-term platform specifications deliver the deepest margin pools, with Toyota Boshoku and Hyundai Mobis controlling captive supply chains.
- Aftermarket:Independent service network expansion across Indonesia, Thailand, and Vietnam redirects volume toward fast-turn regional compounders capable of rapid color-matching turnaround.
- Dealers:Authorized service channels capture warranty-period replacements and upgrade sales in structured OEM ecosystems.
- Fleet Operators:Grab, Gojek, and regional leasing platforms unbundle flooring refresh cycles from full-vehicle maintenance schedules, creating standalone contract opportunities.
OEMs lock in platform economics. Fleet operators are compressing replacement intervals fastest.
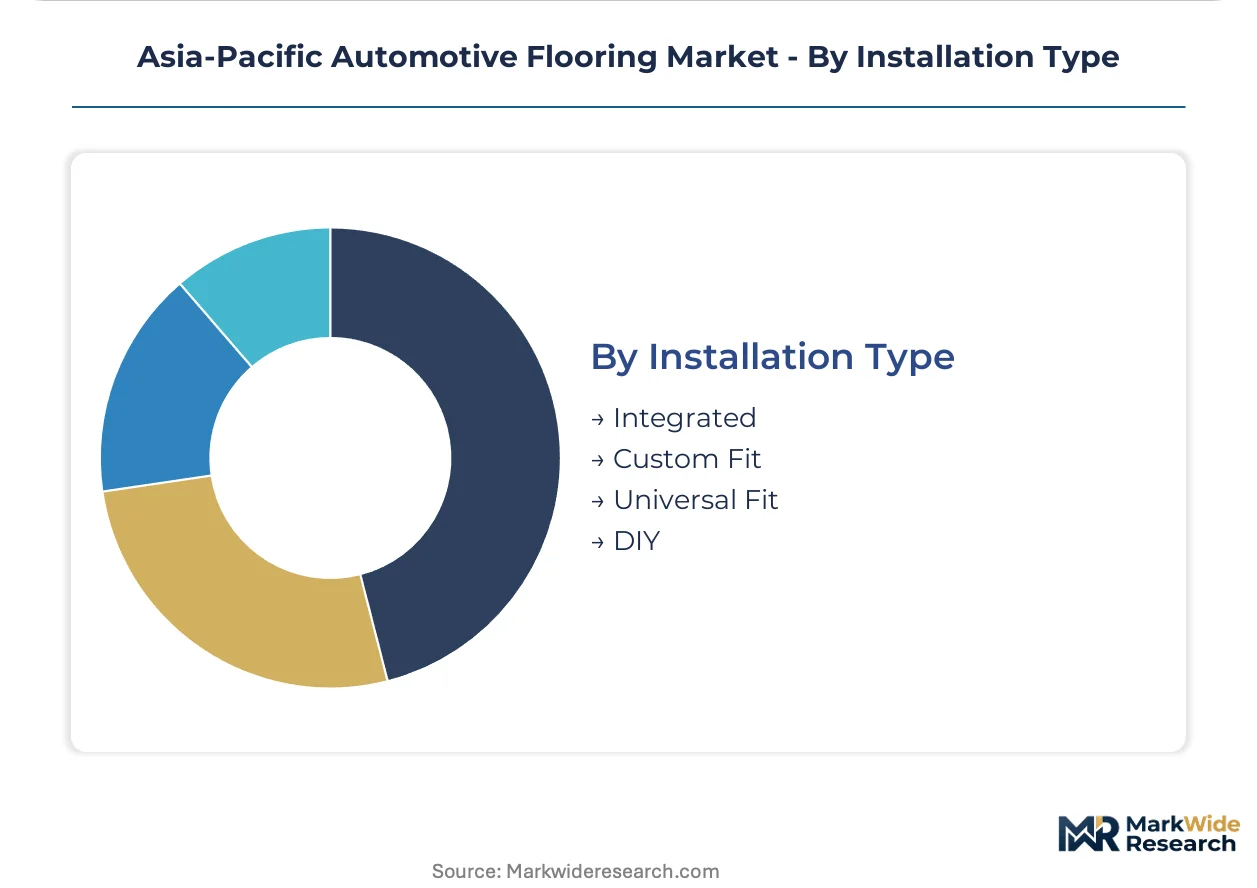
Installation Type:
Installation complexity determines supplier qualification tier and margin structure, with integrated systems demanding full module integration capabilities.
- Integrated:Factory-installed systems with bonded acoustic backing and thermal insulation layers require tier-one supplier certification against multi-standard protocols spanning China's GB emissions, Japan's JIS flame resistance, and emerging ASEAN harmonization drafts.
- Custom Fit:Vehicle-specific designs for replacement markets demand rapid pattern development and 72-hour production turnaround from regional manufacturers.
- Universal Fit:Trim-to-fit formulations serve price-sensitive aftermarket segments with standardized sizing across vehicle classes.
- DIY:Consumer-direct sales through e-commerce platforms grow with independent vehicle owner maintenance behavior in Indonesia and Philippines.
Integrated systems retain structural margin. Custom fit formats are gaining share in compressed fleet replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polypropylene resin supply concentrates in Zhejiang Province's three-facility cluster, creating vulnerability to environmental compliance shutdowns that ripple through downstream automotive textile production. This geographic chokepoint shapes procurement risk profiles for OEMs across the region.
China
Yangtze River Delta assembly plants operated by Toyota, BYD, and NIO anchor integrated flooring demand for EV platforms. MIIT dual carbon goals mandate recyclability quotas that accelerate thermoplastic olefin backing adoption. Shanghai and surrounding Jiangsu and Zhejiang provinces concentrate both polymer supply and finished carpet manufacturing capacity.
Japan
Domestic OEM specifications sustain demand for needle-punch and tufted constructions meeting premium acoustic standards. METI tightened JIS L 1091 flame resistance protocols now require self-extinguishing performance within three seconds. Aichi Prefecture's automotive corridor hosts tier-one supplier qualification facilities serving Toyota and Honda long-term platform contracts.
India
Tamil Nadu and Gujarat industrial corridors attract carpet system investments under the PLI scheme for advanced materials manufacturing. BIS and CDSCO frameworks converge toward mandatory ELV compliance for carpet constituents. Pune and Chennai assembly ecosystems generate pull for integrated acoustic-backed systems in both passenger and commercial vehicle segments.
Thailand
Grab and Gojek fleet operators compress replacement intervals to 60,000 kilometers, redirecting volume toward fast-turn regional compounders. Aftermarket channel expansion accelerates as vehicle age profiles exceed eight years. Bangkok metropolitan manufacturing zones supply both domestic fitment and cross-border export to Vietnam and Indonesia.
Indonesia
Independent service network expansion creates demand for replacement carpet and mat systems outside OEM capture. Java-based fabricators develop rapid pattern development capabilities for custom-fit replacement markets. Jakarta and Surabaya logistics hubs enable 72-hour production turnaround for compressed fleet maintenance schedules.
Asia-Pacific Automotive Flooring Market Competitive Landscape
Concentration sits with captive textile operations and tier-one interior module integrators that control supply chains from polymer feedstock through finished vehicle fitment. Japanese and South Korean automotive suppliers anchor the premium tier through long-term platform specifications, while Chinese fabricators compete on turnaround velocity for aftermarket channels. Three archetypes dominate: OEM-captive suppliers with backward integration into fiber production, independent tier-one specialists in acoustic-thermal integration, and regional compounders serving compressed fleet replacement cycles. Competitive moves center on qualification against multi-standard certification protocols and capacity positioning near Yangtze River Delta assembly clusters.
Among Japan-based textile specialists, Toyota Boshoku Corporation and Suminoe Textile Co., Ltd. exemplify the OEM-captive archetype with sustained supply relationships anchoring premium passenger vehicle programs. Hyundai Mobis Co. Limited represents the module integration approach, bundling flooring with broader interior systems. These three companies illustrate how geographic origin and corporate structure shape competitive positioning across certification-intensive integrated supply versus fast-turn aftermarket segments.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| Hyundai Mobis Co. Limited |
| Suminoe Textile Co., Ltd. |
| Hayashi Telempu |
| Shanghai Shenda |
| Autoneum Holding AG |
| Lear Corporation |
| Magna International Inc |
| Shandong Exceeding Auto Interior Parts Co., Ltd |
| Others |
Value Network & Pricing Analysis
Bio-based polyamide displacing petroleum-based nylon 6,6 simultaneously redraws raw material sourcing geography toward Indian and Thai agricultural processors while compressing caprolactam-linked pricing benchmarks across Yangtze River Delta supply contracts.
Pricing Analysis
China's MIIT recyclability mandates dictate the pricing tier structure across integrated flooring systems, separating premium EV platform contracts with traceable recycled-content documentation from entry-level polypropylene formulations. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with OEM integrated contracts commanding structural premiums over aftermarket channels. Cost compression in entry-level segments is intensifying because polypropylene feedstock volatility in Zhejiang Province transmits directly to compounder margins. Fleet operators at Grab and Gojek exhibit highest price sensitivity due to compressed 60,000-kilometer replacement cycles, while Mercedes-Benz and BMW China sourcing teams show lowest sensitivity for bio-based qualification programs.
Supply Chain Analysis
China, Japan, and South Korea anchor automotive textile manufacturing, with Zhejiang Province's three-facility polypropylene cluster feeding downstream carpet and mat production across the region. Nylon 6 chip, thermoplastic olefin resins, and acoustic foam substrates form critical input dependencies, with caprolactam pricing tethered to crude oil derivative movements. Single-source vulnerability concentrates in Zhejiang's environmental compliance exposure, where shutdowns ripple through 60% of regional resin supply. Distribution runs through tier-one module integrators for OEM channels and independent service networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in Asia-Pacific automotive flooring are inflecting around EV-dedicated architectures that unbundle acoustic-thermal modules from traditional interior systems, with battery pack insulation integration creating new interoperability standards.
For Market Incumbents: Consolidate backward integration into bio-based polyamide feedstocks to defend against agricultural processor encroachment from India and Thailand. Lock in multi-standard certification capacity against Japan's METI JIS L 1091 three-second flame resistance protocols before ASEAN harmonization extends qualification timelines. Prioritize Yangtze River Delta manufacturing positioning to capture Toyota, BYD, and NIO platform contract renewals.
For New Entrants and Emerging Players: Fleet direct service layers where incumbents under-serve Grab and Gojek compressed replacement cycles offer the most penetrable entry vector. Target Indonesia's independent service network expansion with 72-hour custom-fit turnaround capabilities. Pursue acoustic-thermal module bundling partnerships with dedicated EV architecture suppliers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional compounders in Thailand and Indonesia possessing rapid pattern development capabilities but lacking OEM qualification infrastructure. Long-term viability hinges on certification moat depth rather than volume scale alone. Monitor ASEAN automotive material standards harmonization drafts as the critical inflection signal for cross-border supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Captures margin from Indian and Thai castor oil agricultural processors displacing petroleum supply chains. |
| Multi-Standard Certification Investment | Accelerates qualification against China's GB emissions, Japan's JIS flame resistance, and ASEAN harmonization protocols. |
| Fleet Direct Service Channel Development | Addresses Grab and Gojek 60,000-kilometer replacement intervals outside traditional OEM capture. |
| Acoustic-Thermal Module Bundling | Aligns flooring substrates with battery pack insulation layers in dedicated EV architectures. |
| Regional Compounder Capacity Expansion | Positions fast-turn manufacturing in Indonesia and Thailand for compressed aftermarket replacement cycles. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-one supplier procurement leads, aftermarket distributor operations heads, and fleet maintenance directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, customs and trade flow records, and MIIT regulatory filings. Bottom-up segmentation modeling triangulated against top-down market sizing across material, product type, and end-user dimensions.
Sensitivity analysis tested volume and value outputs across the projection horizon against caprolactam price volatility scenarios and Zhejiang environmental compliance disruption events. Segmentation dimensions modeled encompass vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from historical trajectory analysis adjusted for platform transition timing in EV-dedicated architectures. Industry-specific forecast inputs incorporated MIIT dual carbon goal implementation pace and METI JIS protocol revision compliance costs.
Underlying assumptions cover OEM platform contract renewal rates, bio-based polyamide qualification timelines, and ASEAN harmonization draft finalization, with deviation risk concentrated in polypropylene supply concentration and fleet operator replacement cycle compression. Recalibration cycles align with material shifts in regulatory protocol adoption and raw material substitution economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Rear-View Mirror Market
Automotive Interior & Exterior
Europe Automotive Seat Market
Automotive Interior & Exterior
Decorative Car Accessories Market
Automotive Interior & Exterior
Commercial Vehicle Seats Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Paint Protection Film Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market