
 Heated Windshield Market | 2026-2036
Heated Windshield Market Size, Share, and Industry Trends Forecast 2026-2036
Heated Windshield Market Outlook
Factory-installed bundling of heated windshields with advanced driver-assistance sensor housings is pivoting buyer choice away from standalone aftermarket solutions. Fuyao Glass Industry Group leverages its integrated float-glass and coating operations to dominate OEM supply contracts in North America. Saint-Gobain Sekurit anchors European premium vehicle programs through specialized conductive silver-frit printing capabilities. AGC Inc. competes in Asian markets with laminated glass configurations optimized for head-up display projection and simultaneous heating functions.
Heated windshields incorporate electrically conductive materials, typically tungsten or silver-based micro-wire grids or transparent conductive oxide coatings laminated between glass layers, generating resistive heat to eliminate ice and fog within minutes of activation. Front windshield applications lead volume due to regulatory visibility requirements and integration with camera and radar mounting zones, while infrared heating technology represents the fastest-expanding segment as it reduces energy consumption compared to traditional wire-based systems. Factory-installed configurations command the dominant margin pool because OEMs specify thermal performance thresholds and optical clarity standards that aftermarket providers struggle to replicate at equivalent cost structures.
NHTSA visibility standards in the United States, ECE R43 regulations in Europe, and JIS safety benchmarks in Japan collectively mandate minimum light transmission and defrosting performance that shape product design and testing protocols. The EU F-Gas Regulation and evolving EPA vehicle efficiency guidelines are forcing manufacturers to abandon fluid-based heating in favor of all-electric architectures that eliminate refrigerant-dependent defrost cycles. Stakeholders must monitor how cybersecurity standards for connected vehicles will extend to heated windshield control modules as automotive electronics integration deepens.
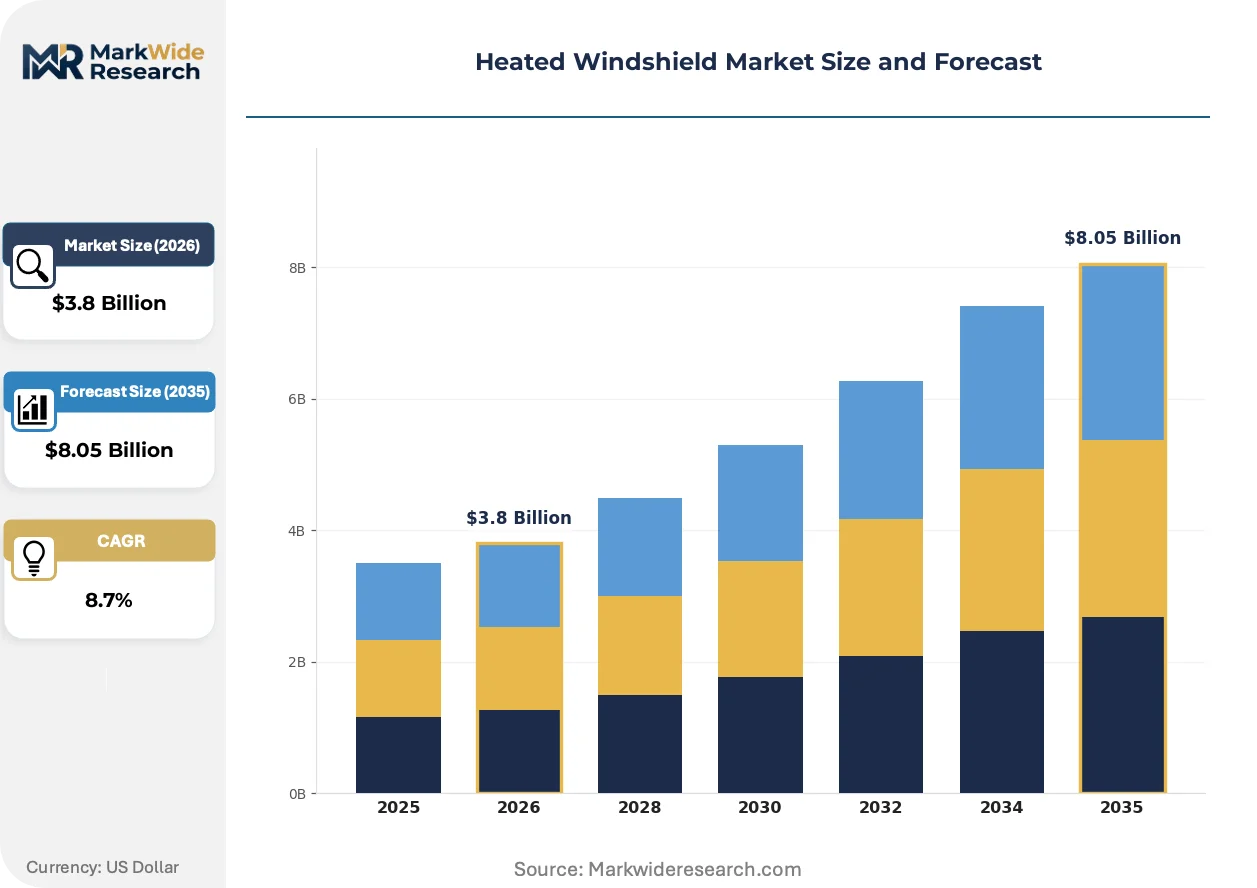
Market Dynamics
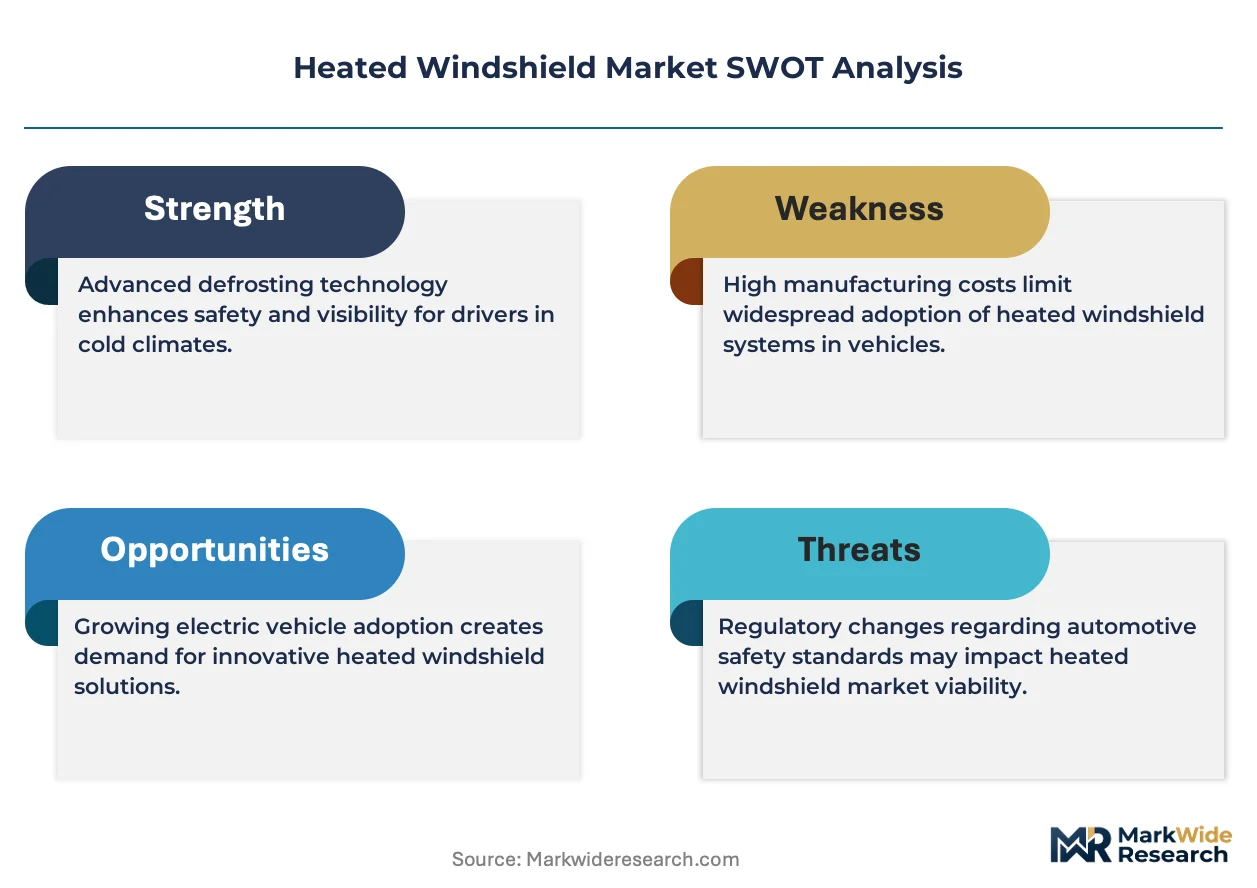
Automotive OEMs are bundling heated windshields with ADAS sensor housings as standard equipment, collapsing the aftermarket channel and concentrating margin capture at the factory level. This structural shift toward integrated thermal-optical systems is reshaping supplier relationships and procurement patterns across cold-climate vehicle programs.
Growth Catalysts
- ECE R43 visibility mandates:European regulations requiring rapid defrosting performance are compelling OEMs to specify electrically heated architectures in all-season vehicle configurations.
- Silver-frit conductive printing:Advanced coating technologies enable simultaneous heating and head-up display projection, expanding functional integration in premium glass programs.
- Japan winter safety protocols:JIS standards for optical clarity under icing conditions are accelerating factory-installed heated windshield penetration in domestic vehicle production.
Market Restraints
- Tungsten wire supply concentration:Limited qualified suppliers of ultra-fine conductive filaments create input vulnerability for traditional heated glass architectures.
- EU F-Gas Regulation phase-out:Restrictions on refrigerant-dependent defrost systems force costly R&D pivots for manufacturers with legacy fluid-based heating portfolios.
- Optical distortion thresholds:NHTSA light transmission requirements constrain the density of conductive elements that can be embedded without compromising driver visibility.
Strategic Opportunities
- India cold-chain commercial vehicles:Underpenetrated fleet segments in northern states present first-mover potential for heated windshield specification in refrigerated transport.
- IR heating convergence:Integration of infrared emitter arrays with laminated glass substrates offers energy efficiency gains over resistive wire systems.
- US Inflation Reduction Act clean vehicle credits:Efficiency-weighted incentives favor electrically heated architectures that reduce auxiliary power draw in EV platforms.
Industry Challenges
- ADAS calibration technician shortage:Heated windshield replacement now requires recalibration of integrated camera and radar mounts, straining service network capacity.
- Multi-layer lamination capex:Conductive oxide coating equipment demands substantial capital investment, creating barriers for mid-scale glass processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heated Windshield Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Windshield, Rear Windshield, Side Windows, Panoramic Roof Technology: Electric Heating, Hydrogel Technology, Infrared Heating, Thermoelectric End User: Automotive OEMs, Aftermarket Providers, Fleet Operators, Heavy Equipment Manufacturers Installation Type: Factory-installed, Aftermarket Installation, Retrofit Solutions, Integrated Systems |
| Companies Covered | Fuyao Glass Industry Group, Xinyi Glass Holdings, AGC Inc., Safelite AutoGlass, PGW Auto Glass, Saint-Gobain Sekurit, Guardian Industries, Rehau, Nippon Sheet Glass Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heated Windshield Market Strategic Shifts
Infrared emitter technology is compressing energy requirements while expanding design flexibility for curved and panoramic windshield formats. These thermal innovations are converging with sensor integration demands to redefine glass system architecture.
Transparent conductive oxide coatings doped with indium tin oxide or aluminum zinc oxide generate uniform heat distribution across complex curvature geometries. European premium OEMs are adopting these films for panoramic roof and windshield combinations. This architecture is overtaking wire-grid systems in applications where optical clarity for camera-based ADAS functions is non-negotiable.
EPA vehicle efficiency guidelines are tightening auxiliary power consumption limits for cabin thermal management. Manufacturers must demonstrate watt-per-defrost-cycle performance that favors solid-state heating over fluid-based alternatives. The regulatory pressure is most acute in US EV programs where range preservation drives specification decisions.
Fleet operators are consolidating glass procurement through national service networks that bundle heated windshield replacement with ADAS recalibration. This channel compression is displacing independent aftermarket distributors in commercial vehicle segments. The pattern is most pronounced in Germany and the United States where large fleet lessors negotiate direct supplier contracts.
Heated Windshield Market Segmentation
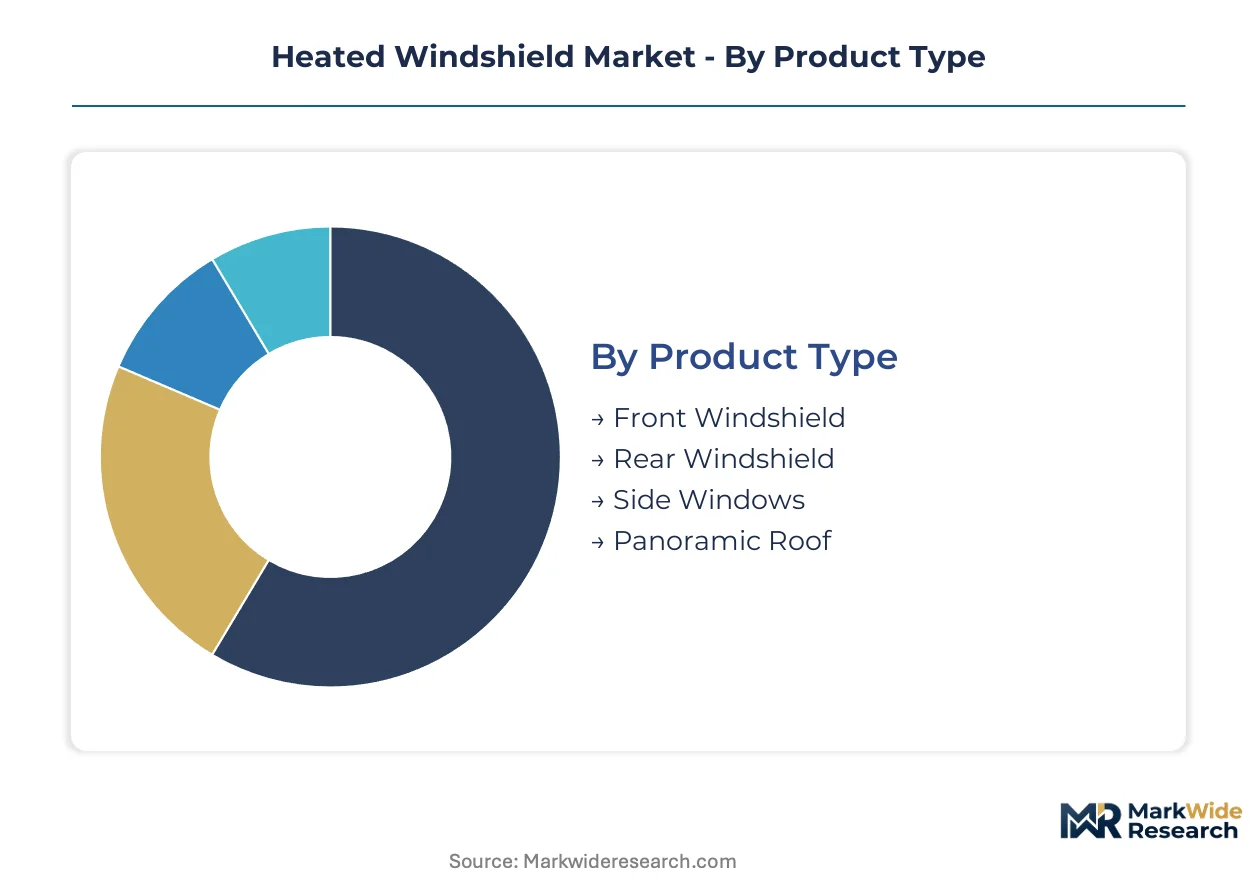
Segmentation in the heated windshield market reveals how thermal-optical systems align with distinct vehicle architectures and procurement channels. Each dimension—product placement, heating mechanism, buyer type, and installation timing—carries different margin profiles and technical specifications that shape supplier strategy.
Product Type:
Customization intensity varies sharply across vehicle glazing positions, with front applications demanding the tightest optical tolerances and panoramic formats permitting greater design flexibility.
- Front Windshield:Incorporates tungsten micro-wire grids or transparent conductive oxide coatings between laminated glass layers to meet NHTSA visibility standards. Demand concentrates in Germany and the United States where winter safety regulations mandate rapid defrosting performance for driver visibility zones.
- Rear Windshield:Uses printed silver-frit conductive circuits on tempered glass with less stringent optical clarity requirements than front applications. Fleet operators in Japan specify heated rear glass for commercial van configurations where cargo access timing drives operational efficiency.
- Side Windows:Electrically heated laminated configurations prevent mirror icing and improve peripheral visibility. Premium OEM programs integrate these with frameless door designs.
- Panoramic Roof:Infrared heating films address complex curvature geometries where wire grids create optical distortion. European luxury vehicle lines favor this architecture for cabin thermal comfort.
Leading the category by volume: Front Windshield. Growing fastest: Panoramic Roof.
Technology:
Energy efficiency thresholds separate mature resistive systems from emerging solid-state alternatives, with regulatory pressure on auxiliary power draw reshaping R&D allocation.
- Electric Heating:Resistive wire grids and conductive coatings generate heat through ohmic losses, dominating current OEM specifications due to proven durability and repairability. EPA vehicle efficiency guidelines are forcing watt-per-cycle reductions that favor optimized conductive oxide films over legacy tungsten architectures.
- Infrared Heating:Solid-state emitter arrays bonded to glass substrates deliver targeted thermal radiation with lower energy consumption than resistive alternatives. The EU Green Deal efficiency mandates are accelerating adoption in EV platforms where range preservation priorities override cost premiums.
- Hydrogel Technology:Phase-change materials embedded in interlayers provide passive thermal management. Limited commercial deployment in specialty applications.
- Thermoelectric:Peltier-effect modules enable active heating and cooling but face cost barriers for widespread automotive adoption. Experimental integration in concept vehicles.
Dominant by installation base: Electric Heating. Expanding most quickly: Infrared Heating.
End User:
Procurement concentration differs across buyer types, with automotive OEMs capturing margin through bundled ADAS integration while fleet operators prioritize total cost of ownership over upfront specification.
- Automotive OEMs:Specify thermal performance thresholds, optical clarity standards, and sensor integration requirements that factory-installed configurations must satisfy. Cold-climate vehicle programs in the United States and Germany now bundle heated windshields as standard equipment rather than premium options.
- Fleet Operators:Negotiate national service contracts bundling glass replacement with ADAS recalibration to minimize vehicle downtime. Large lessors in Germany and the United States are consolidating procurement through direct supplier relationships.
- Aftermarket Providers:Face margin compression as OEM bundling collapses the replacement channel for newer vehicle generations. Independent distributors retain relevance in older vehicle parc.
- Heavy Equipment Manufacturers:Specify heated glass for construction and agricultural machinery operating in extreme cold. Lower volume but higher per-unit specification tolerance.
Highest volume concentration: Automotive OEMs. Steepest share gains: Fleet Operators.
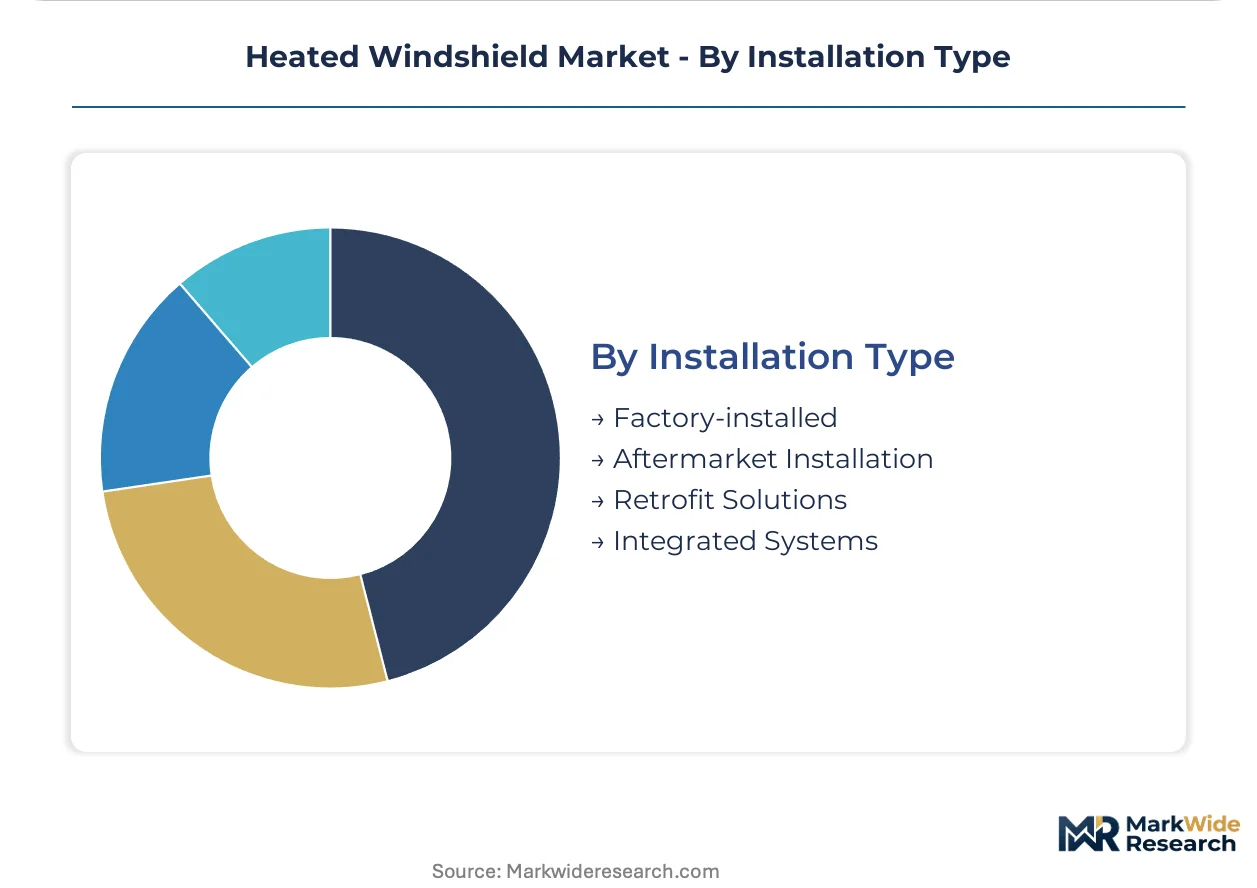
Installation Type:
Timing of thermal system integration determines margin capture, with factory installation locking in multi-year supply contracts and aftermarket channels facing technical complexity barriers.
- Factory-installed:OEMs specify conductive element density, lamination protocols, and sensor mounting integration during vehicle design phase. This channel commands the dominant margin pool because thermal-optical performance validation occurs before production ramp.
- Integrated Systems:Combines heated glass with ADAS sensor housings, antenna integration, and head-up display projection in single module architectures. Premium vehicle programs favor this approach for warranty consolidation.
- Aftermarket Installation:Requires ADAS recalibration capabilities that strain independent service network capacity. Technician shortage constrains growth.
- Retrofit Solutions:Add-on heating films and external defrost systems address legacy vehicle populations. Limited to commercial applications where downtime costs justify modification expense.
Capturing majority value: Factory-installed. Gaining specification fastest: Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of heated windshields concentrates in industrial glass manufacturing corridors while consumption patterns track cold-climate vehicle registrations and fleet density. Germany, Japan, and the United States anchor both supply capacity and end-use specification.
Germany
OEM bundling of heated windshields with ADAS sensor housings drives factory-installed penetration in premium vehicle programs. ECE R43 visibility mandates compel rapid defrosting performance standards across all-season configurations. The Stuttgart-Munich corridor hosts specialized conductive silver-frit printing operations serving European luxury brands.
United States
Fleet operators consolidate procurement through national service networks bundling glass replacement with ADAS recalibration. NHTSA light transmission requirements constrain conductive element density in windshield designs. Michigan and Ohio anchor automotive glass fabrication clusters supplying Detroit-based OEMs.
Japan
JIS safety benchmarks for optical clarity under icing conditions accelerate heated windshield specification in domestic production. METI efficiency guidelines favor electrically heated architectures over fluid-based alternatives. The Aichi Prefecture cluster integrates laminated glass configurations with head-up display projection capabilities.
China
Integrated float-glass and coating operations capture OEM supply contracts for North American and European vehicle programs. MIIT vehicle efficiency standards align with export market requirements for low-energy thermal management. The Fujian-Guangdong corridor dominates conductive oxide coating capacity for panoramic roof applications.
India
Underpenetrated cold-chain commercial vehicle fleets in northern states present specification opportunities for refrigerated transport operators. BIS automotive safety standards are evolving to address visibility performance in extreme weather conditions. The Haryana-Rajasthan logistics corridor drives initial fleet trials of heated windshield configurations.
Heated Windshield Market Competitive Environment
The competitive structure tilts toward integrated glass-coating conglomerates with captive float-glass supply. Tiered specialization separates premium conductive-printing specialists from scale-driven laminated glass fabricators. Two dominant competitive moves are reshaping positioning: backward integration into conductive oxide coating equipment and strategic partnerships with ADAS sensor module suppliers.
Within the integrated conglomerate tier, Fuyao Glass Industry Group and Saint-Gobain Sekurit exemplify divergent geographic anchoring strategies. AGC Inc. occupies a position bridging Asian market specialization with premium optical integration. Specialists in aftermarket service networks, including Safelite AutoGlass, represent the channel-compression response to OEM bundling trends. Xinyi Glass Holdings and Nippon Sheet Glass Co., Ltd. sit within the scale-fabrication archetype serving volume vehicle programs.
| Leading Market Players |
|---|
| Fuyao Glass Industry Group |
| Xinyi Glass Holdings |
| AGC Inc. |
| Safelite AutoGlass |
| PGW Auto Glass |
| Saint-Gobain Sekurit |
| Guardian Industries |
| Rehau |
| Nippon Sheet Glass Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Silver price indices cascade through conductive coating costs, compressing margins for tungsten wire alternatives while amplifying pricing power for integrated oxide-film suppliers serving OEM thermal-optical specifications.
Pricing Analysis
Cost-down pressure on aftermarket channels accelerates because factory-installed bundling with ADAS modules eliminates standalone replacement demand. Three-tier pricing structure across premium conductive-oxide, standard silver-frit, and economy wire-grid configurations separates optical-grade certification tiers. Price differentiation hinges on NHTSA light-transmission compliance and ECE R43 defrost-cycle validation. Fleet operators exhibit highest price sensitivity due to national contract consolidation, while premium OEMs prioritize thermal uniformity over per-unit cost.
Supply Chain Analysis
Automotive glass qualification protocols gate supplier entry through NHTSA, ECE R43, and JIS optical-clarity certifications that demand multi-year validation cycles. Manufacturing concentrates in Germany, China, and Japan where float-glass corridors feed conductive coating operations. Supply chains draw from indium, tin oxide, and ultra-fine tungsten filament inputs. Single-source vulnerability concentrates in qualified silver-frit printing equipment. Distribution runs through OEM direct contracts and national fleet service networks bypassing traditional aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance arena where ECE R43 visibility mandates erect regulatory moats favoring incumbent conductive-coating specialists with validated thermal-optical platforms.
For Market Incumbents: Deploy backward integration into indium-tin-oxide coating equipment to secure input cost control against silver price volatility. Consolidate ADAS recalibration service partnerships to defend factory-installed channel share from independent aftermarket encroachment. Threat substitution from infrared emitter arrays demands accelerated R&D allocation to solid-state thermal architectures. For New Entrants and Emerging Players: Begin with India refrigerated transport fleet trials in Haryana-Rajasthan logistics corridors where BIS standards remain permissive and first-mover specification windows persist. Target hydrogel phase-change technology for specialty agricultural equipment segments bypassing wire-grid incumbent dominance. Go-to-market angle centers on energy-efficiency certification for EU Green Deal-aligned export vehicle programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale laminated glass fabricators with latent conductive-coating capacity in China's Fujian-Guangdong corridor. Long-term viability over the coming decade rests on EV platform thermal-efficiency specification trajectories. Signal to watch: EPA auxiliary power consumption threshold tightening for solid-state heating preference over resistive alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Oxide Coating | Captive indium-tin-oxide film production insulates margin from precious metal price swings. |
| ADAS Sensor Housing Integration | Combined thermal-optical modules command OEM specification through warranty consolidation. |
| Infrared Emitter Technology Licensing | Solid-state heating IP addresses EU Green Deal efficiency mandates for EV range preservation. |
| India Cold-Chain Fleet Partnership | Refrigerated transport trials in northern states establish specification precedent for BIS evolution. |
| National Service Network Consolidation | Fleet operator direct contracts displace independent aftermarket distributors in Germany and United States. |
Study Parameters
Document review covered SEC automotive supplier filings, ECE R43 technical bulletins, and JIS safety standard amendments, complemented by interviews with OEM platform engineers, Tier 1 glass procurement leads, and aftermarket distributor operations heads. Secondary validation drew from vehicle production databases, customs trade records for conductive oxide materials, and EPA vehicle efficiency guideline drafts. Bottom-up segment sizing triangulated against top-down OEM thermal-system specification rates.
Output projections span volume units and value aggregates across the analysis window, with segmentation modeling across front-rear-side-panoramic product types, electric-infrared-hydrogel-thermoelectric technology tiers, and factory-installed-integrated-aftermarket-retrofit installation channels. CAGRs derived from regression against cold-climate vehicle registration trajectories and regulatory mandate phase-in schedules. Key inputs included OEM ADAS bundling adoption curves and fleet operator procurement consolidation patterns.
Underlying measurement precision varies by segment; factory-installed and integrated system categories carry tighter precision than fragmented aftermarket channels due to OEM disclosure transparency. Forecasts rest on assumptions regarding ECE R43 enforcement timelines and EPA auxiliary power threshold evolution. A model refresh is warranted upon material change in EU F-Gas Regulation phase-out acceleration or NHTSA optical-distortion threshold revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Intelligent Lighting System Market
Automotive Interior & Exterior
Latin America Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Europe Automotive Interiors Market
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Morocco Automotive Industry Market
Automotive Interior & Exterior
Automotive Flooring Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Fog Free Mirrors Market