
 Automotive Convertible Top Market | 2026-2036
Automotive Convertible Top Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Convertible Top Market Analysis
Specialized tooling expertise for complex folding kinematics is unwinding capacity constraints among European suppliers. Webasto Group leverages decades of soft-top and retractable-hardtop engineering to sustain technology leadership across German and Italian OEM programs. Magna International anchors North American convertible production through integrated module assembly at its Ontario facilities. Valmet Automotive competes via specialized contract manufacturing for low-volume premium roadster platforms.
An automotive convertible top is a retractable roof system, typically comprising multi-layer fabric laminates or articulated polymer panels with electro-hydraulic actuation mechanisms, designed to transform enclosed passenger compartments into open-air configurations while preserving structural integrity and weather sealing. Power-operated systems dominate volume production due to consumer convenience expectations, though hybrid manual-electric mechanisms retain share in weight-sensitive roadster applications where mass reduction directly impacts vehicle dynamics. Fabric materials, particularly advanced canvas-polyester composites with butyl rubber cores, command the largest material segment by installed base; leather treatments concentrate in ultra-luxury roadster variants where tactile quality justifies substantial cost premiums. UV resistance functionality has matured as a baseline expectation, while noise reduction specifications now differentiate premium-tier systems through multi-layer acoustic barriers and improved sealing architectures.
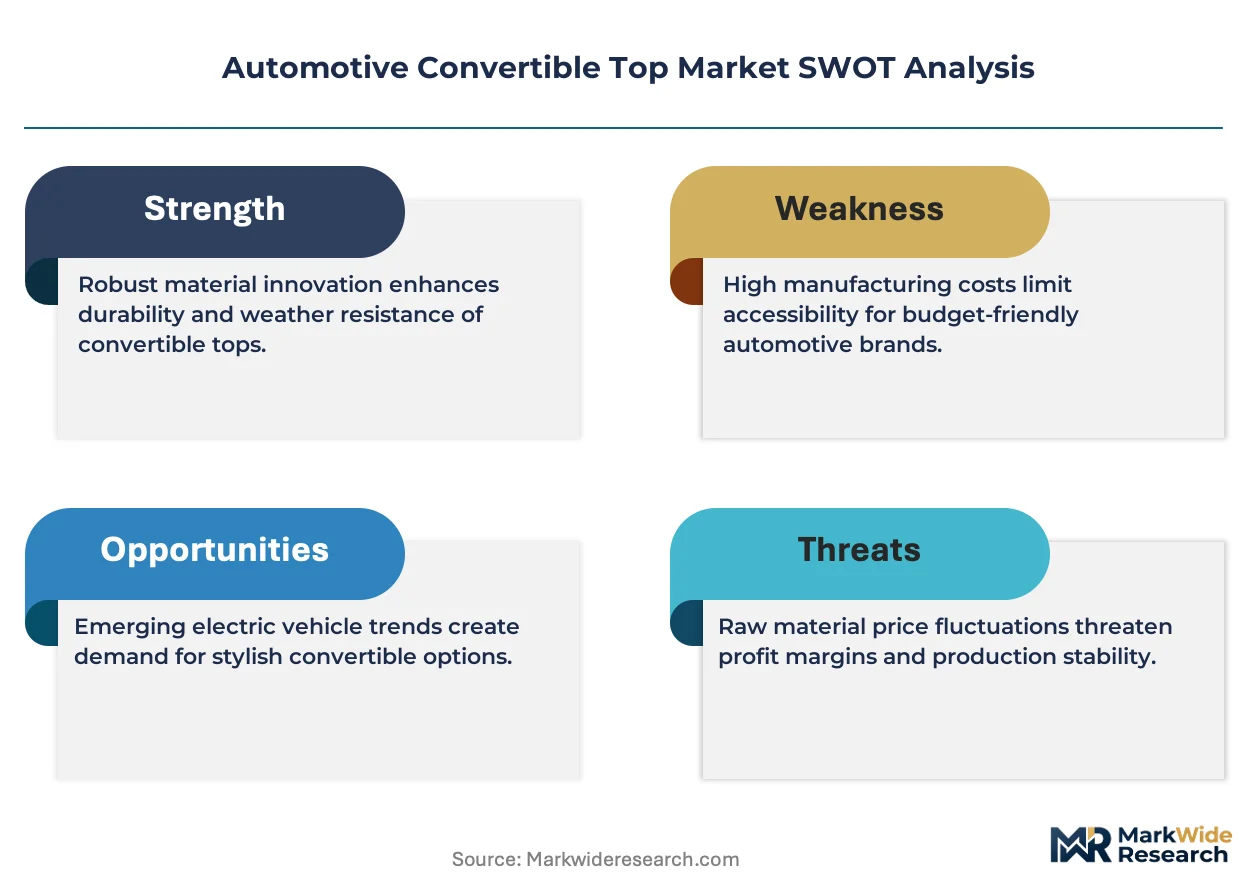
NHTSA's Federal Motor Vehicle Safety Standard 216a governs roof crush resistance for convertibles sold in the United States, compelling reinforcement strategies that add mass and cost to open-top architectures. ECE R43 and ECE R46 standards in Europe regulate transparent and reflective materials used in rear-window assemblies integrated into folding tops, shaping supplier qualification requirements. EPA fuel economy testing methodologies penalize convertible variants for aerodynamic efficiency losses, influencing OEM decisions on powertrain pairing and top-system weight targets. Stakeholders must monitor evolving pedestrian protection standards and their implications for front-hinged hood and windshield-frame designs that interact with top stowage mechanisms.
Market Dynamics
Electro-hydraulic actuation hardware is miniaturizing while preserving load-bearing capacity, compressing packaging volume in rear-deck stowage compartments and enabling convertible configurations on compact vehicle architectures previously constrained by dimensional limits.
Growth Catalysts
- Soft-top material advances:Multi-layer canvas-polyester composites with butyl rubber cores achieve acoustic isolation targets without weight penalties. Roadster manufacturers in Germany adopt these laminates for NVH-critical applications.
- ECE R43 compliance frameworks:European safety standards for transparent rear-window materials drive qualification investments by glazing suppliers. Certification against ECE R43 opens access to German, Italian, and British OEM supply chains.
- Stuttgart-Munich manufacturing clusters:Geographic concentration of premium vehicle assembly creates localized demand pull for convertible top module integration. Suppliers co-locate technical centers to support just-in-sequence delivery.
Market Restraints
- Aluminum-intensive reinforcement structures:NHTSA's Federal Motor Vehicle Safety Standard 216a mandates roof crush resistance that adds mass to open-top architectures. Compliance hardware consumes 15-25% of convertible-specific bill-of-materials cost.
- Butyl rubber supply volatility:Core layer material for acoustic laminates faces petrochemical feedstock price swings. European compounders pass through ethylene-propylene cost fluctuations with limited hedging instruments.
- Retractable hardtop kinematic complexity:Articulated polymer panel systems require precision-machined hinge mechanisms with tight tolerance stacks. Manufacturing yield losses concentrate in low-volume Italian roadster programs.
Strategic Opportunities
- Electric roadster platform expansion:Battery-electric architectures eliminate exhaust routing constraints that complicated soft-top packaging in internal-combustion vehicles. German OEMs are reconfiguring rear-deck volumes for top stowage around flat battery packs.
- India BIS certification pathway:India's Bureau of Indian Standards is developing automotive component safety frameworks. Early qualification against emerging BIS standards positions suppliers for premium vehicle local assembly.
- Sensor-integrated top modules:Convergence of electro-hydraulic actuation with antenna and lidar housing creates multifunctional roof systems. Luxury SUV convertibles in Italy integrate ADAS hardware into folding hardtop panels.
Industry Challenges
- Sealing system validation cycles:Weather-tightness testing across temperature and humidity extremes extends development timelines. Each design iteration requires 12-16 weeks of accelerated aging protocols.
- Folding kinematics simulation expertise:Multi-body dynamics modeling for complex four-bar linkage systems depends on scarce CAE specialists. German engineering services firms command premium rates for convertible-specific simulation support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Convertible Top Market |
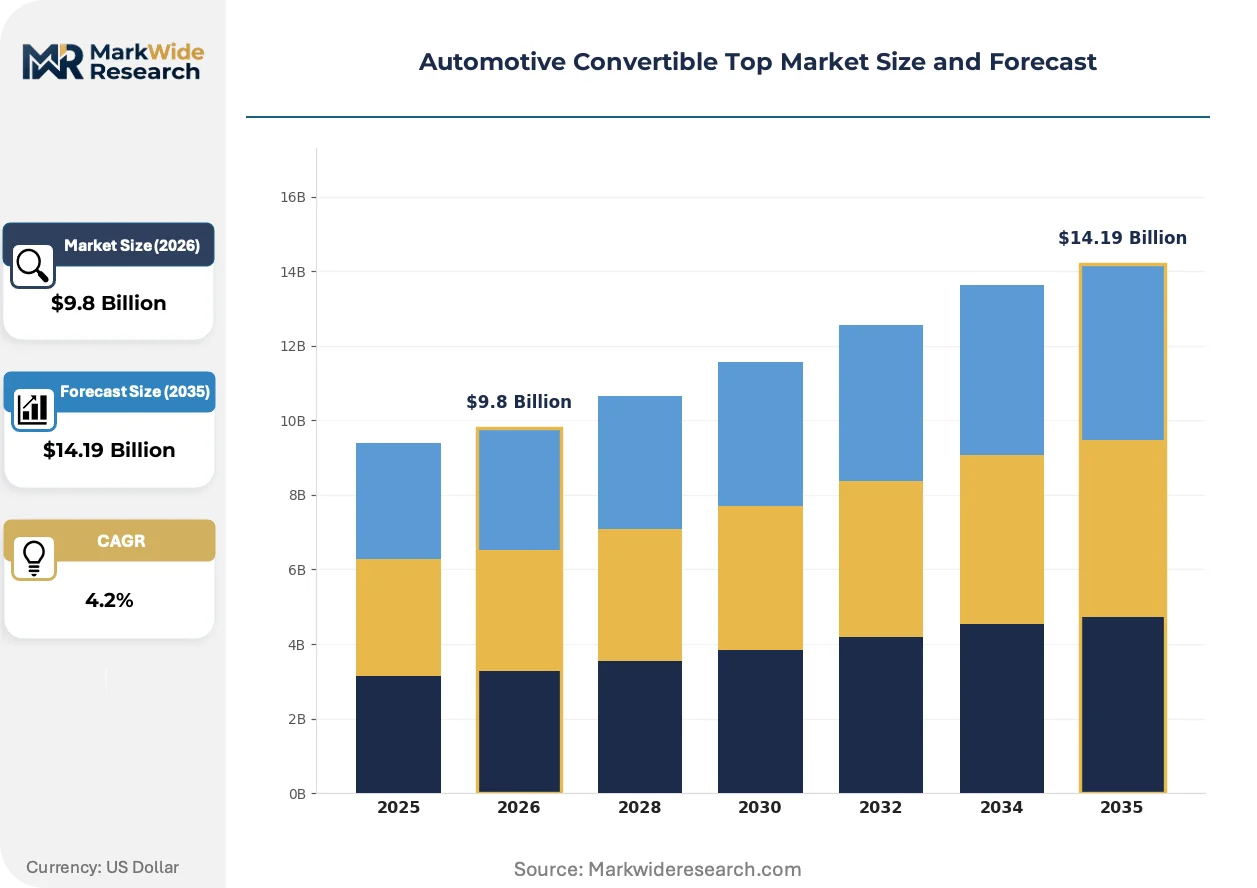
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $14.19 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Power, Hybrid, Fabric Vehicle Type: Coupes, Roadsters, SUVs, Luxury Cars Material: Cotton, Vinyl, Canvas, Leather Functionality: Weather Protection, Aesthetic Appeal, UV Resistance, Noise Reduction |
| Companies Covered | Inalfa Roof Systems, Valmet Automotive, Webasto Group, Grupo Antolin, The Haartz Corporation, Magna International, Aisin Seiki, Edscha, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Convertible Top Market Emerging Trajectories
Material science breakthroughs and regulatory harmonization pressures are compressing development cycles while expanding the addressable vehicle segments for open-top architectures. Three forces dominate current investment patterns.
Electro-hydraulic pump and cylinder assemblies are miniaturizing through high-pressure fluid circuit redesigns and compact motor integration. Tier 1 suppliers serving German OEM roadster programs have reduced actuator packaging volume by 30% since 2020. This dimensional compression enables convertible top fitment on subcompact electric vehicles where rear-deck space competes with battery thermal management hardware.
EPA fuel economy testing methodologies penalize convertible variants for aerodynamic efficiency losses versus fixed-roof counterparts. NHTSA's roof crush standards compound mass penalties that reduce electric vehicle range ratings. OEM engineering teams in the United States are responding with active aerodynamic elements—deployable rear spoilers integrated into top modules—that trigger during open-top operation to mitigate drag coefficient degradation.
Direct sourcing relationships between OEM convertible program offices and specialized textile laminators are displacing traditional tiered supply arrangements. Italian ultra-luxury roadster manufacturers now contract directly with Como-based fabric finishers for bespoke leather treatments. This channel compression eliminates margin stacking but requires OEMs to assume raw material inventory risk previously borne by system integrators.
Automotive Convertible Top Market Segmentation
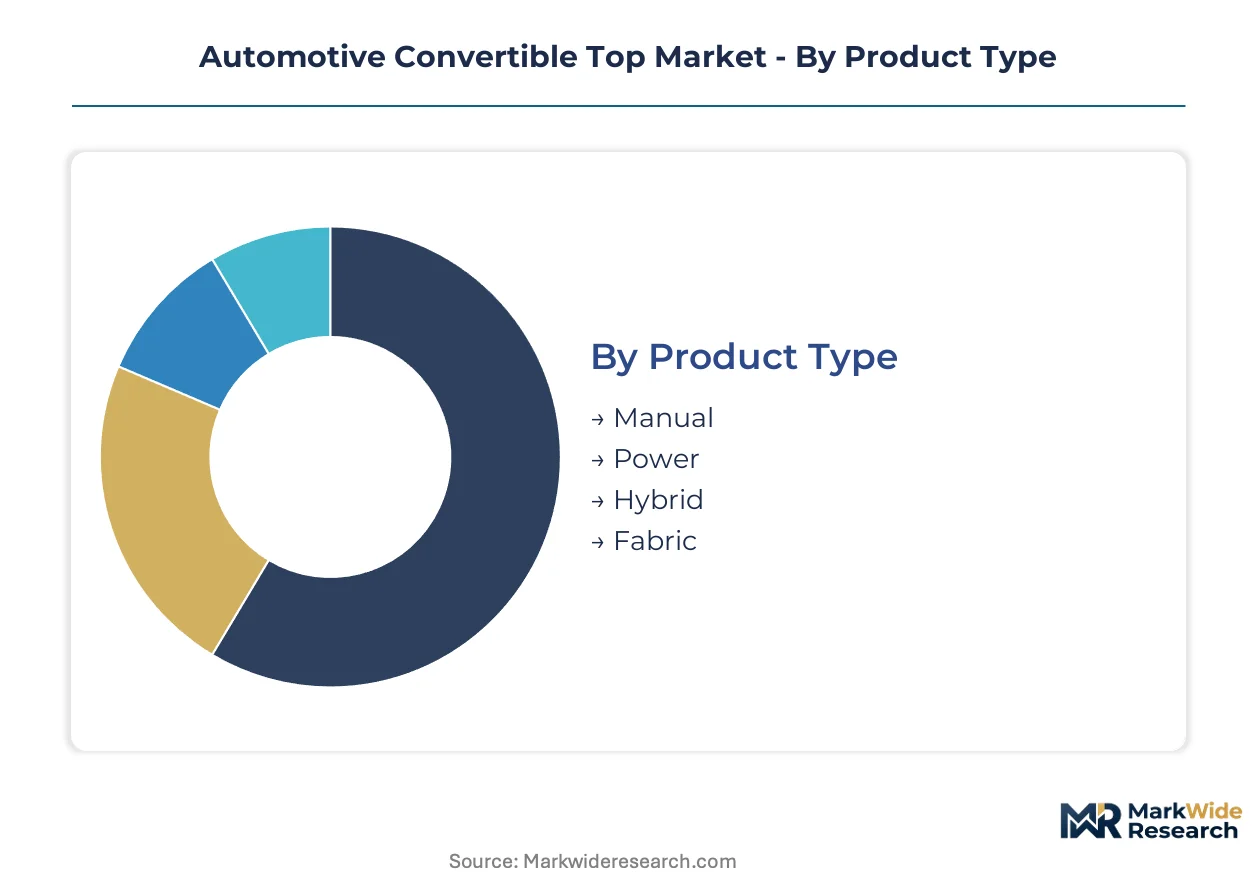
Convertible top procurement decisions split across actuation technology, vehicle architecture, material specification, and functional performance tiers. Each segmentation axis carries distinct regulatory compliance burdens and cost structures that reshape supplier qualification pathways.
Product Type:
NHTSA's Federal Motor Vehicle Safety Standard 216a and ECE R43 impose divergent testing protocols across actuation categories, fragmenting supplier certification investments by mechanism type.
- Power:Electro-hydraulic pump and cylinder assemblies integrate compact motor designs with high-pressure fluid circuits. German OEM roadster programs concentrate demand here as rear-deck packaging constraints tighten around battery thermal management hardware. NVH specifications and sealing validation cycles extend development timelines.
- Hybrid:Manual-electric mechanisms combine weight-sensitive roadster requirements with consumer convenience expectations. Italian ultra-luxury manufacturers specify these for mass-critical applications where kilogram reduction directly impacts vehicle dynamics and range ratings.
- Manual:Pure mechanical systems retain niche positioning in heritage-inspired roadster variants and cost-optimized entry configurations.
- Fabric:Fixed soft-top architectures without folding kinematics serve aftermarket replacement and restoration segments.
Established volume favors Power; emerging adoption favors Hybrid.
Vehicle Type:
Platform architecture dictates top-system packaging volume, kinematic complexity, and integration with structural reinforcement strategies.
- Coupes:Fixed-roof convertible configurations—retractable hardtops—demand precision-machined hinge mechanisms with tight tolerance stacks. Stuttgart-based engineering centers dominate development support for these programs.
- Roadsters:Purpose-built open-top architectures optimize rear-deck stowage compartments around folding kinematics. Battery-electric roadster platforms from German OEMs are reconfiguring top stowage around flat battery packs, eliminating exhaust routing constraints.
- SUVs:High-center-of-gravity vehicles require reinforced rollover protection integrated into top modules, adding mass and cost.
- Luxury Cars:Ultra-premium specifications drive direct sourcing relationships with Como-based fabric finishers for bespoke material treatments.
Coupe configurations anchor current revenue; roadster platforms are climbing the fastest on electric architecture transitions.
Material:
Raw material selection determines acoustic performance, UV degradation resistance, and tactile quality premiums across price tiers.
- Canvas:Advanced canvas-polyester composites with butyl rubber cores achieve acoustic isolation targets without weight penalties. German roadster manufacturers specify these laminates for NVH-critical applications where multi-layer barriers replace mass-intensive alternatives.
- Leather:Tactile quality justifies substantial cost premiums in Italian ultra-luxury variants. Direct OEM relationships with specialized finishers displace traditional tiered supply arrangements.
- Vinyl:Cost-optimized synthetic surfaces serve volume convertible segments and replacement markets.
- Cotton:Heritage-inspired natural fiber treatments retain niche positioning in classic roadster restorations.
Canvas dominates installed base; leather gains share fastest on ultra-premium SUV convertible expansion.
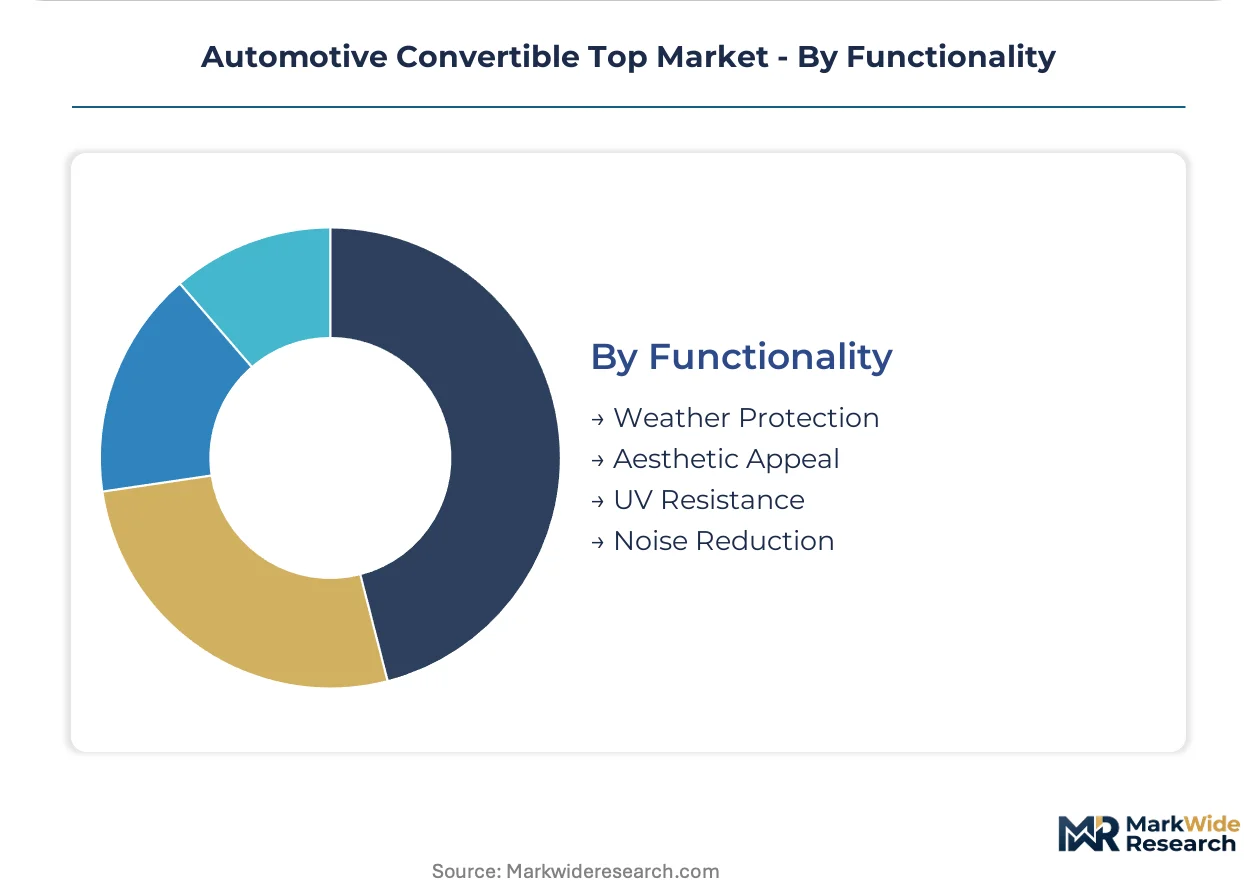
Functionality:
Performance specifications differentiate tiered offerings, with baseline expectations rising across all vehicle categories.
- Weather Protection:Multi-layer sealing architectures and accelerated aging protocols—12-16 weeks per design iteration—define qualification thresholds. ECE R43 compliance for transparent rear-window materials shapes glazing supplier investments.
- Noise Reduction:Multi-layer acoustic barriers and improved sealing architectures now differentiate premium-tier systems from standard offerings.
- UV Resistance:Baseline functionality across all material categories, with additive packages preventing degradation in high-solar-load geographies.
- Aesthetic Appeal:Surface finish quality and color matching drive direct sourcing decisions for luxury roadster programs.
Weather protection anchors procurement specifications; noise reduction represents the steepest expansion trajectory on premium-tier differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECE R43 compliance requirements for transparent rear-window materials anchor European convertible top procurement, with German premium OEMs driving specification intensity across Stuttgart and Munich manufacturing clusters.
Germany
Stuttgart-based OEMs specify multi-layer canvas-polyester composites with butyl rubber cores for NVH-critical roadster applications. KBA vehicle type approval processes govern convertible top system homologation for domestic and export markets. Munich engineering centers concentrate electro-hydraulic actuation development for battery-electric roadster platforms reconfiguring rear-deck stowage around flat battery packs.
United States
NHTSA's Federal Motor Vehicle Safety Standard 216a mandates roof crush resistance that adds mass to open-top architectures sold domestically. EPA fuel economy testing methodologies penalize convertible variants for aerodynamic efficiency losses, influencing powertrain pairing decisions. Michigan-based OEM engineering offices coordinate with Ontario module assembly facilities to manage cross-border supply integration.
Italy
Ultra-luxury roadster manufacturers in Northern Italy contract directly with Como-based fabric finishers for bespoke leather treatments, displacing traditional tiered supply arrangements. ECE R43 certification opens access to broader European OEM supply chains. Turin and Modena engineering clusters specialize in precision-machined hinge mechanisms for retractable hardtop kinematics with tight tolerance stacks.
Japan
METI industrial policy supports lightweight material development for convertible applications in domestic roadster programs. JIS standards govern textile laminate quality specifications for OEM supply qualification. Nagoya-area manufacturing clusters produce hybrid manual-electric mechanisms for mass-sensitive applications where kilogram reduction directly impacts vehicle dynamics.
India
BIS is developing automotive component safety frameworks for convertible top systems as premium vehicle local assembly expands. Early qualification against emerging BIS standards positions suppliers for German and Italian OEM sourcing from Indian operations. Maharashtra and Gujarat manufacturing corridors attract module integration investments for export-oriented roadster component supply.
Automotive Convertible Top Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in convertible top supply. Webasto Group and Magna International anchor the integrated tier through captive engineering and module assembly capabilities. Specialists concentrate in textile lamination, precision hinge machining, and electro-hydraulic component supply. Strategic moves center on co-location with OEM engineering centers for just-in-sequence delivery and direct sourcing relationships that compress channel structures.
Among European-based system integrators, Webasto Group and Valmet Automotive exemplify divergent positioning archetypes. Webasto represents the technology leadership model built on decades of soft-top and retractable-hardtop engineering across German and Italian OEM programs. Valmet Automotive occupies the specialized contract manufacturing position for low-volume premium roadster platforms. Magna International anchors North American production through integrated module assembly capabilities.
| Leading Market Players |
|---|
| Inalfa Roof Systems |
| Valmet Automotive |
| Webasto Group |
| Grupo Antolin |
| The Haartz Corporation |
| Magna International |
| Aisin Seiki |
| Edscha |
| Continental AG |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-week sealing validation cycles compress inventory turns and amplify pricing power for qualified suppliers serving German and Italian OEM roadster programs. This lead-time band concentrates procurement leverage among system integrators with captive testing infrastructure, while tier-two textile laminators absorb margin pressure from raw material volatility.
Pricing Analysis
Geographic price spreads of 20-35 percent separate Stuttgart-engineered premium systems from volume-oriented Asian supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with ECE R43 compliance commanding substantial premiums over baseline weather-protection specifications. Cost compression in mid-tier canvas-polyester laminates is intensifying because European compounders pass through ethylene-propylene feedstock swings without hedging instruments. Aftermarket replacement channels exhibit highest price sensitivity; ultra-luxury roadster OEMs demonstrate least sensitivity given direct-sourcing relationships with Como-based finishers.
Supply Chain Analysis
Butyl rubber core supply from Antwerp-Rotterdam petrochemical corridors represents a chokepoint for acoustic laminate production across European convertible programs. Manufacturing gravity centers on Germany, Italy, and Mexico, with Stuttgart-Munich clusters anchoring engineering development and Ontario facilities serving North American module assembly. The supply chain draws from specialized textile laminators in Northern Italy, precision hinge machinists in Turin-Modena, and electro-hydraulic component suppliers in Nagoya. Single-source vulnerability concentrates in low-volume Italian roadster programs where tight tolerance stacks generate manufacturing yield losses. Distribution runs through just-in-sequence delivery networks co-located with OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around ECE R43 and NHTSA 216a compliance creates formidable defensive moats for incumbent system integrators. Switching costs escalate as OEMs lock in validation cycles and homologation investments across multi-year platform lifecycles.
For Market Incumbents: Consolidate around electro-hydraulic actuation miniaturization and sensor-integrated top modules to defend against battery-electric platform entrants. Acquire specialized CAE simulation capabilities in Stuttgart engineering corridors before German services firms escalate premium rates. Prioritize backward integration into butyl rubber compounding to insulate margins from petrochemical volatility. For New Entrants and Emerging Players: Anchor in India's emerging BIS certification pathway as German and Italian OEMs expand local assembly for export-oriented roadster component supply. Target Maharashtra-Gujarat manufacturing corridors with module integration investments positioned for premium vehicle sourcing. Pursue direct relationships with battery-electric roadster platforms reconfiguring rear-deck stowage around flat battery packs. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because ECE R43 and NHTSA compliance burdens compound faster than new entrant qualification timelines. Target specialized textile laminators with captive finishing capabilities in Como and Stuttgart-adjacent technical centers. Watch electric roadster platform announcements from German OEMs as inflection indicators for top-system packaging demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| ECE R43 Certification Investment | Opens access to Stuttgart, Munich, and Italian OEM supply chains for glazing suppliers. |
| Electro-Hydraulic Actuator Miniaturization | Enables convertible fitment on subcompact electric vehicles competing for rear-deck volume. |
| Direct Sourcing with Textile Laminators | Eliminates margin stacking for ultra-luxury roadster programs assuming inventory risk. |
| Co-Location with OEM Engineering Centers | Supports just-in-sequence delivery requirements across German and Italian manufacturing clusters. |
| Sensor-Integrated Top Module Development | Integrates ADAS hardware into folding hardtop panels for luxury SUV convertibles in Italy. |
Methodological Framework
Desk research of vehicle production databases, IHS Markit registration data, and OEM supplier qualification records preceded structured interviews with Tier 1 procurement managers, platform engineers at Stuttgart and Munich engineering centers, aftermarket distributors, and textile laminator technical directors. Bottom-up volume estimates triangulated against top-down OEM program spending allocations across the analysis window.
Variance decomposition across actuation technology, vehicle architecture, material specification, and regional production clusters shaped the analytical framework. Segmentation dimensions modeled include power-hybrid-manual actuation categories, coupe-roadster-SUV-luxury vehicle classes, canvas-leather-vinyl-cotton material tiers, and weather-noise-UV-aesthetic functionality specifications. CAGRs derived from installed base evolution, replacement cycle timing, and electric platform transition assumptions.
Material uncertainties — BIS standard finalization timelines, ethylene-propylene feedstock volatility, and pedestrian protection standard evolution — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization pressures and OEM platform commitment durability. Practitioners should keep alternative scenarios live as battery-electric roadster volume trajectories and Indian premium vehicle localization policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Active Spoiler Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Automotive Interior Bovine Leather Market