
 Automotive Fire Suppression System Market | 2026-2036
Automotive Fire Suppression System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fire Suppression System Market Outlook
Certified fire suppression technicians is reorganizing supply capacity across the automotive fire suppression value chain, creating bottlenecks for system installation and maintenance networks. Johnson Controls International PLC sustains broad geographic coverage through its building technologies infrastructure that extends into vehicular safety applications. Minimax Viking Group specializes in industrial fire protection engineering that translates directly into heavy-duty automotive specifications. Rosenbauer dominates European emergency vehicle integration, leveraging its firefighting equipment heritage to anchor premium system design standards.
An automotive fire suppression system constitutes an engineered assembly of detection sensors, extinguishing agent storage vessels, and discharge nozzles designed to automatically identify and suppress combustion events in engine compartments, battery enclosures, or cargo areas, typically activating within 10-30 seconds of flame detection to prevent total vehicle loss. These systems serve the primary commercial purpose of protecting high-value mobile assets, reducing insurance liabilities, and ensuring operator survival in enclosed cabin environments. Aerosol systems lead the product type landscape due to their compact form factor and minimal residue characteristics, while smart technology systems represent the fastest-growing technology dimension as CAN-bus integration enables real-time diagnostic feedback to fleet management platforms. Chemical foam systems retain entrenched positions in heavy-duty trucking applications where Class B fuel fire risks predominate.
The U.S. NHTSA and FMCSA jointly shape North American demand through motor carrier safety regulations that mandate fire suppression on specific commercial vehicle categories, while the EU's UNECE R107 standard governs bus and coach fire safety performance across member states. China's MIIT enforces GB standards for new energy vehicle battery compartment protection, directly stimulating domestic system procurement. Stakeholders must monitor evolving electric vehicle thermal runaway protocols across multiple jurisdictions to anticipate next-generation system specifications and certification requirements.
Market Dynamics
Fleet operators are retrofitting legacy commercial vehicles under tightening NHTSA motor carrier safety protocols, compressing installation timelines and straining certified technician networks across North American trucking corridors.
Growth Catalysts
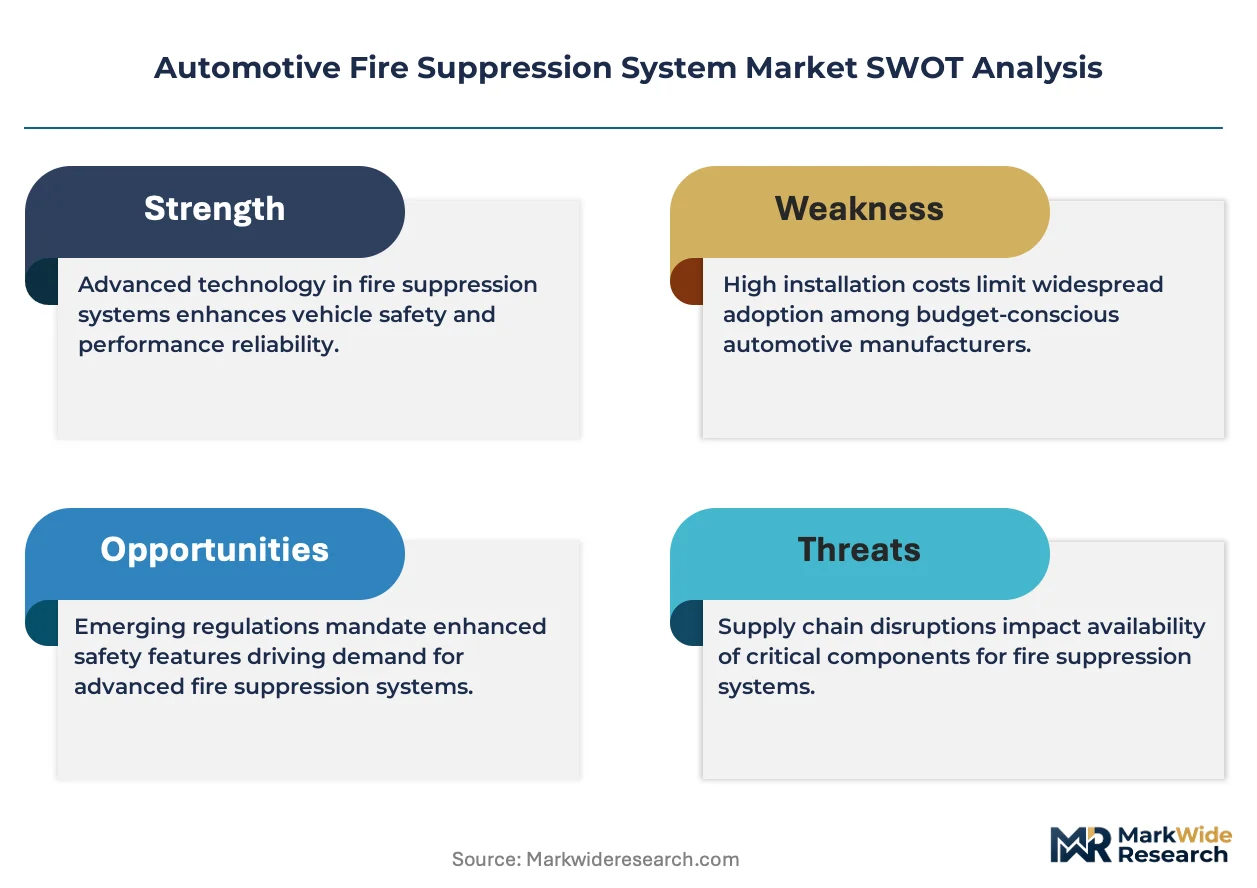
- UNECE R107 bus safety mandates:European operators must install automatic fire suppression in engine compartments and battery enclosures, creating sustained replacement demand across aging municipal fleets.
- Electric vehicle thermal runaway protocols:China's MIIT enforces GB standards for new energy vehicle battery compartment protection, directly stimulating domestic system procurement from local manufacturers.
- Long-haul corridor risk concentration:Commercial vehicle fleet operators traversing high-temperature southwestern US routes are expanding installation mandates to reduce cargo loss and insurance exposure.
Market Restraints
- Certified technician scarcity:Supply capacity bottlenecks in fire suppression system installation and maintenance networks limit deployment velocity regardless of hardware availability.
- Extinguishing agent cost volatility:Fluorinated chemical feedstocks face input price pressure under EU F-Gas Regulation phase-down schedules, compressing margins for foam-based system manufacturers.
- Legacy fleet retrofit economics:Aging diesel-powered commercial vehicles face prohibitive installation costs relative to remaining service life, delaying adoption in owner-operator segments.
Strategic Opportunities
- CAN-bus integrated diagnostics:Smart technology systems enabling real-time flame detection feedback to fleet management platforms represent underpenetrated white space in connected vehicle architectures.
- Aerosol system form factor miniaturization:Compact residue-minimal designs open installation pathways in electric passenger vehicle battery enclosures where space constraints previously excluded active suppression.
- Germany's industrial automotive belt concentration:Commercial vehicle OEMs integrating factory-installed systems at rising rates create captive supply relationships with tier-one safety component suppliers.
Industry Challenges
- Multi-jurisdiction certification complexity:System manufacturers must navigate divergent NHTSA, UNECE, and GB testing protocols simultaneously, extending product validation timelines.
- Integration friction with legacy vehicle electronics:Retrofit installations require custom wiring harness modifications that conflict with existing warranty coverage and fleet maintenance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fire Suppression System Market |
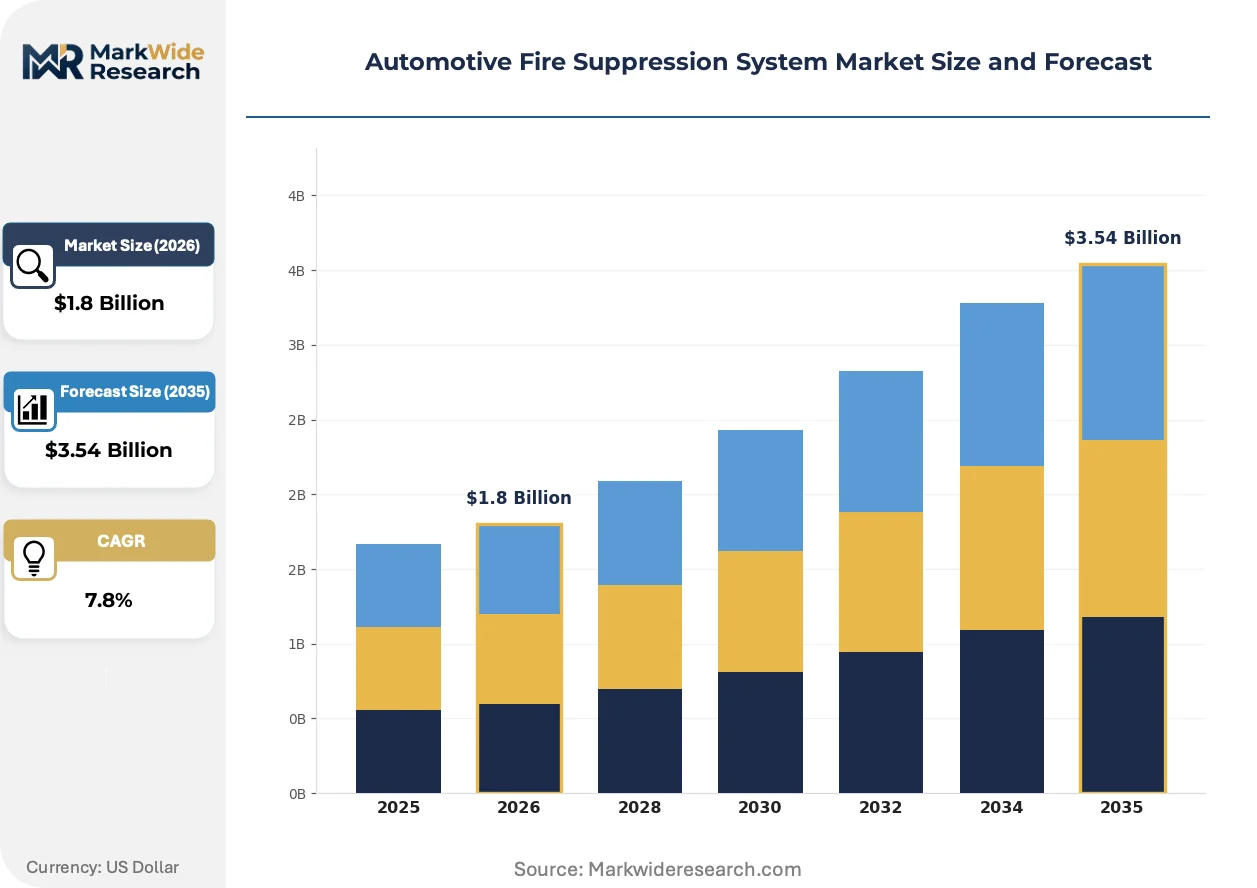
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosol Systems, Water Mist Systems, Chemical Foam Systems, Dry Powder Systems Technology: Active Systems, Passive Systems, Hybrid Systems, Smart Technology Systems Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Heavy-Duty Trucks End User: OEMs, Aftermarket Providers, Fleet Operators, Vehicle Manufacturers |
| Companies Covered | Firetrace International, Fike Corporation, Johnson Controls International PLC, Kidde, Minimax Viking Group, Honeywell International Inc., Reacton Fire Suppression, Rosenbauer, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fire Suppression System Market Strategic Shifts
Detection sensor architectures are fragmenting across optical, thermal, and multi-spectral modalities while extinguishing agent formulations pivot toward low-global-warming-potential alternatives. These shifts are compressing product lifecycles and redrawing competitive boundaries.
Aerosol-based suppression technology is decomposing traditional chemical foam market share in enclosed engine compartment applications. European bus manufacturers are specifying potassium-based condensed aerosol systems for UNECE R107 compliance due to minimal residue and reduced maintenance intervals. This displacement is compressing service revenue streams for incumbent foam system providers while enabling new entrants with compact agent storage expertise.
NHTSA's updated motor carrier safety protocols are accelerating retrofit requirements for specific commercial vehicle categories operating in interstate commerce. The regulatory pressure is forcing fleet operators to prioritize fire suppression alongside electronic logging device compliance in capital allocation decisions. Long-haul trucking corridors in Arizona, Texas, and California are experiencing the fastest compliance-driven installation rates.
After-sales service unbundling is disrupting traditional distribution relationships between system manufacturers and fleet maintenance providers. Large commercial vehicle operators are negotiating direct procurement contracts with suppression system OEMs while outsourcing installation to certified third-party technician networks. This channel disintermediation is most visible in Germany's Ruhr industrial region where major logistics conglomerates operate centralized procurement functions.
Automotive Fire Suppression System Market Segmentation
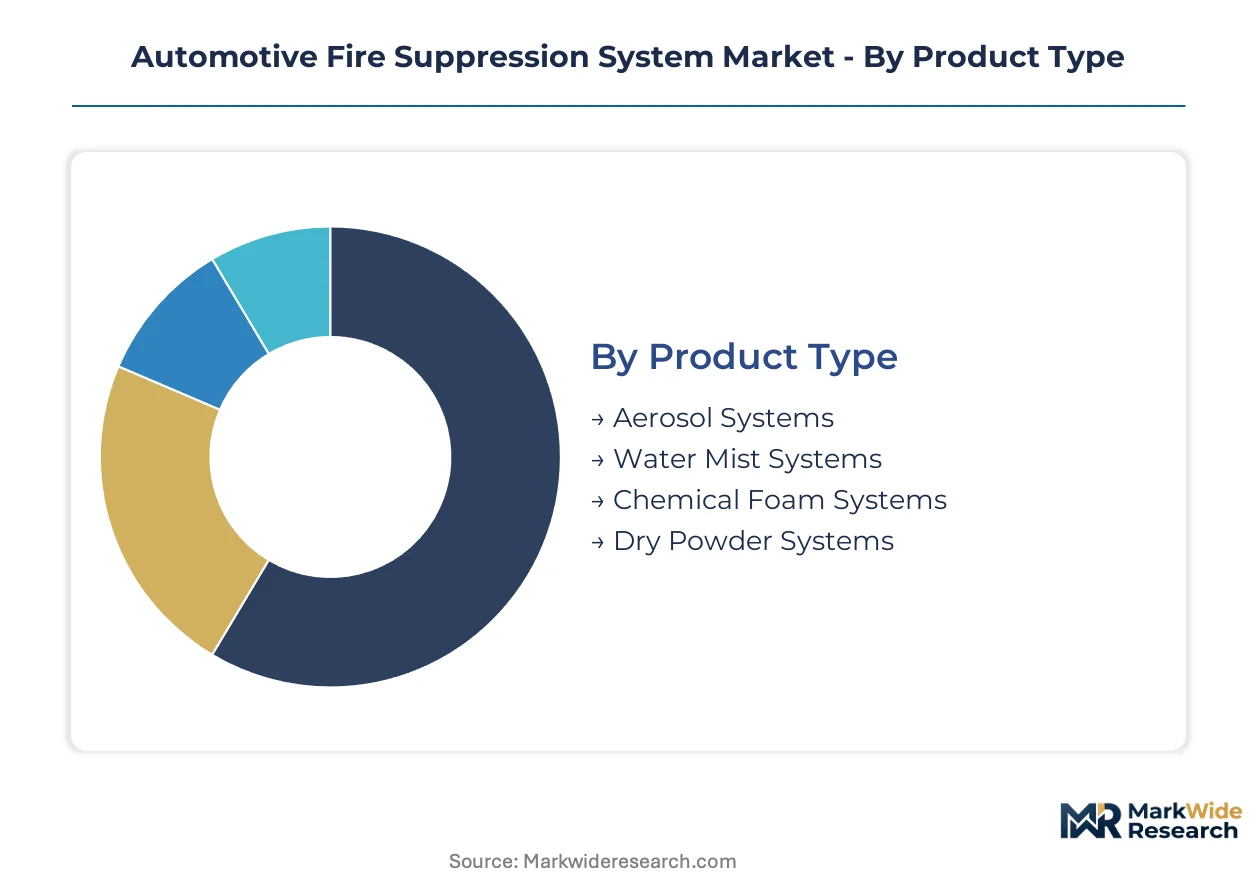
Automotive fire suppression systems fragment across four critical dimensions that determine installation protocols, certification requirements, and procurement economics. Product chemistry and detection technology define performance specifications, while application context and end-user procurement power shape margin distribution across the value chain.
Product Type:
Margin pools concentrate in compact, residue-minimal formulations that reduce maintenance downtime and insurance liability exposure for fleet operators.
- Aerosol Systems:Potassium-based condensed aerosol generators discharge ultra-fine solid particles that interrupt combustion without oxygen displacement. Municipal bus fleets across Germany's industrial automotive belt specify these for UNECE R107 compliance due to minimal cleanup requirements and extended service intervals.
- Chemical Foam Systems:Fluorinated surfactant formulations create oxygen-excluding blankets over Class B fuel fires in diesel engine compartments. Long-haul trucking corridors through Arizona and Texas retain entrenched demand despite EU F-Gas Regulation phase-down pressure on feedstock costs.
- Water Mist Systems:High-pressure micro-droplet dispersion cools combustion zones through vaporization heat absorption without electrical conductivity risks.
- Dry Powder Systems:Sodium bicarbonate or monoammonium phosphate-based suppressants target specific fire classes in mining and off-highway vehicle applications.
The dominant share belongs to chemical foam systems in heavy-duty trucking, while aerosol systems are gaining share fastest in European bus and coach retrofits.
Technology:
Detection and activation architectures determine system responsiveness, false alarm rates, and integration complexity with modern vehicle electronics.
- Smart Technology Systems:CAN-bus integrated platforms transmit real-time flame detection, agent pressure, and nozzle integrity data to fleet management dashboards. These systems command premium positioning as commercial vehicle OEMs in Germany's Ruhr region embed factory-installed configurations with predictive maintenance algorithms.
- Active Systems:Optical, thermal, or multi-spectral sensors trigger automatic discharge within 10-30 seconds of confirmed flame detection.
- Passive Systems:Thermally activated tubing or fusible link mechanisms require no electrical power, serving legacy vehicle retrofits where wiring modifications conflict with warranty terms.
- Hybrid Systems:Dual-mode configurations combine automatic detection with manual override capabilities for operator intervention in specialized cargo applications.
Smart technology systems capture the steepest expansion trajectory through fleet telematics integration, while active systems retain volume leadership across interstate commerce mandates.
Application:
Vehicle category determines fire risk profiles, regulatory exposure, and space constraints for agent storage and nozzle placement.
- Commercial Vehicles:Interstate trucking fleets face NHTSA and FMCSA retrofit deadlines that compress installation timelines across North American corridors. These operators prioritize total cost of ownership calculations balancing hardware investment against cargo loss and liability exposure.
- Electric Vehicles:Battery enclosure thermal runaway protocols in China's MIIT GB standards mandate compartment-specific suppression architectures. Cell-to-pack designs create space constraints that favor miniaturized aerosol generators over foam-based alternatives.
- Heavy-Duty Trucks:Diesel-powered long-haul configurations concentrate in high-temperature southwestern US routes where engine compartment fire risks escalate.
- Passenger Cars:Factory-installed systems remain limited to premium segments and performance variants with elevated thermal management requirements.
Commercial vehicles command the dominant procurement volume, while electric vehicles are climbing the fastest as battery safety regulations proliferate across multiple jurisdictions.
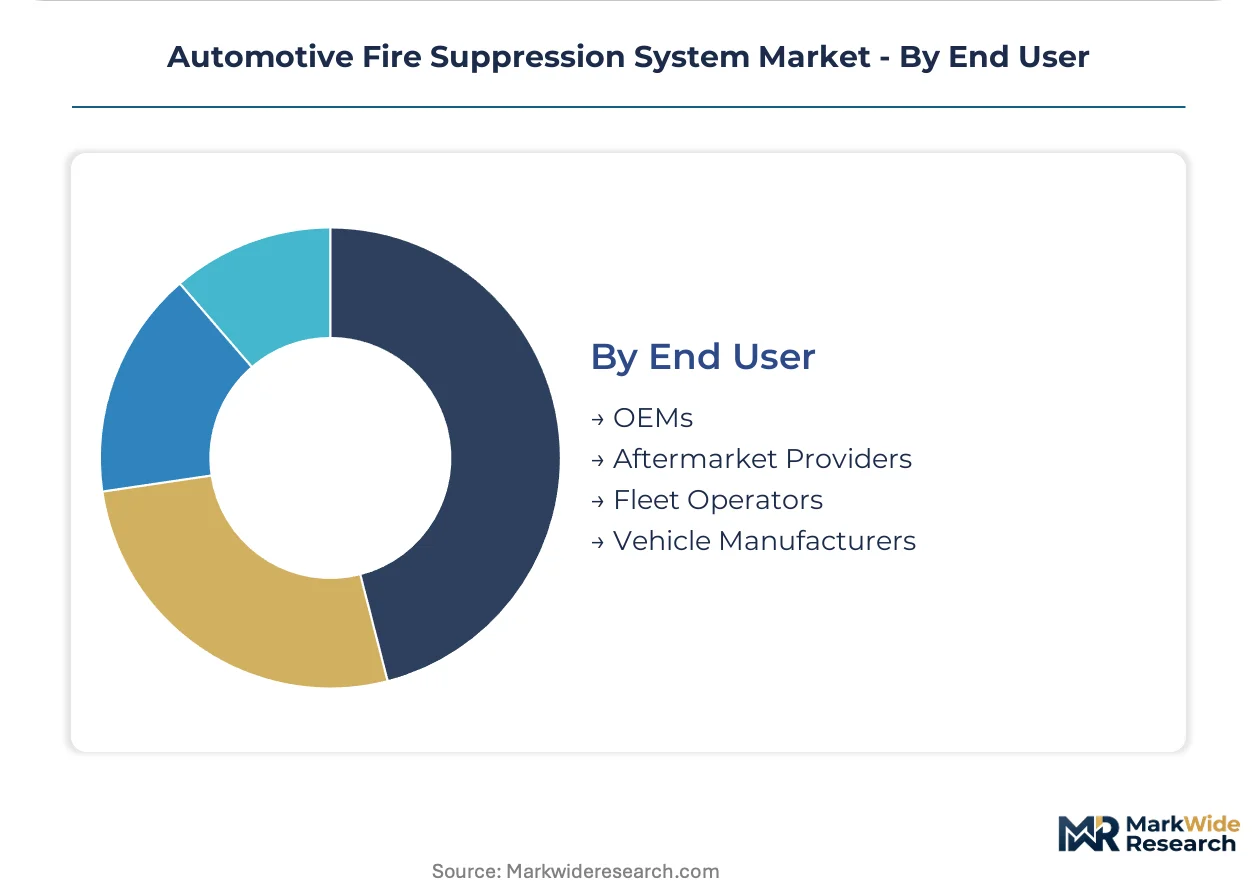
End User:
Procurement authority and technical integration capabilities vary sharply across direct manufacturers, third-party installers, and fleet-owning operators.
- Fleet Operators:Large logistics conglomerates negotiate direct supply contracts with suppression system OEMs while outsourcing installation to certified technician networks. Germany's centralized procurement functions in the Ruhr industrial region exemplify this channel disintermediation pattern.
- OEMs:Commercial vehicle manufacturers in Germany's industrial automotive belt integrate factory-installed systems at rising rates, creating captive supply relationships with tier-one safety component suppliers.
- Aftermarket Providers:Independent distributors and service networks face certified technician scarcity that limits deployment velocity regardless of hardware availability.
- Vehicle Manufacturers:Passenger car and light truck producers specify suppression systems as optional or standard equipment based on platform thermal management architecture.
Fleet operators are consolidating procurement influence fastest, while OEMs retain margin capture through factory integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA motor carrier safety protocols anchor North American demand, while UNECE R107 mandates and China's MIIT battery enclosure standards create parallel regulatory engines across three continents.
United States
Long-haul trucking corridors through Arizona, Texas, and California concentrate retrofit installation demand as fleet operators compress timelines to meet FMCSA deadlines. NHTSA updated protocols now mandate automatic fire suppression for specific commercial vehicle categories in interstate commerce. The Southwestern route network experiences the fastest compliance-driven deployment rates as temperature extremes elevate engine compartment fire risks.
Germany
Commercial vehicle OEMs in the Ruhr industrial region integrate factory-installed systems at rising rates, creating captive supply relationships with tier-one safety component suppliers. UNECE R107 bus and coach safety standards govern fire performance requirements across EU member states. Municipal bus fleets across North Rhine-Westphalia specify potassium-based condensed aerosol systems for minimal residue and extended service intervals.
China
Domestic system procurement accelerates under MIIT enforcement of GB standards for new energy vehicle battery compartment protection. Cell-to-pack battery designs create space constraints favoring miniaturized aerosol generators over foam-based alternatives. Yangtze River Delta automotive clusters drive factory-installed integration as local OEMs respond to thermal runaway protocol mandates.
Japan
Commercial vehicle manufacturers face METI pressure to align with evolving UNECE technical standards for export market access. Kanto region logistics operators test CAN-bus integrated smart systems for fleet telematics compatibility. Tokyo-based OEMs embed predictive maintenance algorithms in factory-installed configurations for premium heavy-duty platforms.
India
Long-haul commercial vehicle operators traverse high-temperature western and southern corridors where engine fire risks escalate during summer months. The country's national automotive regulator enforces CMVR safety standards that increasingly reference active suppression for passenger-carrying commercial categories. Maharashtra and Gujarat industrial belts concentrate aftermarket installation networks serving owner-operator segments.
Automotive Fire Suppression System Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with premium system engineering concentrated among European emergency equipment specialists and volume manufacturing scaling through diversified industrial conglomerates. The vendor base organizes into three strategic tiers: integrated building-technology multinationals extending into vehicular safety, specialized fire protection engineering firms with heavy-duty automotive specifications, and compact aerosol system innovators penetrating electric vehicle battery enclosures. Dominant competitive moves include strategic partnerships for CAN-bus integration capabilities and geographic expansion through certified technician network licensing.
Among diversified industrial technology providers, Johnson Controls International PLC and Siemens AG occupy positions spanning building automation into vehicular safety applications. Minimax Viking Group and Rosenbauer exemplify the specialized engineering tier, with the former representing industrial fire protection heritage and the latter anchoring European emergency vehicle integration standards. Reacton Fire Suppression sits within the compact system innovation segment.
| Leading Market Players |
|---|
| Firetrace International |
| Fike Corporation |
| Johnson Controls International PLC |
| Kidde |
| Minimax Viking Group |
| Honeywell International Inc. |
| Reacton Fire Suppression |
| Rosenbauer |
| Siemens AG |
| Others |
Value Chain & Pricing Dynamics
Aerosol generator substitution for fluorinated foam systems redraws supply geography toward East Asian electronics manufacturing clusters while compressing pricing premiums previously anchored in European chemical engineering heritage. This input shift simultaneously elevates price competition in compact system tiers and concentrates procurement leverage among fleet operators with centralized technical specifications.
Pricing Analysis
Geographic price spreads of 15-25% separate German factory-integrated systems from North American retrofit installations, with premium-mid-economy pricing differentiation anchored in certification grade and after-sales service bundling. Cost compression in foam-based tiers is intensifying because EU F-Gas Regulation feedstock restrictions elevate input expenses. Fleet operators with centralized procurement functions exhibit lowest price sensitivity, while owner-operator segments in India's western corridors face acute budget constraints.
Supply Chain Analysis
China and Germany anchor aerosol generator and precision nozzle fabrication respectively, with South Korea supplying optical detection sensors for smart system integration. Extinguishing agent formulations draw from fluorochemical feedstocks concentrated in Belgian and Chinese production bases. Single-source vulnerability in certified technician networks creates deployment bottlenecks regardless of hardware availability. Distribution runs through tier-one safety component suppliers capturing factory-install contracts with OEMs, while aftermarket channels fragment across independent service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where multi-jurisdiction certification requirements create switching costs that protect incumbent positions against technology substitution threats.
For Market Incumbents: Secure captive supply relationships with commercial vehicle OEMs in Germany's Ruhr industrial region through exclusive factory-install agreements. Deepen backward integration into aerosol generator production to offset fluorochemical feedstock cost volatility. Prioritize CAN-bus diagnostic certification investment to defend against compact system innovators penetrating electric vehicle battery enclosures. For New Entrants and Emerging Players: Lead with miniaturized aerosol form factors targeting China's Yangtze River Delta electric vehicle clusters where cell-to-pack designs exclude foam alternatives. India's high-temperature western corridors present the most penetrable retrofit geography for residue-minimal systems. Pursue direct procurement contracts with logistics conglomerates operating centralized fleet management platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed fire protection engineering specialists holding UNECE R107 certification portfolios and established technician training networks. Five-to-ten year viability hinges on electric vehicle thermal runaway protocol alignment across multiple jurisdictions. Monitor NHTSA motor carrier safety protocol expansion timelines as the critical inflection signal for North American retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| CAN-Bus Integration Partnership | Enables real-time diagnostic feedback to fleet management platforms in Germany's Ruhr region. |
| Aerosol Generator Miniaturization | Opens battery enclosure pathways in China's Yangtze River Delta electric vehicle production. |
| Certified Technician Network Licensing | Addresses supply capacity bottlenecks constraining North American retrofit installation velocity. |
| UNECE R107 Certification Investment | Secures mandatory compliance positioning for European municipal bus fleet replacements. |
| Fluorochemical Feedstock Substitution | Mitigates EU F-Gas Regulation margin compression for foam-based system manufacturers. |
Study Parameters
Initial hypotheses were tested against primary input from fleet operations directors, OEM platform engineers, certified fire suppression technicians, and aftermarket distribution managers and refined through secondary validation. Primary fieldwork combined structured interviews with secondary sources including NHTSA motor carrier safety filings, UNECE technical regulation databases, MIIT GB standard publications, and commercial vehicle production registration data. Bottom-up installation volume estimates and top-down regulatory mandate projections were triangulated to establish market sizing boundaries.
Variance decomposition across product chemistry, detection technology, vehicle application, and end-user procurement authority shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling applied to regulatory mandate timelines and fleet replacement cycles. Industry-specific forecast inputs incorporated electric vehicle thermal runaway protocol adoption curves and certified technician network expansion rates.
Forecasts assume regulatory continuity in NHTSA motor carrier safety protocols, UNECE R107 bus safety standards, and China's MIIT battery enclosure mandates; material policy shifts would require re-modeling. Electric vehicle fire safety regulation acceleration or fluorochemical feedstock restriction tightening represent specific revision triggers. Recalibration cycles align with material shifts in regulatory mandate scope and electric vehicle platform architecture transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Inspection Tunnels Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Emergency Vehicle Lights Market
Automotive Safety and Security Systems
Anti-Lock Braking System (ABS) Market
Automotive Safety and Security Systems
Remote Vehicle Shutdown System Market
Automotive Safety and Security Systems
Global Automotive Radar Sensors Market
Automotive Safety and Security Systems
Automotive Smart Security Device Market
Automotive Safety and Security Systems
Automotive HD/Imaging Radar Market
Automotive Safety and Security Systems
China Traffic Sign Recognition Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Europe Airbag Systems Market
Automotive Safety and Security Systems
Motorcycle Start Stop Systems Market
Automotive Safety and Security Systems
Automotive Night Vision Sensors Market
Automotive Safety and Security Systems
Automotive Immobilizer Market
Automotive Safety and Security Systems
Automotive Inflatable Seat Belt Market
Automotive Safety and Security Systems
Motorcycle E-Call Market