
 Automotive Cockpit Soc Market | 2026-2036
Automotive Cockpit Soc Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cockpit Soc Market Insights
The capability gap between custom silicon designers and legacy automotive MCU suppliers is rotating competitive capital allocation toward high-performance compute. Qualcomm Technologies leverages its Snapdragon Digital Chassis platform to sustain design wins across premium infotainment consolidation. NVIDIA Corporation anchors next-generation cockpit visualization through GPU-accelerated rendering for multi-display architectures. NXP Semiconpetitors in instrument cluster safety integrity levels with its domain controller portfolio.
An automotive cockpit SoC integrates heterogeneous compute cores, GPU clusters, neural processing units, and functional safety islands onto monolithic or chiplet-based silicon to power real-time driver information, entertainment streaming, and human-machine interfaces. These devices typically operate across AEC-Q100 Grade 2 temperature ranges while executing mixed-criticality workloads under ISO 26262 ASIL-B to ASIL-D constraints. The passenger vehicles application segment dominates socket volume as OEMs standardize widescreen digital clusters and head-up displays across mass-market trims. The artificial intelligence technology segment leads content growth through voice biometrics, occupant monitoring, and predictive HMI personalization engines. The electric vehicles application segment exhibits the fastest design-in velocity as native EV platforms omit mechanical gauges entirely.
The US NHTSA distraction guidelines and Europe's ECE R79 driver interaction standards constrain touchscreen response latency and gaze-transition times, directly shaping SoC real-time performance requirements. China's MIIT GB/T standards for in-vehicle network security and data privacy mandate hardware-rooted trust execution environments, adding silicon area and certification cost. Stakeholders must monitor how UN ECE WP.29 cybersecurity regulation propagation and EPA-adjacent state-level autonomous testing frameworks reshape cockpit compute redundancy requirements.
Market Dynamics
Automotive cockpit SoC procurement is bifurcating between monolithic high-performance dies for premium EV platforms and chiplet-based modular architectures for cost-sensitive mass-market trims. This structural split is reshaping foundry capacity allocation, IP licensing negotiations, and tier-one system integrator partnerships across the supply chain.
Growth Catalysts
- China's MIIT GB/T cybersecurity mandates:Hardware-rooted trust execution environments are becoming mandatory for connected vehicle data governance, expanding silicon content per vehicle.
- Electric vehicle platform consolidation:Native EV architectures omit mechanical instrument clusters entirely, requiring full-digital cockpit compute from single SoC suppliers.
- Head-up display standardization:Widescreen HUD penetration across mid-tier passenger vehicles is driving GPU cluster requirements upward.
Market Restraints
- Advanced node foundry concentration:Sub-7nm automotive-qualified capacity concentrates at TSMC and Samsung Foundry, creating single-source exposure for high-performance cockpit silicon.
- AEC-Q100 Grade 2 qualification timelines:Extended thermal cycling and electromigration testing stretches time-to-revenue for new SoC tapeouts to 18-24 months.
- ISO 26262 ASIL-D certification costs:Functional safety documentation and third-party assessment fees add substantial non-recurring engineering overhead.
Strategic Opportunities
- India's domestic EV manufacturing incentives:PLI scheme subsidies for automotive electronics are attracting cockpit SoC packaging and testing investments from multinational suppliers.
- Software-defined vehicle architectures:Over-the-air update requirements are converging with zonal E/E designs, creating demand for virtualization-capable heterogeneous compute.
- Occupant monitoring system mandates:Euro NCAP 2026 protocols for driver distraction detection are mandating neural processing unit integration into base-trim cockpit controllers.
Industry Challenges
- Functional safety architect scarcity:ISO 26262-certified hardware designers command premium compensation, constraining R&D scaling for mid-tier semiconductor houses.
- Legacy CAN-FD integration complexity:Mixed-criticality workloads must coexist with 20-year-old vehicle network protocols, complicating real-time scheduling verification.
- IP licensing fragmentation:ARM CPU cores, Imagination GPU blocks, and proprietary NPU designs require multi-party royalty negotiations that extend contract closure timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cockpit Soc Market |
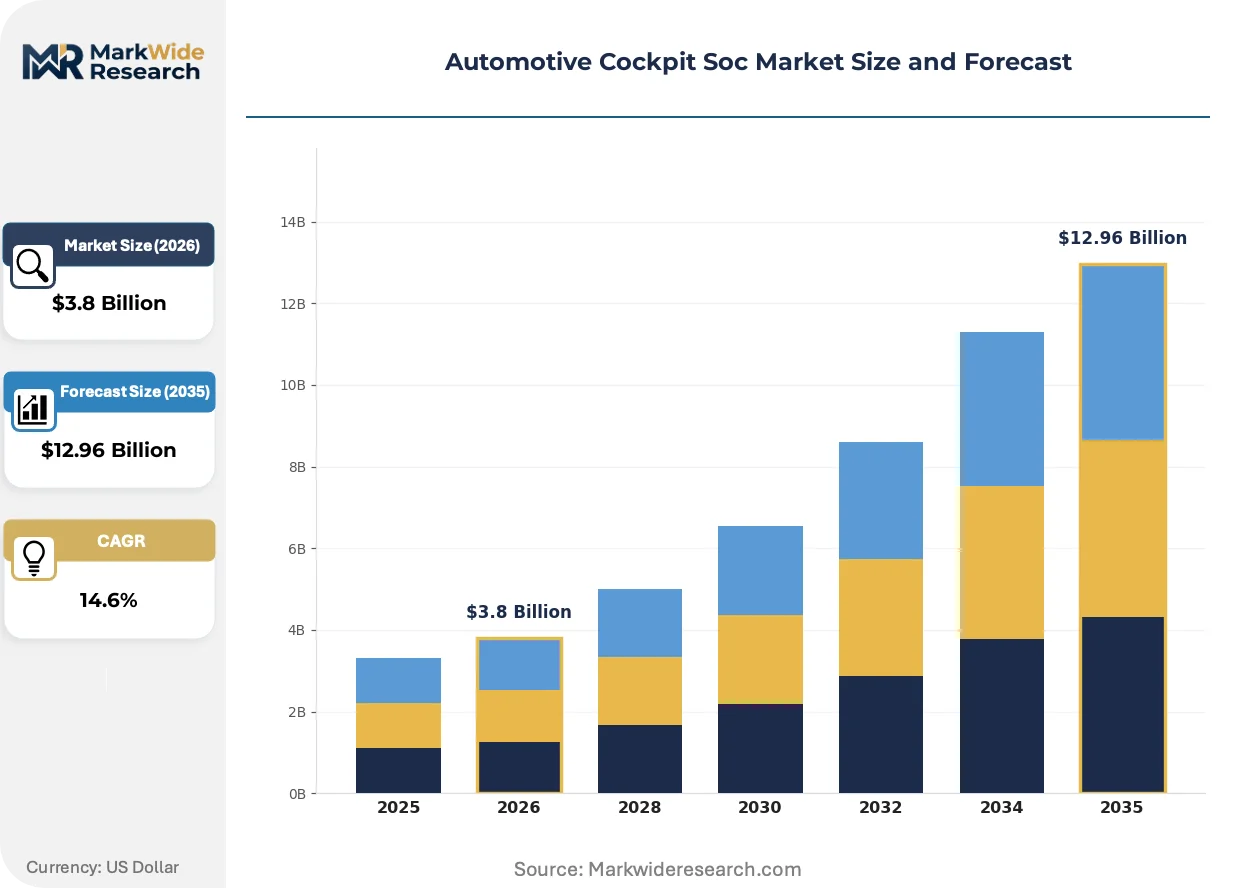
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infotainment Systems, Instrument Clusters, HUD, Connectivity Modules End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Fleet Operators Technology: Artificial Intelligence, Touchscreen Interfaces, Voice Recognition, Wireless Connectivity Application: Passenger Vehicles, Commercial Vehicles, Luxury Cars, Electric Vehicles |
| Companies Covered | Qualcomm Technologies, NVIDIA Corporation, Texas Instruments, Infineon Technologies, NXP Semiconductors, Renesas Electronics, HiSilicon, Rockchip Electronics, Telechips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cockpit Soc Market Trends and Innovations
Cockpit electronics are converging toward centralized compute domains that consolidate previously distributed instrument cluster, infotainment, and ADAS visualization functions. This architectural compression is eliminating redundant silicon and rewiring tier-one supplier competitive positioning.
Chiplet-based SoC packaging is bifurcating the market between integrated monolithic dies and disaggregated compute tiles. Premium EV platforms from German and US OEMs are adopting chiplet architectures to mix process nodes and reduce reticle-limited yield risk. This technology is bifurcating foundry relationships and IP licensing models as designers source chiplets from multiple vendors.
Europe's ECE R79 driver distraction regulation is tightening gaze-transition time limits and touchscreen response latency requirements. The industrial consequence is mandatory deterministic GPU rendering pipelines that preempt frame drops under thermal throttling. German premium OEMs are most affected, accelerating adoption of hardware-scheduled display controllers with guaranteed worst-case execution times.
Long-term supply agreements are displacing spot-market purchasing for automotive-grade memory and advanced packaging substrates. Tier-one cockpit system integrators are locking multi-year die supply directly with foundries, bypassing traditional semiconductor distributor channels. This pattern is most visible in China where domestic EV brands are securing captive capacity for 2027-2028 platform launches.
Automotive Cockpit Soc Market Segmentation
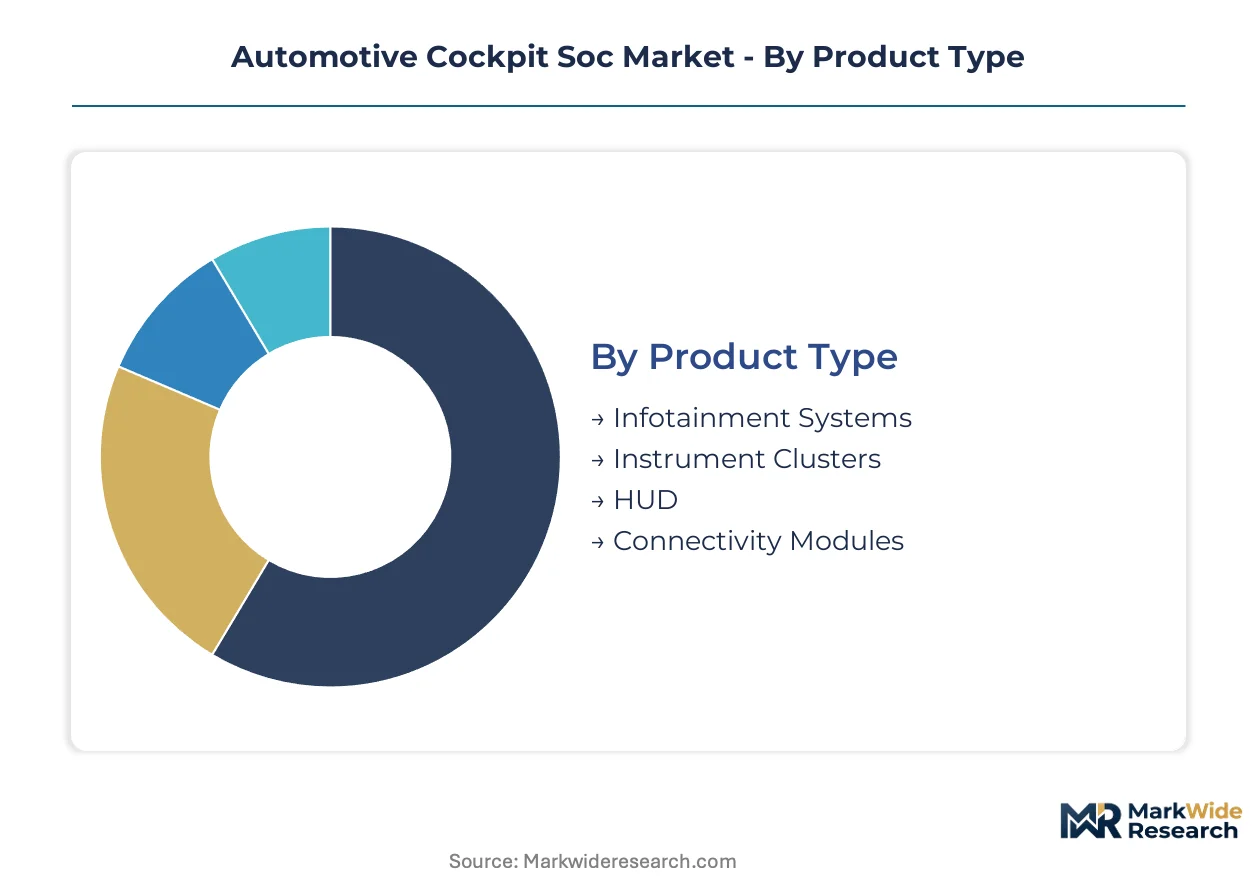
Automotive cockpit SoC procurement varies sharply across integration depth, buyer sophistication, and compute intensity requirements. Segment boundaries are blurring as domain consolidation pushes previously discrete functions onto unified silicon, yet procurement channels and certification tiers maintain distinct economic profiles.
Product Type:
Infotainment Systems face acute substitution pressure from smartphone mirroring protocols and wireless projection standards that bypass native silicon entirely.
- Infotainment Systems:These SoCs manage multimedia streaming, navigation rendering, and third-party app ecosystems through heterogeneous CPU-GPU clusters. China's domestic EV brands and German premium OEMs are driving socket demand for 4K-capable multi-display controllers with hardware virtualization support.
- Instrument Clusters:Safety-critical digital gauge controllers execute ISO 26262 ASIL-B to ASIL-D workloads with deterministic frame rendering. US and German passenger vehicle platforms are standardizing full-digital clusters even on mid-tier trims, eliminating mechanical gauge substitution risk.
- HUD:Head-up display processors require dedicated GPU pipelines for real-time optical distortion correction and brightness compensation across temperature ranges.
- Connectivity Modules:Telematics and V2X communication controllers integrate cellular modems with hardware security modules for GB/T and UN ECE WP.29 compliance.
Instrument Clusters retain volume leadership; Electric Vehicle native platforms are accelerating HUD adoption fastest.
End User:
Cost tier stratification separates captive OEM design teams from merchant market suppliers competing on qualification speed.
- OEMs:Vertical integration into silicon specification and firmware co-development is concentrating among US and Chinese EV manufacturers with dedicated compute architecture teams. These buyers prioritize long-term roadmap alignment over unit pricing.
- Tier-1 Suppliers:Continental, Bosch, and Denso-equivalent integrators aggregate SoC demand across multiple OEM programs, capturing scale economies in AEC-Q100 qualification and safety documentation. Their procurement concentrates on programmable platforms supporting multi-customer reuse.
- Aftermarket Providers:Retrofit infotainment and cluster upgrade suppliers target vehicle parc renewal with reduced functional safety requirements and faster certification cycles.
- Fleet Operators:Commercial vehicle and mobility-service buyers prioritize telematics integration and remote diagnostics over occupant experience features.
Tier-1 Suppliers dominate procurement volume; OEM direct engagement is climbing the fastest.
Technology:
Application intensity determines which compute modalities command silicon area allocation and thermal design power budgets.
- Artificial Intelligence:Neural processing units for voice biometrics, occupant monitoring, and predictive HMI personalization are expanding die area fastest. Euro NCAP protocols mandating driver distraction detection are accelerating NPU integration into base-trim controllers.
- Touchscreen Interfaces:Capacitive multi-touch controllers with haptic feedback synthesis require dedicated sensor fusion processors and deterministic latency guarantees under ECE R79 constraints.
- Voice Recognition:Natural language processing engines execute on-die or cloud-hybrid architectures depending on connectivity reliability requirements.
- Wireless Connectivity:Wi-Fi 6E, Bluetooth 5.3, and ultra-wideband positioning modules integrate baseband processing with hardware security for keyless entry and phone-as-key ecosystems.
Touchscreen Interfaces retain installed base dominance; Artificial Intelligence is expanding most quickly.
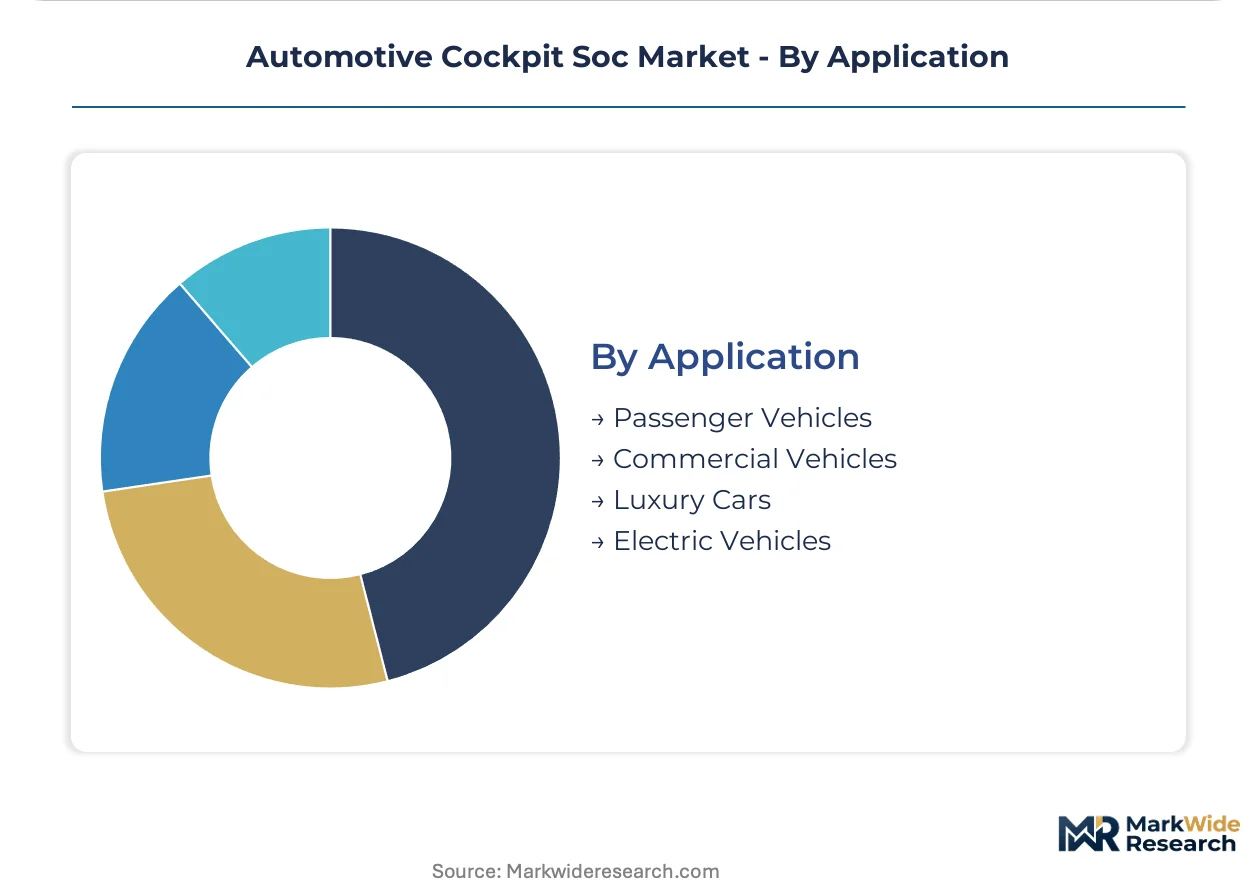
Application:
Vehicle electrification status creates the steepest divergence in cockpit compute requirements and replacement timelines.
- Passenger Vehicles:Mass-market sedans and crossovers standardize widescreen digital clusters and central infotainment displays across trim levels. Chinese and US OEMs are driving the highest volume procurement for consolidated domain controllers.
- Electric Vehicles:Native EV architectures omit mechanical gauges entirely, requiring full-digital cockpit compute from single SoC suppliers. These platforms adopt the newest silicon nodes and chiplet packaging fastest.
- Commercial Vehicles:Truck and bus applications prioritize durability and regulatory compliance over display density, with slower refresh cycles.
- Luxury Cars:Premium sedans and SUVs deploy multi-display arrays with passenger entertainment zones and advanced ambient lighting control.
Passenger Vehicles anchor procurement volume; Electric Vehicles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese EV buyers demonstrate the lowest price elasticity for consolidated cockpit silicon, while European mass-market OEMs impose the strictest cost-per-socket constraints. This divergence shapes where suppliers allocate advanced node capacity versus legacy process derivatives.
China
Domestic EV brands BYD and NIO are driving the fastest design-in velocity for multi-display domain controllers. MIIT GB/T cybersecurity standards mandate hardware-rooted trust execution environments, expanding die area requirements. Shanghai and Shenzhen host the densest clusters of cockpit system integrators securing long-term foundry capacity through 2028.
Germany
Premium OEMs BMW and Mercedes-Benz are accelerating chiplet adoption to reduce reticle-limited yield risk on large monolithic dies. ECE R79 driver distraction regulations enforce deterministic GPU rendering with guaranteed worst-case execution times. Bavaria's automotive electronics corridor around Munich concentrates tier-one R&D centers for functional safety documentation.
United States
Tesla and Rivian are standardizing full-digital cockpits across all trims, eliminating mechanical gauge suppliers entirely. NHTSA distraction guidelines constrain touchscreen response latency, shaping real-time performance specifications. Austin and Detroit anchor competing design philosophies between native EV architectures and legacy platform migrations.
South Korea
Hyundai Motor Group and Kia are procuring integrated cockpit processors for global EV platform exports. Korea's national semiconductor strategy subsidizes domestic advanced packaging investments. Seoul's Pangyo techno-valley clusters fabless cockpit SoC designers partnering with Samsung Foundry for 4nm automotive qualification.
India
Domestic EV manufacturing incentives under the PLI scheme are attracting cockpit SoC packaging and testing investments. Automotive electronics import substitution policies favor local assembly of imported die. Tamil Nadu and Gujarat host emerging substrate fabrication facilities serving multinational tier-one suppliers.
Automotive Cockpit Soc Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in cockpit SoC supply. Qualcomm and NVIDIA occupy the premium consolidation layer through heterogeneous compute platforms, while NXP and Renesas anchor the safety-critical instrument cluster segment. Three archetypes define competitive positioning: mobile-silicon transplants with consumer IP leverage, legacy automotive MCU suppliers with functional safety certification depth, and domestic Chinese designers with captive EV OEM relationships. Capacity reservation agreements and multi-year die supply contracts represent the dominant competitive moves, displacing spot-market purchasing.
Within the mobile-silicon transplant archetype, Qualcomm Technologies and NVIDIA Corporation exemplify how consumer GPU and AI accelerator IP migrates into automotive-qualified silicon. Texas Instruments and NXP Semiconductors occupy positions within the legacy automotive tier, leveraging decades of AEC-Q100 qualification experience and ISO 26262 certification infrastructure. These groupings illustrate how competitive capital allocation rotates between custom silicon design capabilities and established automotive supply chain relationships.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| NVIDIA Corporation |
| Texas Instruments |
| Infineon Technologies |
| NXP Semiconductors |
| Renesas Electronics |
| HiSilicon |
| Rockchip Electronics |
| Telechips |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month AEC-Q100 Grade 2 qualification timelines concentrate pricing power with foundry incumbents possessing automotive-certified capacity, while tier-one integrators leverage long-term die supply contracts to compress spot-market premiums. This lead-time band forces OEMs into multi-year offtake commitments that lock in silicon costs before volume production ramps.
Pricing Analysis
After-sales firmware subscription tiers and over-the-air feature unlocks now drive lifetime value beyond initial silicon procurement. Three-tier pricing structure across premium domain controllers, standard integrated clusters, and economy discrete modules separates socket economics by certification grade and thermal envelope. Pricing pressure stems from Chinese domestic EV brands demanding cost-downs on base-trim controllers while premium German OEMs absorb ASIL-D certification premiums. Tier-one suppliers exhibit highest price sensitivity due to multi-customer program reuse requirements, whereas captive OEM silicon teams prioritize roadmap alignment over unit economics.
Supply Chain Analysis
Sub-7nm automotive-qualified foundry chokepoints at Taiwan and South Korea tether high-performance cockpit silicon to TSMC and Samsung Foundry capacity allocation decisions. Advanced packaging substrates from Japan and substrate fabrication emerging in India feed heterogeneous integration requirements for chiplet-based architectures. Single-source vulnerability concentrates in EUV lithography equipment dependencies and ABF substrate supply. Distribution runs through direct foundry-tier-one partnerships that displace traditional semiconductor distributor channels, with Chinese EV brands pioneering captive capacity reservation models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cockpit SoC procurement is approaching a platform-economics inflection where software-defined vehicle architectures and zonal E/E consolidation reward ecosystem orchestrators over discrete component suppliers. Interoperability shifts toward hypervisor-capable heterogeneous compute are rewriting competitive moats around firmware stacks rather than silicon specifications alone.
For Market Incumbents: Secure multi-year foundry capacity reservations at sub-7nm nodes before Chinese EV brands exhaust automotive-qualified allocation. Deepen functional safety certification infrastructure to defend against mobile-silicon transplants lacking ISO 26262 ASIL-D documentation depth. Prioritize backward integration into advanced packaging substrates to mitigate ABF supply concentration risk from Japanese suppliers. For New Entrants and Emerging Players: Lead with occupant monitoring system mandates as the most penetrable white-space entry point, targeting base-trim cockpit controllers where Euro NCAP 2026 protocols are forcing NPU integration. India's PLI-subsidized packaging and testing investments offer geographic arbitrage for cost-sensitive mass-market programs. Pursue fabless partnerships with Samsung Foundry's 4nm automotive qualification pipeline to bypass TSMC capacity constraints. For Investors and Strategic Acquirers: Carve-out targets emerge from legacy automotive MCU parents with stranded functional safety assets and dormant AEC-Q100 certification infrastructure. Long-term viability favors specialists with chiplet packaging capabilities and zonal E/E architecture alignment over monolithic die designers facing reticle-limited yield risk. Watch for inflection signals in tier-one direct foundry contracting velocity as indicator of pricing power migration from semiconductor houses to system integrators.| Strategic Initiative | Industry Significance |
|---|---|
| Chiplet Packaging Investment | Reduces reticle-limited yield risk for large monolithic cockpit dies across German premium OEM programs. |
| Functional Safety Certification Expansion | ASIL-D documentation depth defends against mobile-silicon transplants lacking automotive qualification heritage. |
| Direct Foundry Partnership | Long-term die supply contracts with TSMC or Samsung Foundry bypass distributor channels and secure capacity. |
| Occupant Monitoring Integration | Euro NCAP 2026 mandates for driver distraction detection accelerate NPU socket wins in base-trim controllers. |
| India Packaging Localization | PLI scheme subsidies attract substrate fabrication and testing investments for cost-sensitive mass-market trims. |
Research Methodology
Operator-level perspectives from OEM platform engineers, Tier 1 supplier procurement leads, foundry automotive business units, and aftermarket distribution channels anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, IHS Markit vehicle production databases, MIIT GB/T standard drafts, and UN ECE WP.29 regulatory texts. Bottom-up socket demand modeling triangulated against top-down semiconductor content-per-vehicle estimates across passenger, electric, and commercial vehicle architectures.
Sensitivity analysis framed volume and value outputs across the projection horizon by propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from segment-level growth rate reconciliation between demand-side adoption curves and supply-side capacity expansion schedules. Forecast inputs incorporated AEC-Q100 qualification timeline distributions, ISO 26262 certification completion rates, and foundry automotive node ramp schedules without year-specific assumptions.
Forecasts assume regulatory continuity in China's MIIT cybersecurity mandates, Europe's ECE R79 driver distraction enforcement, and US NHTSA distraction guidelines; material policy shifts would require re-modeling real-time performance and hardware security requirements. Scenario risks include advanced node foundry concentration disruptions, functional safety architect scarcity compensation inflation, and legacy CAN-FD integration complexity delays. Practitioners should keep alternative scenarios live as zonal E/E architecture migration timelines and chiplet packaging yield maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive AR HUD Market
Automotive Electronics & Wiring
Automotive Radiator Water Temperature Sensor Market
Automotive Electronics & Wiring
Global Automotive Intelligence Park Assist System Market
Automotive Electronics & Wiring
Automotive Sparking Cable Market
Automotive Electronics & Wiring
Automotive Wiring Harness Market
Automotive Electronics & Wiring
Automotive Throttle-By-Wire System Market
Automotive Electronics & Wiring
Connected Car Devices Market
Automotive Electronics & Wiring
Automotive Head-Up Display (HUD) and Instrument Cluster Market
Automotive Electronics & Wiring
Germany Automotive Smart Keys Market
Automotive Electronics & Wiring
Boat Wiring Harness Market
Automotive Electronics & Wiring
Automotive 360 Degree Technology Market
Automotive Electronics & Wiring
Automotive Fuse Block Market
Automotive Electronics & Wiring
Automotive Monitor Touch Market
Automotive Electronics & Wiring
Automotive OLED Market
Automotive Electronics & Wiring
Europe Automotive Smart Keys Market
Automotive Electronics & Wiring
Automotive Console Box Market