
 Automotive Intelligent Rear-View Mirror Market | 2026-2036
Automotive Intelligent Rear-View Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Intelligent Rear-View Mirror Market Outlook
Aftermarket service revenue is fragmenting as original equipment manufacturers capture recurring software update and calibration income previously held by independent repair networks. Gentex Corporation leverages its electrochromic expertise to dominate North American OEM supply contracts for digital mirror systems. Magna International sustains manufacturing scale across multiple continents, anchoring production capacity for major European and Asian automakers. Continental AG competes through integrated sensor-to-display architectures that bundle camera modules with mirror housings.
An automotive intelligent rear-view mirror is an electro-optical display system that replaces or supplements traditional reflective glass with high-resolution camera feeds rendered on LCD or OLED panels, typically operating at refresh rates exceeding 60 Hz and incorporating ambient light compensation algorithms. Its primary commercial purpose is to eliminate rear blind spots, reduce aerodynamic drag, and provide augmented visual data such as traffic alerts or navigation overlays to vehicle operators. Digital mirrors lead product type adoption among luxury vehicle segments where consumers accept premium pricing for expanded field-of-view capabilities, while camera-based technology anchors the largest installed base due to lower per-unit cost and established supply chains. OLED displays represent the fastest-growing technology segment as manufacturers pursue thinner form factors and superior contrast ratios for night-driving visibility.
NHTSA Federal Motor Vehicle Safety Standard No. 111 governs rear visibility requirements in the United States, compelling automakers to certify camera-based mirror systems for field-of-view equivalence with conventional glass. ECE R46 in Europe and GB standards administered by China's MIIT establish parallel compliance frameworks that shape product design and testing protocols across export markets. ISO 16505 provides international performance benchmarks for camera-monitor systems, creating a baseline for cross-border homologation. Stakeholders must monitor evolving cybersecurity mandates for connected mirror systems as regulators in multiple jurisdictions draft over-the-air update and data privacy requirements.
Market Dynamics
Camera-to-display architectures are compressing the traditional mirror supply chain by eliminating glass substrate dependencies and consolidating electro-optical component sourcing under single-tier vendor relationships.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard No. 111:This regulation mandates rear visibility equivalence for camera-based systems, compelling OEMs to certify digital mirrors and accelerating homologation investments across passenger vehicle platforms.
- Commercial fleet operators:Logistics companies operating heavy-duty trucks are specifying intelligent mirrors to eliminate blind spots during urban maneuvering and reduce accident liability exposure.
- OLED panel technology:Thinner form factors and superior contrast ratios are enabling aerodynamic drag reductions that improve electric vehicle range without compromising nighttime visibility performance.
Market Restraints
- Semiconductor input volatility:Image signal processors and display driver ICs face allocation constraints from competing consumer electronics demand, creating cost instability for mirror system integrators.
- Single-source sensor dependency:High-dynamic-range camera modules concentrate among Japanese and South Korean component suppliers, exposing OEMs to geographic concentration risk.
- ECE R46 homologation complexity:European type-approval requirements for camera-monitor systems impose testing protocols that extend development cycles and raise certification barriers for new entrants.
Strategic Opportunities
- India commercial vehicle segment:Stringent government mandates for vehicle safety equipment are creating first-mover advantages for suppliers establishing local assembly partnerships.
- Over-the-air software monetization:Connected mirror platforms enable subscription-based feature activation, generating recurring revenue streams from fielded vehicle populations.
- Sensor fusion convergence:Integration of mirror camera feeds with surround-view and ADAS perception stacks is consolidating hardware footprints and reducing per-vehicle sensor counts.
Industry Challenges
- Embedded software engineering scarcity:Real-time video pipeline optimization and functional safety certification require specialized talent pools that compete with autonomous driving programs.
- ISO 16505 cross-border alignment:Divergent national interpretations of camera-monitor performance benchmarks create retesting requirements that fragment product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Intelligent Rear-View Mirror Market |
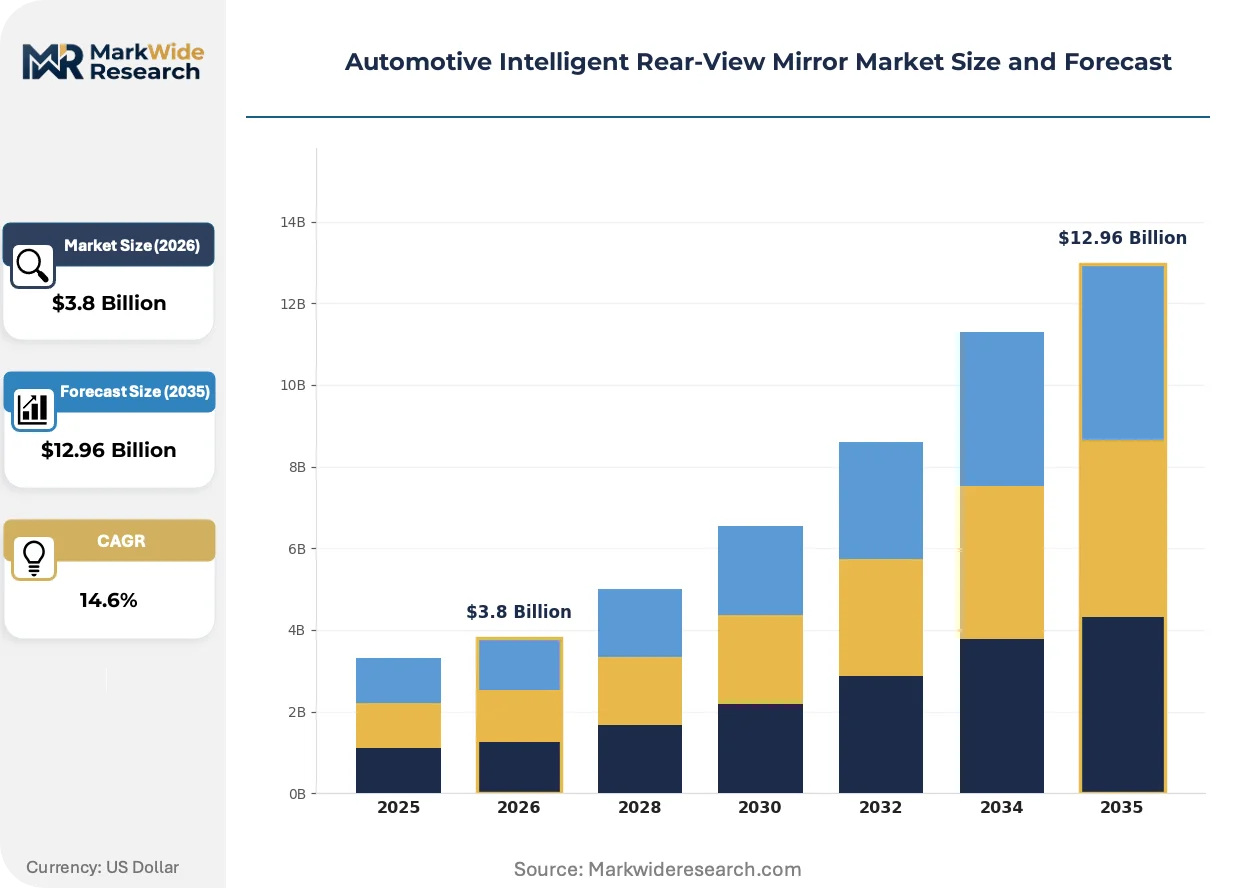
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mirrors, Smart Mirrors, Standard Mirrors, Adaptive Mirrors Technology: Camera-Based, Augmented Reality, LCD, OLED End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Dealerships Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, Luxury Vehicles |
| Companies Covered | Gentex Corporation, Magna International, Ficosa International, Murakami Corporation, Samvardhana Motherson Reflectec, Continental AG, Valeo, MEKRA Lang, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Intelligent Rear-View Mirror Market Strategic Shifts
Electro-optical virtualization is dissolving the boundary between physical mirror hardware and software-defined display surfaces, enabling feature updates that outpace traditional automotive refresh cycles.
Camera-based digital mirror technology is virtualizing the rear-view function by replacing reflective glass with real-time video streams rendered on automotive-grade displays. Premium electric vehicle manufacturers are standardizing these systems across their lineups to achieve aerodynamic efficiency targets. This virtualization is compressing the supplier base by eliminating tiered glass-molding and coating specialists from the value chain.
European ECE R46 regulations are tightening field-of-view and latency requirements for camera-monitor systems, forcing suppliers to upgrade image processing pipelines. The industrial consequence is accelerated R&D spending on low-latency video encoding and fail-operational display architectures. Commercial vehicle segments in Germany and France are responding by pre-certifying integrated mirror systems to avoid production delays.
Fleet procurement departments are consolidating mirror specifications under centralized technical standards that favor integrated sensor-to-display suppliers over component assemblers. Tier-1 distributors serving independent repair networks are losing service revenue to captive OEM calibration and update channels. This consolidation is most visible in North American long-haul trucking, where fleet management companies specify mirror systems with embedded telematics connectivity.
Automotive Intelligent Rear-View Mirror Market Segmentation
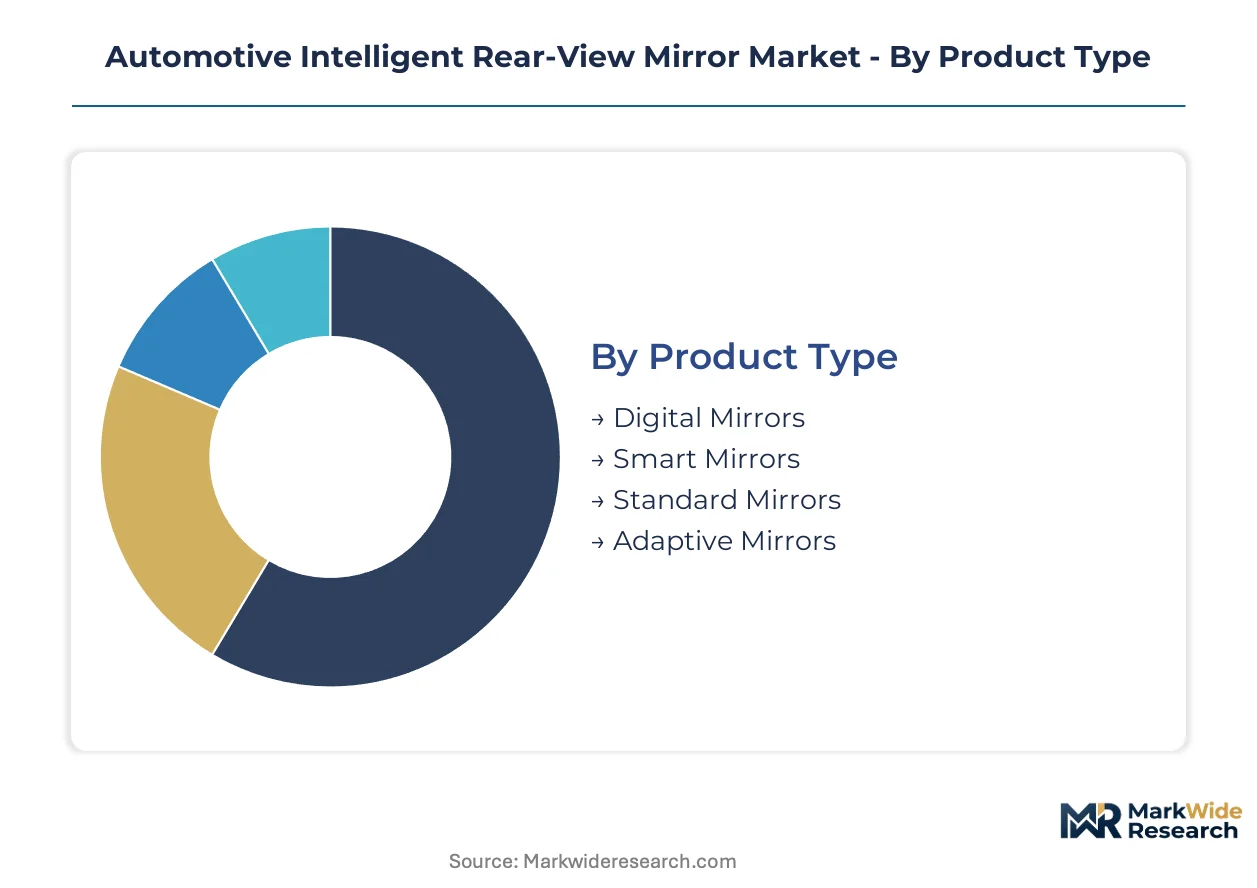
Segmentation in automotive intelligent rear-view mirrors determines warranty exposure, calibration service intervals, and software monetization potential across divergent hardware architectures. After-sales revenue concentration varies dramatically by product complexity and customer channel.
Product Type:
After-sales-service intensity escalates from passive glass replacements to software-dependent electro-optical systems requiring ongoing calibration support.
- Digital Mirrors:Full-display systems replacing reflective glass with camera-fed LCD or OLED panels operating at 60+ Hz refresh rates. Demand concentrates among premium electric vehicle manufacturers in Germany and the United States seeking aerodynamic drag reduction for range optimization.
- Smart Mirrors:Hybrid configurations retaining physical glass with embedded display overlays for navigation and alert data. Fleet operators in North American long-haul trucking specify these for telematics integration without full electro-optical dependency.
- Standard Mirrors:Conventional reflective glass with minimal electro-optical augmentation. Entry-level passenger vehicle platforms in cost-sensitive markets maintain this specification.
- Adaptive Mirrors:Electrochromic systems with automatic dimming and glare suppression. Luxury vehicle lineups standardize these for nighttime driving comfort.
Digital mirrors hold the largest share; momentum sits with smart mirrors bridging cost and functionality.
Technology:
Component sourcing complexity fragments margin structures across display technologies with divergent supply chain maturity.
- Camera-Based:HDR image sensors feeding dedicated image signal processors with real-time distortion correction. Lower per-unit costs anchor the largest installed base across mass-market passenger vehicles.
- OLED:Self-emissive display panels enabling sub-3mm form factors and infinite contrast ratios. Expanding most quickly as Korean and Chinese panel manufacturers scale automotive-grade production.
- Augmented Reality:Overlay rendering engines projecting navigation and hazard alerts onto mirror surfaces. Premium German automakers pilot these for differentiated user experience.
- LCD:Transmissive display technology with mature backlighting supply chains. Cost-sensitive commercial vehicle specifications favor this proven architecture.
Camera-based architectures dominate volume; OLED displays are climbing the fastest on design flexibility.
End User:
Channel structure determines who captures recurring software revenue versus one-time hardware margin.
- OEMs:Vehicle manufacturers specifying mirror systems at platform design stage. Direct procurement relationships consolidate tier-1 supplier access.
- Tier-1 Manufacturers:System integrators bundling camera modules, displays, and processing hardware. These suppliers anchor production contracts for major European and Asian automakers.
- Aftermarket Suppliers:Independent distributors serving vehicle retrofit and replacement demand. Calibration complexity and proprietary software interfaces erode this channel's service revenue.
- Dealerships:Authorized retail channels handling warranty replacements and feature activations. Connected mirror platforms shift revenue toward captive OEM update channels.
OEMs command the primary value pool; tier-1 manufacturers are gaining share fastest on integrated system contracts.
Vehicle Type:
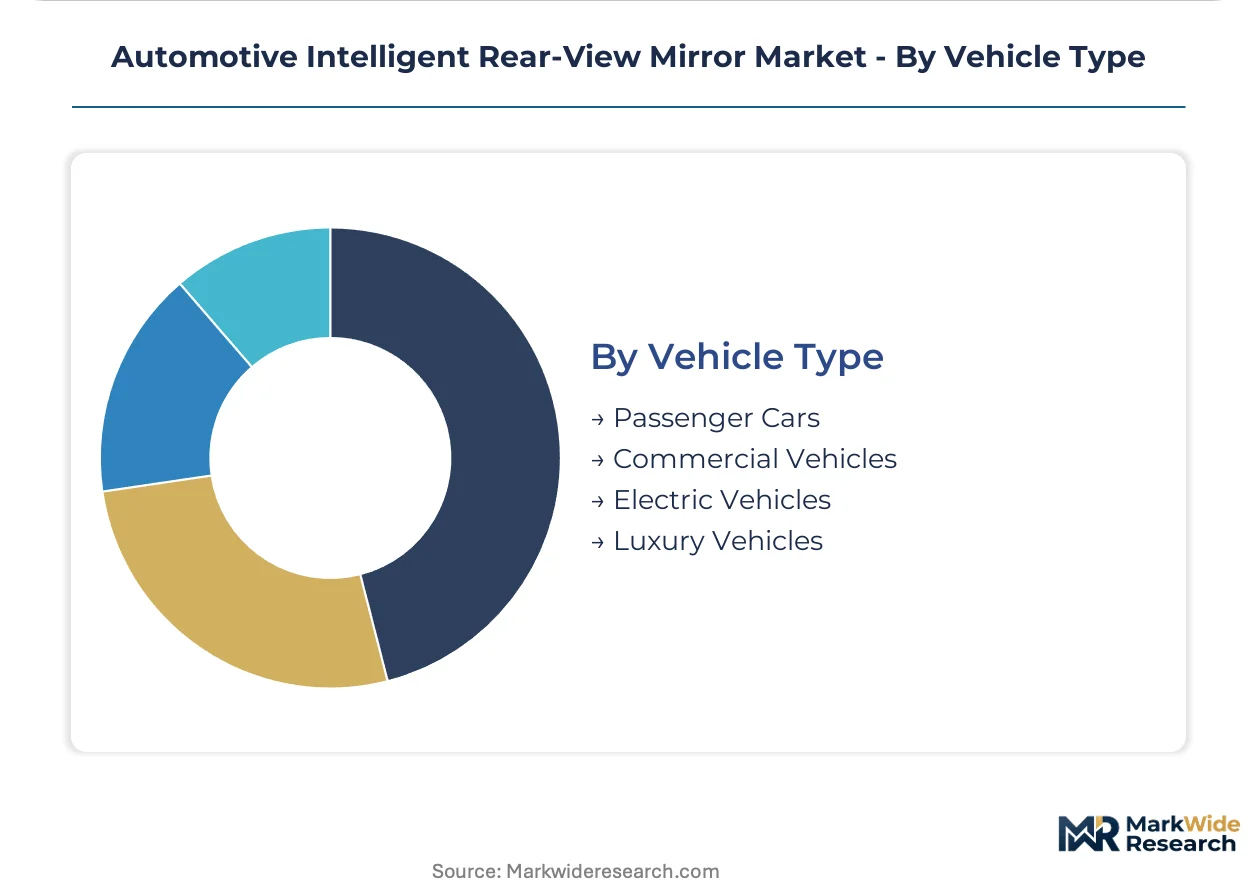
Homologation requirements and aerodynamic priorities segment demand by regulatory exposure and efficiency targets.
- Electric Vehicles:Range-sensitive platforms where mirror drag coefficient improvements yield measurable efficiency gains. Chinese and German manufacturers standardize intelligent mirrors across lineups.
- Commercial Vehicles:Heavy-duty trucks and buses with stringent blind-spot elimination mandates. Fleet procurement departments in North America and Europe consolidate specifications under centralized technical standards.
- Luxury Vehicles:Price-insensitive segments accepting premium electro-optical features for differentiation. OLED and augmented reality configurations concentrate here.
- Passenger Cars:Mass-market internal combustion platforms with cost-constrained specifications. Camera-based digital mirrors penetrate upper trim levels selectively.
Passenger cars retain volume leadership; electric vehicles show steepest expansion trajectory on aerodynamic imperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys intelligent rear-view mirrors primarily for aerodynamic efficiency on electric vehicle platforms, while Germany and the United States emphasize ADAS integration and regulatory compliance as the dominant adoption vectors.
China
Domestic EV manufacturers standardize camera-based digital mirrors across premium lineups to maximize range efficiency. MIIT-administered GB standards mandate rear visibility performance benchmarks that accelerate electro-optical system certification. Shanghai and Shenzhen anchor production clusters where BYD and NIO suppliers integrate mirror cameras with surround-view perception stacks.
Germany
Premium automakers specify OLED mirror displays for nighttime contrast performance in luxury segments. KBA enforces ECE R46 type-approval protocols that extend development cycles but ensure cross-border homologation acceptance. Bavaria concentrates R&D activity where Continental AG and Magna International anchor integrated sensor-to-display manufacturing.
United States
Fleet operators in long-haul trucking specify smart mirrors with embedded telematics for blind-spot liability reduction. NHTSA Federal Motor Vehicle Safety Standard No. 111 compels field-of-view equivalence certification for camera-based systems. Michigan and Tennessee host OEM technical centers where Gentex Corporation dominates electrochromic and digital mirror supply contracts.
Japan
Automotive tier-1 suppliers concentrate image sensor production for HDR camera modules feeding mirror systems. METI promotes connected vehicle standards that shape over-the-air update requirements for software-defined mirrors. Nagoya and Tokyo metropolitan areas house Murakami Corporation and Panasonic Corporation facilities serving domestic and export OEM programs.
South Korea
Display panel manufacturers scale automotive-grade OLED production for thin-form-factor mirror applications. MFDS-equivalent automotive safety frameworks align with international ISO 16505 benchmarks for camera-monitor system performance. Gyeonggi-do province clusters Samsung Display and LG Display operations supplying German and Chinese automakers.
Automotive Intelligent Rear-View Mirror Market Competitive Environment
Capability concentration sits with electro-optical specialists possessing image processing expertise; scale advantage sits with diversified tier-1 suppliers spanning multiple vehicle platforms. The vendor base separates into three strategic archetypes: integrated sensor-to-display system integrators, electrochromic technology incumbents pivoting to digital architectures, and display panel specialists entering automotive verticals. Competitive dynamics center on M&A activity consolidating camera module suppliers and strategic partnerships binding mirror integrators to OLED panel sources.
Among North American electro-optical specialists, Gentex Corporation anchors the premium OEM supply tier, while Magna International exemplifies the diversified tier-1 archetype with multi-continent manufacturing scale. Continental AG occupies a position bridging European regulatory expertise with integrated ADAS sensor fusion capabilities.
| Leading Market Players |
|---|
| Gentex Corporation |
| Magna International |
| Ficosa International |
| Murakami Corporation |
| Samvardhana Motherson Reflectec |
| Continental AG |
| Valeo |
| MEKRA Lang |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Japanese and South Korean HDR camera module suppliers anchor upstream concentration, directing margin capture toward integrated system integrators who bundle electro-optical components under single-tier contracts. OEM procurement teams leverage long-term offtake agreements to lock in display panel allocation, compressing spot-market participation to aftermarket retrofit channels.
Pricing Analysis
Long-term offtake contracts dominate OEM procurement, with annual price reviews tied to semiconductor input indices and display panel commodity cycles. Price differentiation separates ISO 16505-certified systems from uncertified aftermarket alternatives, while volume scale discounts concentrate among German and Chinese EV manufacturers with platform-standardization mandates. Cost compression in camera-based architectures intensifies as Korean panel manufacturers scale automotive OLED production. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, whereas luxury vehicle OEMs accept premium positioning for augmented reality overlay capabilities.
Supply Chain Analysis
Export controls on advanced image signal processors and display driver ICs limit technology flows from United States and Japanese suppliers to Chinese mirror system integrators. Manufacturing concentrates in China, Germany, and South Korea, with raw material dependencies spanning gallium nitride substrates, rare-earth phosphors for OLED emitters, and specialized optical glass for camera lenses. Single-source vulnerability concentrates in Japanese HDR sensor suppliers, exposing tier-1 integrators to geographic concentration risk. Distribution runs through captive OEM calibration channels rather than independent aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded software engineering talent pools for real-time video pipeline optimization and functional safety certification lag demand from autonomous driving programs, constraining supplier expansion velocity.
For Market Incumbents: Insulate margin pools by backward integration into image signal processor design and captive supply of HDR camera modules. Secure ECE R46 pre-certification for integrated sensor-to-display architectures before regulatory latency requirements tighten. Prioritize long-term offtake contracts with Korean OLED panel manufacturers to lock in thin-form-factor supply allocation. For New Entrants and Emerging Players: Pursue white-space positioning in Indian commercial vehicle segment where government safety mandates create first-mover advantages for local assembly partnerships. Target aftermarket retrofit demand for smart mirror overlays in North American long-haul trucking fleets seeking telematics integration without full platform redesign. Lead with subscription-based software activation models to capture recurring revenue from fielded vehicle populations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive electronics specialists possessing ECE R46 certification infrastructure but lacking OEM platform integration scale. Long-term viability hinges on sensor fusion convergence with surround-view ADAS stacks. Monitor NHTSA cybersecurity rulemaking for connected mirror systems as inflection indicator for software-defined valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces per-vehicle sensor counts by consolidating mirror camera feeds with surround-view perception stacks. |
| Software-Defined Vehicle Investment | Enables over-the-air feature activation generating recurring revenue from Gentex and Magna fielded populations. |
| Geographic Manufacturing Footprint | Local assembly partnerships in India and China satisfy MIIT and BIS homologation requirements for commercial vehicle segments. |
| Backward Integration into Image Processing | Captive ISP design reduces dependency on Japanese semiconductor allocation constraints. |
| Regulatory Pre-Certification Program | ECE R46 and NHTSA equivalence certification accelerates OEM platform integration timelines. |
Study Parameters
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement directors, aftermarket distributors, and dealership service managers anchored the qualitative base. Primary interviews combined with secondary validation from NHTSA Federal Motor Vehicle Safety Standard filings, ECE R46 type-approval databases, MIIT GB standard publications, and vehicle production registration data. Bottom-up segment sizing triangulated against top-down OEM procurement budget analysis.
Scenario-bracketing around semiconductor input volatility and regulatory latency requirement evolution shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle propulsion architecture, mirror product type, display technology tier, and regional production cluster. CAGRs derived from installed base growth rates and content-per-vehicle trajectory analysis, with electric vehicle aerodynamic efficiency targets and commercial fleet safety mandates as primary demand inputs.
Sensitivities concentrate around image sensor allocation constraints, ECE R46 homologation timeline extensions, and cybersecurity mandate implementation schedules. Forecasts reflect documented assumptions on OEM platform standardization velocity and OLED panel cost curves. Material shifts in NHTSA rear visibility equivalence testing protocols or export control expansion on display driver ICs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Automotive Air Suspension System Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Trunk Lid Panel Market
Automotive Interior & Exterior
Automotive Display Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Exterior Car Accessories Market