
 North America Automotive Upholstery Market | 2026-2036
North America Automotive Upholstery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Upholstery Market Analytics
Premium-grade interior specifications is rotating through North American assembly plants as OEMs chase higher trim mix on SUVs and light trucks. Lear Corp anchors large-scale seating programs with captive foam and frame operations across the region. Faurecia SE leverages its integrated interiors platform to compete on electrified vehicle architectures. Katzkin Leather Inc specializes in aftermarket leather conversion kits, sustaining margin-rich positions outside OEM supply chains.
Automotive upholstery encompasses the engineered textile, leather, synthetic, and foam materials applied to vehicle interior surfaces including seats, door panels, headliners, and floor coverings, typically specified to meet flammability, abrasion, and VOC emission standards while providing occupant comfort and cabin aesthetics. Leather commands the highest material-tier pricing in full-size truck and luxury SUV configurations, while fabric maintains volume leadership in mid-market sedans and compact crossovers. Interior Seating absorbs the dominant share of material input value across all vehicle types, with Door Panels representing the fastest-growing application segment as ambient lighting and haptic interfaces expand surface complexity.
NHTSA flammability standards, EPA volatile organic compound regulations, and California Air Resources Board material restrictions collectively dictate foam formulation, adhesive selection, and textile finishing processes across the supply base. The USMCA rules of origin framework shapes sourcing decisions for Mexican assembly plants serving US and Canadian markets. Stakeholders must monitor evolving California chemical disclosure requirements and pending federal recycled-content mandates to anticipate specification shifts before contract renewals.
Market Dynamics
Full-size truck and luxury SUV trim escalation is compressing material specification cycles across North American assembly plants, forcing suppliers to synchronize foam and textile development with 18-month vehicle refresh timelines rather than traditional 5-year platform cycles.
Growth Catalysts
- EPA VOC emission limits:Low-VOC foam formulations are unlocking premium cabin air quality certifications that OEMs now feature in marketing materials.
- Southeast US manufacturing corridor:Proximity to BMW, Mercedes-Benz, and Volkswagen assembly plants is pulling specialized leather finishing operations into Alabama and South Carolina.
- Light-truck interior refresh rates:Ford F-150 and Ram 1500 model-year updates are accelerating aftermarket leather kit demand through Katzkin's dealer network.
Market Restraints
- Petrochemical input volatility:Polyurethane foam precursors track crude oil indices, compressing margin visibility for seating suppliers on fixed-price OEM contracts.
- Monterrey-Tijuana supplier concentration:Mexican border assembly zones concentrate 60% of North American seat frame production, exposing programs to cross-border logistics friction.
- California Air Resources Board chemical disclosure:Proposition 65 litigation risk is extending compliance timelines for new textile chemistries by 8-14 months.
Strategic Opportunities
- USMCA regional value content rules:Foam-in-place seating operations in Mexico can qualify for preferential tariff treatment while serving Detroit Three just-in-sequence requirements.
- Aftermarket digital configurators:Web-based interior visualization tools are shortening leather kit sales cycles from 3 weeks to 72 hours for independent dealers.
- Recycled-content mandates:Pending federal procurement standards for fleet vehicles are creating specification pull for post-industrial textile blends in government SUV orders.
Industry Challenges
- Automotive color-matching precision:Batch-to-batch leather dye consistency requires spectrophotometer calibration expertise that tanneries struggle to staff at scale.
- Dual-chemistry foam certification:NHTSA flammability testing protocols must validate both traditional and bio-based formulations, doubling validation costs for material introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Upholstery Market |
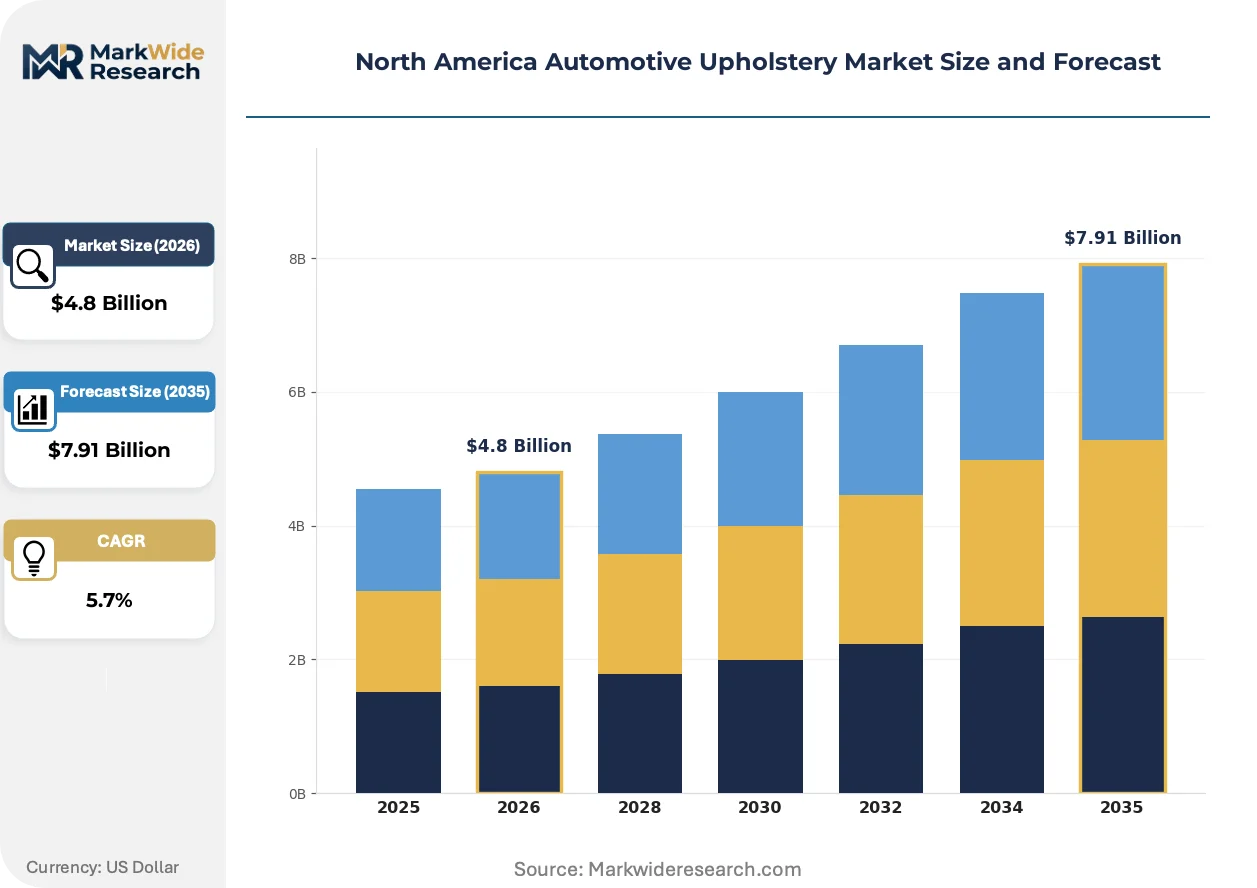
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Fabric, Vinyl, Suede End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Vehicle Type: SUV, Sedan, Hatchback, Truck Application: Interior Seating, Door Panels, Headliners, Carpets |
| Companies Covered | Faurecia SE, Katzkin Leather Inc, Lear Corp, The Woodbridge Group, CMI Enterprise, Adient Plc, Seiren Co Ltd, IMS Nonwoven, Toyota Boshoku Corp, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Upholstery Market Evolving Landscape
Material science convergence with electrification architectures is redefining upholstery weight targets and thermal management requirements across North American vehicle programs.
Hot-melt adhesive lamination is displacing solvent-based bonding in seat assembly operations. Tier 1 seating suppliers at Ford and GM truck plants adopted the shift during 2022-2024 platform updates. The technology is displacing legacy spray-booth configurations and their associated VOC abatement capital requirements across the supply base.
NHTSA's updated Federal Motor Vehicle Safety Standard 302 flammability testing protocol is compressing foam formulation development timelines. Suppliers must now validate ignition resistance across accelerated aging conditions that simulate 10-year vehicle life. Full-size SUV and light-truck seating programs face the steepest compliance burden due to larger surface areas and stricter performance thresholds.
Fleet buyers and rental operators are consolidating upholstery specification authority at corporate procurement centers rather than regional fleet managers. Direct OEM relationships are replacing distributor-mediated purchasing for national accounts covering 500+ vehicle annual acquisitions. The concentration is most visible in Texas and Florida light-truck fleet registrations where single-source leather specifications now cover mixed-brand orders.
North America Automotive Upholstery Market Segmentation
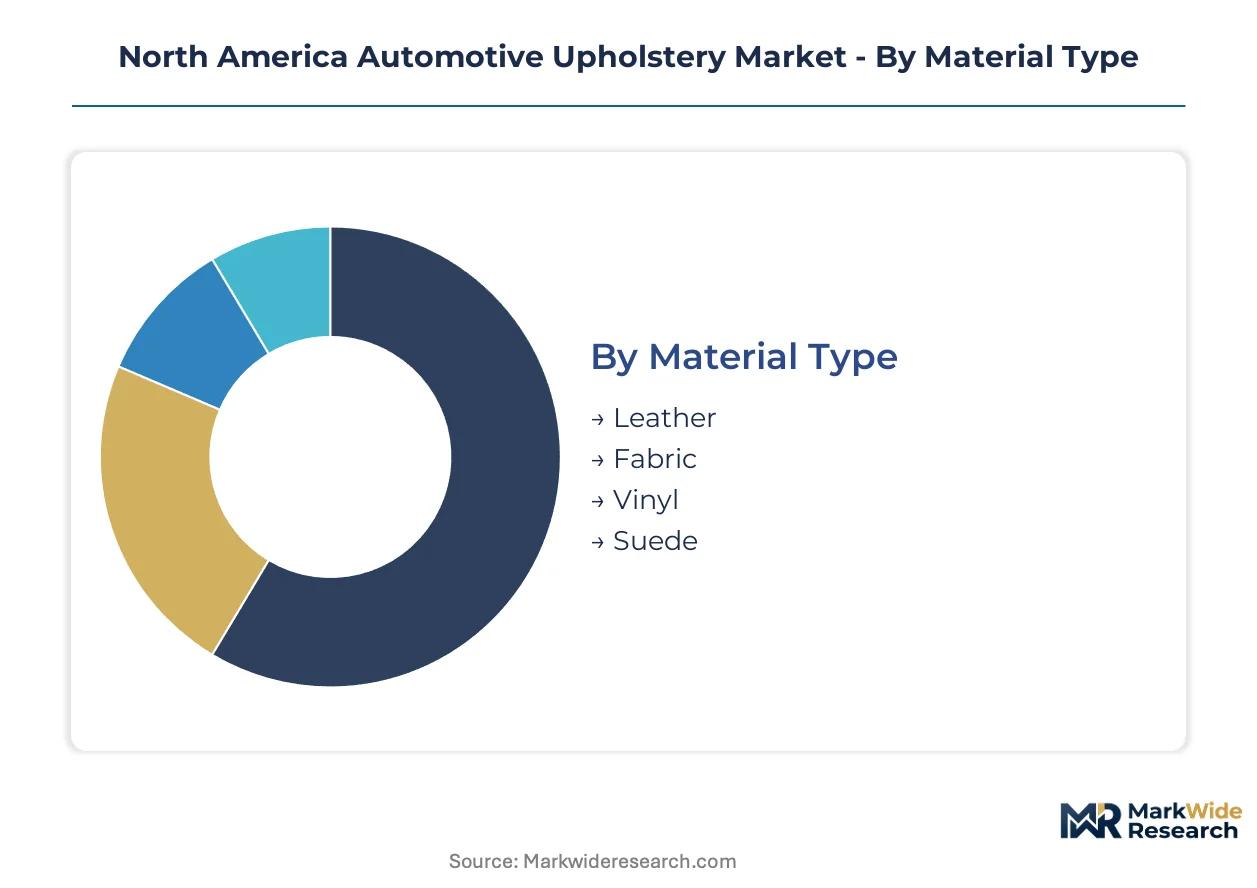
Material specification cycles in North American automotive upholstery compress as OEMs chase trim escalation on light trucks and SUVs. Segmentation reveals where regulatory pressure, supply concentration, and margin structure create divergent competitive dynamics across the value chain.
Material Type:
NHTSA flammability standards and EPA VOC limits create tiered compliance burdens that reshape material selection economics across vehicle programs.
- Leather:Full-grain and corrected-grain hides command specification priority in luxury SUV and full-size truck interiors. Alabama and South Carolina tanning operations now serve BMW Spartanburg and Mercedes-Benz Tuscaloosa assembly plants with finished leather meeting 10-year durability warranties.
- Fabric:Woven polyester and nylon blends dominate mid-market sedan and compact crossover volumes where cost-per-seat targets constrain material spend. Southeast US textile mills supply Ford Kentucky Truck and GM Arlington Assembly with engineered fabrics certified to FMVSS 302 ignition resistance protocols.
- Vinyl:PVC-based synthetic leather substitutes for genuine leather in fleet vehicle specifications where procurement centers prioritize unit cost over tactile premium.
- Suede:Alcantara and microfiber variants accent headliner and door panel surfaces in performance trim packages, limiting volume exposure to niche SUV configurations.
Fabric handles the majority of throughput; leather is the fastest mover on share as truck trim escalation accelerates.
End User:
Procurement authority consolidation is reshaping channel economics, with direct OEM relationships displacing intermediary purchasing for large-volume accounts.
- OEMs:Detroit Three and transplant assemblers specify upholstery through captive seating divisions or direct Tier-1 contracts, locking in foam-in-place operations synchronized to just-in-sequence delivery windows.
- Aftermarket Providers:Katzkin Leather and regional conversion specialists supply dealer-channel leather kits for F-150 and Ram 1500 owners seeking trim upgrades outside factory specifications.
- Tier-1 Suppliers:Lear Corp and Faurecia SE integrate frame, foam, and cover operations to capture value across the seating stack while meeting USMCA regional content thresholds.
- Dealerships:Independent franchised outlets represent the most fragmented channel, sourcing conversion materials through distributor networks with 3-week traditional sales cycles compressing to 72 hours via digital configurators.
OEMs handle the majority of throughput; aftermarket providers are expanding most quickly as truck refresh rates accelerate kit demand.
Vehicle Type:
Platform architecture and interior surface area dictate material input intensity, with larger vehicle formats consuming disproportionate upholstery value per unit.
- SUV:Three-row configurations maximize seating surface area while premium trim penetration concentrates in full-size and luxury segments where leather specification rates exceed industry averages.
- Truck:Crew cab and luxury trim packages on Ford F-150, Ram 1500, and GM Silverado drive the steepest material escalation in the North American market.
- Sedan:Declining segment volume concentrates remaining demand in mid-market fleet configurations where fabric maintains cost leadership.
- Hatchback:Compact urban formats limit interior surface area and trim complexity, constraining upholstery value per vehicle to the lowest tier across passenger categories.
Truck handles the majority of throughput; SUV is climbing the fastest as consumer preference shifts from sedans to utility formats.
Application:
Surface complexity expansion in non-seating zones is redistributing engineering resources and supplier development priorities.
- Interior Seating:Seat covers, foam cushions, and trim assemblies absorb the dominant share of upholstery input value across all vehicle types, with eight-way power configurations multiplying material specification points per unit.
- Door Panels:Ambient lighting integration, haptic control surfaces, and acoustic lamination layers are expanding surface engineering requirements faster than any other application zone.
- Headliners:Fabric-wrapped and suede-accented ceiling treatments now extend into C-pillar and sun visor surfaces on premium SUV configurations.
- Carpets:Nylon and polypropylene floor coverings face margin compression as OEMs consolidate specification authority and reduce grade differentiation across vehicle tiers.
Interior Seating handles the majority of throughput; Door Panels are gaining share fastest as surface complexity multiplies engineering requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seat frame and foam operations cluster along the US-Mexico manufacturing corridor, with just-in-sequence delivery networks radiating from Detroit, Monterrey, and the US Southeast. NHTSA safety standards and EPA emissions mandates govern material specifications across all three markets, while USMCA rules of origin shape cross-border sourcing decisions.
United States
Ford Kentucky Truck and GM Arlington Assembly drive leather and fabric demand for full-size truck and SUV programs. NHTSA FMVSS 302 flammability protocols require accelerated aging validation for all foam formulations. Alabama and South Carolina host specialized leather finishing operations serving BMW Spartanburg and Mercedes-Benz Tuscaloosa plants.
Mexico
Monterrey and Tijuana concentrate 60% of North American seat frame production for Detroit Three just-in-sequence requirements. USMCA regional value content rules qualify foam-in-place seating operations for preferential tariff treatment. Mexican border assembly zones face cross-border logistics friction from customs processing and rail capacity constraints.
Canada
Ontario-based vehicle assembly pulls upholstery materials through integrated Tier-1 supply chains serving Windsor and Oakville operations. Environment and Climate Change Canada aligns VOC emission standards with EPA benchmarks to maintain cross-border material certification reciprocity. Toronto-area logistics hubs coordinate finished seat deliveries to US Midwest assembly plants.
North America Automotive Upholstery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American automotive upholstery supply base. Integrated seating divisions of multinational Tier-1 suppliers dominate OEM just-in-sequence contracts through captive foam and frame operations. Specialized aftermarket converters occupy margin-rich positions outside factory supply chains through dealer-channel distribution. The competitive arena features two dominant moves: backward integration into foam formulation to secure margin control, and geographic co-location with transplant assembly plants to compress logistics costs.
Within the integrated seating tier, Lear Corp and Faurecia SE exemplify the multinational archetype with captive operations spanning frame, foam, and cover integration. Katzkin Leather Inc occupies a specialist position in aftermarket leather conversion kits, sustaining dealer-channel relationships independent of OEM supply chains. These three entities represent the structural split between factory-integrated and aftermarket-focused competitive models in the regional market.
| Leading Market Players |
|---|
| Faurecia SE |
| Katzkin Leather Inc |
| Lear Corp |
| The Woodbridge Group |
| CMI Enterprise |
| Adient Plc |
| Seiren Co Ltd |
| IMS Nonwoven |
| Toyota Boshoku Corp |
| Others |
Value Network & Pricing Analysis
Hot-melt adhesive lamination displacing solvent-based bonding simultaneously pulls finishing operations toward US Southeast assembly corridors and compresses legacy spray-booth capital recovery timelines across supplier balance sheets. This substitution dynamic concentrates pricing power among early adopters while forcing laggards into accelerated depreciation cycles on stranded VOC abatement assets.
Pricing Analysis
NHTSA FMVSS 302 flammability protocols dictate the pricing tier structure across foam and textile specifications. Three-tier pricing structure across premium, standard, and economy levels separates full-grain leather warranties from corrected-grain fleet specifications and fabric-dominated value trims. Cost compression in mid-market fabric seating intensifies because polyurethane precursor volatility outpaces contract renegotiation windows. Fleet procurement centers exhibit highest price sensitivity; luxury SUV program managers prioritize certification tier over unit cost.
Supply Chain Analysis
Monterrey-Tijuana border crossings underwrite just-in-sequence delivery reliability for Detroit Three truck programs. Mexico, the United States, and Canada anchor regional value content compliance, with foam-in-place operations drawing from US petrochemical feedstocks and South Carolina tanning outputs. Single-source vulnerability concentrates in cross-border rail capacity constraints. Distribution runs through integrated Tier-1 seating divisions synchronized to OEM assembly windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America automotive upholstery market operates as a defensive-moat arena where USMCA regulatory entrenchment and just-in-sequence switching costs protect incumbent positions against distant challengers.
For Market Incumbents: Consolidate foam formulation capabilities through backward integration into polyurethane precursor operations, securing margin control against petrochemical volatility. Lock in Alabama and South Carolina leather finishing capacity to anchor BMW and Mercedes-Benz transplant relationships. NHTSA accelerated aging validation requirements create compliance barriers that favor scaled players with dedicated testing infrastructure. For New Entrants and Emerging Players: Anchor in aftermarket digital configurators where 72-hour sales cycles displace three-week distributor lead times for independent dealership channels. Target Katzkin's leather kit model for unmet demand in Ram 1500 and Ford F-150 owner upgrade segments. Pursue direct-to-dealer partnerships bypassing legacy distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated seating platforms with captive foam and frame operations. Long-term viability hinges on USMCA regional content compliance and electrification thermal management adaptation. Watch for California Air Resources Board chemical disclosure rulings as inflection indicators for textile chemistry validation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Formulation | Captive polyurethane precursor supply insulates Lear and Faurecia from crude-linked input volatility. |
| USMCA-Compliant Mexican Capacity Expansion | Monterrey foam-in-place operations qualify for preferential tariff treatment on Detroit Three programs. |
| Hot-Melt Adhesive Platform Conversion | Ford and GM truck plant adoption during 2022-2024 updates displaced legacy solvent-based bonding infrastructure. |
| Aftermarket Digital Configurator Deployment | Katzkin's web-based visualization tools compressed independent dealer sales cycles from weeks to days. |
| Accelerated Aging Validation Investment | NHTSA FMVSS 302 protocol compliance requires 10-year simulation testing that favors scaled testing facilities. |
Research Methodology
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers provided ongoing calibration across primary interview cycles. Secondary validation drew from vehicle production databases, IHS Markit registration data, USMCA customs filings, and EPA VOC emission compliance records. Bottom-up segment modeling and top-down market sizing underwent iterative reconciliation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from segment-level trajectory analysis incorporating leather specification mix shifts and truck refresh rate acceleration.
Underlying assumptions cover USMCA stability, NHTSA flammability protocol continuity, and petrochemical input correlation persistence, with deviation risk concentrated in California chemical disclosure litigation and cross-border logistics friction. Practitioners should keep alternative scenarios live as electrification thermal requirements and recycled-content mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
United Kingdom Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Door Sills Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
China Automotive Seats Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Automotive Ambient Lighting Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Europe Automotive Seat Market