
 Global Urology Surgical Instruments Market | 2026-2036
Global Urology Surgical Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urology Surgical Instruments Market Foresight
Polymer composites are replacing stainless steel in disposable ureteroscopes and is restructuring cost-per-procedure economics across outpatient settings. Boston Scientific Corporation leverages vertical integration in polymer sourcing to protect margin pools on single-use devices. Olympus Corporation anchors its competitive position through captive manufacturing of optical imaging stacks for flexible endoscopes. KARL STORZ SE & Co. KG specializes in rigid endoscope architectures that dominate European hospital procurement channels.
Urology surgical instruments comprise precision-engineered tools designed for diagnostic and therapeutic manipulation of the urinary tract and male reproductive system, typically manufactured from medical-grade stainless steel, titanium alloys, or polymer composites with tolerances measured in micrometers for minimally invasive access. These instruments enable visualization, tissue dissection, stone fragmentation, and stent placement through natural orifices or laparoscopic ports. Endoscopes command the largest revenue share due to their optical complexity and replacement cycles, while robotic-assisted technology segments are expanding fastest as hospitals amortize capital-intensive da Vinci and competing platform installations. Urethral catheters represent a mature, high-volume category where margin compression from commodity competition is offset by antimicrobial coating premiums.
The FDA enforces 510(k) clearance pathways and quality system regulations that shape product development timelines and clinical evidence requirements for urology device manufacturers entering the United States. The EU Medical Device Regulation and CE marking framework impose post-market surveillance obligations and unique device identification mandates that filter smaller competitors from European distribution. Japan's PMDA maintains stringent biological safety testing protocols that extend registration timelines but reward compliant entrants with stable reimbursement access. Stakeholders must monitor how divergent sterilization validation requirements across these jurisdictions influence make-versus-buy decisions for instrument portfolios.
Market Dynamics
Robotic-assisted surgical platforms are compressing replacement cycles for rigid endoscopes while simultaneously elevating capital expenditure thresholds for hospital procurement committees. This dual pressure is restructuring vendor relationships toward long-term service bundling rather than transactional instrument sales.
Growth Catalysts
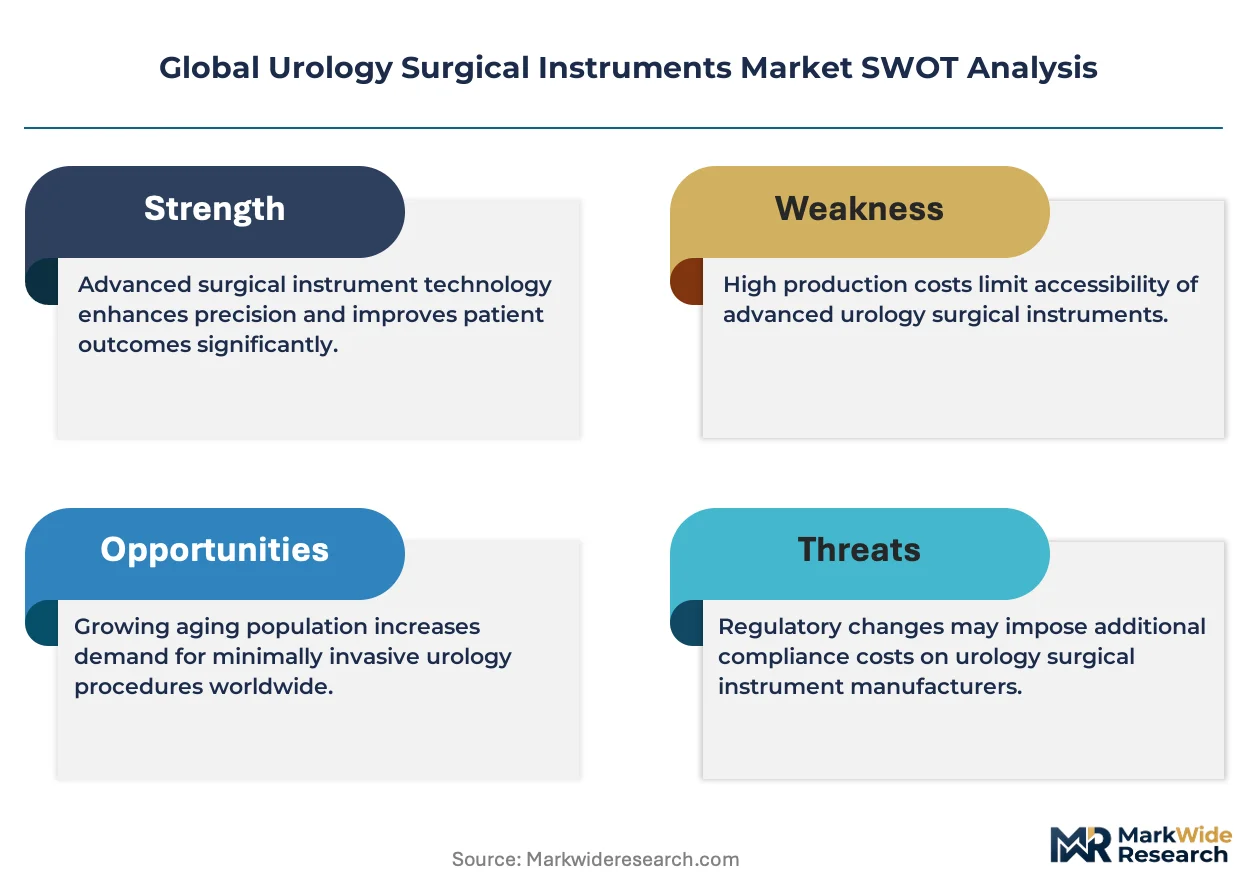
- EU Medical Device Regulation traceability mandates:Reusable instrument sterilization protocols are tightening across German and French hospital networks, accelerating replacement demand for compliant instrument sets.
- Polymer composite single-use ureteroscopes:Outpatient lithotripsy centers in the United States are eliminating reprocessing costs through disposable architectures.
- Japan's PMDA reimbursement stability:Predictable device pricing frameworks reward manufacturers completing extended biological safety testing protocols.
Market Restraints
- Titanium alloy supply concentration:Aerospace and medical grade titanium sourcing clusters in limited Japanese and Chinese smelter networks create input cost volatility.
- 510(k) clearance pathway friction:FDA quality system regulations extend product development timelines for novel instrument geometries entering United States distribution.
- Optical imaging stack technical limitation:Miniaturized CMOS sensor yield rates constrain flexible endoscope production scaling.
Strategic Opportunities
- Underpenetrated ambulatory surgery centers:United States outpatient urology clinics lack robotic-assisted platform density present in academic medical centers.
- CE marking regulatory tailwind:Post-market surveillance obligations filter smaller competitors, consolidating European distribution channels for compliant manufacturers.
- AI-enhanced imaging convergence:Machine learning tissue recognition algorithms are integrating with optical stacks to reduce operative time.
Industry Challenges
- Robotic platform integration complexity:Instrument compatibility engineering with legacy da Vinci installations demands specialized firmware and mechanical adaptation expertise.
- ISO 13485 certification timeline compression:Accelerated audit schedules strain quality management system documentation resources across mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urology Surgical Instruments Market |
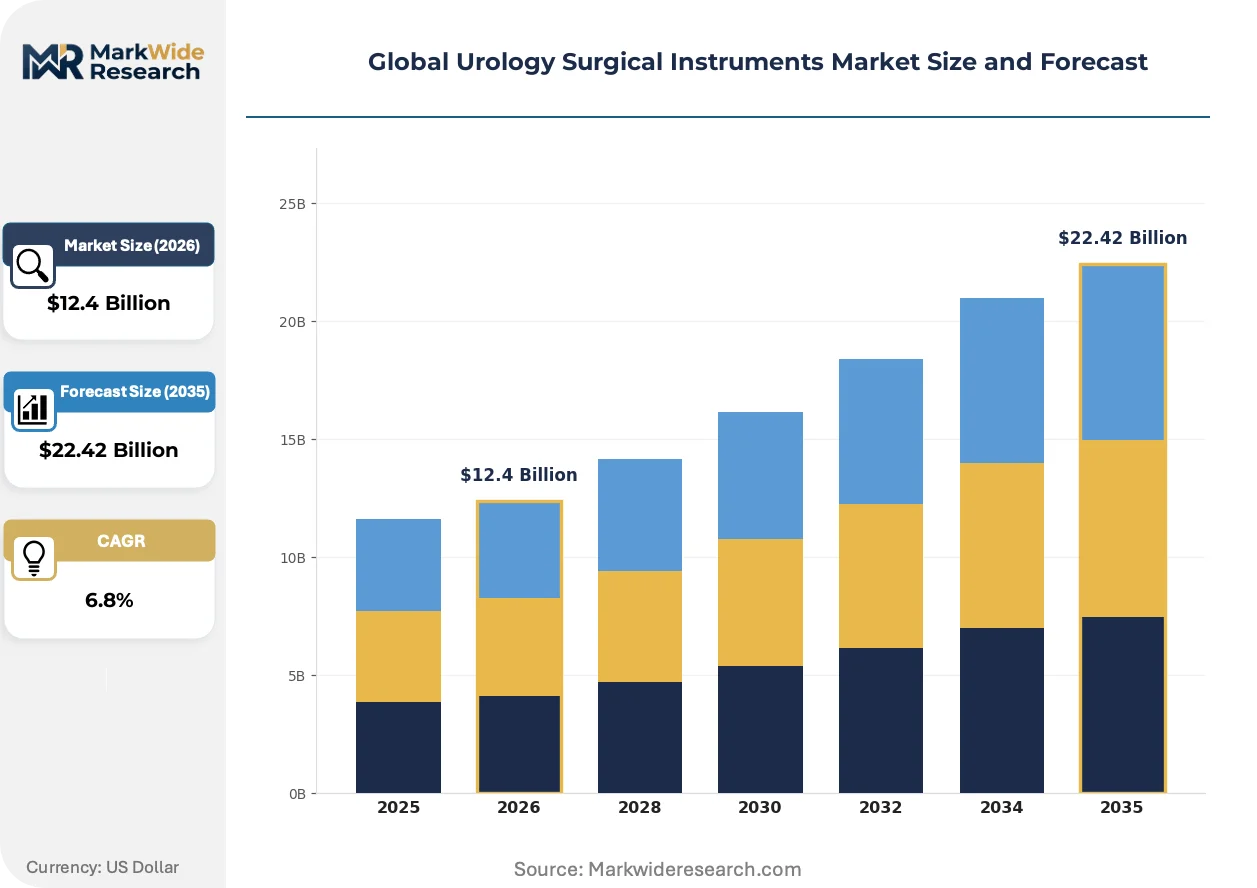
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Forceps, Scalpels, Retractors, Urethral Catheters, Dilators Application: Lithotripsy, Prostate Surgery, Bladder Reconstruction, Kidney Stone Removal, Ureteral Stenting, Tumor Resection End User: Hospitals, Ambulatory Surgery Centers, Specialty Clinics, Diagnostic Laboratories Technology: Laser-Assisted, Robotic-Assisted, Conventional, Ultrasound-Guided, Fluoroscopic, Optical Imaging |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Olympus Corporation, KARL STORZ SE & Co. KG, Cook Medical LLC, Richard Wolf GmbH, Stryker Corporation, Teleflex Incorporated, Coloplast Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urology Surgical Instruments Market Shifts & Advancements
Disposable polymer architectures are disrupting stainless steel instrument economics while regulatory traceability requirements reshape manufacturing footprints. Three convergent developments are compressing traditional competitive advantages.
Single-use flexible ureteroscopes constructed from medical-grade polymer composites are expanding into lithotripsy and upper tract urothelial carcinoma surveillance procedures. United States ambulatory surgery centers are adopting these devices to eliminate reprocessing labor and sterilization validation costs. This shift is expanding into cost-per-procedure contracting models that bypass capital equipment procurement committees entirely.
Japan's PMDA maintains stringent biological safety testing protocols that extend registration timelines but reward compliant entrants with stable reimbursement access. Manufacturers completing these extended validation cycles gain preferential positioning in Japanese hospital tender processes. Flexible endoscope categories face the most significant compliance burden under these requirements.
Hospital procurement committees are consolidating vendor relationships through multi-year instrument service agreements that bundle maintenance, replacement, and training. Academic medical centers in Germany and the United States are displacing transactional purchasing with total-cost-of-ownership frameworks. This behavioral shift is most visible in robotic-assisted platform ecosystems where instrument obsolescence risk shifts to manufacturers.
Global Urology Surgical Instruments Market Segmentation
Procurement committees evaluate urology instrument portfolios across multiple axes simultaneously. Product durability, reimbursement compatibility, and capital amortization schedules drive divergent sourcing strategies across hospital networks and outpatient chains.
Product Type:
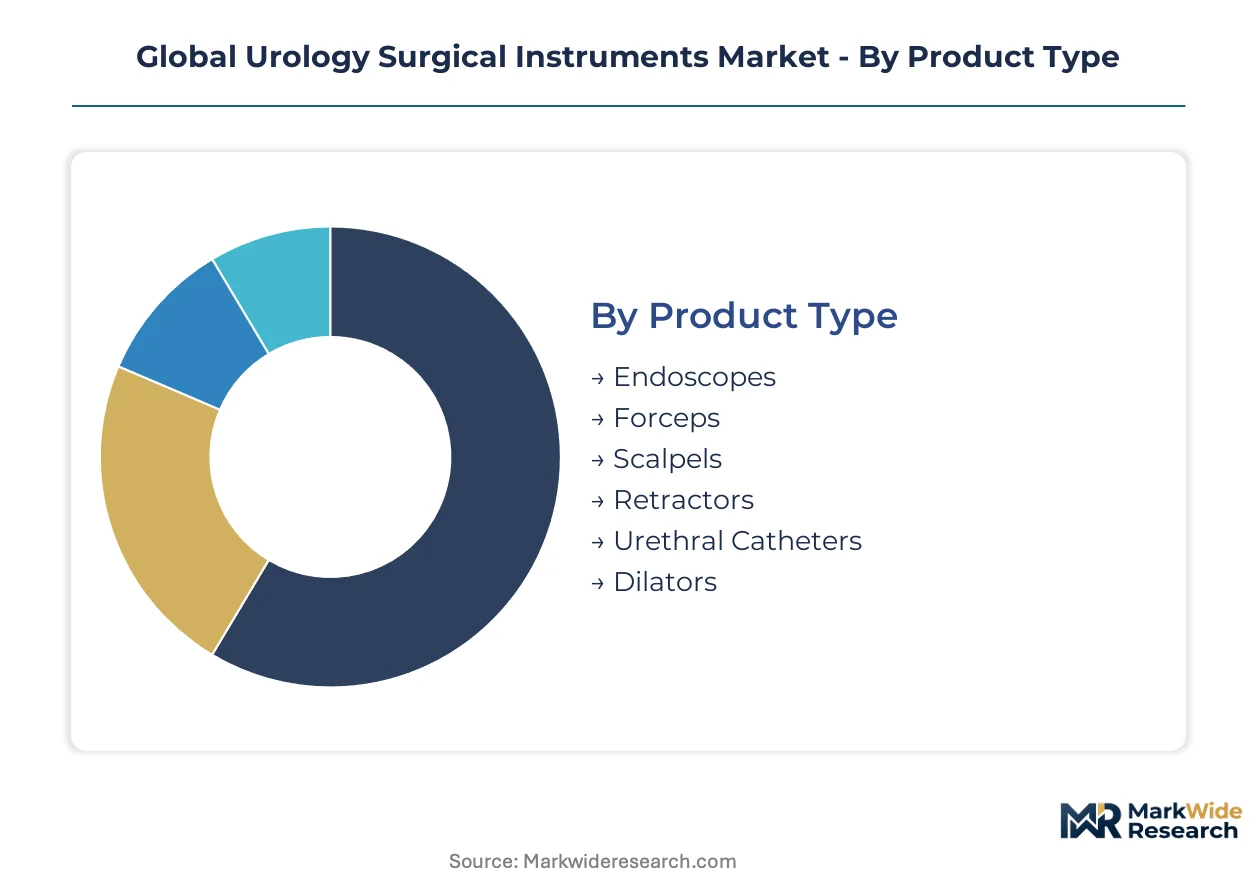
Replacement cycle economics dominate buyer calculus, with optical complexity and sterilization tolerance dictating budget allocation across surgical departments.
- Endoscopes:Flexible and rigid optical architectures incorporate medical-grade glass fiber bundles or CMOS sensor arrays with micrometer-scale alignment tolerances. German university hospitals and Japanese academic medical centers concentrate demand for 4K and 3D visualization capabilities as they expand robotic-assisted surgical programs.
- Urethral Catheters:Polymer extrusions in latex, silicone, or hydrophilic-coated configurations serve high-volume indwelling and intermittent drainage applications. United States long-term care facilities and outpatient clinics drive antimicrobial-coated premium variants to reduce catheter-associated urinary tract infection liability.
- Forceps:Biopsy and grasping instruments with ergonomic handle geometries and disposable jaw inserts.
- Scalpels:Precision cutting instruments with safety-engineered retractable mechanisms for open urological procedures.
- Retractors:Self-retaining and handheld designs enabling surgical field exposure across prostate and bladder interventions.
- Dilators:Graduated caliber instruments for urethral and tract dilation in stricture management.
Volume sits with Urethral Catheters; growth tilts toward Endoscopes.
Application:
Procedure reimbursement rates and operative time compression determine technology adoption velocity across clinical settings.
- Lithotripsy:Stone fragmentation procedures leverage intracorporeal pneumatic, ultrasonic, or laser energy delivery through minimally invasive access channels. United States ambulatory surgery centers are displacing hospital-based procedures as disposable ureteroscope economics eliminate reprocessing infrastructure requirements.
- Prostate Surgery:Transurethral resection and robotic-assisted radical prostatectomy demand specialized electrosurgical loops and articulating instruments. German hospital networks concentrate procurement of bipolar resection systems under EU Medical Device Regulation traceability mandates.
- Bladder Reconstruction:Augmentation cystoplasty and urinary diversion procedures requiring bowel anastomosis instrumentation.
- Kidney Stone Removal:Percutaneous nephrolithotomy access tracts and nephroscope configurations for complex staghorn calculi.
- Ureteral Stenting:Double-J and externalized stent placement for hydronephrosis decompression.
- Tumor Resection:Transurethral and laparoscopic approaches to urothelial carcinoma management.
Procedure volume clusters in Lithotripsy; steepest expansion trajectory belongs to Prostate Surgery.
End User:
Capital equipment access and sterile processing capacity create sharp segmentation in purchasing authority and contract structure.
- Hospitals:Academic and community institutions with centralized sterile processing departments and robotic platform installations. United States and German hospital systems amortize da Vinci and competing platform capital through multi-year instrument service agreements that bundle maintenance and replacement cycles.
- Ambulatory Surgery Centers:Outpatient facilities eliminating reprocessing costs through single-use instrument adoption. United States lithotripsy and cystoscopy centers are expanding fastest as payor migration favors site-of-service arbitrage.
- Specialty Clinics:Urology-focused practices with limited sterile processing infrastructure favoring disposable instrument economics.
- Diagnostic Laboratories:Cytology and pathology units supporting urological malignancy screening with biopsy acquisition tools.
Revenue concentration remains with Hospitals; share gains flow to Ambulatory Surgery Centers.
Technology:
Platform compatibility and clinical outcome differentiation drive capital allocation and training investment across surgical departments.
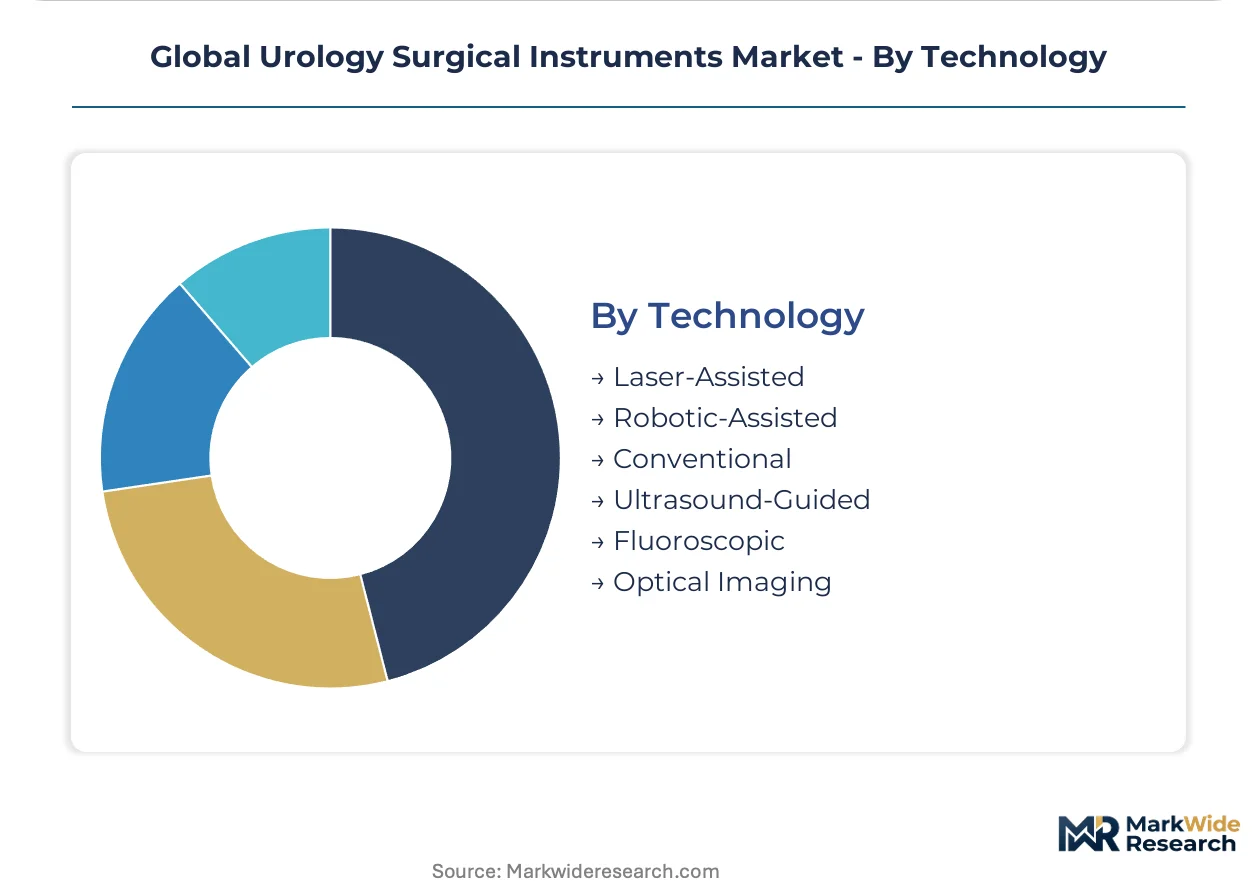
- Robotic-Assisted:Telemanipulation platforms with wristed instrument articulation and tremor filtration enabling single-port and reduced-access procedures. United States academic medical centers and Japanese tertiary hospitals anchor installed base expansion as Intuitive Surgical and competing vendors extend indication approvals.
- Laser-Assisted:Holmium and thulium fiber laser systems for stone fragmentation and soft tissue ablation with minimized thermal spread. German outpatient clinics concentrate adoption of portable laser units for office-based lithotripsy.
- Conventional:Manual and electromechanical instruments without energy integration or computer assistance.
- Ultrasound-Guided:Real-time imaging for percutaneous access and biopsy targeting in renal interventions.
- Fluoroscopic:X-ray based guidance for endourological navigation and stent placement verification.
- Optical Imaging:White light, narrow band, and photodynamic diagnosis for mucosal lesion detection.
Installed base dominance belongs to Conventional platforms; technology investment is climbing the fastest in Robotic-Assisted systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical device special economic zones in Costa Rica and Malaysia concentrate sterile instrument manufacturing for North American and Asian hospital networks respectively.
United States
Academic medical centers in Boston and Houston scale robotic-assisted surgical programs while ambulatory surgery centers in Florida and Arizona eliminate reprocessing costs through single-use polymer instruments. FDA 510(k) clearance pathways shape product development timelines for manufacturers entering distribution. The Minneapolis medical technology corridor anchors precision instrument fabrication for flexible endoscope components.
Germany
University hospitals in Munich and Berlin concentrate procurement of 4K visualization systems under EU Medical Device Regulation traceability mandates. The Tuttlingen surgical instrument cluster maintains rigid endoscope manufacturing dominance through captive optical engineering capabilities. Baden-Württemberg's Mittelstand fabricators supply specialized forceps and retractors across European hospital networks.
Japan
Tertiary hospitals in Tokyo and Osaka expand installed bases of telemanipulation platforms as PMDA reimbursement stability rewards extended biological safety testing compliance. The Nagoya medical device corridor concentrates CMOS sensor integration for flexible endoscope production. Kobe's polymer processing specialists supply disposable ureteroscope architectures for domestic lithotripsy chains.
China
Provincial hospital networks in Shanghai and Guangzhou accelerate procurement of domestically manufactured rigid endoscopes under national medical device localization policies. NMPA registration pathways filter foreign competitors while rewarding joint-venture manufacturers with accelerated approval timelines. Suzhou's medical device industrial park concentrates polymer extrusion capabilities for catheter production.
India
Corporate hospital chains in Delhi and Mumbai expand minimally invasive urology programs while government medical colleges in Chennai and Hyderabad drive volume procurement of conventional instruments. CDSCO medical device rules impose quality system requirements that filter smaller domestic manufacturers. The Ahmedabad surgical goods cluster supplies cost-optimized retractors and dilators for export markets.
Global Urology Surgical Instruments Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with optical complexity favoring integrated producers and commodity categories fragmenting toward regional fabricators. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with captive distribution, specialized endoscope manufacturers with optical engineering depth, and regional instrument fabricators serving price-sensitive procurement channels. Competitive dynamics center on multi-year service bundling agreements and backward integration into polymer supply chains.
Among diversified medical technology conglomerates, Medtronic plc and Stryker Corporation exemplify scale-driven positioning across capital equipment and disposable instrument portfolios. Boston Scientific Corporation anchors the specialized disposable architecture segment through upstream control of polymer sourcing. Olympus Corporation and KARL STORZ SE & Co. KG occupy differentiated positions in optical imaging systems, with the former representing flexible endoscope capabilities and the latter exemplifying rigid instrument engineering. Richard Wolf GmbH and Cook Medical LLC sit within the mid-tier specialized fabricator category serving European and North American hospital procurement networks respectively.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Olympus Corporation |
| KARL STORZ SE & Co. KG |
| Cook Medical LLC |
| Richard Wolf GmbH |
| Stryker Corporation |
| Teleflex Incorporated |
| Coloplast Group |
| Others |
Supply & Pricing Matrix
EU Medical Device Regulation sterilization traceability mandates gate qualified supply access and premium-tier pricing for compliant instrument sets, compressing margins for manufacturers lacking validated reprocessing documentation while rewarding certified vendors with hospital procurement preference.
Pricing Analysis
Lead-time-driven pricing stratification separates emergency spot orders commanding premium multiples from contracted scheduled deliveries with volume discounts. Three-tier pricing structure across premium ISO-certified, standard CE-marked, and economy non-traceable tiers reflects sterilization validation depth and optical resolution specifications. Pricing pressure stems from ambulatory surgery centers adopting disposable polymer architectures that bypass capital committees entirely. Academic medical centers exhibit lowest price sensitivity due to bundled service agreements, while independent specialty clinics face acute margin compression.
Supply Chain Analysis
Domestic-content mandates in China's NMPA registration pathways and India's PLI scheme for medical devices are reshaping sourcing toward joint-venture manufacturing and localized polymer extrusion. Titanium alloy feedstock concentrates in Japanese and Chinese smelter networks; optical glass fiber bundles draw from German and Japanese specialty manufacturers; polymer resins feed from South Korean and Chinese petrochemical complexes. Single-source vulnerability in CMOS sensor arrays for flexible endoscopes creates procurement risk. Distribution runs through hospital procurement committees and group purchasing organizations with multi-year contract lock-in.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Optical imaging stack miniaturization yields represent the binding capacity constraint propping pricing for qualified flexible endoscope supply, creating durable margin pools for manufacturers with captive sensor integration capabilities.
For Market Incumbents: Anchor market position through backward integration into polymer resin supply chains and captive CMOS sensor fabrication for flexible endoscope lines. Defend against single-use disposables by bundling reprocessing validation services with instrument replacement cycles under total-cost-of-ownership contracts. CE marking regulatory investment filters mid-tier competitors from European hospital networks. For New Entrants and Emerging Players: Launch via direct-to-ambulatory-surgery-center distribution models bypassing hospital procurement committee gatekeeping. Target United States lithotripsy chains and German outpatient clinics with polymer composite single-use ureteroscopes eliminating sterilization infrastructure requirements. White-space concentration sits in AI-enhanced imaging software companion modules for existing robotic platforms. For Investors and Strategic Acquirers: FDA 510(k) clearance pathway acceleration for novel instrument geometries is the leading indicator that regulatory friction is easing for differentiated entrants. Five-to-ten year viability favors manufacturers with dual CE-FDA certification and polymer sourcing control. Acquisition target archetype: mid-tier optical engineering specialists with CMOS integration capabilities and Japanese PMDA compliance track records.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR traceability mandates filter competitors from German hospital procurement channels. |
| Polymer Sourcing Integration | Captive resin supply protects margin pools on disposable ureteroscope architectures. |
| Hospital System Partnership | Multi-year service bundling agreements displace transactional instrument purchasing. |
| Software Companion Development | AI tissue recognition algorithms reduce operative time for robotic-assisted platforms. |
| Reimbursement Strategy | Japan PMDA stability rewards extended biological safety testing with tender preference. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and urology department heads combined with FDA 510(k) databases, EU MDR notified body submissions, and Japanese PMDA approval records. Bottom-up instrument shipment triangulation against top-down hospital capital expenditure surveys validated market sizing.
Data-stream reconciliation across product type, application, end user, technology, and regional regulatory cluster dimensions shaped the analytical framework. CAGRs derived from instrument replacement cycle modeling and robotic platform installation trajectories. Forecast inputs incorporated ambulatory surgery center expansion rates and polymer composite adoption curves for disposable architectures.
Titanium alloy supply disruption, EU MDR audit backlog delays, and CMOS sensor yield volatility are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Ultrasonic Tissue Ablation System Market
Surgical Instruments
South Korea General Surgical Devices Market
Surgical Instruments
Laparotomy Sponges Market
Surgical Instruments
Global Dental Surgical Instruments Market
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Monopolar Electrosurgery Instrument Market
Surgical Instruments
High Flow Needle Sets Market
Surgical Instruments
US Integrated Operating Rooms Market
Surgical Instruments
Endoscopic Spinal Surgery Market
Surgical Instruments
Global Bipolar Electrosurgical Devices Market
Surgical Instruments
Non-Absorbable Sutures Market
Surgical Instruments
Global Surgical Scissors Market
Surgical Instruments
Disposable Laparoscopic Instruments Market
Surgical Instruments
Global Veterinary Surgical Instruments Market
Surgical Instruments
Global Bone Wax Market
Surgical Instruments
Neurosurgical Drills Market