
 Hepatitis Test Solution and Diagnosis Market | 2026-2036
Hepatitis Test Solution and Diagnosis Market Size, Share, and Industry Trends Forecast 2026-2036
Hepatitis Test Solution and Diagnosis Market Intelligence
The European Union's In Vitro Diagnostic Regulation (IVDR) is decoupling market access from simple CE marking, raising the barrier for clinical evidence and post-market surveillance. This regulatory shift favors large incumbents with extensive clinical data and regulatory affairs teams. Roche Diagnostics leverages its vast portfolio and global presence to navigate these complex requirements. Abbott Laboratories sustains its market position through significant R&D investment in next-generation immunoassays and molecular tests.
Hepatitis test solutions encompass a range of in-vitro diagnostic assays and instruments used to detect viral antigens, such as the Hepatitis B surface antigen (HBsAg), or specific antibodies in human serum or plasma. The primary purpose is to enable clinical diagnosis, monitor disease progression, and screen blood donations to prevent transmission. Enzyme Immunoassay (EIA) and Chemiluminescent Immunoassay (CLIA) formats dominate high-throughput diagnostic laboratories due to automation compatibility. However, Rapid Diagnostic Tests (RDTs) are a fast-growing product type, driven by demand from government clinics for point-of-care testing.
Regulatory oversight from bodies like the U.S. Food and Drug Administration (FDA) and adherence to World Health Organization (WHO) prequalification standards are critical for market entry. These frameworks mandate stringent performance criteria for sensitivity and specificity, directly influencing product design and commercial viability. Stakeholders must now decide how to balance investment between centralized, high-throughput laboratory systems and decentralized, accessible point-of-care testing platforms.
Market Dynamics
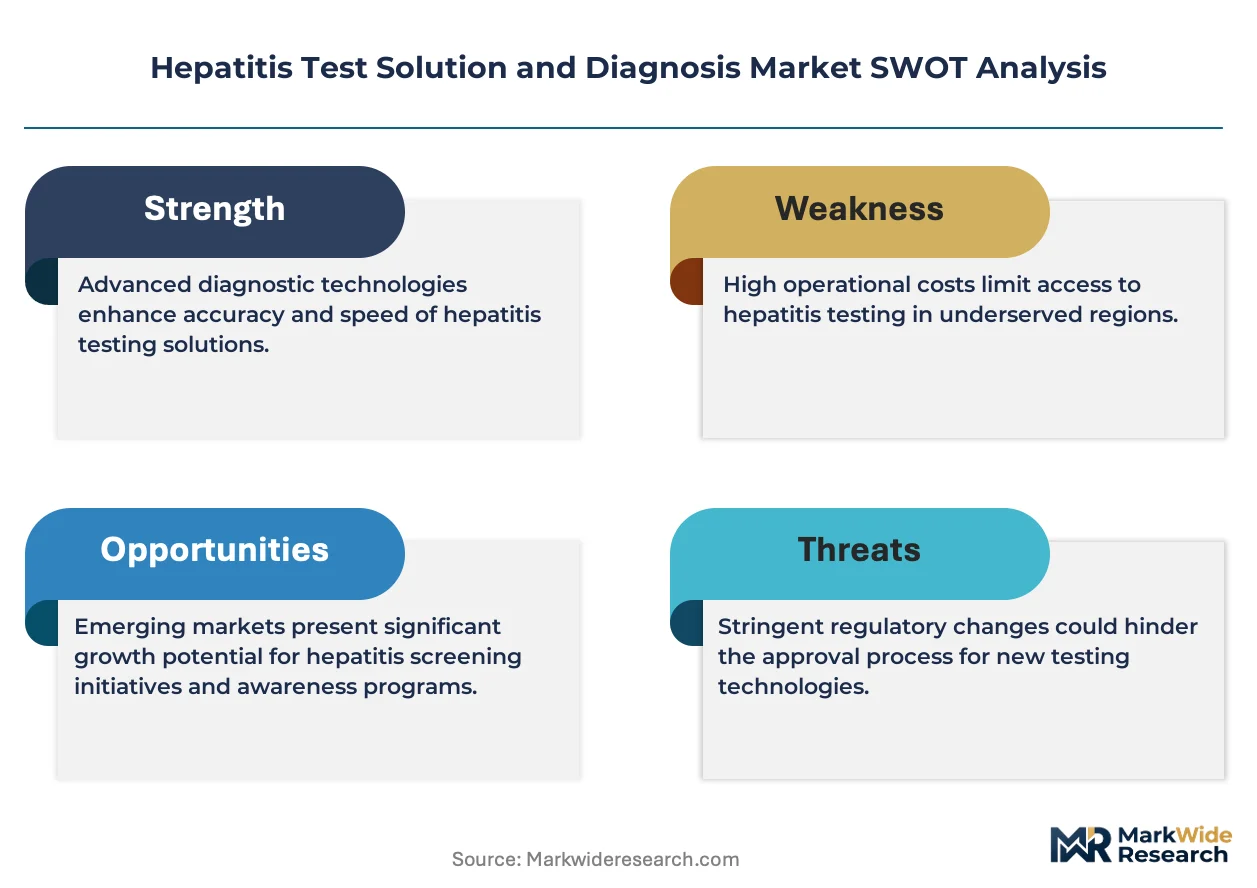
The central structural force shaping the market is a regulatory divergence, where stringent frameworks like the European Union's IVDR increase compliance burdens for high-throughput systems, while WHO prequalification simultaneously streamlines access for simplified point-of-care tests in global health programs.
Growth Catalysts
- WHO Elimination Goals:The World Health Organization's global health sector strategy to eliminate viral hepatitis as a public health threat is compelling national governments to fund and expand screening programs, creating sustained demand for diagnostic tests.
- Public Health Initiatives:Government-led screening campaigns in high-burden countries, particularly China and India, are expanding diagnostic access beyond urban hospitals into regional and community clinics, driving volume growth for both immunoassays and RDTs.
- Blood Safety Mandates:Expanded use of nucleic acid testing (NAT) and sensitive immunoassays in blood and plasma screening centers worldwide is mandated to ensure the safety of the blood supply, providing a stable demand base.
Market Restraints
- Cost of Advanced Testing:The high cost of instruments and reagents for nucleic acid tests and chemiluminescent immunoassays limits their adoption in low-resource settings, where budget constraints favor less sensitive but more affordable rapid tests.
- Regulatory Barriers:The European Union's In Vitro Diagnostic Regulation (IVDR) imposes significant clinical evidence and post-market surveillance requirements, increasing the cost and time to market and creating barriers for smaller manufacturers.
- Diagnostic Window Period:Serological assays have a diagnostic window during which a newly infected individual may test negative because detectable levels of antibodies or antigens have not yet developed, posing a residual risk in screening.
Strategic Opportunities
- Point-of-Care Molecular Diagnostics:The development of affordable, portable, and easy-to-use molecular testing platforms for point-of-care settings presents an opportunity to bring high-sensitivity testing to decentralized locations in regions like sub-Saharan Africa.
- Digital Health Integration:Integrating diagnostic test results with digital health platforms and electronic health records enables improved patient management, disease surveillance, and linkage to care, creating value beyond the initial test result.
- Multiplex Assay Development:There is an opportunity for assays that can simultaneously detect multiple hepatitis viruses (e.g., HBV, HCV, HDV) or co-infections like HIV from a single sample, improving laboratory efficiency and patient convenience.
Industry Challenges
- Compliance and Certification Timelines:Navigating the complex and lengthy approval processes of regulatory bodies like the FDA, EMA, and the WHO Prequalification of In Vitro Diagnostics Programme delays the launch of new and improved testing solutions.
- Laboratory Information System Integration:Ensuring seamless connectivity and data exchange between new diagnostic instruments, particularly point-of-care platforms, and existing, often fragmented, Laboratory Information Systems (LIS) in hospitals is a persistent technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hepatitis Test Solution and Diagnosis Market |
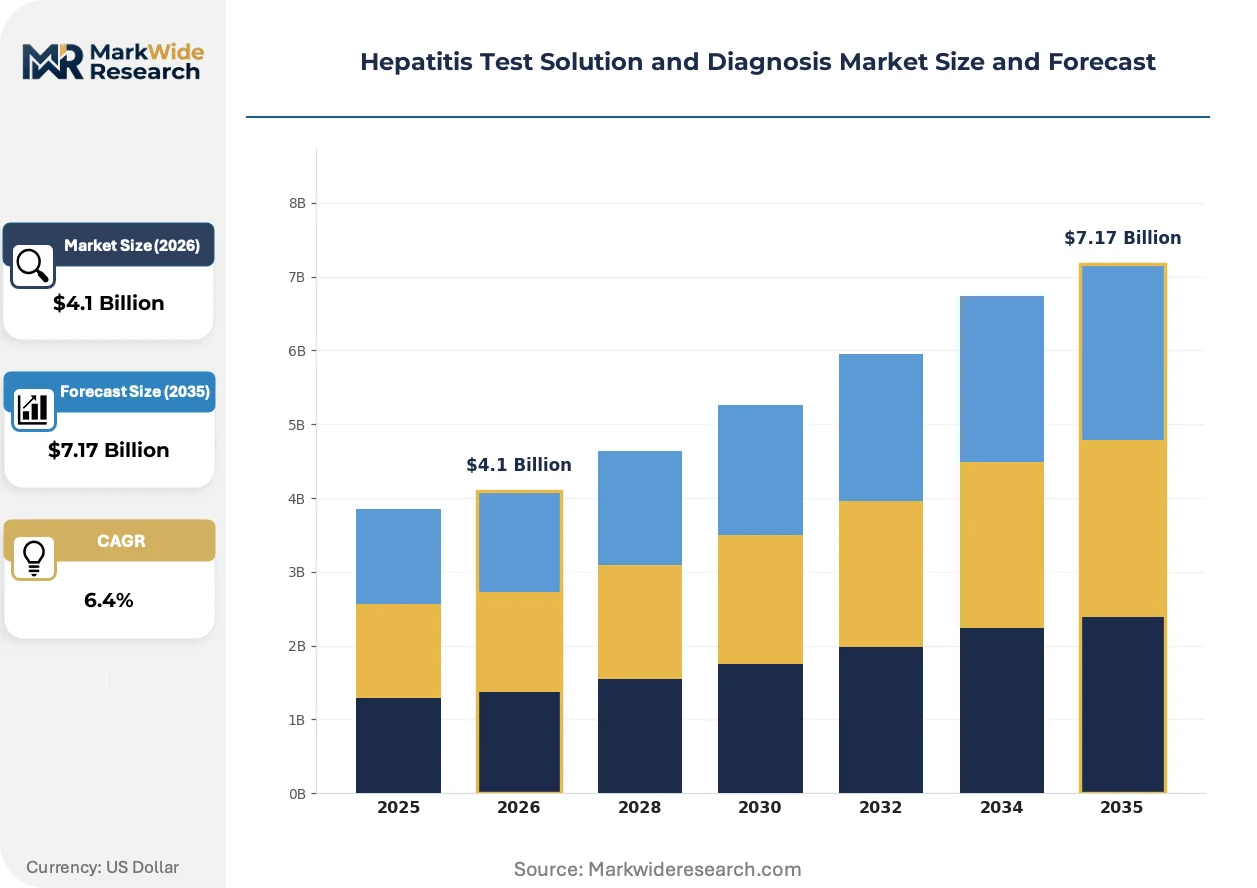
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.17 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
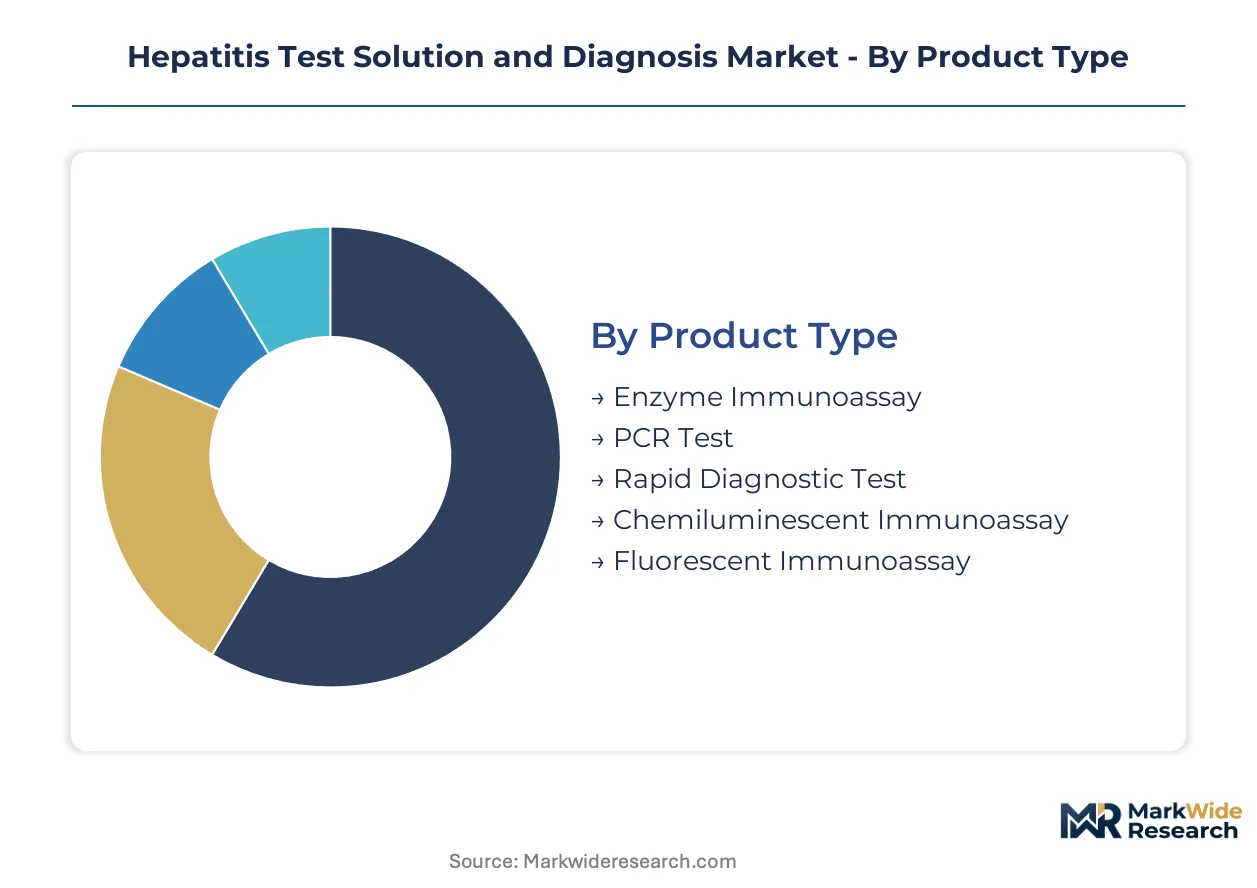
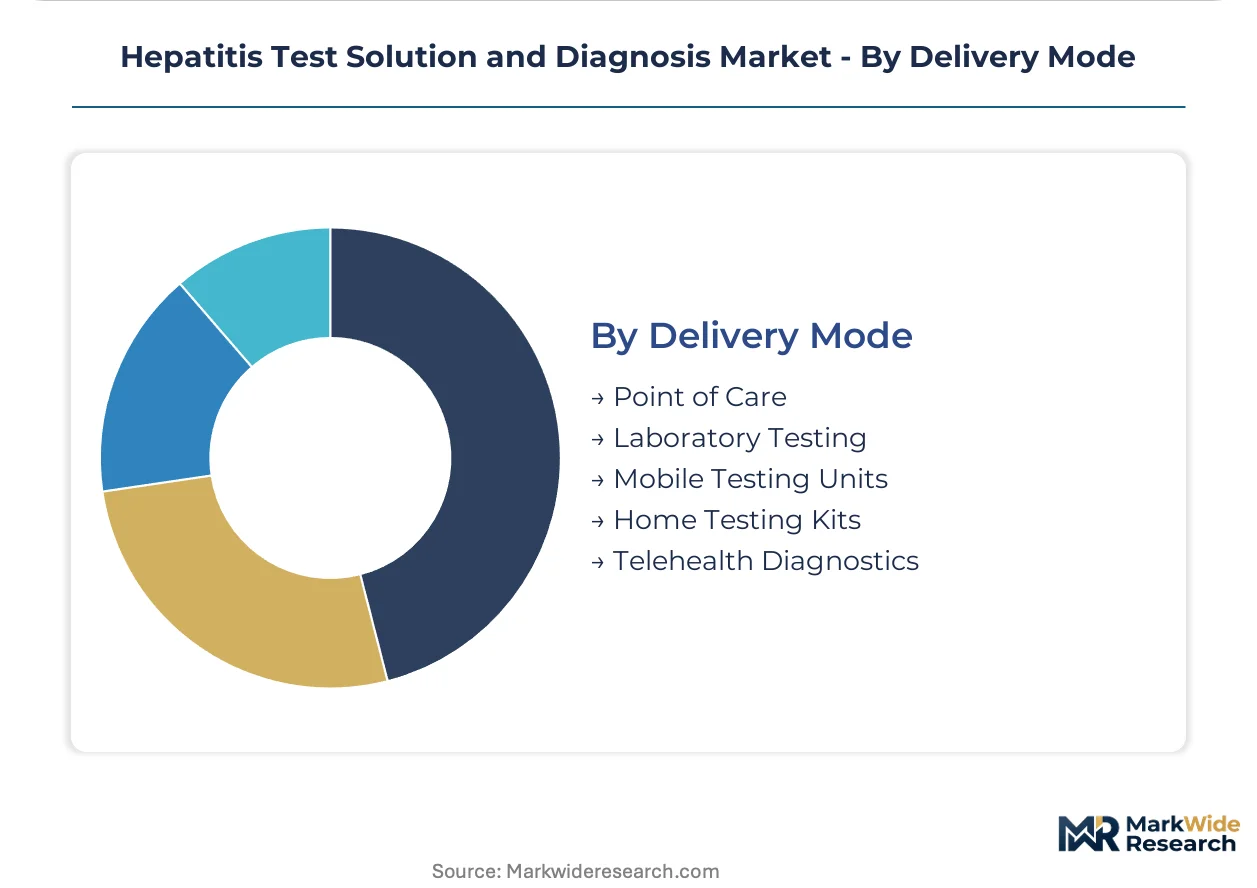
| Segmentation | Product Type: Enzyme Immunoassay, PCR Test, Rapid Diagnostic Test, Chemiluminescent Immunoassay, Fluorescent Immunoassay Application: Blood Screening, Prenatal Testing, Clinical Diagnosis, Epidemiological Surveillance, Organ Transplant Evaluation End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Government Clinics, Private Medical Centers Delivery Mode: Point of Care, Laboratory Testing, Mobile Testing Units, Home Testing Kits, Telehealth Diagnostics |
| Companies Covered | Roche Diagnostics International AG, Abbott Laboratories, Siemens Healthineers AG, DiaSorin S.p.A, Bio-Rad Laboratories, Inc., QIAGEN, bioMérieux SA, Grifols, S.A., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hepatitis Test Solution and Diagnosis Market Strategic Shifts & Innovations
A dual-track evolution defines the market, with innovation concentrating on both ends of the spectrum. This includes fully automated, high-throughput systems for centralized labs and simplified, highly accessible rapid tests for decentralized, point-of-care deployment in public health initiatives.
Chemiluminescent Immunoassay (CLIA) is a core technology for automated, high-sensitivity detection of viral antigens and antibodies. High-volume clinical laboratories and blood donation centers are the primary adopters, seeking to improve efficiency and accuracy. Automated CLIA platforms are overtaking traditional Enzyme Immunoassay (EIA) workflows in developed markets, driven by their superior throughput, wider dynamic range, and reduced hands-on time.
The U.S. FDA’s establishment of performance criteria for CLIA-waived tests and point-of-care diagnostics sets a clear standard for test development. This regulatory focus on usability and accessibility has accelerated innovation in devices intended for use by non-laboratory personnel. Rapid diagnostic test (RDT) manufacturers are the most affected, now designing products specifically to meet these criteria for deployment in clinics, pharmacies, and community health settings.
Demand is shifting from the purchase of individual test kits toward the procurement of managed service contracts. This model bundles instruments, reagents, maintenance, and sometimes even staffing into a single, long-term agreement, disrupting the transactional sales of consumables. This trend is most prominent in large-scale public health tenders in countries like Brazil and South Africa, where governments seek predictable costs and guaranteed service levels.
Hepatitis Test Solution and Diagnosis Market Segmentation
Understanding market segmentation is crucial for stakeholders to identify investment priorities and tailor product development to specific needs within the hepatitis test solution and diagnosis market. This segmentation highlights the diverse technological approaches, application areas, end-user profiles, and delivery mechanisms driving market dynamics.
Product Type:
The capital intensity of diagnostic solutions significantly influences market adoption, with high-throughput automated systems requiring substantial upfront investment for laboratories.
- Chemiluminescent Immunoassay:These highly sensitive and automated assays detect viral antigens or antibodies with superior throughput and dynamic range, primarily adopted by high-volume reference laboratories and blood screening centers for efficiency. Demand concentrates in developed economies like Germany and Japan due to established laboratory infrastructure and funding.
- PCR Test:Polymerase Chain Reaction tests offer high sensitivity and specificity for detecting viral nucleic acids, essential for early infection diagnosis and viral load monitoring. Clinical laboratories and research institutes in countries such as the United States and Canada increasingly utilize PCR for its precision in disease management.
- Enzyme Immunoassay:EIA tests are widely used for screening due to their cost-effectiveness and adaptability, especially in settings with budget constraints.
- Rapid Diagnostic Test:RDTs provide quick results at the point of care, supporting decentralized testing initiatives in community health settings.
- Fluorescent Immunoassay:FIAs offer quantitative results with good sensitivity, often employed in specialized labs for specific diagnostic applications.
Chemiluminescent Immunoassay absorbs the bulk of installed capacity; Rapid Diagnostic Test is expanding most quickly.
Application:
The critical nature of the diagnostic application dictates the required sensitivity, specificity, and regulatory oversight for hepatitis testing solutions.
- Blood Screening:This application focuses on preventing transfusion-transmitted infections by rigorously testing donated blood and plasma for hepatitis viruses, employing highly sensitive nucleic acid tests and immunoassays. Regulatory bodies like the U.S. FDA and the European Medicines Agency mandate stringent screening protocols to ensure public safety across global blood banks.
- Clinical Diagnosis:Clinical diagnosis involves confirming active infections, staging disease progression, and guiding treatment decisions for patients presenting with symptoms or risk factors. Physicians in countries like India and China rely on these tests for patient management within hospital and clinic settings.
- Prenatal Testing:Screening pregnant women for hepatitis B and C prevents mother-to-child transmission, a critical public health intervention.
- Epidemiological Surveillance:These tests monitor disease prevalence and incidence within populations, informing public health strategies and outbreak response.
- Organ Transplant Evaluation:Testing organ donors and recipients for hepatitis ensures transplant safety and prevents disease transmission during transplantation procedures.
Blood Screening applications demand the highest precision; Epidemiological Surveillance is gaining share fastest.
End User:
The scale and operational requirements of end-user facilities significantly shape the demand profile for hepatitis diagnostic products and services.
- Diagnostic Laboratories:These centralized facilities perform a high volume of tests using automated immunoassay and molecular platforms, serving hospitals, clinics, and public health programs. Laboratories in countries such as Brazil and South Africa often manage large-scale testing operations under government contracts.
- Government Clinics:Public health initiatives drive demand in government clinics, where rapid diagnostic tests and simpler immunoassay platforms are deployed for broad access and point-of-care screening. These clinics in India and Nigeria are instrumental in expanding diagnostic reach to underserved populations.
- Research Institutes:Academic and commercial research entities utilize advanced molecular diagnostics for disease characterization, vaccine development, and novel biomarker discovery.
- Blood Banks:These specialized centers conduct mandatory screening of donated blood units to ensure safety before transfusion, relying on sensitive and high-throughput systems.
- Private Medical Centers:Private clinics and hospitals offer a range of hepatitis tests for individual patient care, often prioritizing convenience and rapid turnaround times.
Diagnostic Laboratories manage the largest testing volumes; Government Clinics are experiencing the steepest expansion trajectory.
Delivery Mode:
The choice of delivery mode influences accessibility, turnaround time, and the level of infrastructure required for hepatitis testing.
- Point of Care:Point-of-care testing brings diagnostics closer to the patient, enabling rapid results and immediate clinical decisions in settings like community clinics, pharmacies, and remote areas. The U.S. FDA's CLIA-waived test criteria specifically enable this decentralized approach.
- Laboratory Testing:This traditional mode involves sending samples to centralized laboratories for analysis using high-throughput, complex instruments, providing comprehensive and highly accurate results. Major reference laboratories in countries like France and the UK form the backbone of this delivery system.
- Mobile Testing Units:These units offer flexible diagnostic services in underserved or hard-to-reach populations, often utilizing rapid tests for on-site screening.
- Home Testing Kits:Self-administered kits allow individuals to collect samples and perform initial screening tests privately, enhancing convenience and reducing barriers to access.
- Telehealth Diagnostics:This mode integrates diagnostic results with virtual consultations, facilitating remote patient management and follow-up care.
Laboratory Testing constitutes the largest established segment; Point of Care delivery is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's In Vitro Diagnostic Regulation (IVDR) creates a significant regulatory zone impacting market access across member states. This framework drives demand for robust clinical evidence and post-market surveillance. It influences the strategic decisions of diagnostic manufacturers operating within the region.
United States
The United States market sees strong demand for advanced PCR tests and high-throughput immunoassays for clinical diagnosis. U.S. FDA regulations mandate stringent performance criteria for new diagnostic products, including CLIA-waived tests. Research institutions in regions like Massachusetts and California drive development of next-generation molecular platforms.
Germany
Germany's well-established laboratory infrastructure drives significant adoption of chemiluminescent immunoassay (CLIA) systems for blood screening. The European Union's IVDR framework increases compliance burdens for diagnostic manufacturers in the country. Research and development clusters in cities like Mannheim and Munich concentrate on advanced automated testing solutions.
China
China experiences substantial demand for both immunoassays and rapid diagnostic tests due to extensive government-led public health campaigns. The National Medical Products Administration (NMPA) regulates market entry and product standards for diagnostic solutions. Manufacturing hubs in the Pearl River Delta support the large-scale production of hepatitis testing kits for national initiatives.
India
India's public health initiatives are rapidly expanding diagnostic access, especially in regional and community clinics. The Central Drugs Standard Control Organization (CDSCO) sets standards for in-vitro diagnostic devices. Manufacturing facilities in states like Gujarat and Telangana are scaling up to meet the country's immense testing volume requirements.
Brazil
Brazil's market is shaped by large-scale public health tenders and government contracts for diagnostic services. ANVISA, the national health surveillance agency, regulates the import and sale of diagnostic tests. Major diagnostic laboratories in the São Paulo region manage extensive testing operations for public health programs.
Hepatitis Test Solution and Diagnosis Market Key Industry Players
European producers anchor one tier, focusing on high-throughput automated systems; North American specialists hold strong positions in molecular diagnostics. The market exhibits a tiered structure, with large incumbents leveraging extensive portfolios and smaller innovators focusing on niche point-of-care solutions. Strategic archetypes include global diagnostics giants, specialized molecular test developers, and rapid diagnostic test manufacturers. Portfolio diversification and strategic partnerships are dominant competitive moves.
Among global diagnostics giants, Roche Diagnostics International AG, Abbott Laboratories, and Siemens Healthineers AG exemplify the industry's focus on comprehensive in-vitro diagnostic solutions. These entities represent the established market leaders, providing a broad range of immunoassay and molecular testing platforms. Their presence anchors the high-throughput laboratory segment, influencing technological standards and market access through their extensive global reach and regulatory affairs capabilities. They often set benchmarks for sensitivity and specificity in advanced diagnostic assays, driving continuous innovation.
| Leading Market Players |
|---|
| Roche Diagnostics International AG |
| Abbott Laboratories |
| Siemens Healthineers AG |
| DiaSorin S.p.A |
| Bio-Rad Laboratories, Inc. |
| QIAGEN |
| bioMérieux SA |
| Grifols, S.A. |
| Danaher Corporation |
| Others |
Cost & Logistics Intelligence
The European Union's In Vitro Diagnostic Regulation (IVDR) mandates stringent quality and sustainability standards for diagnostic products. This framework gates access for manufacturers, often leading to premium pricing for compliant tests.
Pricing Analysis
Premium pricing for rapid delivery of specialized reagents reflects critical diagnostic needs, contrasting with discounts for routine screening bulk orders. Contract-based long-term agreements for managed services define a significant pricing model, bundling instruments and services. Price differentiation stems from certification level, such as WHO prequalification, and advanced performance metrics like sensitivity and specificity. Pricing pressure intensifies for high-volume, cost-sensitive public health initiatives, with government clinics demonstrating the highest price sensitivity.
Supply Chain Analysis
Skilled workforce availability in manufacturing hubs like China and India underpins global production of hepatitis test kits. Supply concentration centers on China and India for volume, with specialized component manufacturing in developed economies. Key raw material dependencies include highly purified antigens, antibodies, and specialized chemical reagents. Regulatory restrictions, particularly the EU IVDR, pose a structural risk, while distribution runs through direct sales to diagnostic laboratories and government tenders, alongside specialized distributors for point-of-care solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hepatitis test market is in a technology-transition phase, with advanced chemiluminescent immunoassay (CLIA) systems displacing traditional enzyme immunoassays (EIA) in high-throughput laboratories. This shift enhances efficiency and diagnostic accuracy across global health systems.
For Market Incumbents: Extend investment in next-generation molecular and immunoassay platforms to maintain a competitive edge against emerging point-of-care solutions. Incumbents like Roche Diagnostics must leverage their global presence and regulatory affairs teams to navigate complex frameworks such as the EU IVDR. Strategic partnerships are essential for securing managed service contracts, especially in public health tenders. This approach mitigates threats from regulatory divergence and cost pressures in low-resource settings.
For New Entrants and Emerging Players: The U.S. FDA’s establishment of performance criteria for CLIA-waived tests in the United States opens a window for innovative point-of-care solutions. New entrants should target affordable, portable molecular diagnostic platforms for decentralized locations in regions like sub-Saharan Africa. Developing multiplex assays that detect multiple hepatitis viruses simultaneously presents a significant white-space opportunity. Integrating diagnostic results with digital health platforms offers a compelling go-to-market angle for enhanced patient management.
For Investors and Strategic Acquirers: Increased government funding for viral hepatitis elimination programs is the leading indicator that signals sustained market growth over the next five to ten years. Investors should seek specialized molecular test developers or rapid diagnostic test manufacturers with strong intellectual property in point-of-care diagnostics. Companies demonstrating successful navigation of stringent regulatory frameworks, such as the EU IVDR, represent attractive acquisition targets. Monitoring the adoption rates of point-of-care molecular diagnostics in emerging markets serves as a critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Point-of-Care Molecular Diagnostics | This brings high-sensitivity testing to decentralized locations, expanding diagnostic access in underserved regions. |
| Regulatory Approval Pathway: WHO Prequalification | This unlocks access to global health programs and public health tenders in developing nations. |
| Strategic Partnership: Managed Service Contracts | This secures long-term revenue streams and reduces capital expenditure burdens for end-users like government clinics. |
| R&D Investment: Multiplex Assay Development | This improves laboratory efficiency and patient convenience by detecting multiple pathogens from one sample. |
| Digital Health Integration: Diagnostic Result Platforms | This enhances patient management and disease surveillance through seamless data exchange with electronic health records. |
Research Approach
Multi-period observation of diagnostic test volumes, regulatory approval timelines, and technology adoption rates anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved conversations with diagnostic manufacturers' R&D leads, regulatory affairs specialists, public health officials, and laboratory directors. Secondary validation utilized WHO reports, FDA filings, NMPA product registries, and academic literature. This approach ensured robust bottom-up and top-down triangulation of market insights.
Segment-weighting across product type, application, end user, delivery mode, and regional geography informed the quantitative modeling over the analysis window. The analytical framework incorporated historical growth rates extrapolated through regression analysis to derive compound annual growth rates. Key industry-specific forecast inputs included government funding for public health campaigns and global viral hepatitis prevalence rates.
The model assumes a particular technology adoption path; alternative pathways for point-of-care molecular diagnostics would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and public health funding. Material deviation in unforeseen regulatory changes or public health funding warrants re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Glucose Tolerance Test Market
Diagnostics
Vibrio Diagnostics Market
Diagnostics
BNP and NT-Probnp Market
Diagnostics
Global Women's Health Diagnostics Market
Diagnostics
Allergy Diagnostics Market
Diagnostics
DNA Probes - Based Diagnostics Market
Diagnostics
Germany in-Vitro Diagnostics Market
Diagnostics
Asia Pacific Predictive Disease Analytics Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Blood Grouping Reagents Market
Diagnostics
In-Vitro Diagnostics (IVD) Instruments Market
Diagnostics
Viral Antigens Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Diabetes Diagnostics Market
Diagnostics
Self-Administered HPV Test Market