
 Global Molecular Diagnostics Services Market | 2026-2036
Global Molecular Diagnostics Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Molecular Diagnostics Services Market Foresight
Clinical bioinformatician shortages is redrawing competitive boundaries across molecular diagnostics services. F. Hoffmann-La Roche Ltd. leverages automated nucleic acid extraction platforms to reduce technician dependency in high-throughput labs. Thermo Fisher Scientific Inc. anchors its position through end-to-end sequencing workflows that compress turnaround times. QIAGEN specializes in sample-to-insight bioinformatics pipelines that address the interpretive bottleneck in variant classification.
Molecular diagnostics services encompass laboratory-based nucleic acid detection, amplification, and sequencing workflows operating at analytical sensitivities often below one copy per microliter, with primary purpose spanning pathogen identification, cancer mutation profiling, and pharmacogenomic guidance. Infectious disease testing dominates current service volumes while oncology diagnostics captures expanding margin pools as companion diagnostic requirements multiply across pharmaceutical pipelines. Cloud-based analytics deployment is gaining share among multi-site health systems seeking centralized quality control and real-time bioinformatics access.
FDA oversight of laboratory-developed tests and CLIA proficiency standards govern analytical validity claims in the United States, while EMA In Vitro Diagnostic Regulation pathways shape market access across European member states. China's NMPA nucleic acid test registration requirements and Japan's PMDA quality management standards add further compliance layers for multinational service providers. Stakeholders must monitor evolving premarket submission requirements as regulators tighten evidentiary standards for algorithm-driven variant interpretation.
Market Dynamics
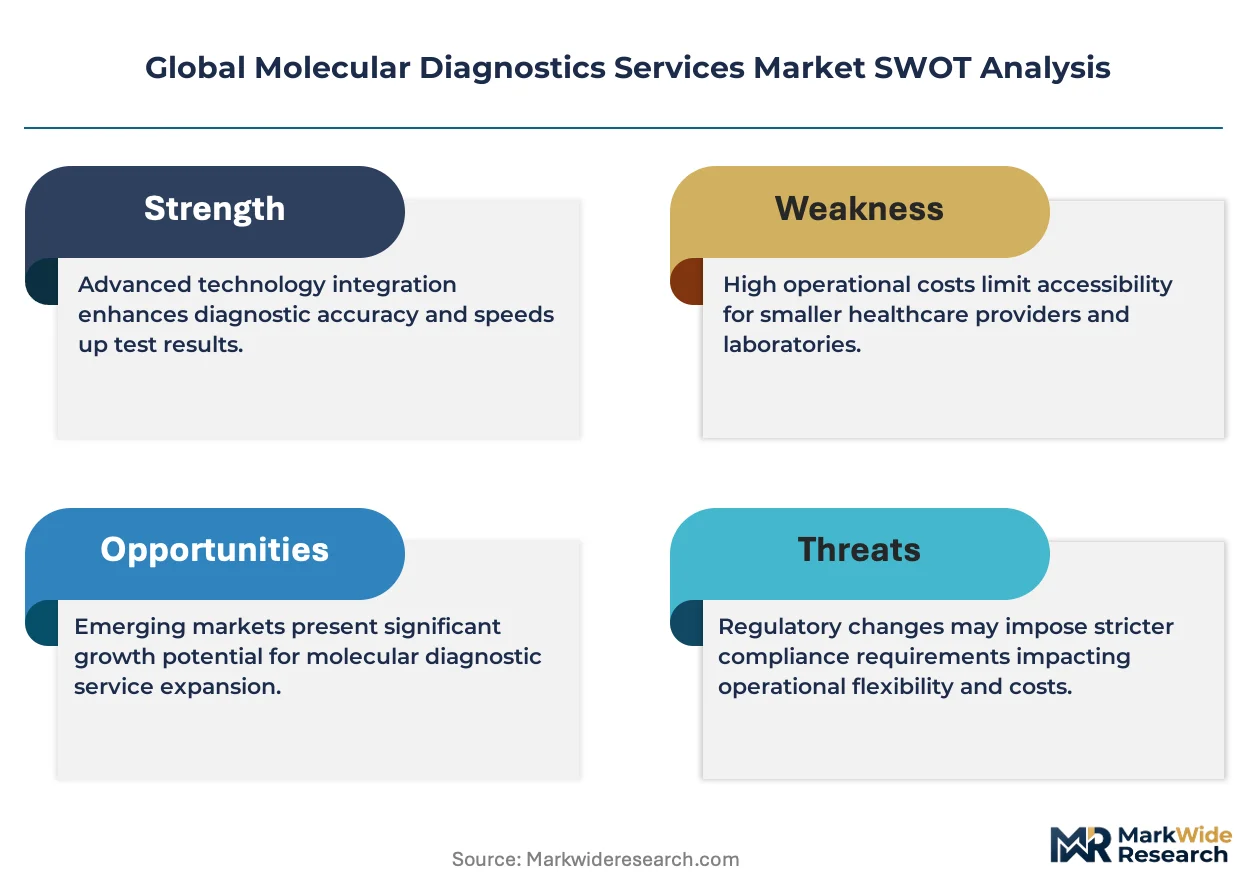
Automated liquid handling systems and cloud-native bioinformatics pipelines are compressing technician-to-sample ratios across high-throughput molecular diagnostics laboratories. CLIA laboratory certification requirements and FDA premarket review pathways are simultaneously elevating capital barriers for new market entrants.
Growth Catalysts
- Companion diagnostic mandates:Pharmaceutical pipelines in oncology and infectious disease now require co-developed biomarker tests, locking in recurring service contracts with centralized laboratories.
- Cloud-based quality control:Multi-site health systems in Germany and China are deploying centralized LIMS architectures that standardize variant interpretation across distributed lab networks.
- Precision medicine infrastructure:The United States and China are expanding reimbursement codes for pharmacogenomic testing, directly expanding addressable service volumes.
Market Restraints
- Reagent supply concentration:Nucleic acid extraction chemistries and sequencing consumables depend on a narrow supplier base concentrated in the United States and Germany, exposing service providers to input cost volatility.
- Algorithm evidentiary standards:FDA tightening of premarket submission requirements for AI-driven variant classification is extending regulatory timelines for new assay launches.
- Technical substitution:Point-of-care nucleic acid amplification devices are capturing low-complexity infectious disease testing previously routed to centralized laboratories.
Strategic Opportunities
- Liquid biopsy expansion:Cell-free DNA testing for minimal residual disease monitoring represents underpenetrated oncology application with recurring revenue potential.
- India laboratory accreditation:NABL certification expansion is opening compliant channel access for multinational service providers seeking cost-optimized production nodes.
- NGS-PCR convergence:Integrated platforms combining targeted sequencing with rapid amplification are enabling same-day turnaround for time-critical infectious disease diagnostics.
Industry Challenges
- Bioinformatician talent scarcity:Variant classification and clinical interpretation functions face acute staffing gaps, forcing laboratories to outsource tier-one analysis or delay report delivery.
- CLIA certification timelines:Proficiency testing documentation and inspector availability are stretching new laboratory commissioning cycles beyond eighteen months in high-demand metropolitan clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Molecular Diagnostics Services Market |
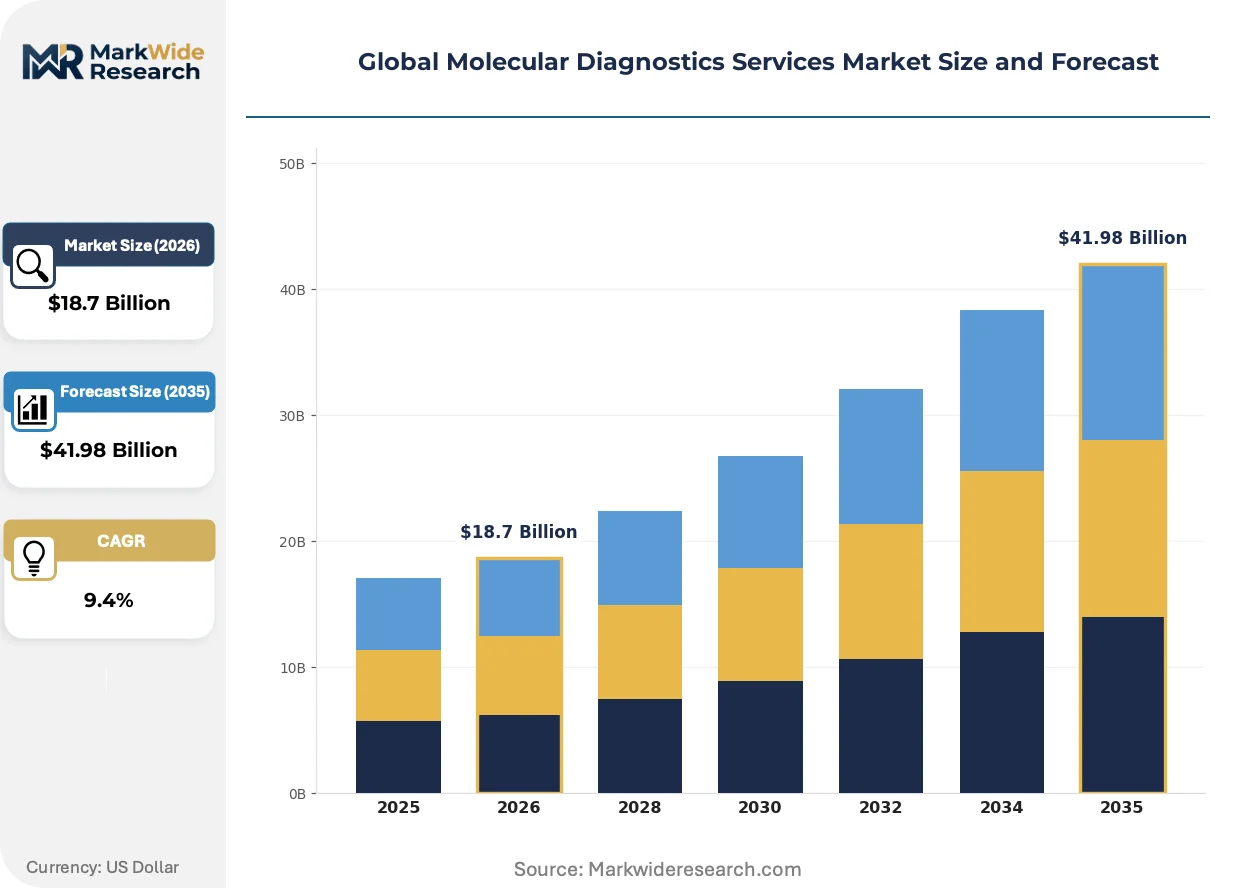
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Genetic Testing, Infectious Disease Testing, Oncology Diagnostics, Prenatal Screening, Pharmacogenomics, Microbial Detection Application: Pathogen Identification, Cancer Detection, Genetic Disorder Diagnosis, Drug Response Prediction, Mutation Analysis, Biomarker Discovery End User: Research Laboratories, Diagnostic Centers, Academic Institutions, Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations Deployment Model: On-Premise, Cloud-Based Analytics, Hybrid Systems, Centralized Labs, Mobile Labs, Point-of-Care Facilities |
| Companies Covered | F. Hoffmann-La Roche Ltd., Danaher Corporation, QIAGEN, bioMérieux SA, Abbott Laboratories, Hologic Inc., Thermo Fisher Scientific Inc., Siemens Healthcare GmbH, Illumina Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Molecular Diagnostics Services Market Shifts & Advancements
Digital pathology integration and real-time bioinformatics access are redefining service delivery architectures across hospital-integrated molecular diagnostics networks. Three developments are compressing competitive response windows.
Next-generation sequencing panels are fragmenting the traditional single-gene testing market. Community oncology practices and mid-sized hospital networks are adopting comprehensive genomic profiling at accelerating cadence. This technology shift is fragmenting referral patterns away from academic medical centers toward regional reference laboratories with compressed turnaround capabilities.
EMA In Vitro Diagnostic Regulation pathways are elevating clinical evidence requirements for algorithm-based variant interpretation across European member states. Manufacturers must now submit prospective performance data for computational pipelines previously validated through retrospective benchmarking. Oncology companion diagnostics face the steepest compliance ramps, with several pharmaceutical sponsors restructuring co-development timelines to accommodate notified body review queues.
Health system procurement departments are consolidating molecular diagnostics contracts under centralized laboratory management agreements. Integrated delivery networks in the United States are unbundelling esoteric testing from traditional reference laboratory relationships, directly negotiating with specialty toxicology and pharmacogenomics providers. This purchasing behavior shift is most visible in California and Texas, where hospital consolidation has produced super-regional systems with sufficient volume to justify captive laboratory investments.
Global Molecular Diagnostics Services Market Segmentation
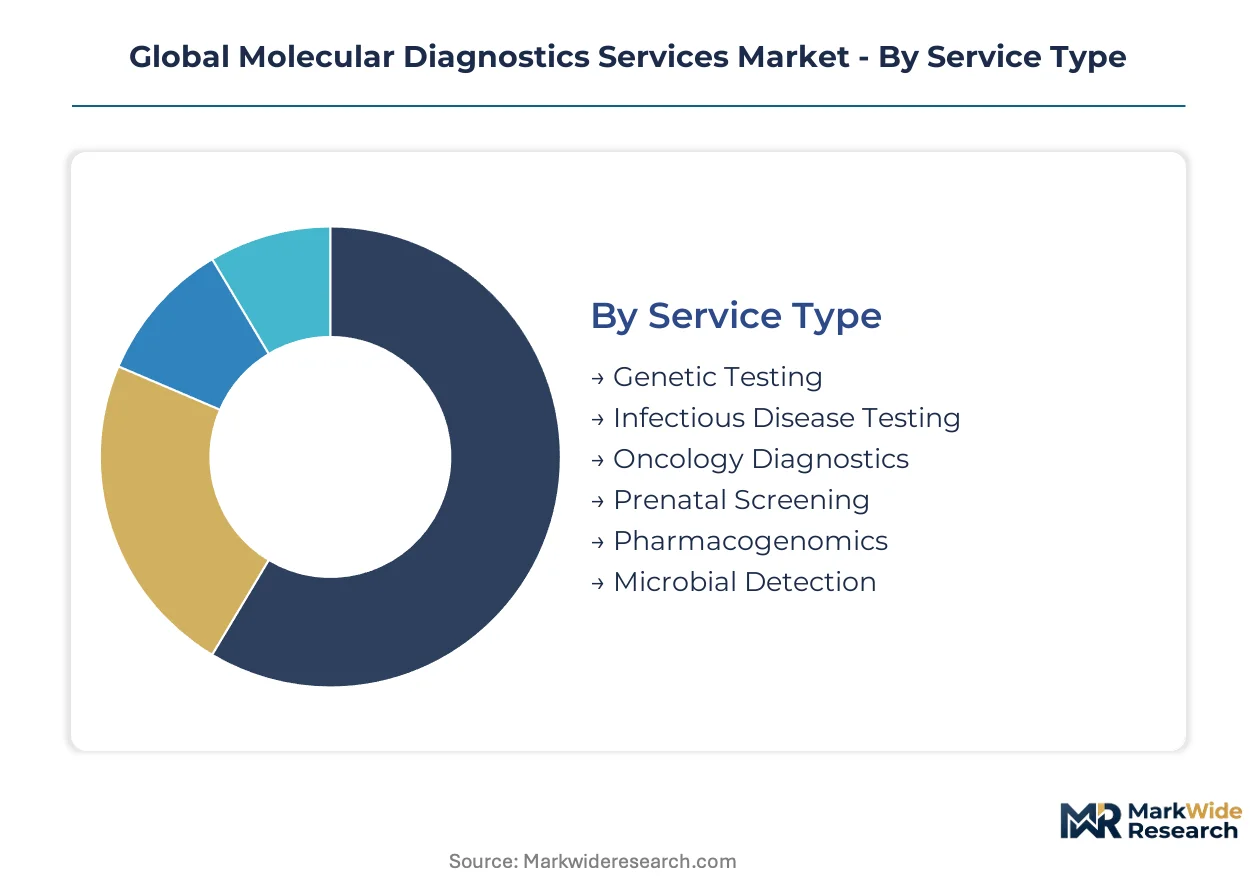
Service delivery architectures in molecular diagnostics fragment across technical complexity tiers and regulatory exposure levels. Understanding substitution pressures and margin concentration across these divides enables targeted capability investments and partnership prioritization.
Service Type:
Point-of-care nucleic acid amplification devices threaten centralized laboratory volumes most acutely in low-complexity infectious disease testing, compressing economics for legacy service providers.
- Infectious Disease Testing:Real-time PCR and isothermal amplification workflows dominate current service volumes, with demand concentrating in hospital emergency departments and urgent care networks facing CLIA-waived device competition. Turnaround pressure and reimbursement compression are forcing laboratories to automate or exit.
- Oncology Diagnostics:Next-generation sequencing panels and companion diagnostic assays command premium pricing through pharmaceutical co-development contracts. Companion diagnostic mandates from FDA and EMA are locking in recurring revenue streams with centralized reference laboratories.
- Genetic Testing:Hereditary risk assessment and carrier screening applications.
- Prenatal Screening:Non-invasive prenatal testing using cell-free fetal DNA analysis.
- Pharmacogenomics:Drug-gene interaction testing for psychiatric and cardiovascular therapeutics.
- Microbial Detection:Culture-independent pathogen identification in sepsis and meningitis protocols.
Infectious Disease Testing retains volume leadership; Oncology Diagnostics holds the steepest expansion curve.
Application:
Margin stratification across applications tracks directly to pharmaceutical sponsorship density and regulatory evidentiary requirements.
- Cancer Detection:Comprehensive genomic profiling for therapy selection and minimal residual disease monitoring integrates tissue-based sequencing with liquid biopsy validation. Demand concentrates in community oncology practices seeking to retain patients who would otherwise transfer to academic centers for molecular testing.
- Pathogen Identification:Syndromic respiratory and bloodstream infection panels compress diagnostic uncertainty into actionable timeframes. Health systems in Germany and China are deploying these assays to reduce empiric antibiotic utilization and length-of-stay metrics.
- Genetic Disorder Diagnosis:Exome and genome sequencing for rare disease identification.
- Drug Response Prediction:Pharmacogenomic guidance for anticoagulant and antidepressant selection.
- Mutation Analysis:Targeted variant detection in hereditary cancer syndromes.
- Biomarker Discovery:Exploratory sequencing for pharmaceutical target validation.
Cancer Detection captures margin concentration; Pathogen Identification faces the steepest price erosion from point-of-care substitution.
End User:
Procurement consolidation is reshaping vendor relationships across customer categories, with integrated delivery networks unbundling esoteric testing from traditional reference contracts.
- Diagnostic Centers:Independent reference laboratories and hospital-affiliated labs process high-throughput molecular testing under CLIA and CAP accreditation. Volume concentration in the United States and China is driving automation investments and cloud-based quality control deployment.
- Pharmaceutical Companies:Companion diagnostic co-development partnerships require analytical validation and regulatory submission support. EMA In Vitro Diagnostic Regulation and FDA premarket review pathways are extending timelines and elevating evidence standards for these collaborations.
- Research Laboratories:Academic medical center core facilities and government research institutes.
- Academic Institutions:University-affiliated clinical laboratories with mixed research-service missions.
- Biotechnology Firms:Development-stage companies outsourcing GLP-compliant bioanalysis.
- Contract Research Organizations:Full-service providers managing multi-site clinical trial testing.
Diagnostic Centers retain volume leadership; Pharmaceutical Companies offer the steepest expansion trajectory through companion diagnostic mandates.
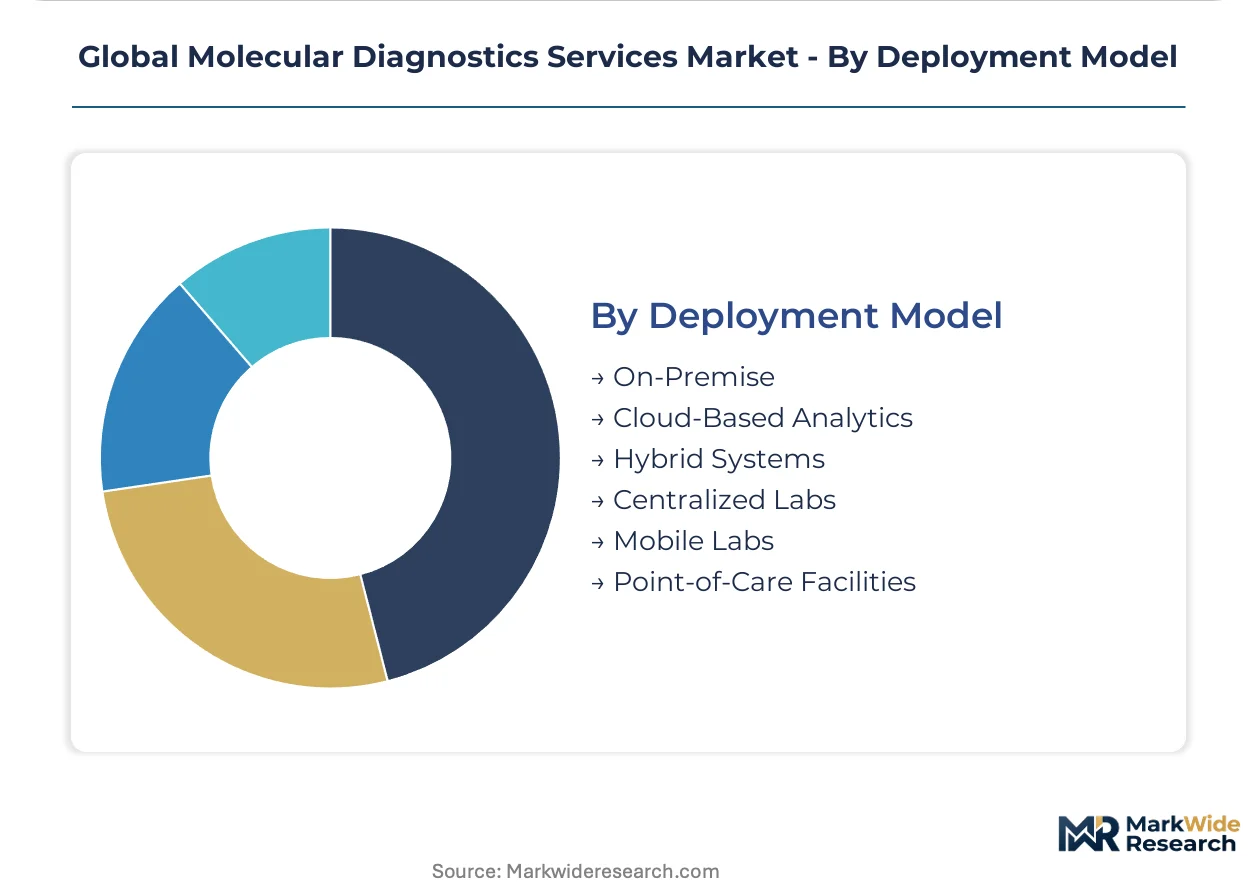
Deployment Model:
Capital intensity and regulatory jurisdiction create distinct competitive dynamics across infrastructure configurations.
- Centralized Labs:High-throughput facilities achieving economies of scale through automated liquid handling and batch sequencing. Germany's reference laboratory networks and China's hospital-affiliated mega-labs exemplify this model, with NMPA and BfArM quality standards governing analytical validity claims.
- Cloud-Based Analytics:Distributed bioinformatics pipelines enabling real-time variant interpretation across multi-site health systems. Deployment concentrates in the United States and Germany where HIPAA and GDPR compliance architectures have matured.
- On-Premise:Institutionally managed hardware and software stacks.
- Hybrid Systems:Mixed local sequencing with remote bioinformatics processing.
- Mobile Labs:Containerized or vehicle-mounted testing units for outbreak response.
- Point-of-Care Facilities:CLIA-waived devices in physician offices and retail clinics.
Centralized Labs retain volume leadership; Cloud-Based Analytics holds the steepest expansion curve as health systems consolidate quality control functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket review pathways and CLIA laboratory certification requirements anchor the United States as the dominant geography, with Germany's EMA In Vitro Diagnostic Regulation pathways and China's NMPA nucleic acid test registration requirements adding compliance layers for multinational service providers.
United States
Hospital consolidation in California and Texas is producing super-regional systems with sufficient volume to justify captive laboratory investments. FDA tightening of premarket submission requirements for AI-driven variant classification is extending regulatory timelines for new assay launches. The Greater Boston cluster concentrates academic medical center core facilities pursuing comprehensive genomic profiling adoption.
Germany
Reference laboratory networks are deploying centralized LIMS architectures that standardize variant interpretation across distributed lab networks. EMA In Vitro Diagnostic Regulation pathways are elevating clinical evidence requirements for algorithm-based variant interpretation across European member states. The Munich and Heidelberg clusters anchor pharmaceutical co-development partnerships requiring analytical validation support.
China
Hospital-affiliated mega-labs are expanding precision medicine infrastructure with NMPA nucleic acid test registration compliance. The country's national pharmaceutical regulator is tightening evidentiary standards for algorithm-driven variant interpretation. The Yangtze River Delta and Beijing-Tianjin-Hebei clusters concentrate cloud-based analytics deployment among multi-site health systems.
Japan
Community oncology practices are adopting comprehensive genomic profiling to retain patients who would otherwise transfer to academic centers. PMDA quality management standards govern analytical validity claims for molecular diagnostics services. The Kanto region around Tokyo concentrates diagnostic center investments seeking NABL-equivalent accreditation alignment.
India
NABL certification expansion is opening compliant channel access for multinational service providers seeking cost-optimized production nodes. The country's national pharmaceutical regulator is aligning laboratory accreditation with international proficiency testing standards. The Maharashtra and Karnataka clusters concentrate contract research organization investments serving pharmaceutical trial networks.
Global Molecular Diagnostics Services Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in molecular diagnostics services. The upper tier commands end-to-end sequencing workflows and automated nucleic acid extraction platforms that compress turnaround times. Specialist competitors anchor positions through sample-to-insight bioinformatics pipelines and cloud-native quality control architectures. Dominant competitive moves include companion diagnostic co-development partnerships with pharmaceutical sponsors and vertical integration into reagent manufacturing to secure input supply.
Among Swiss and German-integrated conglomerates, F. Hoffmann-La Roche Ltd. and Siemens Healthcare GmbH exemplify the scale-driven archetype with automated platform portfolios. Thermo Fisher Scientific Inc. represents the end-to-end workflow specialist position. QIAGEN occupies a position within the bioinformatics pipeline tier addressing interpretive bottlenecks in variant classification.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Danaher Corporation |
| QIAGEN |
| bioMérieux SA |
| Abbott Laboratories |
| Hologic Inc. |
| Thermo Fisher Scientific Inc. |
| Siemens Healthcare GmbH |
| Illumina Inc. |
| Others |
Supply & Pricing Matrix
Automated liquid handling throughput in high-volume reference laboratories creates scale thresholds that lock in price floors for nucleic acid extraction and sequencing services. CLIA-certified mega-labs in the United States and NMPA-registered hospital networks in China leverage batch economics to undercut mid-tier competitors, compressing margins for laboratories below critical mass.
Pricing Analysis
United States-Germany price spreads for comprehensive genomic profiling exceed threefold, with EMA IVDR compliance costs and fragmented payer landscapes in Europe sustaining premium tiers. Pricing stratifies across companion diagnostic co-development contracts, fee-for-service reference testing, and CLIA-waived point-of-care devices, with pharmaceutical sponsorship anchoring the premium tier. Cost compression in infectious disease panels intensifies as isothermal amplification devices capture emergency department volumes. Hospital procurement committees exhibit highest price sensitivity, while pharmaceutical sponsors prioritize analytical validity over unit cost.
Supply Chain Analysis
Sequencing consumable inventories stretch sixteen to twenty-four weeks for European service providers dependent on United States and German reagent manufacturers. Nucleic acid extraction chemistries, flow cell consumables, and CRISPR guide RNA libraries draw from concentrated supplier bases in the United States, Germany, and China, exposing laboratories to single-source vulnerability for proprietary chemistries. Distribution runs through direct manufacturer contracts for high-volume reference laboratories and specialty distributors serving mid-tier hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face acute substitution pressure from point-of-care nucleic acid amplification devices capturing low-complexity infectious disease testing. Defense requires capability investments that widen the moat between centralized laboratory value and decentralized device limitations.
For Market Incumbents: Consolidate companion diagnostic co-development pipelines with pharmaceutical sponsors to lock in recurring revenue streams resistant to point-of-care displacement. Automate nucleic acid extraction workflows to compress technician-to-sample ratios below competitor reach. Secure captive supply of sequencing consumables through backward integration or long-term offtake agreements with German and United States reagent manufacturers. For New Entrants and Emerging Players: Differentiate on liquid biopsy specialization for minimal residual disease monitoring, a service tier where reference laboratory infrastructure retains irreplaceable value. Target NABL-accredited production nodes in India for cost-optimized service delivery to European and North American pharmaceutical trial networks. Pursue cloud-native bioinformatics partnerships with multi-site health systems in Germany seeking centralized variant interpretation. For Investors and Strategic Acquirers: Cloud-based analytics specialists with HIPAA-GDPR dual compliance architectures represent the most defensible acquisition archetype as health systems consolidate quality control functions. Long-term viability hinges on regulatory moats around algorithm-driven variant interpretation where FDA and EMA evidentiary standards are tightening. Watch for inflection when CLIA certification timelines stretch beyond twenty-four months in metropolitan clusters, triggering laboratory acquisition premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development Partnership | Locks in recurring revenue with pharmaceutical sponsors under FDA and EMA mandates. |
| Automated Liquid Handling Platform Deployment | Compresses technician dependency below competitor scale thresholds in high-throughput labs. |
| Cloud-Native Bioinformatics Pipeline Integration | Enables real-time variant interpretation across multi-site health systems under HIPAA compliance. |
| NABL-Certified Production Node Establishment | Opens cost-optimized channel access in India for multinational service delivery. |
| Reagent Manufacturing Backward Integration | Secures captive supply of nucleic acid extraction chemistries against input cost volatility. |
Research Methodology
Operator-level perspectives from clinical laboratory directors, pharmaceutical biomarker development leads, hospital procurement managers, and regulatory affairs specialists anchored the qualitative base. Primary interviews triangulated with secondary validation from FDA 510(k) filings, EMA IVDR submission databases, CLIA laboratory certification records, and CMS Medicare reimbursement code analyses. Bottom-up service volume estimates across infectious disease, oncology, and pharmacogenomics segments converged with top-down market sizing from nucleic acid test registration data.
Sensitivity analysis tested forecast robustness across alternative CLIA certification timeline scenarios and point-of-care device penetration rates. The analytical framework modeled service type, application, end user, and deployment model dimensions across the projection horizon. CAGRs derived from segment-level volume trajectories and pricing elasticity assumptions, with nucleic acid extraction automation curves and companion diagnostic pipeline maturities as key forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained precision medicine reimbursement expansion or accelerated point-of-care regulatory clearance would require recalibration. Forecasts reflect documented assumptions regarding health system consolidation trajectories and pharmaceutical co-development contract structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Human Immunodeficiency Virus Rapid Test Kit Market
Diagnostics
Body Fluid Collection and Diagnostics Market
Diagnostics
Blood Glucose Testing Devices Market
Diagnostics
Blood Ketone Test Meter Market
Diagnostics
Global Saliva Collection and Diagnosis Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Lipid Panel Test Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
Artificial Intelligence in IVD Market
Diagnostics
Primary Care POC Diagnostics Market
Diagnostics
Helicobacter Pylori (H. Pylori) Diagnostics Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
Global Comprehensive Metabolic Panel Market
Diagnostics
Elisa Tests Market
Diagnostics
Global Tissue Diagnostics Market
Diagnostics
Immunodiagnostics Market