
 Global Specimen Validity Testing Market | 2026-2036
Global Specimen Validity Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specimen Validity Testing Market Foresight
Point-of-care immunoassay miniaturization is narrowing the performance gap between rapid field tests and centralized laboratory confirmations. Abbott leverages integrated diagnostic platforms to sustain workflow efficiency across clinical and workplace settings. Thermo Fisher Scientific anchors its position through chromatography technology leadership in forensic reference laboratories. Quest Diagnostics competes on geographic reach, operating one of the largest networks of SAMHSA-certified testing facilities across North America.
Specimen validity testing encompasses analytical procedures that verify the integrity, authenticity, and physiological appropriateness of biological samples submitted for drug, alcohol, or toxicological analysis, typically assessing creatinine concentration, specific gravity, pH, oxidant presence, and temperature parameters within minutes of collection to prevent substitution, dilution, or adulteration. Immunoassay technology dominates routine workplace screening due to throughput economics and instrument portability, while chromatography methods capture premium margin pools in forensic and clinical research applications where legally defensible quantification is mandatory. Electrochemical sensor platforms represent the fastest-growing technology segment as manufacturers reduce electrode costs and improve stability for on-site adulteration detection.
The U.S. Department of Health and Human Services, the U.S. Food and Drug Administration, and the European Medicines Agency collectively shape product standards through mandatory certification pathways and evolving substance panel requirements. FDA clearance timelines and SAMHSA laboratory certification protocols directly determine market access for new testing platforms and reagent kits. Stakeholders must monitor regulatory divergence between U.S. federal workplace guidelines and EU member state variations in sports anti-doping protocols to anticipate compliance-driven replacement cycles.
Market Dynamics
Regulatory tightening across workplace safety protocols is compressing testing timelines and forcing infrastructure upgrades at both centralized laboratories and point-of-care facilities. The U.S. Department of Transportation's updated specimen integrity guidelines are mandating real-time validity verification before confirmatory analysis, creating immediate equipment replacement cycles.
Growth Catalysts
- Federal workplace mandates:The U.S. Department of Health and Human Services substance abuse testing panels are expanding to include synthetic opioids, requiring validity testing protocol updates across SAMHSA-certified facilities.
- Electrochemical sensor advancement:Miniaturized electrode arrays are achieving stability thresholds that enable on-site adulterant detection without laboratory infrastructure, opening field deployment in construction and transportation sectors.
- Germany's occupational safety framework:The country's implementation of comprehensive workplace drug screening standards for safety-critical positions is driving centralized laboratory capacity expansion.
Market Restraints
- Chromatography reagent cost volatility:High-purity solvents and derivatization agents face supply concentration among German and Swiss specialty chemical suppliers, squeezing margin structures for forensic reference laboratories.
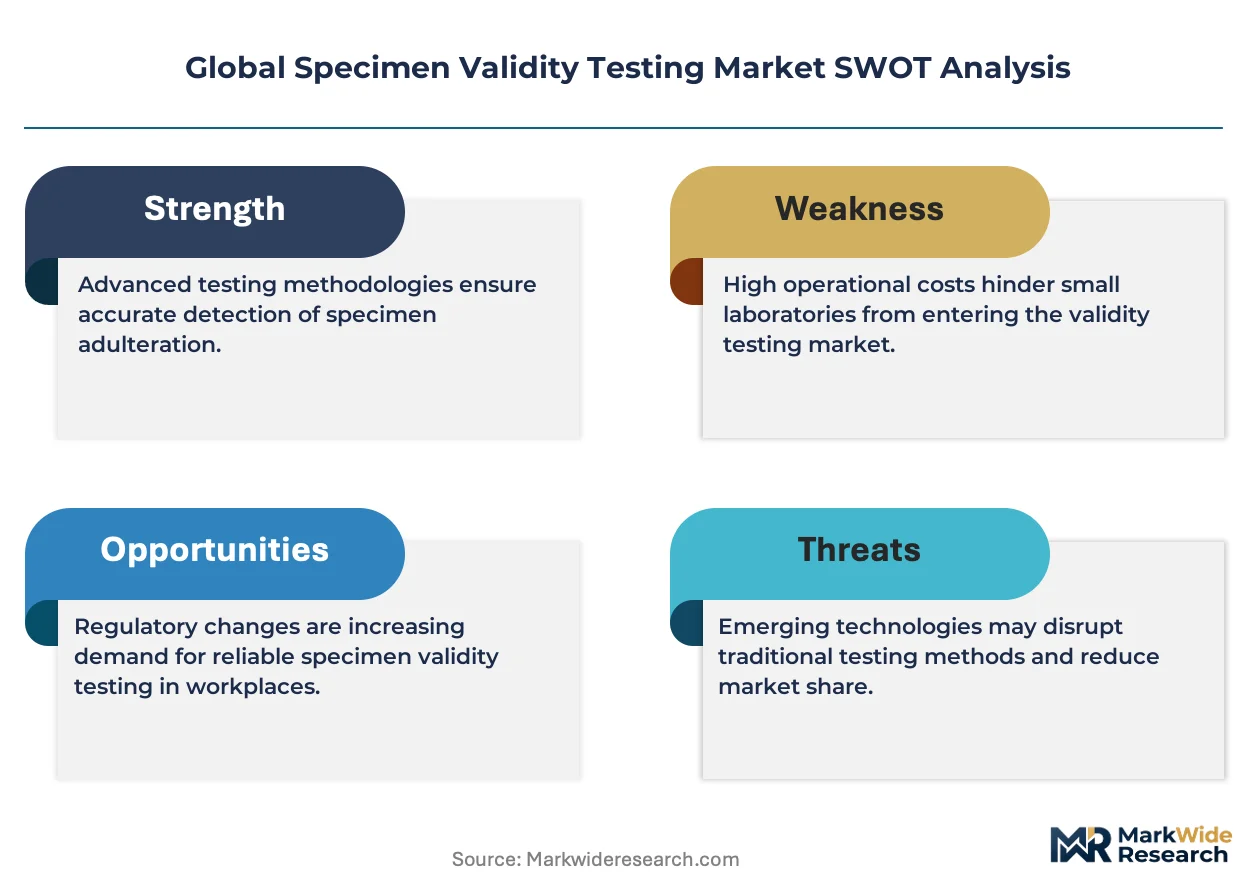
- FDA clearance timeline friction:New immunoassay platform approvals average 18-24 months for 510(k) pathways, delaying market entry for innovative adulterant detection chemistries.
- Point-of-care performance gaps:Temperature strip and specific gravity dipstick methods retain false-negative rates for sophisticated substitution agents that centralized chromatography detects reliably.
Strategic Opportunities
- China's occupational health expansion:The country's state-owned enterprise restructuring is incorporating systematic drug screening for transportation and energy sector workers, creating demand for integrated validity-confirmation workflows.
- Sports anti-doping protocol convergence:The World Anti-Doping Agency's harmonized standards are creating certification pathways for laboratories serving international athletic federations with specimen integrity verification.
- Remote workforce monitoring:Telehealth platforms are integrating at-home collection kits with chain-of-custody documentation and real-time validity indicators for clinical toxicology monitoring.
Industry Challenges
- SAMHSA certification backlog:Laboratory accreditation queues are extending to 14-16 months, constraining capacity expansion for workplace testing providers seeking federal compliance.
- Cross-platform data integration:Immunoassay screening instruments from different manufacturers generate non-standard result formats, complicating centralized data management for multi-site employers.
- Specimen handler training gaps:Collection site personnel turnover requires continuous re-certification on temperature monitoring and chain-of-custody documentation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specimen Validity Testing Market |
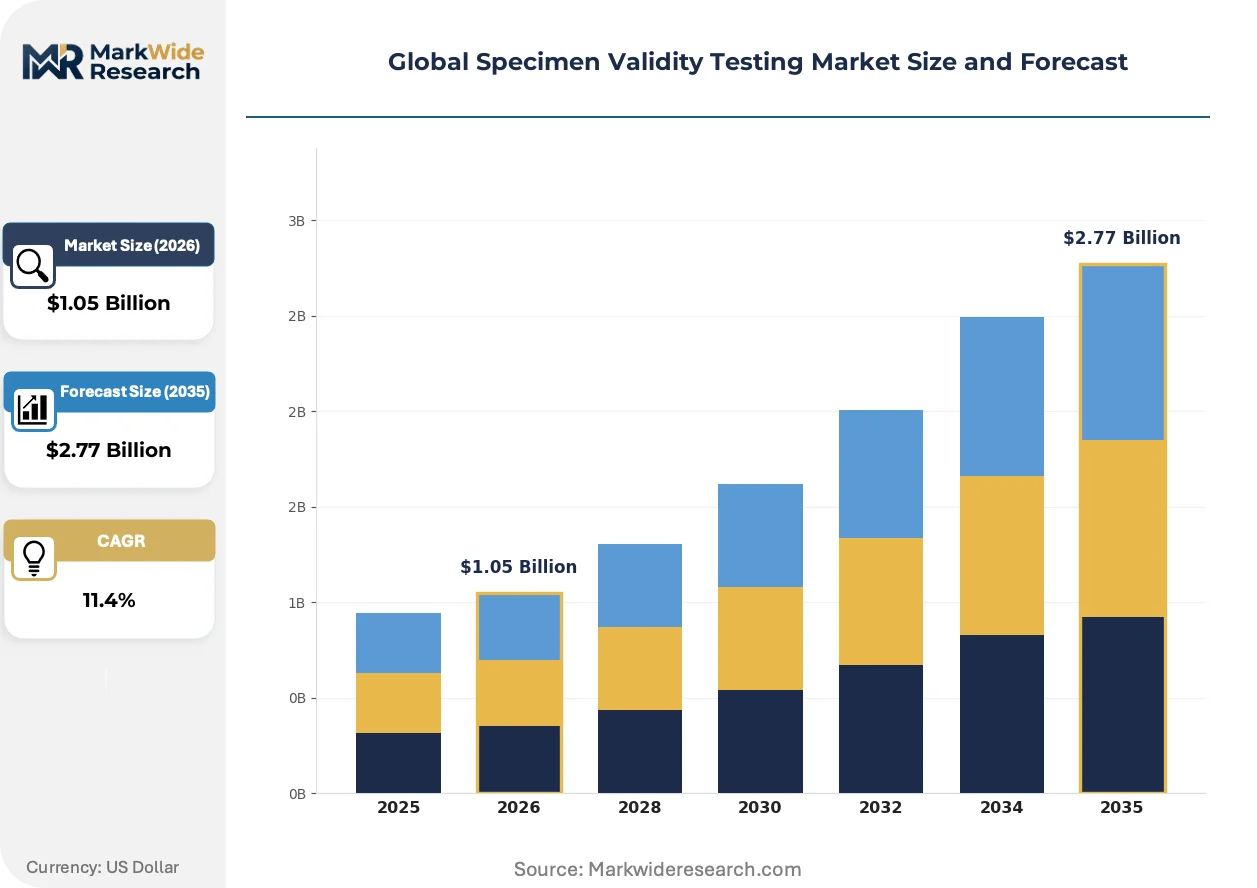
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.77 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drug Testing Kits, Alcohol Testing Devices, Adulteration Detectors, Temperature Monitors, pH Meters Application: Workplace Screening, Forensic Analysis, Clinical Research, Rehabilitation Centers, Sports Anti-Doping End User: Clinical Laboratories, Government Agencies, Sports Federations, Corporate Employers, Law Enforcement Technology: Immunoassay, Chromatography, Spectroscopy, Enzyme-Based, Electrochemical Sensors |
| Companies Covered | Abbott, Thermo Fisher Scientific Inc., Laboratory Corporation of America Holdings, Quest Diagnostics, Sciteck, American Bio Medica Corporation, Alfa Scientific Designs, Premier Biotech, Nona Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specimen Validity Testing Market Shifts & Advancements
Specimen validity testing is undergoing platform convergence as electrochemical, optical, and chromatographic methods integrate into unified workflows. Device miniaturization and cloud-connected result reporting are compressing the traditional separation between screening and confirmation stages.
Electrochemical sensor arrays for oxidant and pH detection are migrating from laboratory benchtop configurations to handheld field units. Construction firms and logistics operators in the United States are deploying these devices at remote collection sites, eliminating specimen transport delays. This technology is migrating from centralized quality control to distributed screening, collapsing the traditional two-stage testing model into single-visit protocols.
The European Union's Medical Device Regulation (MDR) is reclassifying point-of-care validity testing devices from Class I to Class IIa, imposing clinical performance documentation requirements. Manufacturers serving forensic and clinical markets must now submit equivalence data for adulterant detection claims. German and French testing facilities are prioritizing MDR-compliant platforms to maintain access to workplace and clinical contracts.
Employer purchasing departments are consolidating toxicology services under national contract vehicles, displacing fragmented site-by-site procurement. Third-party administrators are aggregating validity testing, confirmatory analysis, and medical review officer services into bundled offerings. This concentration is most visible among Fortune 500 manufacturers with multi-state U.S. operations seeking uniform policy enforcement.
Global Specimen Validity Testing Market Segmentation
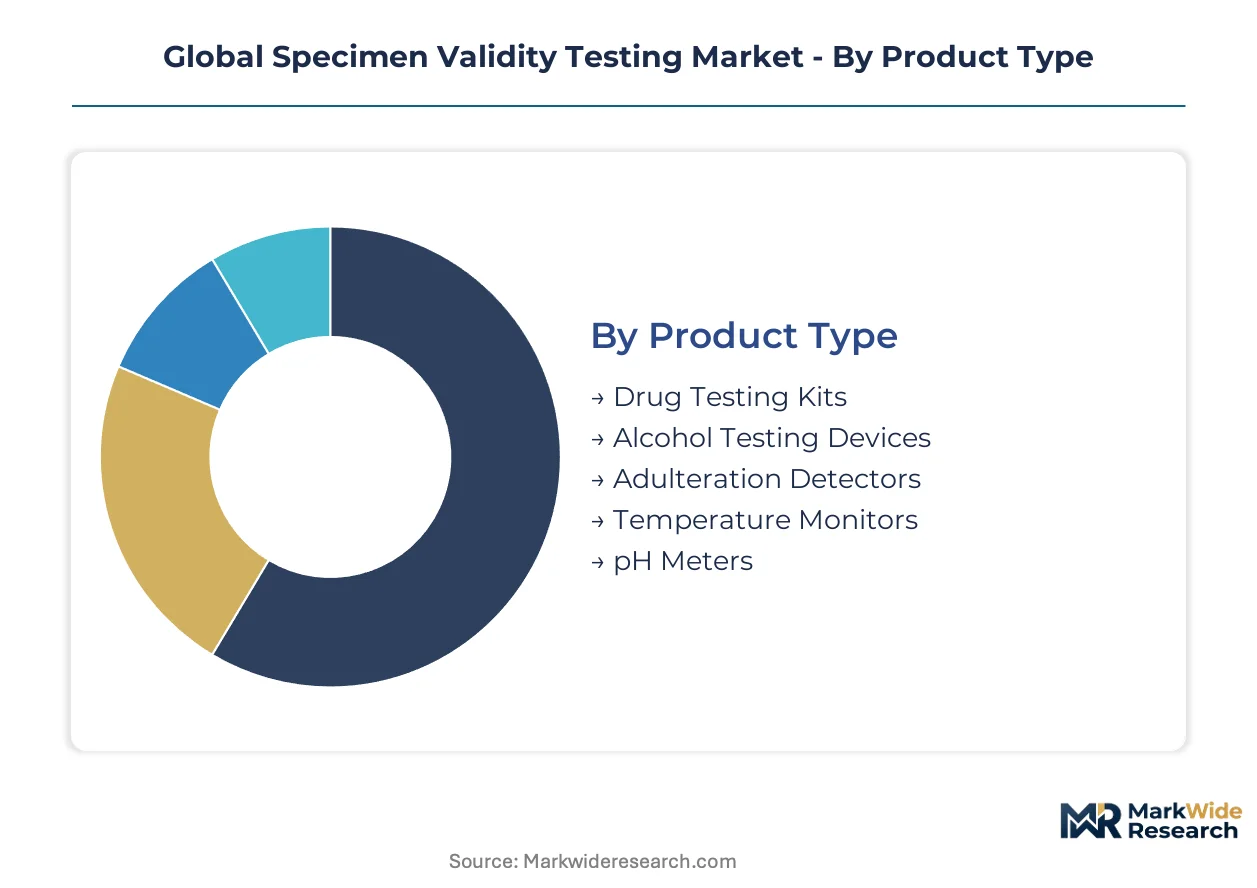
Specimen validity testing segments reflect divergent performance requirements across workplace compliance, forensic defensibility, and clinical precision. Product architecture, application context, and end-user infrastructure dictate technology selection and procurement economics.
Product Type:
Product architecture spans from disposable consumables to integrated instrument platforms, with cost-per-test economics driving procurement patterns across centralized and distributed testing models.
- Drug Testing Kits:Disposable immunoassay panels deliver rapid qualitative screening for multiple substance classes at collection sites. Corporate employers in the United States deploy these for pre-employment and random testing programs under SAMHSA guidelines.
- Alcohol Testing Devices:Breathalyzers and saliva-based ethanol detectors incorporate fuel cell or infrared sensor technology for immediate quantitative results. Transportation sector mandates in Germany and China are accelerating replacement cycles for connected, tamper-evident devices.
- Adulteration Detectors:Multi-parameter strips and digital readers identify oxidants, specific gravity anomalies, and synthetic urine markers.
- Temperature Monitors:Digital thermochromic strips and infrared sensors verify specimen collection within physiological ranges.
- pH Meters:Handheld electrochemical probes and colorimetric assays detect alkaline or acidic adulteration attempts.
Established volume favors drug testing kits; emerging adoption favors alcohol testing devices.
Application:
Application contexts range from high-throughput workplace compliance to low-volume, high-stakes forensic confirmation, with regulatory stringency determining technology tier selection.
- Workplace Screening:Federally mandated safety-sensitive position testing drives standardized panel configurations and chain-of-custody documentation. United States Department of Transportation rules require validity verification before confirmatory analysis.
- Forensic Analysis:Court-admissible toxicology demands quantitative chromatography methods with certified reference materials and documented uncertainty calculations. State crime laboratories face backlog pressures from synthetic opioid caseload expansion.
- Clinical Research:Pharmacokinetic studies require specimen integrity protocols that preserve analyte stability across collection, transport, and storage intervals.
- Rehabilitation Centers:Treatment monitoring programs combine rapid screening with medical review officer oversight for compliance documentation.
- Sports Anti-Doping:World Anti-Doping Agency protocols mandate A and B sample collection with witnessed validity verification.
Workplace screening commands the largest installed base; sports anti-doping exhibits the steepest expansion trajectory.
End User:
End-user infrastructure varies from reference laboratory automation to field-deployable point-of-care systems, with certification requirements constraining vendor selection.
- Clinical Laboratories:SAMHSA-certified facilities operate integrated immunoassay-chromatography workflows with laboratory information management system connectivity. Quest Diagnostics and similar networks compete on geographic coverage and turnaround time.
- Government Agencies:Federal, state, and municipal procurement vehicles prioritize compliance documentation and audit trail completeness over per-test cost minimization.
- Sports Federations:International Olympic Committee and professional league programs require WADA-accredited laboratory partnerships with specimen integrity verification.
- Corporate Employers:Third-party administrator consolidation is displacing fragmented site-by-site toxicology service procurement.
- Law Enforcement:Evidentiary standards for driving under the influence and probation monitoring vary by jurisdiction.
Clinical laboratories anchor current revenue; corporate employers are gaining share fastest through national contract consolidation.
Technology:
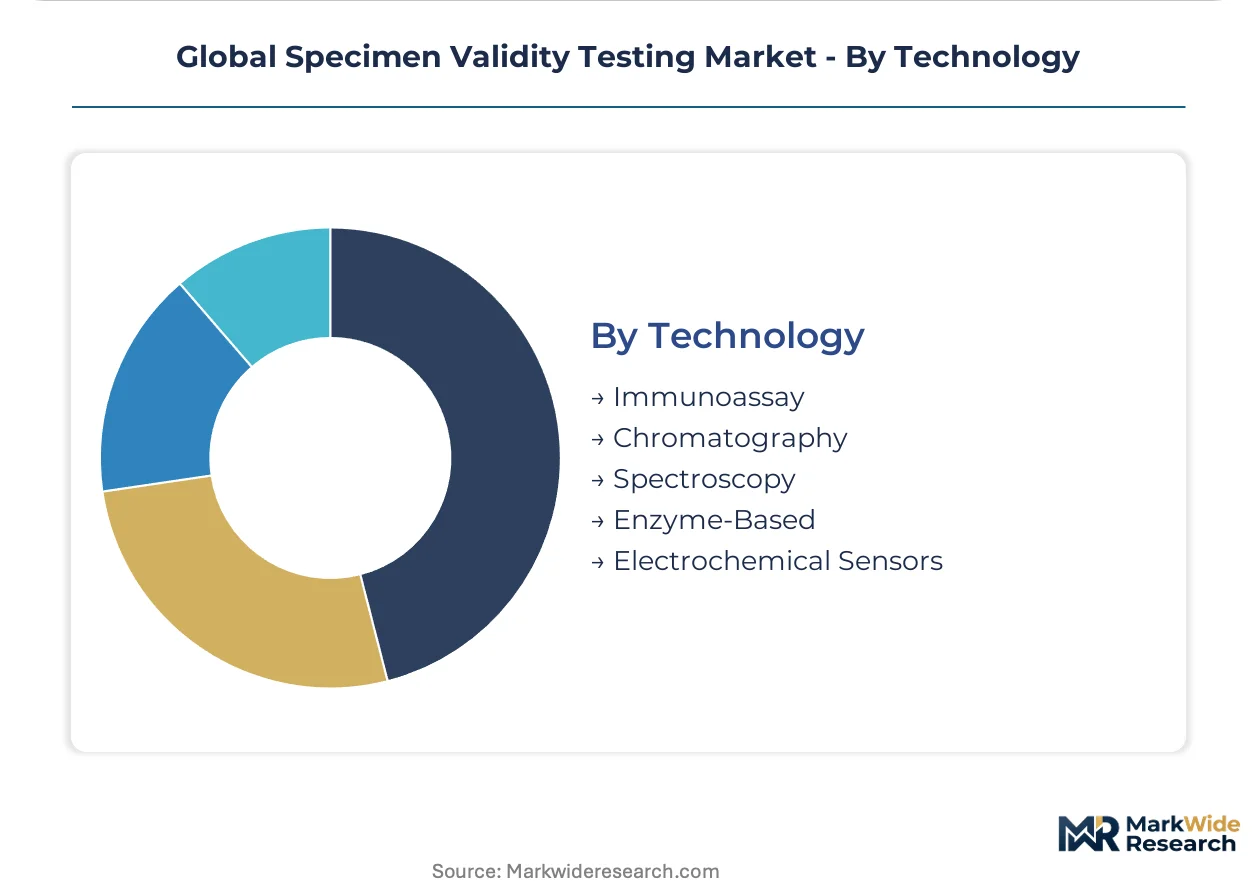
Technology platforms span cost-efficient immunoassay screening to capital-intensive chromatography confirmation, with electrochemical methods narrowing the performance gap for distributed deployment.
- Immunoassay:Competitive and sandwich format antibody-antigen reactions enable rapid, multi-analyte detection on portable platforms. Workplace screening economics favor this technology for negative result determination without laboratory transport.
- Chromatography:Gas and liquid chromatography with mass spectrometry detection delivers definitive identification and quantification for legal proceedings. Forensic reference laboratories in Germany and Switzerland maintain technology leadership through solvent purification and derivatization expertise.
- Spectroscopy:UV-Vis and infrared methods support adulterant identification through molecular fingerprint matching.
- Enzyme-Based:Alcohol dehydrogenase and oxidase reactions provide substrate-specific detection with minimal instrumentation requirements.
- Electrochemical Sensors:Miniaturized electrode arrays for pH, oxidant, and creatinine detection are migrating to handheld field units. Construction and logistics operators in the United States deploy these for remote collection site validity verification.
Immunoassay retains dominant volume position; electrochemical sensors are expanding most quickly through point-of-care miniaturization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of specimen validity testing equipment concentrate in the United States, Germany, and China, while Switzerland and Japan export high-purity chromatography reagents and reference materials. The trade imbalance reflects divergent manufacturing capabilities across electrochemical sensors, immunoassay platforms, and forensic-grade solvents.
United States
Department of Transportation safety-sensitive position mandates and SAMHSA-certified laboratory networks drive equipment procurement. The FDA's 510(k) clearance pathways for new adulterant detection chemistries create regulatory bottlenecks extending 18-24 months. Houston and Dallas-Fort Worth host major third-party administrator consolidation hubs serving Fortune 500 employers with multi-state testing contracts.
Germany
Occupational safety frameworks for chemical and manufacturing sectors mandate systematic workplace drug screening. The country's national pharmaceutical regulator enforces MDR compliance for point-of-care devices, elevating documentation requirements for adulterant detection claims. The Rhine-Ruhr industrial corridor anchors centralized laboratory capacity expansion serving safety-critical positions across automotive and chemical plants.
China
State-owned enterprise restructuring incorporates systematic drug screening for transportation and energy sector workers. The National Medical Products Administration certifies testing platforms for domestic clinical and workplace applications. The Yangtze River Delta clusters electrochemical sensor manufacturing, with Shanghai-based facilities supplying handheld validity verification units to construction and logistics operators.
Switzerland
Forensic reference laboratories maintain technology leadership through solvent purification and derivatization expertise for legally defensible quantification. Swissmedic oversees certification of chromatography-based confirmation systems exported to EU and North American markets. Basel and Zurich host specialty chemical suppliers concentrating high-purity reagent production for gas and liquid chromatography applications.
Japan
Precision manufacturing capabilities support miniaturized electrode array production for pH and oxidant detection platforms. The Ministry of Economy, Trade and Industry promotes sensor technology exports through standardization initiatives. The Kanto region around Tokyo houses electrochemical component fabricators supplying handheld field units to U.S. construction firms and German logistics operators.
Global Specimen Validity Testing Market Competitive Landscape
On the supply side, the industry is moderately consolidated around diagnostic conglomerates with integrated platform portfolios and specialized forensic laboratories with chromatography expertise. Three strategic archetypes dominate: full-service diagnostic networks with SAMHSA certification, electrochemical sensor specialists pursuing point-of-care miniaturization, and forensic reference laboratories competing on legally defensible quantification. Competitive moves center on national contract consolidation for employer toxicology services and MDR compliance investments for EU market access.
Among U.S.-based diagnostic conglomerates, Abbott and Quest Diagnostics exemplify the integrated platform archetype, combining immunoassay screening with laboratory confirmation workflows. Thermo Fisher Scientific Inc. anchors the technology supply tier, representing chromatography and mass spectrometry instrumentation leadership serving forensic reference laboratories. These three entities occupy positions spanning clinical, workplace, and forensic applications without direct product-level competition.
| Leading Market Players |
|---|
| Abbott |
| Thermo Fisher Scientific Inc. |
| Laboratory Corporation of America Holdings |
| Quest Diagnostics |
| Sciteck |
| American Bio Medica Corporation |
| Alfa Scientific Designs |
| Premier Biotech |
| Nona Scientific |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta electrochemical sensor manufacturing cluster feeds cost-competitive handheld units to global workplace testing programs, compressing price points for on-site validity verification while elevating margin pressure on centralized laboratory equipment suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based pricing for high-throughput immunoassay platforms, with three-tier pricing structure across premium, standard, and economy levels differentiating by SAMHSA certification tier and geographic service coverage. Price differentiation hinges on turnaround time guarantees and chain-of-custody documentation rigor. Cost compression in economy-tier dipstick consumables is intensifying because of Chinese electrode array imports. Third-party administrators exhibit highest price sensitivity; forensic reference laboratories show lowest.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement negotiations between U.S. third-party administrators and reagent suppliers, reflecting working capital pressure downstream. Manufacturing concentrates in China, Germany, and Switzerland—electrochemical sensors from Shanghai, immunoassay platforms from the Rhine-Ruhr corridor, chromatography solvents from Basel. High-purity derivatization agents and certified reference materials constitute critical dependencies. Single-source vulnerability from Swiss-German specialty chemical suppliers elevates risk. Distribution runs through national contract vehicles aggregating validity testing, confirmation analysis, and medical review services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across point-of-care miniaturization, electrochemical sensor advancement, and remote workforce monitoring creates multiple entry niches for specialized players. Federal mandate expansion for synthetic opioid panels splinters demand across technology tiers.
For Market Incumbents: Entrench SAMHSA certification moats through capacity addition in Texas and Florida third-party administrator hubs. Accelerate MDR compliance documentation for EU point-of-care device reclassification. Electrochemical sensor specialists threatening immobilized enzyme platforms represent the core threat. Vertical integration into cloud-connected result reporting systems constitutes the priority defensive lever. For New Entrants and Emerging Players: Remote workforce monitoring kits with integrated chain-of-custody documentation represent the most penetrable entry point. China's state-owned enterprise transportation sector restructuring offers secondary white-space. Sports anti-doping protocol convergence with WADA-accredited laboratory partnerships provides a third avenue. Partner with telehealth platforms for at-home collection kit distribution as the go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-recurring-revenue play because federal workplace mandate expansion and certification backlog create sustained replacement cycle visibility. Target electrochemical sensor specialists with handheld field unit deployments and stable electrode chemistry IP. Monitor FDA 510(k) clearance timeline compression as the inflection signal for platform consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Investment | Class IIa reclassification for point-of-care devices secures EU workplace contract access. |
| Electrochemical Sensor Miniaturization | Handheld pH and oxidant detection collapses two-stage testing into single-visit protocols. |
| National Contract Consolidation | Fortune 500 employers aggregate toxicology services under unified procurement vehicles. |
| SAMHSA Certification Expansion | Laboratory accreditation queues extending to 14-16 months constrain competitor capacity. |
| Cloud-Connected Result Reporting | Real-time validity verification before confirmatory analysis satisfies DOT timeline compression. |
Research Methodology
Desk research of FDA 510(k) filings, SAMHSA laboratory certification records, and EU MDR technical documentation preceded structured interviews with diagnostic platform product managers, forensic laboratory directors, third-party administrator procurement leads, and occupational health compliance officers. Secondary validation drew from customs trade data for electrochemical sensor imports, SEC 10-K instrument revenue disclosures, and GPO contract award databases. Bottom-up equipment unit economics and top-down regulatory mandate expansion models were triangulated.
Assumptions held fixed include current DOT specimen integrity guideline stringency and WADA protocol harmonization trajectory; variables tested include electrochemical sensor stability thresholds and MDR compliance timeline acceleration. Segmentation modeling spanned product architecture tiers, application regulatory stringency levels, end-user certification requirements, and technology platform cost-performance tradeoffs across the projection horizon. CAGRs were derived from equipment replacement cycle analysis and reagent consumable attach rates. Synthetic opioid panel expansion and remote workforce monitoring adoption curves served as primary volume drivers.
Practitioners should monitor FDA adulterant detection chemistry clearance timelines and EU MDR clinical performance documentation requirements for early signals of platform consolidation timing. Forecasts reflect these documented assumptions. Regulatory divergence between U.S. federal workplace guidelines and EU member state sports anti-doping protocols, alongside electrochemical sensor stability breakthroughs, would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Drug Testing Market
Testing Services
Faecal Calprotectin Testing Market
Testing Services
Pharmaceutical Quality Control Market
Testing Services
West Nile Virus Testing Market
Testing Services
Platelet Function Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
South Korea GMP Testing Service Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Sports Drug Testing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Solid Tumor Testing Market
Testing Services
Pregnancy Point of Care Testing Market