
 Global Blood Culture Tests Market | 2026-2036
Global Blood Culture Tests Market Size, Share, and Industry Trends Forecast 2026-2036
Global Blood Culture Tests Market Foresight
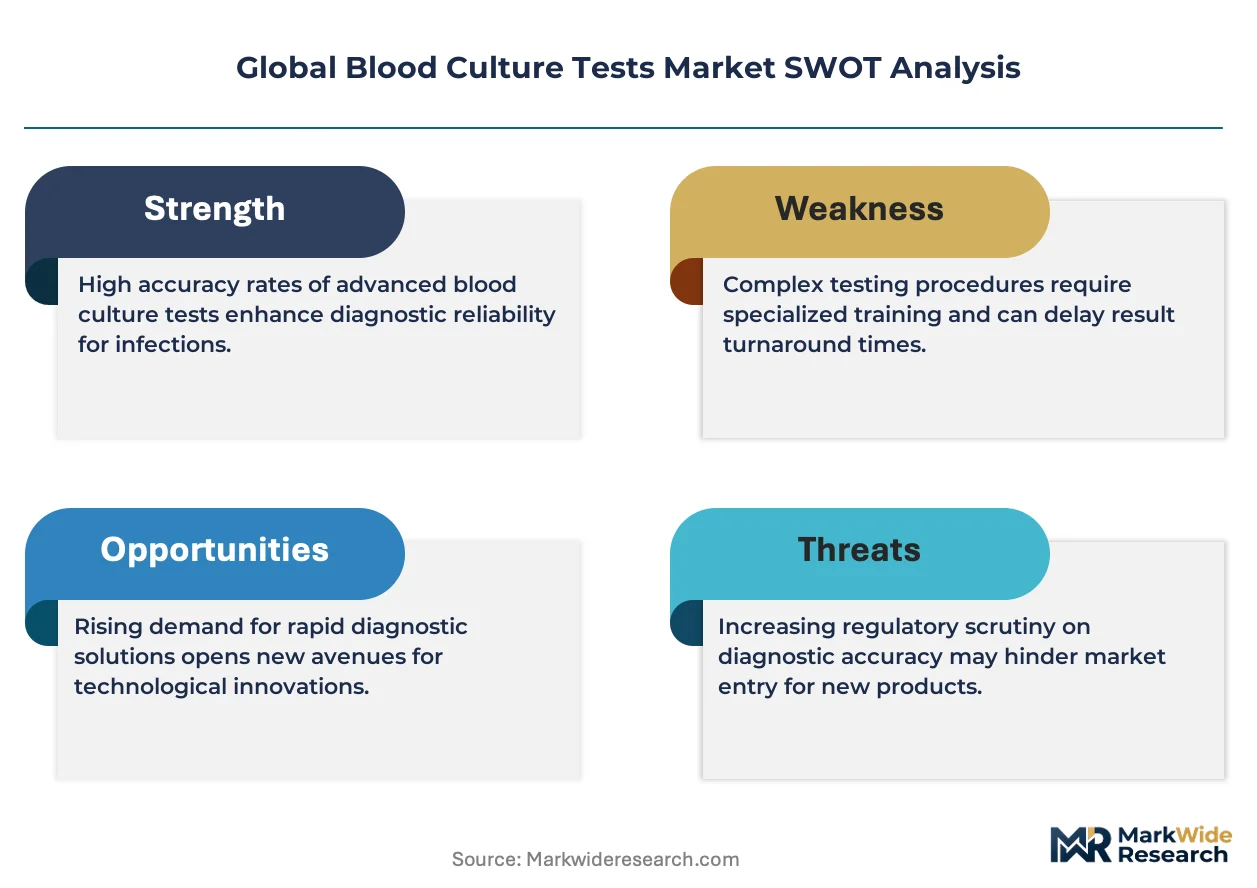
The EU In Vitro Diagnostic Regulation is restructuring procurement criteria across European hospital networks, forcing manufacturers to recertify legacy platforms under stricter clinical evidence rules. Becton, Dickinson and Company leverages its automated blood culture installed base to sustain service contracts across integrated delivery networks. bioMérieux SA anchors its competitive position through specialized molecular identification workflows that reduce time-to-result for sepsis pathways. Thermo Fisher Scientific Inc. competes by extending its mass spectrometry footprint into microbiology labs seeking consolidated diagnostic platforms.
Blood culture tests are microbiological diagnostic procedures that detect viable bacteria or fungi in bloodstream samples through aerobic and anaerobic incubation, typically requiring 24–72 hours for positive signal detection using colorimetric or fluorescent sensor technologies. Their primary commercial purpose is enabling targeted antimicrobial therapy initiation and reducing mortality from sepsis and bacteremia. Automated blood culture systems dominate capital expenditure budgets in high-throughput clinical laboratories, while molecular diagnostic kits capture the fastest expansion as hospitals prioritize rapid pathogen identification. Culture-based technology remains the volume backbone due to reimbursement familiarity, though polymerase chain reaction methods are displacing conventional workflows in tertiary care centers where turnaround time directly affects patient outcomes.
The FDA enforces stringent premarket notification requirements for blood culture devices under 21 CFR 866, while the EU MDR and IVDR frameworks mandate post-market surveillance and clinical performance data renewal. ISO 15189 accreditation standards shape laboratory quality management and drive standardization of blood culture processing protocols across accredited facilities. Stakeholders must monitor evolving antimicrobial stewardship mandates from CMS and Joint Commission criteria that increasingly tie reimbursement to rapid diagnostic utilization.
Market Dynamics
Antimicrobial resistance surveillance mandates are compressing diagnostic turnaround windows, forcing hospital laboratories to restructure capital allocation toward rapid pathogen identification platforms that bypass traditional incubation cycles.
Growth Catalysts
- Sepsis Bundle Compliance:CMS quality metrics penalize hospitals for delayed antimicrobial administration, creating institutional pressure to adopt automated blood culture systems that accelerate positive signal detection.
- EU IVDR Recertification:The In Vitro Diagnostic Regulation's stricter clinical evidence requirements for bloodstream infection diagnostics are consolidating procurement toward validated platform suppliers with established performance dossiers.
- MALDI-TOF Integration:Mass spectrometry-based identification workflows are penetrating tertiary care networks, reducing species-level identification from days to hours.
Market Restraints
- Capital Equipment Intensity:Automated blood culture systems require substantial upfront investment in incubators, detection modules, and laboratory information system integration, constraining adoption in budget-constrained facilities.
- Reimbursement Familiarity Lock-In:Culture-based methods retain entrenched coding and payment pathways, creating friction for molecular diagnostic platforms seeking equivalent compensation.
- Consumable Supply Concentration:Specialized blood culture bottles and antimicrobial neutralization media concentrate manufacturing among limited suppliers, exposing procurement to single-source vulnerability.
Strategic Opportunities
- Point-of-Care Expansion:Emergency departments in the United States are piloting rapid molecular panels that bypass centralized laboratory routing, creating demand for compact, cartridge-based systems.
- Antifungal Resistance Surveillance:Candida auris outbreaks are driving dedicated fungal blood culture protocols, opening specialized product lines for thermotolerant organism detection.
- Antimicrobial Stewardship Mandates:Joint Commission certification requirements for stewardship programs are embedding diagnostic stewardship into hospital accreditation, institutionalizing rapid identification as standard of care.
Industry Challenges
- Microbiology Technologist Shortage:Specialized training requirements for blood culture interpretation and contamination control are colliding with pipeline constraints in clinical laboratory science programs.
- Legacy System Interoperability:Hospital information system fragmentation complicates bidirectional data exchange between automated blood culture instruments and electronic health records.
- Contamination Rate Management:Skin flora introduction during collection remains a persistent quality metric, requiring sustained investment in phlebotomy training and collection kit design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Blood Culture Tests Market |
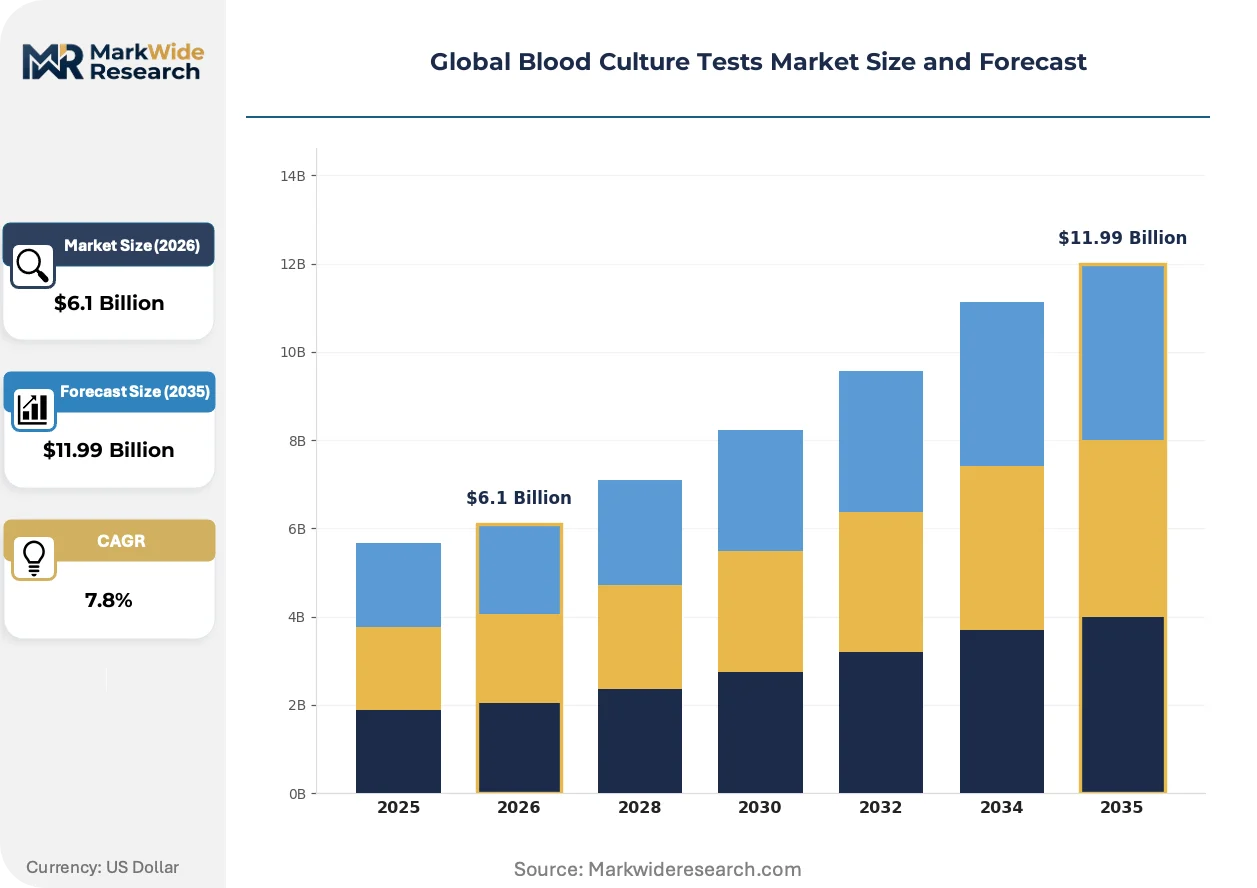
| Market Size in 2026 | $6.1 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Blood Culture Systems, Manual Blood Culture Bottles, Molecular Diagnostic Kits, Microbial Identification Panels Application: Sepsis Detection, Infectious Disease Diagnosis, Antibiotic Susceptibility Testing, Neonatal Screening, Febrile Neutropenia Assessment End User: Clinical Laboratories, Research Institutes, Diagnostic Centers, Blood Banks Technology: Culture-Based, Polymerase Chain Reaction, Fluorescence Detection, Mass Spectrometry, Microfluidics |
| Companies Covered | Becton, Dickinson and Company, bioMérieux SA, Thermo Fisher Scientific Inc., Danaher Corporation, Bruker Corporation, Terumo Corporation, Roche Diagnostics, Abbott Laboratories, Luminex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Blood Culture Tests Market Shifts & Advancements
Diagnostic velocity is overtaking sensitivity as the primary purchasing criterion, restructuring competitive advantage around time-to-result compression rather than analytical performance alone.
Digital microscopy coupled with artificial intelligence classification is overtaking manual Gram stain interpretation in high-volume laboratories. Tertiary medical centers in Germany and Japan are deploying automated imaging systems that flag positive bottles within minutes of signal detection. This compression of morphological assessment is overtaking traditional workflow bottlenecks and enabling same-shift antimicrobial targeting.
The EU MDR and IVDR transition timelines are forcing bloodstream infection diagnostic manufacturers to regenerate clinical performance data under post-market surveillance obligations. Legacy platforms without contemporary prospective studies face recertification failure, narrowing the vendor landscape to those with sustained clinical trial investment. European hospital networks are consolidating procurement around suppliers with demonstrated IVDR technical documentation completeness.
Integrated delivery networks are unbundling service contracts from instrument placement, treating maintenance and consumable supply as separately negotiable spend categories. United States health systems with centralized laboratory operations are consolidating vendor relationships across multiple hospital sites, extracting volume-based pricing concessions. This procurement rationalization is most visible among multi-hospital systems in Texas and California seeking standardized platforms across affiliated laboratories.
Global Blood Culture Tests Market Segmentation
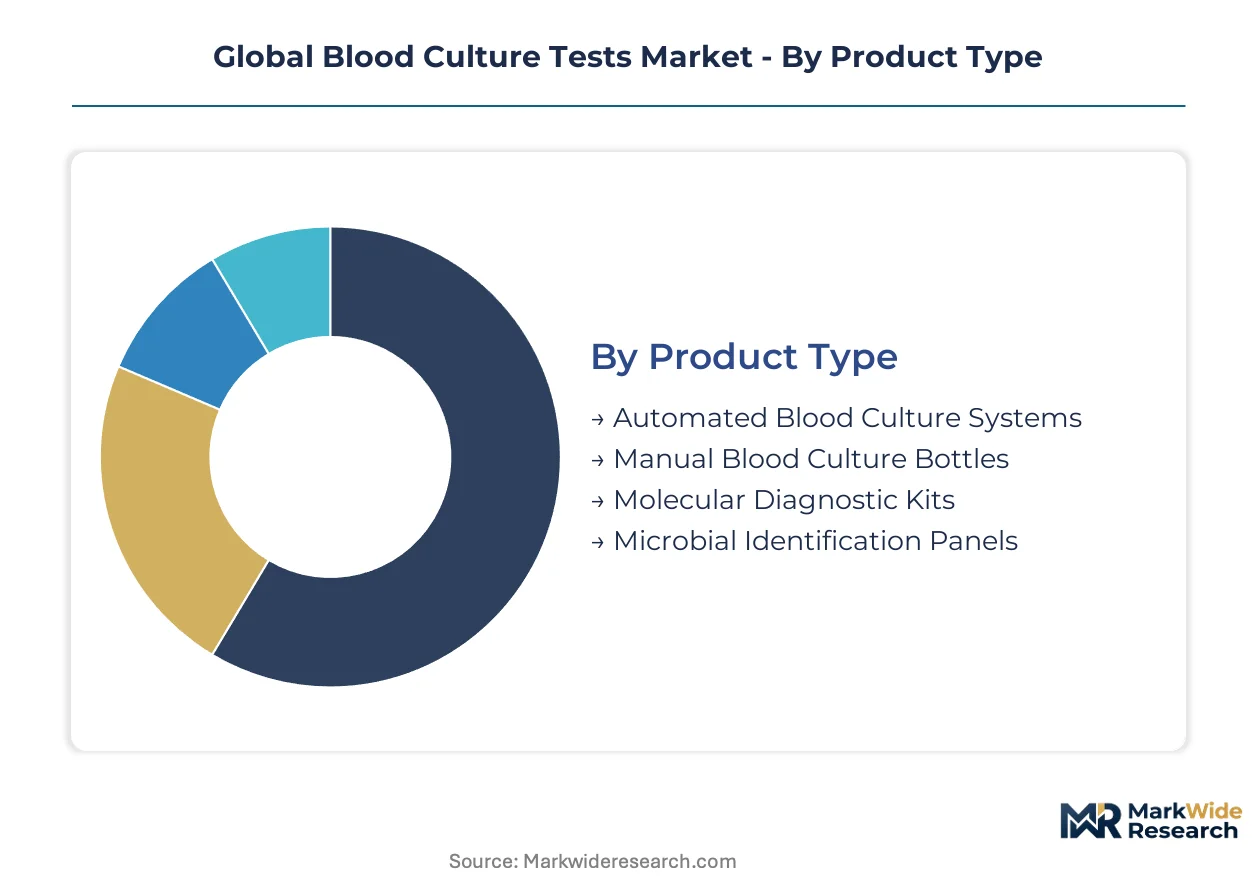
Segmentation in blood culture diagnostics reveals divergent capital deployment strategies across laboratory tiers. Automated platforms dominate throughput-intensive settings while molecular methods capture emergency department budgets prioritizing velocity over sensitivity.
Product Type:
Volume concentration sits with legacy platforms while premium pricing attaches to rapid identification technologies.
- Automated Blood Culture Systems:Continuous monitoring incubators with colorimetric or fluorescent sensors detect microbial growth through automated bottle agitation and gas exchange measurement. United States hospital networks with centralized laboratory operations prioritize these systems to meet CMS sepsis bundle compliance deadlines. Capital intensity limits penetration to tertiary care centers with dedicated microbiology infrastructure.
- Molecular Diagnostic Kits:Nucleic acid amplification platforms bypass incubation cycles to deliver pathogen identification within hours rather than days. German university hospitals lead adoption where antimicrobial stewardship programs mandate rapid turnaround for bloodstream infection protocols. Reimbursement coding gaps in outpatient settings constrain broader deployment.
- Manual Blood Culture Bottles:Conventional aerobic and anaerobic media bottles requiring manual inspection and subculture remain prevalent in resource-constrained facilities.
- Microbial Identification Panels:Biochemical and proteomic assay cards standardize species-level characterization following initial positive culture detection.
Today's leader: Automated Blood Culture Systems. Tomorrow's challenger: Molecular Diagnostic Kits.
Application:
Clinical urgency determines pricing power across diagnostic indications.
- Sepsis Detection:Bloodstream infection protocols represent the foundational use case driving automated platform placement. Japan's antimicrobial resistance surveillance network mandates rapid detection for intensive care unit admissions. Mortality reduction metrics directly tie procurement decisions to time-to-result performance.
- Antibiotic Susceptibility Testing:Phenotypic resistance profiling guides targeted therapy selection following positive culture identification. United States integrated delivery networks consolidate susceptibility testing workflows to optimize formulary compliance and resistance tracking.
- Infectious Disease Diagnosis:Broad pathogen detection supports fever of unknown origin workups in immunocompromised populations.
- Neonatal Screening:Low blood volume requirements drive specialized bottle configurations for pediatric intensive care units.
- Febrile Neutropenia Assessment:Oncology emergency protocols demand rapid exclusion of bloodstream infection in chemotherapy patients.
Sepsis pathways command the steepest expansion trajectory as regulatory penalties harden turnaround requirements.
End User:
Laboratory scale dictates technology selection and service contract structure.
- Clinical Laboratories:Hospital-based microbiology departments process the majority of blood culture volume through integrated automated platforms. High-throughput facilities in Texas and California health systems standardize instruments across multiple sites to extract volume pricing.
- Diagnostic Centers:Independent reference laboratories compete on turnaround time for outpatient sepsis rule-out testing.
- Research Institutes:Academic medical centers drive protocol development for novel resistance marker detection.
- Blood Banks:Transfusion medicine applications focus on sterility testing and donor screening protocols.
Procurement authority concentrates with Clinical Laboratories. Research Institutes capture emerging protocol influence.
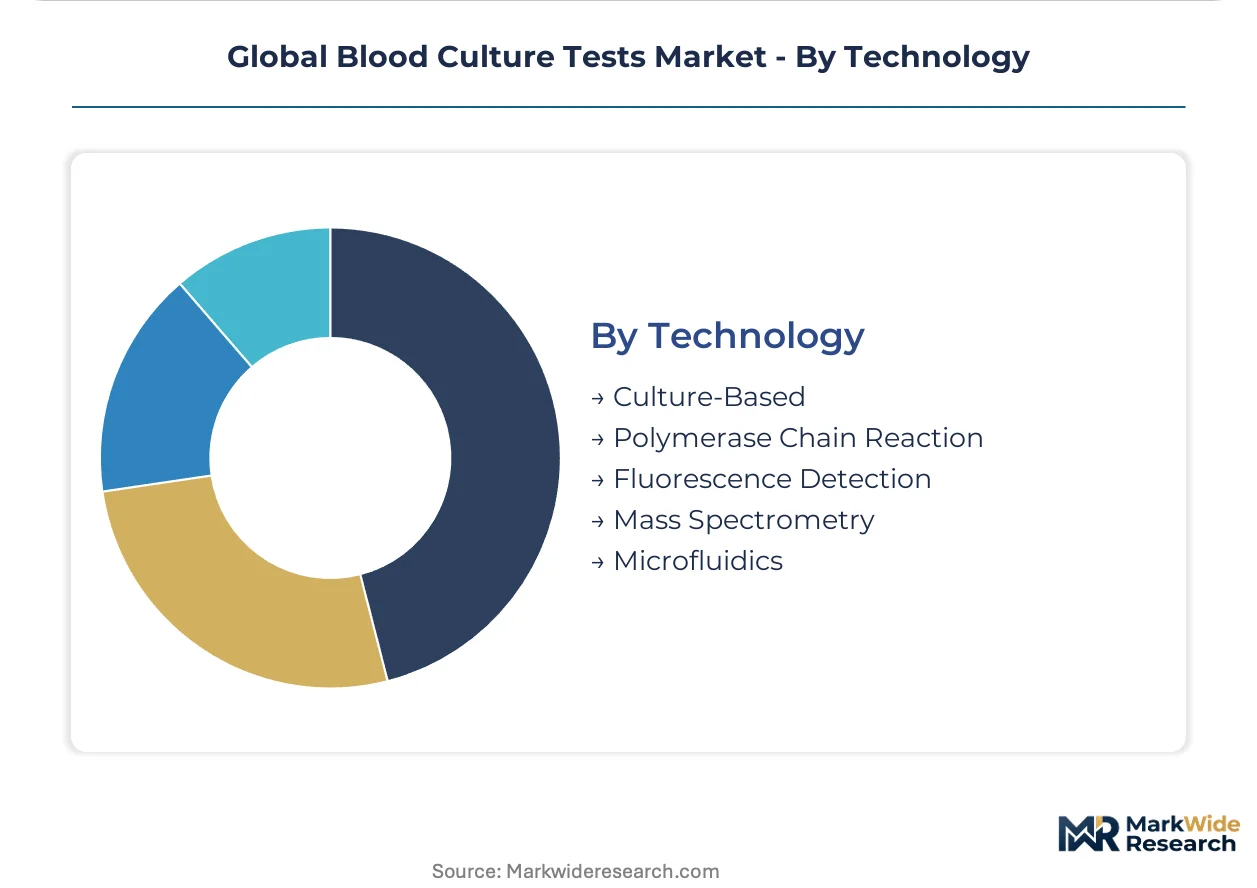
Technology:
Detection methodology separates throughput-optimized from speed-optimized deployments.
- Culture-Based:Aerobic and anaerobic incubation with automated growth detection remains the reimbursement anchor for bloodstream infection diagnosis. FDA 21 CFR 866 validation pathways entrench this technology in United States hospital billing systems.
- Mass Spectrometry:MALDI-TOF platforms compress species identification from days to minutes following positive culture. German tertiary centers lead integration with automated blood culture systems for same-shift antimicrobial targeting.
- Polymerase Chain Reaction:Direct-from-blood nucleic acid detection eliminates culture dependency for selected pathogen panels.
- Fluorescence Detection:Real-time optical monitoring of metabolic byproducts enables continuous growth surveillance.
- Microfluidics:Miniaturized sample processing targets point-of-care deployment in emergency department settings.
Culture-Based methods defend installed base. Mass Spectrometry gains share fastest through workflow integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blood culture diagnostics originated in European university hospitals during the mid-20th century, with automated detection systems first commercialized through German and Swiss engineering clusters before spreading to North American integrated delivery networks.
United States
CMS sepsis bundle penalties and Joint Commission antimicrobial stewardship mandates drive automated platform procurement across Texas and California health systems. FDA 21 CFR 866 enforcement maintains stringent premarket validation pathways for bloodstream infection devices. The Greater Boston corridor anchors academic medical center adoption of rapid molecular identification workflows.
Germany
University hospitals in Bavaria and Baden-Württemberg lead MALDI-TOF integration with automated blood culture systems for same-shift species identification. EU IVDR recertification deadlines are consolidating procurement toward suppliers with complete technical documentation. The Rhine-Main cluster around Frankfurt standardizes platforms across multi-hospital integrated networks.
Japan
Meti's antimicrobial resistance surveillance programs mandate rapid detection protocols for intensive care unit admissions in Tokyo and Osaka metropolitan areas. PMDA post-market surveillance requirements shape validation investment for bloodstream infection diagnostics. The Kansai region's tertiary centers pioneer digital microscopy with artificial intelligence classification for Gram stain interpretation.
United Kingdom
NHS England quality improvement initiatives prioritize turnaround time compression for sepsis pathways in London and Manchester hospital networks. MHRA alignment with EU MDR transition timelines affects legacy platform recertification strategies. The Oxford-Cambridge arc drives protocol development for novel resistance marker detection in academic settings.
India
CDSCO tightening of IVD import registration is accelerating local manufacturing partnerships for blood culture consumables in Maharashtra and Karnataka. Hospital chains in Delhi-NCR and Chennai deploy automated systems to meet accreditation standards for medical tourism facilities. The Hyderabad biotech cluster attracts contract research for antimicrobial resistance surveillance assay development.
Global Blood Culture Tests Market Competitive Landscape
Premium-margin players sit above commodity-margin players across service contract bundling and installed base conversion economics. The vendor landscape concentrates around automated platform suppliers with multi-decade laboratory relationships and molecular diagnostic specialists with rapid identification portfolios. Three archetypes dominate: integrated diagnostics conglomerates with broad microbiology portfolios, mass spectrometry platform specialists, and rapid molecular assay developers. Consolidation through service contract unbundling and geographic procurement rationalization represents the primary competitive dynamic, alongside technology licensing partnerships that bridge culture-based and molecular workflows.
Among United States-based diversified conglomerates, Becton, Dickinson and Company and Danaher Corporation exemplify the integrated diagnostics archetype through extensive automated platform installed bases and consumable supply concentration. bioMérieux SA represents the European molecular specialization model, anchoring competitive positioning through dedicated sepsis pathway workflows. These three entities collectively illustrate how geographic origin and corporate structure shape strategic options within bloodstream infection diagnostics.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| bioMérieux SA |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Bruker Corporation |
| Terumo Corporation |
| Roche Diagnostics |
| Abbott Laboratories |
| Luminex Corporation |
| Others |
Supply & Pricing Matrix
Polycarbonate resin indices and specialized polymer feedstock benchmarks cascade through blood culture bottle manufacturing into tiered instrument-consumable bundles, compressing margins for mid-tier automated platform suppliers while entrenching premium pricing for IVDR-validated systems with captive media production.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fully integrated automated systems with proprietary consumable lock-in from modular platforms with third-party bottle compatibility. Price differentiation rests on IVDR certification completeness and antimicrobial neutralization media formulation exclusivity. Pricing pressure stems from hospital procurement consolidation in Texas and California health systems extracting volume-based concessions across multi-site contracts. Budget-constrained secondary hospitals in India exhibit highest price sensitivity, while German university hospitals prioritize time-to-result performance over capital outlay.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States integrated delivery networks and EU hospital procurement frameworks concentrate blood culture bottle manufacturing among qualified suppliers in Germany, Japan, and the United States. Raw material dependencies center on medical-grade polycarbonates, fluorescent sensor dyes, and selective antimicrobial neutralization compounds. Supply chain risk concentrates in single-source vulnerability for specialized anaerobic media formulations. Distribution runs through regional laboratory supply distributors with consignment inventory arrangements at high-throughput hospital sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Blood Culture Tests Market operates as a stable compounder anchored by antimicrobial stewardship mandates that institutionalize recurring consumable demand regardless of macroeconomic cycles.
For Market Incumbents: Deploy service contract unbundling to defend installed base conversion economics against molecular diagnostic entrants. Consolidate procurement relationships across multi-hospital systems through standardized platform footprints. Accelerate IVDR technical documentation investment to capture European procurement consolidation toward validated suppliers. For New Entrants and Emerging Players: Begin with point-of-care emergency department deployments in United States health systems where turnaround time premiums override capital intensity constraints. Target febrile neutropenia assessment protocols in oncology centers with cartridge-based rapid molecular panels. Pursue antimicrobial stewardship program certification as the primary go-to-market credential. For Investors and Strategic Acquirers: Asymmetric upside sits with rapid molecular assay developers possessing FDA 510(k) pathways and hospital laboratory information system integration capabilities. Long-term viability favors platforms with consumable recurring revenue models over pure instrument placements. Monitor Joint Commission antimicrobial stewardship mandate expansion as the signal for accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Technical Documentation Completion | European hospital networks consolidate procurement around suppliers with validated performance dossiers under EU IVDR recertification deadlines. |
| Hospital System Partnership | Integrated delivery networks in Texas and California extract volume pricing through standardized platform deployment across affiliated laboratories. |
| Software Companion Development | Artificial intelligence-enabled digital microscopy integration accelerates Gram stain interpretation and reduces microbiologist staffing requirements. |
| Reimbursement Strategy | CMS sepsis bundle compliance metrics create institutional pressure for automated detection platforms with rapid positive signal capabilities. |
| CE Marking Pathway | EU MDR transition timelines force bloodstream infection diagnostic manufacturers to regenerate clinical performance data under post-market surveillance obligations. |
Research Methodology
Bottom-up hospital laboratory modeling reconciled against top-down automated platform shipment tracking forms the analytical core of this study. Primary interviews with clinical microbiologists, hospital procurement committee members, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU IVDR technical documentation databases, hospital procurement records, and CMS quality metric disclosures. Triangulation between end-user demand signals and manufacturer supply-side data ensures cross-verified volume estimates.
Historical trendline analysis of automated blood culture system placements and molecular diagnostic kit adoption patterns informed the projection framework across the analysis window. Segmentation modeling incorporated product type tiers, application urgency levels, end-user laboratory scale categories, and detection technology methodologies. CAGRs were derived from regression analysis of instrument placement cycles and consumable utilization rates, with antimicrobial resistance surveillance program expansion and sepsis bundle penalty enforcement as key demand drivers.
Caveats apply where IVDR recertification delays or microbiologist workforce shortages could materially shift the outlook. Forecasts reflect assumptions regarding hospital capital expenditure recovery and antimicrobial stewardship mandate enforcement consistency. Deviation in CMS sepsis bundle penalty severity or EU MDR transition timeline extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Remote Diagnosis of Electric Vehicle Market
Diagnostics
Home Diagnostics Market
Diagnostics
Semen Analysis Systems Market
Diagnostics
Heart Attack Diagnostics Market
Diagnostics
Fungal Antigens Market
Diagnostics
Asia-Pacific Syndromic Multiplex Diagnostic Market
Diagnostics
Equine Diagnostic Services Market
Diagnostics
Biochips Based in-Vitro Diagnostics Market
Diagnostics
Thyroid Cancer Diagnostics Market
Diagnostics
Gastrointestinal Diagnostics Market
Diagnostics
Alzheimer's Disease Diagnostics and Therapeutics Market
Diagnostics
Brain Cancer Diagnostics Market
Diagnostics
Veterinary Molecular Diagnostics Market
Diagnostics
Global Respiratory Diagnostics Market
Diagnostics
Pathogen Detection Market
Diagnostics
Mycoplasma Diagnostics Market